
Market Overview:
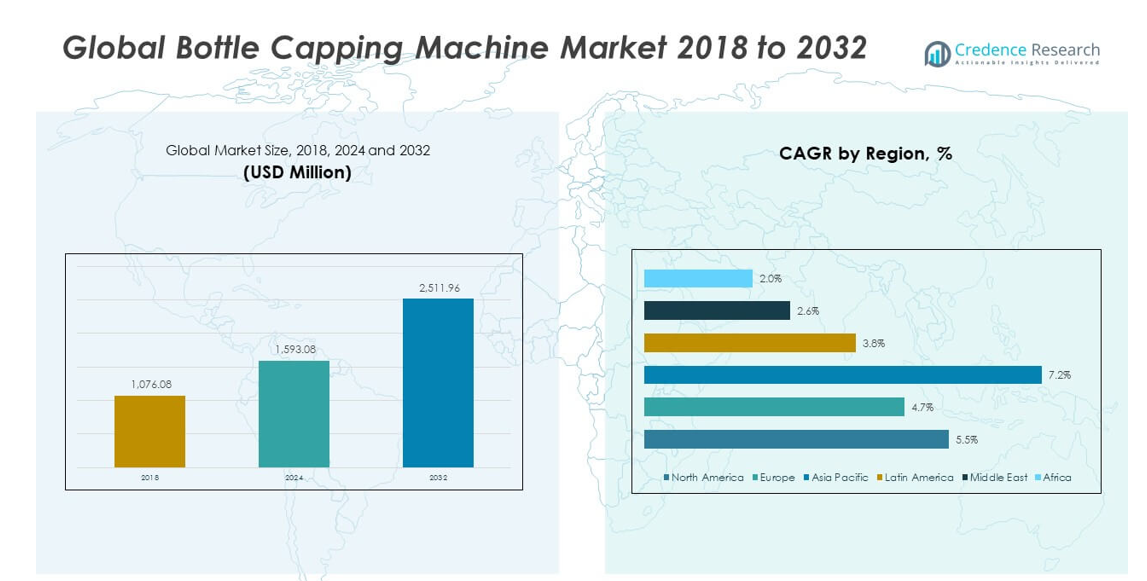
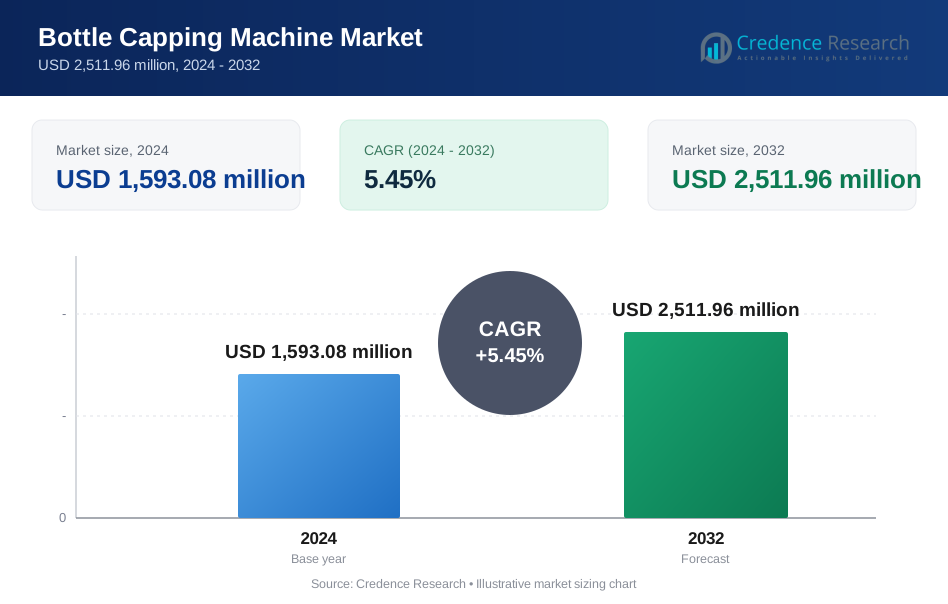
The Global Bottle Capping Machine Market size was valued at USD 1,076.08 million in 2018 to USD 1,593.08 million in 2024 and is anticipated to reach USD 2,511.96 million by 2032, at a CAGR of 5.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bottle Capping Machine Market Size 2024 | USD 1,593.08 million |
| Bottle Capping Machine Market, CAGR | 5.45% |
| Bottle Capping Machine Market Size 2032 | USD 2,511.96 million |
The market is driven by rising demand for efficient packaging solutions across food, beverage, pharmaceutical, and personal care industries. Manufacturers prioritize automation to reduce labor costs, improve accuracy, and increase throughput. Regulatory compliance regarding product safety strengthens the need for reliable capping technologies. Innovations such as servo-driven systems, smart sensors, and quick-changeover mechanisms improve operational efficiency. Sustainability goals encourage investment in energy-efficient and eco-friendly machinery, aligning with industry-wide environmental commitments. Expanding e-commerce further boosts demand for automated packaging lines.
North America leads the market due to its advanced manufacturing base, strict regulations, and strong presence of global players. Europe follows with emphasis on automation and sustainable packaging technologies. Asia Pacific emerges as the fastest-growing region, supported by rising consumption of packaged goods, industrial expansion, and increasing investments in modern production facilities in China and India. Latin America and the Middle East are gradually expanding, driven by food and beverage demand, while Africa shows steady adoption supported by urbanization and industrial development.
Market Insights:
- The Global Bottle Capping Machine Market size was valued at USD 1,076.08 million in 2018, reached USD 1,593.08 million in 2024, and is projected to reach USD 2,511.96 million by 2032, at a CAGR of 5.45%.
- North America led with 43.67% share in 2024 due to advanced manufacturing, strict regulations, and strong pharmaceutical and beverage sectors. Europe followed with 28.23% share supported by automation and sustainability mandates, while Asia Pacific held 19.97% share driven by industrial expansion.
- Asia Pacific will be the fastest-growing region with 19.97% share in 2024, supported by rising packaged goods consumption, industrial growth in China and India, and adoption of automation.
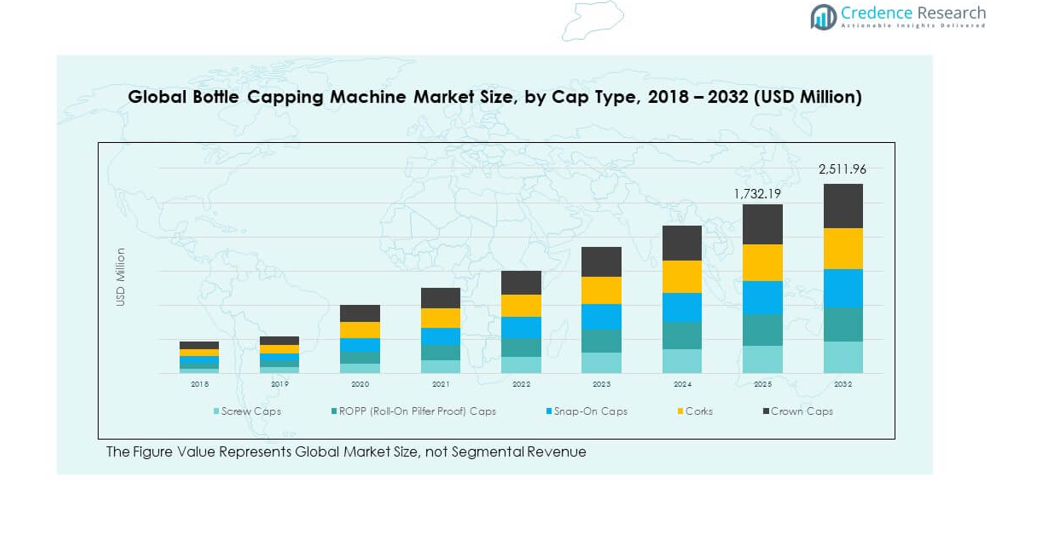
- Screw caps dominated segmental share in 2024 with 36%, reflecting their broad application in food, beverage, and pharmaceuticals due to tamper-evident properties and sealing reliability.
- Crown caps maintained significant demand in 2024 with 22%, largely supported by widespread use in beer, carbonated drinks, and ready-to-drink beverages, ensuring consistent growth in this segment.
Market Drivers
Rising Demand Across Food, Beverage, and Pharmaceutical Industries
The Global Bottle Capping Machine Market benefits from strong demand across critical industries. Food and beverage manufacturers invest in automated capping solutions to meet large-scale production needs. Pharmaceutical companies focus on product safety, creating a need for precise and tamper-proof closures. It supports faster throughput, reducing dependency on manual labor. Growth in packaged goods consumption further strengthens adoption across developed and emerging economies. Regulatory requirements for product integrity accelerate investments in modern machinery. Evolving consumer lifestyles continue to push manufacturers toward packaging upgrades. Global players adopt new systems to meet high-volume demands.
- For instance, Shemesh Automation’s Attilus, launched in 2022, is used by leading beverage and food companies as a continuous motion capping machine. It features integrated robotics and a vision system, enabling flexible, high-speed bottling lines and the ability to switch cap types at the touch of a button—directly addressing the large-scale production demands and quality requirements of international packaged goods brands
Integration of Automation and Smart Manufacturing Systems
The integration of automation drives operational efficiency in the Global Bottle Capping Machine Market. Manufacturers introduce advanced control systems for accuracy and consistency in production. Robotics integration enables faster changeovers and lower downtime. It ensures seamless operation in multi-product facilities with variable packaging demands. Predictive maintenance technologies reduce breakdown risks and improve system reliability. Growing emphasis on digital connectivity supports the adoption of Industry 4.0-enabled equipment. Smart sensors and data analytics optimize production lines with real-time monitoring. Competitive advantage grows for firms leveraging advanced automation in capping solutions.
Regulatory Compliance and Safety Requirements in Packaging Operations
Strict global standards for product packaging accelerate growth in the Global Bottle Capping Machine Market. Food safety authorities demand tamper-evident packaging across multiple product categories. It enforces precise sealing methods to protect consumer health. Pharmaceutical regulators ensure packaging integrity to maintain drug effectiveness and prevent contamination. Compliance creates opportunities for companies offering validated capping systems. Product recalls due to improper sealing reinforce the need for advanced technology. High-value industries prioritize equipment that meets international certification standards. Regulatory alignment drives consistent investment in reliable machinery.
- For instance, U.S. FDA regulation 21 CFR Part 820.72 requires validated and calibrated test equipment with full documentation, while 21 CFR Part 11 establishes standards for electronic records and audit trails. To meet these standards, leading packaging firms use capping machines with programmable torque control and electronic compliance systems, ensuring consistent sealing, regulatory adherence, and consumer safety.
Sustainability and Growing Focus on Energy-Efficient Machinery
Sustainability initiatives reshape investment patterns in the Global Bottle Capping Machine Market. Packaging firms demand systems that consume less energy and reduce material waste. It encourages adoption of servo-driven motors and lightweight design features. Rising environmental awareness motivates companies to adopt recyclable closure solutions. Governments push sustainability agendas with strict emission and waste policies. Energy-efficient machinery reduces long-term operating costs for manufacturers. Investments shift toward machines that align with green certifications and eco-friendly production goals. Market players differentiate by offering sustainable, high-performance systems.
Market Trends
Technological Innovation in Capping System Design and Mechanisms
Continuous technological advances influence the Global Bottle Capping Machine Market. New machine models support versatile cap types including screw, snap, and ROPP closures. It improves flexibility across diverse product lines. Servo-driven technology enhances torque accuracy and cap placement precision. Compact machine designs optimize factory space utilization for manufacturers. Quick-change mechanisms reduce downtime during production shifts. Integration of automated inspection systems ensures defect-free packaging. Companies invest in R&D to improve speed without compromising quality.
- For instance, Neostarpack’s NCW-415S Automatic Dual Servo Motor Capper features precise torque control via dual servo motors, adjustable for 30–60mm caps, offering capping speeds verified at 30 bottles per minute while using real-time PLC touch controls and safety sensors for quality and protection.
Expansion of Customized and Modular Machinery Solutions
The Global Bottle Capping Machine Market experiences rising demand for modular equipment. Customizable machines meet specific production requirements of mid-size and large companies. It supports adjustments for multiple bottle shapes and closure formats. Modular designs enable phased investments and incremental upgrades. Flexibility helps firms adapt to evolving consumer preferences. Small-scale manufacturers adopt compact solutions to match budget constraints. Large firms integrate modular systems to manage diverse product portfolios. Market competition grows as suppliers provide tailored configurations.
- For instance, the Optima Moduline Smart, installed by Louis Widmer, manages format changes across 14 closure and bottle formats using a modular frame and 3D-printed format parts, enabling faster configuration swaps. It has been demonstrated in cosmetics applications, particularly for pump dispensers, highlighting its flexibility and operational efficiency.
Digital Connectivity and Adoption of Industry 4.0 Practices
Industry 4.0 integration reshapes the Global Bottle Capping Machine Market. Machines incorporate sensors that provide real-time performance data. It enhances predictive maintenance and lowers downtime risk. Cloud connectivity enables remote monitoring of line performance. Manufacturers rely on big data analytics to optimize production cycles. Smart diagnostics reduce the need for frequent manual intervention. Digital twins improve equipment design and simulation before deployment. Industrial IoT platforms strengthen connectivity between capping machines and upstream systems.
Shift Toward Compact and Multi-Functional Packaging Equipment
The Global Bottle Capping Machine Market is witnessing a shift toward compact multi-functional machines. Demand for integrated systems combining filling, sealing, and labeling is increasing. It reduces overall equipment investment and factory space usage. Growing preference for turnkey solutions supports market expansion. Compact models appeal to small manufacturers entering competitive markets. Multi-functional machines improve productivity in large plants with diverse product lines. Operational simplicity drives adoption in regions with labor shortages. Industry suppliers compete on versatility and reduced production cost.
Market Challenges Analysis
High Capital Investment and Maintenance Complexity Limiting Adoption
The Global Bottle Capping Machine Market faces challenges related to capital intensity. High upfront investment discourages adoption by small and medium enterprises. It requires specialized maintenance, raising long-term operational costs. Technical complexity makes workforce training essential, creating additional expenses. Companies with limited budgets struggle to justify advanced system purchases. Breakdowns in automated equipment can halt entire production lines. Spare parts and service availability remain critical to ensure continuity. Competitive pricing pressure limits affordability for emerging manufacturers.
Regional Disparities and Slow Adoption in Developing Economies
Disparities across global markets create hurdles for the Global Bottle Capping Machine Market. Developed regions adopt automation quickly, while developing economies face barriers. It slows modernization due to limited industrial budgets. Infrastructure gaps restrict widespread machinery deployment. Local manufacturers often prioritize low-cost manual solutions over advanced equipment. Lack of skilled technicians limits the adoption of modern systems. Import duties increase machine costs in underdeveloped regions. Uneven adoption patterns reduce overall global standardization in packaging.
Market Opportunities
Growing Demand for Smart and Connected Packaging Solutions
The Global Bottle Capping Machine Market presents opportunities in connected packaging solutions. Integration with IoT supports real-time monitoring and predictive analytics. It improves productivity and reduces operational downtime. Smart features provide remote control options for operators. Consumer brands push for packaging traceability, expanding opportunities for machine suppliers. Demand for intelligent closures encourages investment in advanced systems. Suppliers offering connected solutions gain a stronger foothold in the competitive landscape.
Expansion in Emerging Economies with Rising Packaged Goods Consumption
Emerging markets generate significant opportunities for the Global Bottle Capping Machine Market. Rising disposable incomes increase demand for packaged beverages and pharmaceuticals. It drives investment in advanced production lines across Asia Pacific and Latin America. Local manufacturers seek affordable yet efficient equipment to scale operations. Global firms expand distribution networks to capture untapped demand. Export growth from developing nations strengthens the need for reliable packaging systems. Suppliers offering cost-effective models gain an advantage in emerging regions.
Market Segmentation Analysis:
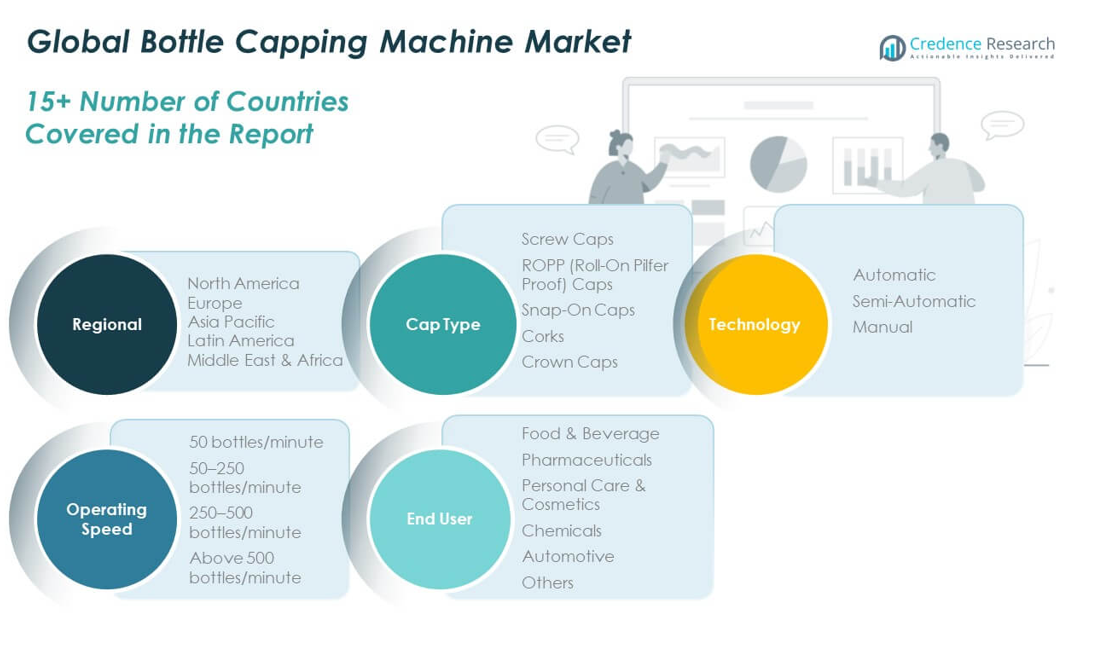
By Type, the Global Bottle Capping Machine Market demonstrates diverse growth patterns across cap type segments. Screw caps dominate due to wide usage in beverages, pharmaceuticals, and personal care, supported by their reliability and tamper-evident features. ROPP caps gain traction in alcoholic beverages and premium packaging, while snap-on caps meet demand in household and personal care products. Corks remain vital in wine and spirits packaging, while crown caps sustain demand in beer and carbonated drinks. Each segment reflects distinct industry preferences tied to product safety, branding, and consumer convenience.
- For instance, AROL offers automatic screw capping machines launched in 2023 that deliver speeds of up to 12,000 bottles per hour using 8 heads, making them one of the most efficient in their class for aluminum screw caps applications.
By technology, automatic machines hold the largest share as manufacturers prioritize efficiency, precision, and throughput. Semi-automatic machines attract small and mid-scale producers seeking flexibility, while manual machines continue to serve low-volume operations. Operating speed segmentation highlights strong adoption of 250–500 bottles/minute and above 500 bottles/minute categories, aligning with large-scale production facilities. Lower speed ranges retain importance among niche manufacturers.
- For instance, Krones AG’s rotary capper models are capable of processing up to 84,000 containers per hour for both screw and press-on cap types, supported by advanced servo and mechanical control for precision application.
By End-user analysis shows food and beverage as the dominant sector, followed by pharmaceuticals requiring stringent packaging compliance. Personal care and cosmetics expand steadily, with chemicals and automotive sectors adopting machines for product integrity. It benefits from the versatility of applications, ensuring steady demand across multiple industries.
Segmentation:
By Cap Type
- Screw Caps
- ROPP (Roll-On Pilfer Proof) Caps
- Snap-On Caps
- Corks
- Crown Caps
By Technology
- Automatic
- Semi-Automatic
- Manual
By Operating Speed
- 50 bottles/minute
- 50–250 bottles/minute
- 250–500 bottles/minute
- Above 500 bottles/minute
By End User
- Food & Beverage
- Pharmaceuticals
- Personal Care & Cosmetics
- Chemicals
- Automotive
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Bottle Capping Machine Market size was valued at USD 474.92 million in 2018 to USD 695.87 million in 2024 and is anticipated to reach USD 1,100.26 million by 2032, at a CAGR of 5.5% during the forecast period. North America holds 43.67% share of the global market in 2024. Strong demand from food and beverage manufacturers drives steady adoption of automated machinery. Pharmaceutical packaging regulations enforce strict standards, making capping solutions essential. It benefits from the presence of major machine manufacturers and strong R&D infrastructure. Advanced automation and Industry 4.0 adoption further accelerate uptake. Growing e-commerce contributes to higher packaged product demand. The U.S. dominates due to its mature industrial base, followed by Canada and Mexico. The regional focus on sustainability also shapes investment in efficient capping systems.
Europe
The Europe Global Bottle Capping Machine Market size was valued at USD 314.71 million in 2018 to USD 449.61 million in 2024 and is anticipated to reach USD 668.75 million by 2032, at a CAGR of 4.7% during the forecast period. Europe accounts for 28.23% share of the global market in 2024. Demand is led by advanced packaging requirements in Germany, France, and the UK. Strict EU regulations on product safety encourage adoption of tamper-proof and precise capping solutions. It benefits from the strong presence of global machine manufacturers and advanced automation practices. Growing investments in personal care and cosmetics industries fuel demand for specialized machines. Sustainability commitments push manufacturers to adopt energy-efficient models. Emerging Eastern European economies provide new growth prospects. The region demonstrates balanced adoption across multiple industries including food, beverage, and pharmaceuticals.
Asia Pacific
The Asia Pacific Global Bottle Capping Machine Market size was valued at USD 197.52 million in 2018 to USD 318.13 million in 2024 and is anticipated to reach USD 571.06 million by 2032, at a CAGR of 7.2% during the forecast period. Asia Pacific captures 19.97% share of the global market in 2024. Rising disposable incomes and population growth boost packaged goods consumption. China and India lead demand due to expanding manufacturing sectors. It benefits from the presence of low-cost manufacturing hubs and growing investment in automation. Japan and South Korea drive technological innovation in packaging machinery. Food, beverage, and pharmaceutical industries dominate machine adoption in the region. Growing exports of packaged products strengthen demand for reliable machinery. Government initiatives to modernize industries also fuel equipment purchases. Asia Pacific remains the fastest-growing regional market.
Latin America
The Latin America Global Bottle Capping Machine Market size was valued at USD 49.75 million in 2018 to USD 72.72 million in 2024 and is anticipated to reach USD 101.20 million by 2032, at a CAGR of 3.8% during the forecast period. Latin America holds 4.56% share of the global market in 2024. Brazil leads the regional market with strong demand in beverages and personal care sectors. It benefits from expanding local manufacturing bases and rising consumer spending on packaged goods. Argentina and Mexico also contribute to steady adoption. Growing exports of processed food and beverages increase demand for modern capping equipment. Limited automation in smaller plants restricts faster adoption. The region relies heavily on imports of advanced machinery from Europe and North America. Sustainability awareness is gradually shaping equipment preferences.
Middle East
The Middle East Global Bottle Capping Machine Market size was valued at USD 24.88 million in 2018 to USD 33.00 million in 2024 and is anticipated to reach USD 41.99 million by 2032, at a CAGR of 2.6% during the forecast period. The Middle East represents 2.07% share of the global market in 2024. Growing food and beverage consumption due to rising urban populations supports machine demand. GCC countries lead adoption with investments in modern packaging infrastructure. It experiences moderate growth due to reliance on imports and limited domestic manufacturing capacity. Pharmaceutical expansion in countries like Saudi Arabia drives localized demand. The presence of multinational beverage companies in the region boosts machinery installation. Israel shows progress in adopting automation in packaging operations. Regional diversification efforts in non-oil industries further create growth opportunities.
Africa
The Africa Global Bottle Capping Machine Market size was valued at USD 14.29 million in 2018 to USD 23.74 million in 2024 and is anticipated to reach USD 28.69 million by 2032, at a CAGR of 2.0% during the forecast period. Africa accounts for 1.49% share of the global market in 2024. South Africa leads regional demand with investments in beverage and food packaging facilities. It benefits from increasing urbanization and growing consumer demand for packaged goods. Egypt also contributes with demand from food processing and pharmaceuticals. Limited industrial infrastructure restricts wider adoption across the continent. Import dependency remains high due to lack of local manufacturing capacity. Smaller-scale producers rely on semi-automatic or manual equipment due to cost concerns. Future growth is expected as economies industrialize and foreign investments expand regional production bases.
Key Player Analysis:
- Krones AG
- Sidel Group
- SACMI Group
- KHS GmbH
- Syntegon Technology
- GEA Group
- ProMach Inc.
Competitive Analysis:
The Global Bottle Capping Machine Market is highly competitive, with multinational and regional players striving to strengthen their positions through innovation, partnerships, and expansions. It features established companies such as Krones AG, Sidel Group, SACMI Group, KHS GmbH, Syntegon Technology, GEA Group, and ProMach Inc., which focus on advanced automation, energy-efficient systems, and flexible designs. Smaller manufacturers compete by offering cost-effective and modular solutions to address niche demands. Strategic developments including mergers, acquisitions, and product launches are common approaches to expand global reach. Companies invest heavily in R&D to integrate smart technologies, predictive maintenance, and faster changeover mechanisms. It benefits from rising adoption of Industry 4.0 practices, where data-driven insights optimize equipment performance. Regional players emphasize affordability and localized service to compete against global leaders. Competitive intensity continues to grow as industries prioritize operational efficiency, sustainability, and precision in packaging operations.
Recent Developments:
- In Nov 2024, KHS GmbH and Ferrum Packaging AG jointly acquired H.F. Meyer Maschinenbau GmbH & Co. KG, forming a competence center for canning technology and packaging machine integration. This merger allows KHS to strengthen its presence in the canning machinery segment, drawing on H.F. Meyer’s expertise in can turners and rinsers.
- In July 2024, ProMach completed the acquisition of MBF, an Italy-based company renowned for its high-precision bottle-filling and capping technologies, especially within the wine and spirits sector. This move expanded ProMach’s expertise in automated bottling lines and reinforced its global market position.
Report Coverage:
The research report offers an in-depth analysis based on Cap Type, Technology, Operating Speed and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Bottle Capping Machine Market will witness rising automation adoption to improve operational efficiency.
- Energy-efficient systems will gain preference as sustainability drives shape investment in modern equipment.
- Smart technologies including IoT and predictive maintenance will strengthen real-time monitoring capabilities.
- Demand from food and beverage producers will remain the largest contributor to market expansion.
- Pharmaceutical packaging growth will sustain demand for precision and tamper-proof sealing systems.
- Modular and compact machine designs will attract mid-sized manufacturers seeking flexible solutions.
- Emerging economies will fuel growth through expanding manufacturing capacities and packaged goods demand.
- Technological collaborations between global and regional players will accelerate product innovation.
- E-commerce expansion will drive need for higher throughput in automated capping lines.
- The market will maintain competitive intensity as firms pursue global reach and efficiency leadership.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bottle Capping Machine Market?
What factors are driving the growth of the Bottle Capping Machine Market?
What are the key segments within the Bottle Capping Machine Market?
What are some challenges faced by the Bottle Capping Machine Market?
Who are the major players in the Bottle Capping Machine Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bottle Capping Machine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bottle Capping Machine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,593.08 million → 2032: USD 2,511.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bottle Capping Machine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bottle Capping Machine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bottle Capping Machine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bottle Capping Machine Market Drivers
- 3.3 Bottle Capping Machine Market Restraints & Challenges
- 3.4 Bottle Capping Machine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bottle Capping Machine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bottle Capping Machine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bottle Capping Machine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bottle Capping Machine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bottle Capping Machine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bottle Capping Machine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bottle Capping Machine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bottle Capping Machine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bottle Capping Machine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bottle Capping Machine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bottle Capping Machine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bottle Capping Machine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bottle Capping Machine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bottle Capping Machine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bottle Capping Machine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bottle Capping Machine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bottle Capping Machine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bottle Capping Machine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bottle Capping Machine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
