
Market Overview:
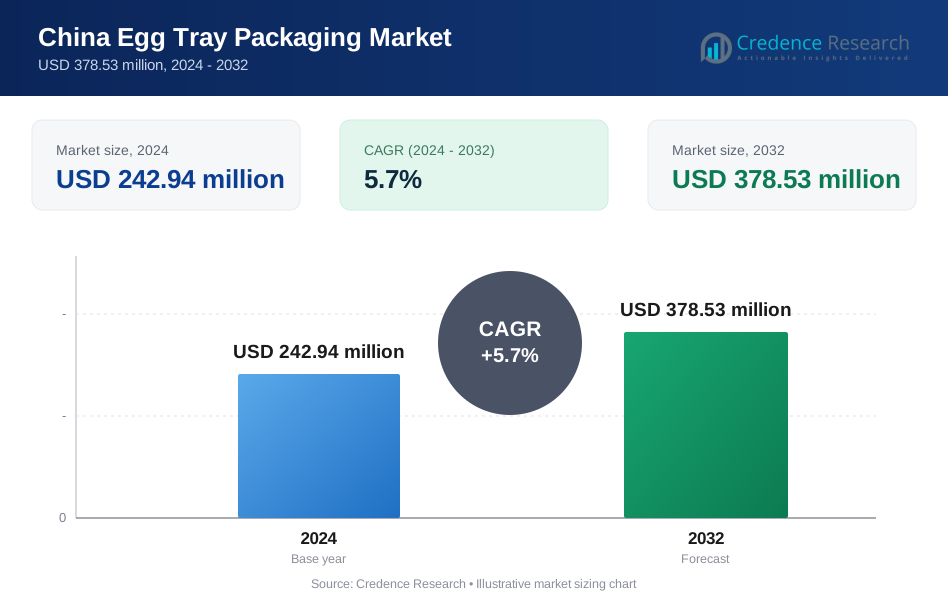
The China Egg Tray Packaging Market size was valued at USD 242.94 million in 2024 and is anticipated to reach USD 378.53 million by 2032, at a CAGR of 5.7% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| China Egg Tray Packaging Market Size 2024 | USD 242.94 Million |
| China Egg Tray Packaging Market, CAGR | 5.7% |
| China Egg Tray Packaging Market Size 2032 | USD 378.53 Million |
Several factors are driving the market’s expansion. The growing preference for eco-friendly packaging solutions, particularly in the food and beverage sector, is boosting the adoption of molded pulp egg trays. These trays, known for their biodegradability and recyclability, align with China’s stringent environmental regulations and the rising consumer demand for sustainable products. Moreover, the increasing penetration of organized retail and the expanding poultry industry are anticipated to further elevate market growth. The government's push for reducing plastic waste is also contributing to the market's momentum.
Regionally, East China leads the market, driven by its strong manufacturing base and significant poultry production. Additionally, the region's rapid urbanization and demand for convenience products are fueling the growth of egg tray packaging. Other regions, such as South and North China, are also witnessing steady growth due to the expanding food processing and retail sectors. With the continuous shift toward sustainability, these regions are expected to contribute significantly to market expansion over the forecast period.
Market Insights:
- The China Egg Tray Packaging Market was valued at USD 242.94 million in 2024 and is expected to reach USD 378.53 million by 2032, growing at a CAGR of 5.7%.
- Increasing demand for biodegradable and recyclable packaging is driving the market as molded pulp egg trays align with sustainability trends.
- Government policies to reduce plastic waste are pushing businesses to adopt eco-friendly packaging, boosting demand for molded pulp egg trays.
- The rapid expansion of China’s poultry industry is driving the need for efficient and sustainable packaging solutions, further supporting market growth.
- The rise of organized retail and e-commerce platforms in China is increasing the demand for safe, eco-friendly packaging for eggs.
- Fluctuations in raw material costs, particularly recycled paper and cardboard, could increase production costs and create supply chain challenges for manufacturers.
- Plastic packaging remains a strong competitor due to its lower cost and flexibility, posing challenges for molded pulp egg trays in large-scale operations.

Market Drivers:
Increasing Demand for Eco-Friendly Packaging Solutions
The growing demand for sustainable packaging is a key driver of the China egg tray packaging market. Consumers and businesses are becoming more environmentally conscious, favoring biodegradable and recyclable materials over plastic alternatives. Egg trays made from molded pulp offer an eco-friendly solution, meeting the rising demand for green packaging options in the food and beverage industry. With China’s stringent environmental regulations, manufacturers are increasingly adopting sustainable packaging solutions, further driving the market’s growth.
Government Support for Reducing Plastic Waste
The Chinese government has implemented various policies to reduce plastic waste and encourage the use of eco-friendly packaging. These measures include restrictions on single-use plastics and incentives for businesses that adopt sustainable practices. Such regulations are pushing companies in the food industry to transition from plastic to biodegradable alternatives, boosting the demand for egg tray packaging. This regulatory push is expected to continue driving market expansion in the coming years.
Growth of the Poultry Industry
The rapid expansion of China’s poultry industry is another significant driver for the egg tray packaging market. As poultry production grows, so does the need for efficient and protective packaging solutions to transport eggs safely. Egg trays made from molded pulp provide the necessary protection while ensuring minimal environmental impact. With China being one of the largest egg producers globally, the continuous growth of this sector will play a crucial role in the market’s development.
- For instance, GI-OVO serves the poultry industry with its innovative EggsCargoSystem, a solution so durable that some of its high-quality components have a service life of more than 15 years.
Expansion of Organized Retail and E-Commerce
The increasing penetration of organized retail and the rise of e-commerce platforms are also fueling the demand for egg tray packaging in China. As supermarkets and online grocery platforms expand, the need for safe and sustainable packaging for eggs and other perishable goods rises. Egg tray packaging, with its protective qualities and eco-friendly nature, is well-positioned to meet these growing demands. This trend supports the market’s growth by catering to the evolving needs of modern retail channels.
- For instance, to meet high-volume retail demand, AGICO has developed the fully automatic ZMDT8*8-10000 egg tray production line, which is capable of producing 10,000 trays per hour.
Market Trends:
Increasing Adoption of Molded Pulp Packaging
One of the key trends in the China egg tray packaging market is the increasing shift towards molded pulp packaging. This material, made from recycled paper or cardboard, is gaining popularity due to its eco-friendly nature and cost-effectiveness. Consumers and businesses are gravitating toward molded pulp because it offers superior protection for eggs during transportation while maintaining environmental sustainability. It aligns with China’s growing focus on reducing plastic usage, and its biodegradability has made it a preferred choice in various industries. The growing focus on sustainable packaging has made molded pulp the go-to material for egg packaging, leading to its wider adoption by producers and retailers alike.
- For instance, in 2024, Brother developed an award-winning molded pulp design that absorbs shock efficiently by being positioned at only 4 corners of a printer, a technological achievement that reduced material usage while maintaining performance.
Advancements in Customization and Design
Customization is another emerging trend in the China egg tray packaging market. Manufacturers are increasingly focusing on providing tailored solutions to meet the specific needs of businesses, including different shapes, sizes, and branding options. Egg tray packaging is evolving to offer more than just protection; it is also becoming a part of the branding and marketing strategy for companies. This trend is particularly strong in the premium egg segment, where packaging design plays a crucial role in consumer appeal. As the market becomes more competitive, businesses are leveraging custom designs to differentiate their products, driving further innovation in the egg tray packaging sector. This trend is expected to continue, fueling the demand for more diverse and visually appealing packaging solutions.
- For instance, Mauser Packaging Solutions showcased a technological achievement with the introduction of its next-generation plastic egg tray, which is designed to last up to 10 years in normal operation, highlighting its durability and reusability.
Market Challenges Analysis:
Raw Material Availability and Cost Fluctuations
One of the key challenges facing the China egg tray packaging market is the fluctuation in the availability and cost of raw materials. Molded pulp, primarily made from recycled paper and cardboard, is subject to price volatility depending on the global supply of these materials. This fluctuation can increase production costs for manufacturers, affecting overall profitability. As demand for sustainable packaging rises, suppliers may struggle to meet this growing need, leading to potential shortages or price hikes. These issues can hamper the market’s growth if manufacturers cannot efficiently manage raw material costs or secure a stable supply chain.
Competition from Alternative Packaging Solutions
The China egg tray packaging market also faces strong competition from alternative packaging solutions, particularly plastic-based options. Despite the rising demand for eco-friendly products, some industries still prefer plastic packaging due to its durability, lower cost, and ease of mass production. Plastics offer greater flexibility in design and can be more cost-effective, especially for large-scale operations. This creates a barrier for molded pulp products, as some businesses may hesitate to transition to more sustainable packaging due to higher initial costs or limited availability of alternative materials.
Market Opportunities:
Growing Demand for Sustainable Packaging
The increasing shift toward sustainability presents a significant opportunity for the China egg tray packaging market. With governments and consumers prioritizing eco-friendly solutions, there is a growing market for molded pulp packaging, which offers biodegradability and recyclability. Companies adopting these sustainable alternatives can gain a competitive edge by meeting the rising demand for greener products. The push for reducing plastic waste and China's stricter environmental regulations create favorable conditions for molded pulp packaging to capture a larger market share in the egg packaging sector.
Expansion in Emerging Markets and Retail Channels
China's expanding retail and e-commerce sectors offer additional growth opportunities for the egg tray packaging market. As the poultry industry grows and retail chains continue to expand, the need for efficient and sustainable packaging solutions increases. E-commerce platforms, in particular, require packaging that ensures the safe delivery of perishable goods. With the shift toward online grocery shopping, molded pulp egg trays are becoming a preferred choice due to their protective qualities and eco-friendliness. This trend opens up new avenues for market players to increase their product offerings and tap into a wider consumer base.
Market Segmentation Analysis:
By Formulation
The China Egg Tray Packaging Market is primarily segmented into molded pulp and plastic egg trays. Molded pulp dominates the market due to its eco-friendly characteristics, biodegradability, and alignment with China’s strict environmental regulations. This formulation is favored for its sustainability, making it a preferred choice for the food packaging industry. Plastic trays remain prevalent due to their durability but are facing growing competition from molded pulp options as demand for sustainable packaging rises.
- For instance, Chinese equipment manufacturers have advanced the production of sustainable packaging, with some automated pulp molding machines achieving a production capacity of 7,000 egg trays per hour.
By Application
Key applications of egg tray packaging include the poultry industry, retail, and food processing sectors. The poultry industry leads the market as the primary consumer of egg packaging, driven by the growing demand for safe and efficient packaging solutions. Retailers, both physical stores and e-commerce platforms, are adopting molded pulp trays due to their eco-friendly appeal. The food processing sector is also a significant user, relying on egg trays for safe storage and transport, further boosting the market’s growth.
- For instance, packaging manufacturers supply to major Chinese poultry producers like Wen’s Food Group, which processed 1,101 million broilers in a single year.
By Distribution Channel
The distribution of egg tray packaging occurs through direct sales and retail channels. Direct sales to poultry producers and large food processing companies make up a substantial share of the market. Retail channels, particularly supermarkets and e-commerce platforms, are experiencing significant growth as consumers increasingly prioritize sustainable products. E-commerce platforms, driven by the rise in online grocery shopping, are becoming an essential distribution channel, further supporting the demand for eco-friendly packaging.
Segmentations:
By Formulation
- Molded Pulp
- Plastic
By Application
- Poultry Industry
- Retail
- Food Processing
By Distribution Channel
- Direct Sales
- Retail
- E-commerce
By Region
- East China
- South China
- North China
- Other Regions
Regional Analysis:
East China: Leading in Production and Demand
East China holds the largest share of the China egg tray packaging market, accounting for 38% of the total market value. The region's strong manufacturing base and substantial poultry production contribute significantly to its dominance. With major industrial hubs like Shanghai and Hangzhou, East China is a critical center for the production and distribution of egg trays. The region's rapid urbanization and robust infrastructure further support the increasing demand for molded pulp packaging, especially within the retail and food sectors. East China’s proximity to large-scale poultry farms also strengthens its position in the market.
South China: Strong Growth in Food and Beverage Sectors
South China commands 30% of the market share in the China egg tray packaging sector, fueled by its growing food processing and beverage industries. Cities like Guangzhou and Shenzhen play a central role in driving industrial development, creating higher demand for eco-friendly packaging solutions. As consumer preferences shift toward sustainable options, the need for molded pulp egg trays continues to rise. South China’s focus on modernizing its food supply chain and its expanding retail sector contribute to the steady growth of egg tray packaging in the region.
North China: Expanding Opportunities in Urban and Rural Areas
North China represents 22% of the China egg tray packaging market, with both urban and rural areas contributing to its growth. Cities like Beijing and Tianjin are experiencing increased demand for molded pulp packaging, driven by urbanization and eco-conscious consumer preferences. The region also benefits from steady poultry production, which drives the need for protective and sustainable packaging solutions. Rural demand for packaging solutions in local poultry farms is another contributing factor, supporting market growth across North China.
Key Player Analysis:
- Shuliy Machinery
- Hartmann
- Best Plus Pulp Co., Ltd.
- Huhtamaki
- DFM Packaging Solutions
- Omni-Pac Group
- Tekni-Plex
- Shandong Sunrising Paper & Pulp
- Edison Trade Co., Ltd.
- Kunze Import and Export Trading
- Hangzhou Key II Manufacturing Co., Ltd.
- Jiangsu Jincai Polymer Materials Science and Technology Co., Ltd.
Competitive Analysis:
The China Egg Tray Packaging Market is highly competitive, driven by the nation's large poultry industry and increasing demand for sustainable packaging solutions. Key players such as Brødrene Hartmann, Huhtamaki, and DFM Packaging Solutions dominate the market, with a strong focus on research and development to enhance product offerings. Domestic companies like Shandong Sun Paper and Zhejiang Huafeng Paper lead in molded fiber packaging, while international firms like Tetra Pak and Sealed Air offer plastic-based alternatives. These companies focus on vertical integration, technological advancements, and meeting regulatory standards. Market growth is influenced by government policies promoting food safety and environmental sustainability, encouraging manufacturers to adopt eco-friendly materials and automated processes to remain competitive and align with consumer preferences for biodegradable options.
Recent Developments:
- In September 2025, Hartmann&Forbes partnered with Lutron Electronics, integrating its handwoven natural textiles into Lutron's motorized shade systems as part of the "Native by Design" program.
- In July 2025, Huhtamaki launched a new line of compostable and recyclable ice cream cups, which are constructed from certified paperboard with a bio-based coating.
Report Coverage:
The research report offers an in-depth analysis based on Formulation, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The China Egg Tray Packaging Market will continue to experience growth driven by increasing poultry production and consumer demand for sustainable packaging.
- Eco-friendly and biodegradable materials will become increasingly popular, as manufacturers focus on reducing environmental impact.
- Advances in automation and manufacturing technology will improve production efficiency and reduce operational costs for key players.
- Government policies promoting food safety and environmental sustainability will further incentivize the adoption of sustainable packaging solutions.
- The rise of e-commerce and online grocery shopping will contribute to higher demand for egg tray packaging in the retail sector.
- Increased consumer awareness of sustainability will push companies to innovate with eco-friendly packaging options, such as molded fiber and paper-based trays.
- Local players will increasingly focus on expanding their market share by adopting cost-effective production techniques and offering customized solutions.
- The demand for premium and reusable packaging solutions will grow, driven by consumer preferences for higher-quality, durable products.
- The rise of animal welfare concerns and organic farming will create new opportunities for packaging manufacturers to cater to these niche markets.
- Overall, the market will evolve to meet both environmental standards and consumer expectations for more sustainable, high-quality packaging options.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Eco-Friendly Packaging Solutions
China's consumers and businesses are prioritizing sustainability, leading to a shift from plastic to biodegradable and recyclable molded pulp egg trays. This aligns with both consumer preferences and regulatory requirements, driving market growth.
Government Support for Reducing Plastic Waste
Stringent government policies and incentives to reduce single-use plastics are compelling food and beverage companies to adopt eco-friendly packaging, directly boosting demand for molded pulp egg trays.
Growth of the Poultry Industry
China's rapidly expanding poultry sector increases the need for efficient, protective, and sustainable egg packaging, as producers seek to ensure safe transport and storage of eggs while meeting environmental standards.
Expansion of Organized Retail and E-Commerce
The rise of supermarkets and online grocery platforms in China is increasing the demand for safe, sustainable, and visually appealing egg tray packaging, as these channels require reliable solutions for the delivery and display of perishable goods.
Advancements in Customization and Design
Manufacturers are offering tailored packaging solutions with enhanced branding and design features, especially for premium and differentiated egg products, which helps companies stand out in a competitive retail environment and supports market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for China Egg Tray Packaging, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the China Egg Tray Packaging market projected to grow between 2024 and 2032?
Which China Egg Tray Packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the China Egg Tray Packaging market?
Who are the leading companies in the China Egg Tray Packaging market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Poultry Industry
- 1.2.2 Retail
- 1.2.3 Food Processing
- 1.3 By Formulation
- 1.3.1 Molded Pulp
- 1.3.2 Plastic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 242.94 million → 2032: USD 378.53 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 China Egg Tray Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 China Egg Tray Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 China Egg Tray Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 China Egg Tray Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 China Egg Tray Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 China Egg Tray Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 China Egg Tray Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 China Egg Tray Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 242.94 million → 2032: USD 378.53 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 China Egg Tray Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Poultry Industry
- 12.3.7.2 Retail
- 12.3.7.3 Food Processing
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Formulation - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Molded Pulp
- 12.4.7.2 Plastic
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 China Egg Tray Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 China Egg Tray Packaging Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 China Egg Tray Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 China Egg Tray Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Shuliy Machinery
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hartmann
- 18.4 Best Plus Pulp Co., Ltd.
- 18.5 Huhtamaki
- 18.6 DFM Packaging Solutions
- 18.7 Omni-Pac Group
- 18.8 Tekni-Plex
- 18.9 Shandong Sunrising Paper & Pulp
- 18.10 Edison Trade Co., Ltd.
- 18.11 Hangzhou Key II Manufacturing Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

