
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pulp Molding Machine Market Size 2024 | USD 912.2 million |
| Pulp Molding Machine Market, CAGR | 3.9% |
| Pulp Molding Machine Market Size 2032 | USD 1,240.5 million |
Market Overview:
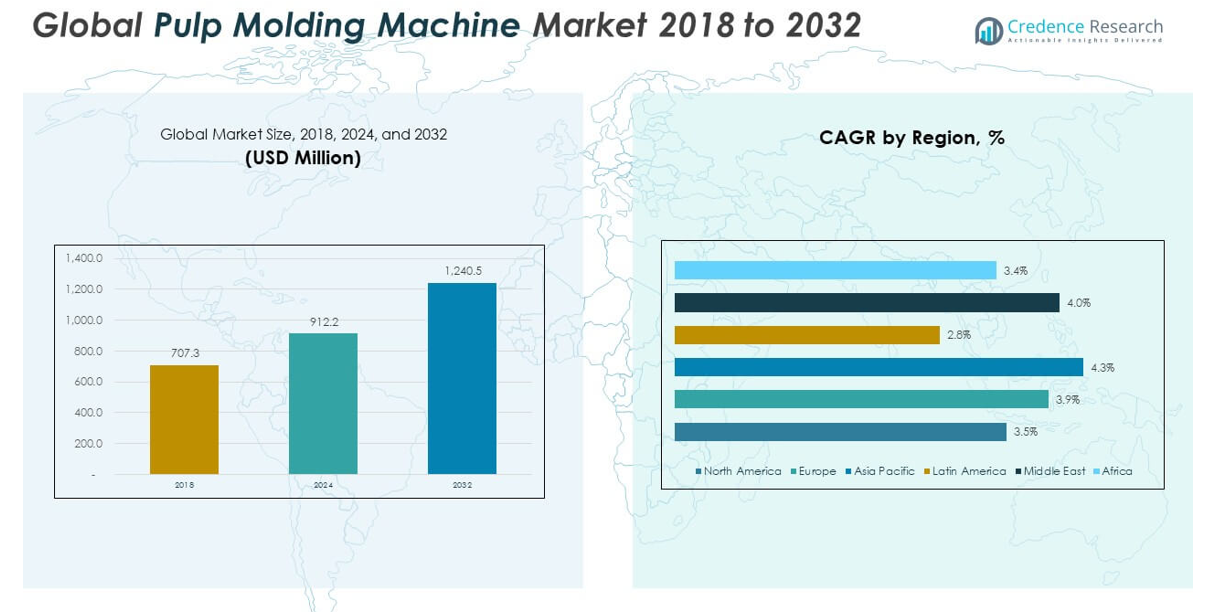
The Global Pulp Molding Machine Market size was valued at USD 707.3 million in 2018 to USD 912.2 million in 2024 and is anticipated to reach USD 1,240.5 million by 2032, at a CAGR of 3.9% during the forecast period.
The market is strongly influenced by a convergence of regulatory pressure and consumer demand for sustainable packaging. Governments across the globe are enacting legislation to ban or tax plastic packaging, compelling manufacturers to transition to biodegradable alternatives. This shift is creating significant opportunities for pulp molding machine suppliers. Additionally, technological advancements in automation, precision engineering, and energy-efficient systems have made pulp molding machines more reliable, cost-effective, and suitable for high-volume production. Integration of smart controls, AI, and IoT technologies is enabling manufacturers to improve productivity while minimizing waste. The surge in e-commerce and food delivery services has also increased the need for molded pulp protective packaging, such as trays, end caps, and clamshells, further accelerating market expansion. Companies are increasingly investing in flexible machines capable of producing customized packaging solutions, enhancing product appeal and reducing environmental footprints.
Regionally, Asia-Pacific dominates the global pulp molding machine market and is expected to retain the leading position due to rapid industrialization, expansion in foodservice sectors, and increasing adoption of green packaging in countries like China, India, and Japan. The region benefits from lower manufacturing costs and favorable government policies promoting sustainability. North America follows closely, led by the United States, which has witnessed significant growth in sustainable packaging adoption driven by advanced R&D, corporate sustainability commitments, and high consumer awareness. Europe also holds a substantial share, fueled by strict environmental regulations and well-established recycling infrastructure. Germany, France, and the UK are key contributors within the region. Meanwhile, Latin America and the Middle East & Africa are emerging markets with untapped potential, supported by growing consumer demand, regulatory developments, and infrastructural improvements. Collectively, these regional dynamics position the global pulp molding machine market for sustained, innovation-led growth in the coming decade.
Market Insights:
- The Global Pulp Molding Machine Market was valued at USD 707.3 million in 2018, reached USD 912.2 million in 2024, and is projected to reach USD 1,240.5 million by 2032, growing at a CAGR of 3.9% during the forecast period.
- Government bans and taxes on single-use plastics are accelerating the adoption of biodegradable packaging, creating strong demand for pulp molding machines across regions.
- The surge in e-commerce and food delivery services has increased the need for protective molded pulp packaging, such as trays, clamshells, and end caps.
- Integration of smart controls, AI, and IoT technologies is enabling manufacturers to enhance output quality, improve energy efficiency, and reduce production waste.
- Businesses are investing in customizable and flexible machines to align with ESG goals and rising consumer demand for environmentally responsible packaging.
- High upfront investment in machines, molds, and drying systems remains a challenge, particularly for SMEs without access to favorable financing or subsidies.
- Asia-Pacific leads the market with the largest share due to rapid industrialization and low-cost manufacturing, followed by North America and Europe; Latin America and MEA show emerging growth through infrastructure and regulatory support.
Market Drivers:
Sustainability Mandates and Bans on Single-Use Plastics Are Creating Long-Term Demand:
The Global Pulp Molding Machine Market is being propelled by tightening environmental regulations and government mandates aimed at phasing out single-use plastics. Regulatory bodies across North America, Europe, and Asia-Pacific are implementing policies that ban or heavily tax plastic packaging, compelling industries to adopt sustainable alternatives. Pulp molding machines enable the production of biodegradable and compostable packaging using recycled paper, aligning directly with these regulatory shifts. The global push toward reducing carbon footprints and landfill waste is accelerating investment in molded fiber packaging. Companies across food service, consumer electronics, and healthcare are integrating pulp-based trays and containers into their packaging portfolios. This shift toward regulatory compliance is reinforcing the value proposition of pulp molding systems across industrial sectors.
- For instance, Huhtamaki, a leading global packaging company, commissioned a new high-capacity molded fiber packaging facility in South Africa in 2024, featuring machines capable of producing over 1.2 billion fiber-based egg trays annually, directly replacing single-use plastics in food packaging.
Rise in E-Commerce and Food Delivery Fuels Packaging Needs:
The exponential growth of e-commerce and online food delivery platforms is driving demand for protective, lightweight, and sustainable packaging. Pulp molded products such as clamshells, trays, inserts, and end caps offer cushioning and structural integrity without relying on plastic foam or bubble wrap. The Global Pulp Molding Machine Market is benefiting from this trend by supplying the manufacturing equipment needed to produce scalable, eco-friendly packaging solutions. Companies are seeking packaging that is both cost-effective and compliant with environmental standards, making molded fiber a compelling choice. Increased urbanization and a shift toward contactless delivery services further boost the requirement for disposable yet sustainable packaging. The need for localized, high-speed production is encouraging businesses to invest in automated and flexible pulp molding equipment.
- For instance, Brødrene Hartmann A/S, a leading pulp molding equipment manufacturer, reported that its automated production lines delivered over 2.5 billion molded fiber packaging units in 2024 to support global e-commerce and food delivery chains, with each line capable of producing up to 60,000 trays per hour.
Technology Advancements Support Greater Customization and Efficiency:
Ongoing innovations in pulp molding machinery are significantly enhancing output quality, energy efficiency, and production flexibility. Equipment manufacturers are introducing automated systems with programmable logic controllers (PLCs), servo motors, and AI-based monitoring tools to streamline operations. These advancements reduce manual labor, minimize material wastage, and improve cycle times, making machines more viable for both large and small-scale applications. The Global Pulp Molding Machine Market is evolving as a result of increasing demand for custom-designed packaging, particularly in premium consumer goods and electronics. High-precision molding systems now allow for varied shapes, textures, and branding features, supporting marketing differentiation. The integration of Industry 4.0 elements is also enabling predictive maintenance and remote monitoring, enhancing machine uptime and operational efficiency.
Corporate Sustainability Goals and Consumer Awareness Are Driving Investment:
Companies are aligning their operations with environmental, social, and governance (ESG) frameworks, boosting capital investment in sustainable packaging technologies. The Global Pulp Molding Machine Market is gaining momentum as businesses seek to meet internal sustainability targets while responding to growing consumer preference for eco-friendly products. Brands are actively shifting toward molded fiber to improve product image and reduce long-term environmental liabilities. Consumer awareness around waste reduction and product lifecycle impact is influencing purchasing decisions, creating downstream pressure on manufacturers to adopt greener packaging. Public campaigns and green certifications have further amplified the importance of using compostable and recyclable materials. This shift in corporate and consumer priorities is cementing the role of pulp molding machines in next-generation packaging strategies.
Market Trends:
Automation and Smart Control Integration Are Redefining Equipment Capabilities:
Manufacturers in the Global Pulp Molding Machine Market are adopting advanced automation technologies to improve operational accuracy and reduce manual intervention. Smart control systems, including PLCs and human-machine interfaces (HMIs), are becoming standard features in modern pulp molding machines. These systems allow for real-time data monitoring, precise temperature and pressure control, and seamless adjustment of production parameters. The integration of sensors and remote diagnostic tools is enabling predictive maintenance and minimizing unplanned downtime. This shift toward smart automation is enhancing productivity while supporting consistent quality across high-volume operations. The market is seeing growing demand for machines that offer digital connectivity and compatibility with Industry 4.0 frameworks.
- For example, the latest generation of automatic pulp molding machines integrates smart sensors and IoT capabilities, enabling real-time monitoring, predictive maintenance, and process optimization.
Demand for Mold Flexibility and Multi-Product Compatibility Is Increasing:
A growing trend in the Global Pulp Molding Machine Market is the need for machines that support multiple mold configurations and rapid changeovers. End users require flexibility to produce different product types-such as trays, cup holders, clamshells, and industrial packaging-on a single machine platform. This shift is driven by seasonal demand fluctuations and diverse customer requirements, especially in contract manufacturing and private-label packaging. Equipment suppliers are responding by designing modular mold systems and quick-release mechanisms that reduce setup time. The ability to produce a wide variety of products without compromising efficiency or increasing labor input is becoming a key competitive differentiator. It is reshaping machine design priorities across the industry.
Growing Preference for Dry-Press and Hot-Press Systems to Enhance Finish Quality:
The market is witnessing a noticeable rise in demand for dry-press and hot-press pulp molding machines that offer superior surface finish and structural strength. These systems produce smooth, high-density products that are ideal for consumer-facing packaging applications, such as electronics, cosmetics, and luxury goods. The Global Pulp Molding Machine Market is moving beyond traditional wet-press techniques, especially in regions focused on value-added packaging. The ability to achieve precision shaping, sharp edges, and embossed branding features is attracting buyers in premium product segments. This trend is pushing manufacturers to invest in high-pressure molding equipment and specialized drying chambers. It supports differentiation in competitive consumer markets where packaging aesthetics influence brand perception.
Localization and Compact Machine Footprints Are Influencing Equipment Design:
With rising global interest in decentralized and small-scale manufacturing, the market is shifting toward compact and modular pulp molding machines. Businesses operating in urban or space-constrained environments are seeking equipment with minimal footprint and energy-efficient operations. The Global Pulp Molding Machine Market is adapting by offering machines that require less infrastructure while still delivering high throughput. This trend is particularly prominent among startups, SMEs, and community recycling initiatives aiming to create closed-loop production systems. Compact units also enable faster installation and relocation, increasing operational flexibility. It reflects a broader movement toward localized packaging solutions that reduce logistics costs and environmental impact.
- For instance, Guangzhou Nanya Pulp Molding Equipment Co. introduced a compact, integrative pulp molding laboratory machine in 2024, measuring just 2.3 meters in length and capable of producing up to 600 pieces per hour with an energy consumption of less than 0.15 kWh per piece.
Market Challenges Analysis:
High Initial Investment and Limited Access to Financing for Small Enterprises:
The Global Pulp Molding Machine Market faces a significant challenge in the form of high capital costs associated with advanced machinery. Many modern pulp molding systems require substantial upfront investment in equipment, molds, and drying systems. This cost barrier is particularly restrictive for small and medium-sized enterprises (SMEs) that lack access to favorable financing or government incentives. The complexity of installation and the need for skilled technicians further increase total ownership costs. It creates a divide between large-scale manufacturers with available resources and smaller players struggling to enter or expand within the market. Without broader financial support or cost-effective entry-level machines, market penetration in emerging regions may remain uneven.
Technical Limitations and Material Dependency Can Restrict Scalability:
Another core challenge impacting the Global Pulp Molding Machine Market involves technical constraints in achieving precision, consistency, and high-speed production. Pulp molding processes often depend on the quality and availability of raw materials such as recycled paper, which may vary across regions. Inconsistent feedstock can lead to quality issues, increased defect rates, and higher operational costs. Machines also face limitations in producing complex shapes or thin-walled structures required for some high-end applications. This restricts their use in specific packaging segments where plastics or molded plastics still dominate. It places pressure on manufacturers to innovate while maintaining low production costs and minimal environmental impact.
Market Opportunities:
Expansion of Sustainable Packaging in New Industry Verticals Presents Growth Potential:
The Global Pulp Molding Machine Market has strong opportunities in untapped sectors such as medical packaging, agriculture, and industrial component housing. As industries seek biodegradable and protective packaging alternatives, demand is emerging for molded fiber products beyond food service and consumer goods. Medical disposables, seedling trays, and protective cushioning for fragile industrial tools are opening new use cases for pulp molding technology. Equipment manufacturers can capitalize by developing machines tailored to specialized shapes, performance requirements, and hygiene standards. It allows diversification across sectors and supports long-term revenue stability for machine suppliers.
Government Support for Green Manufacturing Can Accelerate Market Entry:
Rising policy initiatives that promote circular economy models and local manufacturing present favorable conditions for growth. The Global Pulp Molding Machine Market stands to benefit from subsidies, grants, and tax incentives targeting eco-friendly packaging and recycling industries. Governments across Asia-Pacific, Europe, and Latin America are supporting infrastructure development and innovation in sustainable materials. Market participants that align with these initiatives can secure funding, reduce operational risks, and expand in cost-sensitive regions. It positions the industry to serve both environmental goals and economic development agendas.
Market Segmentation Analysis:
By Machine Type
Automatic pulp molding machines lead the market due to their high-speed operation, precision, and suitability for mass production. These machines are widely adopted by large manufacturers aiming for consistent output and reduced labor dependency. Semi-automatic machines follow in market share, offering a cost-effective solution with partial automation, making them ideal for mid-sized enterprises. Manual machines serve smaller operations with lower output needs and minimal capital investment, though their market share is limited due to labor intensity and lower productivity.
- For instance, Beston Group’s automatic tableware machine (model BCB-950s) can process up to 1 ton per day with fully automated trimming and hot-pressing, supporting large-scale packaging operations.
By Modularity
Rotary pulp molding machines account for the majority share in this segment due to their continuous production cycle, high efficiency, and reliability. These machines are favored in large-scale operations, particularly in the packaging of eggs and food containers. Reciprocating machines are preferred for specialized applications or where space and energy efficiency are priorities. They offer simpler mechanics and flexibility in design but typically support lower output volumes.
- For instance, Reciprocating machines offer design flexibility and are preferred for specialized or lower-volume applications, with energy consumption and output tailored to specific production needs.
By Application
Egg trays and cartons dominate the application segment, driven by consistent global demand from the poultry and agriculture sectors. Fruit trays and disposable plates & cups are gaining ground with the rise in sustainable food packaging solutions. Industrial packaging is an emerging use case as companies seek biodegradable protective alternatives. Other applications include specialty packaging for retail and promotional goods that require custom-shaped molds.
By End User Industry
Food & beverages represent the largest end-user segment, heavily investing in sustainable and compostable packaging. The electrical & electronics industry is increasingly adopting molded fiber inserts for protective transit packaging. The automotive sector uses pulp-based components for lightweight, recyclable packaging of spare parts. Consumer goods and healthcare sectors are expanding their use of molded fiber products to align with regulatory and environmental objectives. Other industries with niche or emerging applications are contributing to the market's overall diversification.
Segmentation:
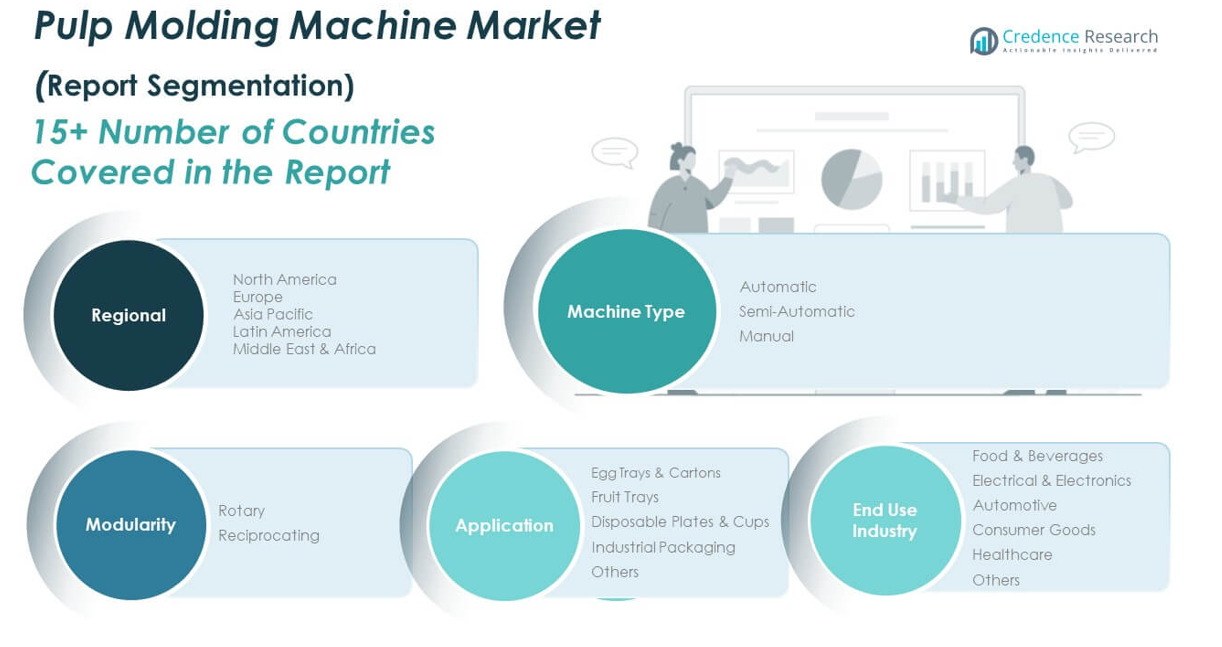
By Machine Type
- Automatic
- Semi-Automatic
- Manual
By Modularity
- Rotary
- Reciprocating
By Application
- Egg Trays & Cartons
- Fruit Trays
- Disposable Plates & Cups
- Industrial Packaging
- Others
By End User Industry
- Food & Beverages
- Electrical & Electronics
- Automotive
- Consumer Goods
- Healthcare
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America: Sustained Demand Driven by Innovation and Regulatory Alignment
The North America Pulp Molding Machine Market size was valued at USD 131.14 million in 2018 to USD 165.30 million in 2024 and is anticipated to reach USD 217.83 million by 2032, at a CAGR of 3.5% during the forecast period. North America accounts for approximately 18.1% of the Global Pulp Molding Machine Market. It benefits from strong environmental regulations, corporate sustainability commitments, and high consumer awareness around eco-friendly packaging. The United States leads the region in both consumption and production of molded fiber packaging, supported by advanced R&D capabilities and an established manufacturing base. Demand is particularly strong in the food and beverage, electronics, and healthcare sectors. Companies are increasingly shifting to biodegradable materials, prompting steady investment in automated, high-capacity pulp molding systems. The presence of leading equipment manufacturers and favorable financing conditions also contribute to regional growth.
Europe: Regulatory Enforcement and Circular Economy Fueling Growth
The Europe Pulp Molding Machine Market size was valued at USD 168.98 million in 2018 to USD 218.37 million in 2024 and is anticipated to reach USD 297.72 million by 2032, at a CAGR of 3.9% during the forecast period. Europe represents roughly 23.9% of the Global Pulp Molding Machine Market and continues to grow on the strength of stringent environmental regulations and circular economy initiatives. Countries such as Germany, France, and the UK are at the forefront of green packaging adoption. The region emphasizes recyclable, compostable materials across industries, increasing demand for high-precision and energy-efficient molding equipment. Government incentives and EU-wide sustainability targets are accelerating adoption of molded fiber technologies. The foodservice and consumer goods sectors dominate demand, while increasing e-commerce activity adds momentum. Localized production trends and energy efficiency standards influence equipment design preferences across Europe.
Asia Pacific: Largest and Fastest-Growing Market Led by China and India
The Asia Pacific Pulp Molding Machine Market size was valued at USD 241.27 million in 2018 to USD 318.56 million in 2024 and is anticipated to reach USD 446.58 million by 2032, at a CAGR of 4.3% during the forecast period. Asia Pacific holds the largest share of the Global Pulp Molding Machine Market, accounting for approximately 34.9%. Rapid industrialization, growing foodservice sectors, and favorable government regulations on plastic reduction are driving strong regional demand. China, India, and Japan lead the market with rising adoption of biodegradable packaging in both domestic and export-driven industries. Cost advantages in manufacturing, availability of recycled paper, and expanding logistics networks support market scalability. High-volume production requirements are prompting adoption of automated systems with quick mold change features. The region continues to attract foreign investment and technology partnerships to meet growing demand efficiently.
Latin America: Gradual Adoption Supported by Growing Awareness and Policy Shifts
The Latin America Pulp Molding Machine Market size was valued at USD 40.88 million in 2018 to USD 49.68 million in 2024 and is anticipated to reach USD 62.02 million by 2032, at a CAGR of 2.8% during the forecast period. Latin America contributes about 5.4% to the Global Pulp Molding Machine Market. The region is witnessing gradual adoption of sustainable packaging, mainly in Brazil, Mexico, and Argentina. Market growth is supported by increasing consumer awareness, regulatory developments, and shifts in retail and foodservice practices. Limited local production capacity for advanced machines creates import dependency, influencing equipment costs. However, public and private sector interest in reducing plastic waste is strengthening demand. Regional players are beginning to explore molded pulp for industrial and agricultural packaging, creating a base for long-term opportunity.
Middle East: Sustainability Goals and Hospitality Sector Drive Uptake
The Middle East Pulp Molding Machine Market size was valued at USD 76.25 million in 2018 to USD 99.20 million in 2024 and is anticipated to reach USD 136.45 million by 2032, at a CAGR of 4.0% during the forecast period. The Middle East accounts for around 10.9% of the Global Pulp Molding Machine Market. The region is increasingly investing in sustainable infrastructure and packaging technologies to align with national green visions and waste reduction goals. Countries like the UAE and Saudi Arabia are promoting non-plastic packaging solutions, especially in hospitality and foodservice industries. Rising demand for takeaway containers, cup holders, and agricultural trays is fueling equipment sales. Government-led initiatives to diversify industrial bases and reduce reliance on imports create favorable conditions for local pulp molding production. Access to capital and partnerships with international supplier’s support growth momentum.
Africa: Emerging Demand Amid Infrastructure and Funding Challenges
The Africa Pulp Molding Machine Market size was valued at USD 48.81 million in 2018 to USD 61.15 million in 2024 and is anticipated to reach USD 79.89 million by 2032, at a CAGR of 3.4% during the forecast period. Africa contributes approximately 6.5% to the Global Pulp Molding Machine Market. The region is in the early stages of sustainable packaging adoption, driven by urban growth, retail development, and environmental awareness. South Africa, Nigeria, and Kenya show emerging potential in food packaging and agriculture-related molded fiber products. Challenges related to infrastructure, financing, and skilled labor persist, slowing rapid uptake of advanced equipment. However, increasing pressure to replace plastic packaging and rising public-private collaboration are laying the foundation for gradual market expansion. It presents long-term growth prospects as demand for localized, low-cost, and eco-friendly packaging gains traction.
Key Player Analysis:
- DKM Machine Manufacturing Inc.
- Beston Group
- BeSure Technology
- Guangzhou Nanya Pulp Molding Equipment Co.
- Sodaltech
- Taiwan Pulp Moulding Co.
- Inmaco Solutions B.V.
- HGHY Pulp Molding
- Southern Pulp Machinery Ltd.
- Acorn Industry Co., Ltd.
Competitive Analysis:
The Global Pulp Molding Machine Market features a moderately fragmented competitive landscape with a mix of established global players and regional manufacturers. Key companies compete on technology innovation, machine efficiency, mold flexibility, and after-sales support. Leading manufacturers are investing in automation, AI integration, and modular design to meet rising demand for customized and sustainable packaging solutions. The market favors companies that can deliver high-speed production, energy efficiency, and minimal downtime. Partnerships with packaging converters, OEMs, and recyclers are strengthening competitive positions across Asia-Pacific, Europe, and North America. It continues to attract new entrants focused on low-cost, compact machines suited for SMEs and emerging markets. Competitive intensity is rising as players expand geographic reach and product portfolios to align with evolving sustainability mandates and customer expectations.
Recent Developments:
- In June 2025, NexGen Research released a report highlighting strong growth in rotary pulp molding machines. It noted the market reached USD 1.2 billion in 2024 with projected CAGR of 9.5% through 2033 based on rising demand and improved production technologies .
- In March 2025, Sodaltechsupplied its Automatic Spiral Paper Core/Tube Production Line to Telangana and its Convolute Core/Drum Winding Machine to Iran, further expanding its global installations of fiber-based packaging machinery. In February 2025, Sodaltech also delivered a Paper Cone Production Line to Bangladesh, demonstrating its ongoing leadership in pulp and paper conversion equipment for sustainable packaging applications.
- In May 2024, Beston Group entered a strategic partnership with Corsair Group to combat plastic waste. It agreed to deliver and install ten advanced pyrolysis plants at Corsair’s facility in Finland, marking a major diversification into sustainable equipment solutions .
Market Concentration & Characteristics:
The Global Pulp Molding Machine Market exhibits moderate market concentration, with a combination of large multinational players and several regional manufacturers serving localized demand. It features a competitive mix of innovation-driven firms focused on automation, energy efficiency, and mold versatility. The market favors companies that can offer scalable, customizable solutions suited for diverse applications across food service, electronics, healthcare, and agriculture. It is characterized by growing demand for environmentally sustainable equipment, increasing automation levels, and the adoption of Industry 4.0 technologies. Buyers prioritize machines that offer operational reliability, reduced downtime, and compatibility with biodegradable materials. Regional diversity in regulations and raw material availability influences machine specifications and pricing strategies.
Report Coverage:
The research report offers an in-depth analysis based on by machine type, modularity, application, and end user industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global bans on single-use plastics will continue to drive adoption of biodegradable pulp molding systems.
- Advancements in automation and AI integration will improve machine precision, uptime, and throughput.
- Increasing demand from non-traditional sectors like healthcare and agriculture will expand market applications.
- Customization capabilities in molding technology will support product differentiation across end-use industries.
- Asia-Pacific will retain its leadership position due to rapid industrialization and favorable regulatory policies.
- North America and Europe will see sustained demand supported by corporate ESG targets and consumer awareness.
- Compact and energy-efficient machines will gain popularity among SMEs and decentralized manufacturers.
- Supply chain developments and access to recycled feedstock will influence machine adoption in emerging markets.
- Strategic collaborations between machine makers and packaging converters will enhance value chain efficiency.
- Government incentives for sustainable manufacturing will accelerate technology upgrades and regional expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustainability Mandates and Bans on Single-Use Plastics
Global regulatory pressure to eliminate single-use plastics is compelling manufacturers to adopt biodegradable packaging, directly increasing demand for pulp molding machines that enable production of compostable alternatives.
Growth of E-Commerce and Food Delivery
The rapid expansion of e-commerce and food delivery services is driving the need for protective, lightweight, and sustainable packaging, boosting the adoption of pulp molding machines for producing trays, clamshells, and end caps.
Technological Advancements in Automation and Smart Controls
Integration of automation, AI, and IoT technologies in pulp molding machines is improving productivity, energy efficiency, and product customization, making these systems more attractive for high-volume and flexible manufacturing.
Corporate Sustainability Goals and Consumer Awareness
Rising corporate ESG commitments and heightened consumer preference for eco-friendly packaging are prompting businesses to invest in pulp molding machines to align with sustainability targets and enhance brand image.
Expansion into New Industry Verticals
Emerging applications in sectors such as healthcare, agriculture, and industrial packaging are creating new growth opportunities for pulp molding machine suppliers, as these industries seek biodegradable and protective packaging solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Pulp Molding Machine Market?
What are the key segments within the Global Pulp Molding Machine Market?
What are some challenges faced by the Global Pulp Molding Machine Market?
Who are the major players in the Global Pulp Molding Machine Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Modularity
- 1.2.1 Rotary
- 1.2.2 Reciprocating
- 1.3 By Application
- 1.3.1 Egg Trays & Cartons
- 1.3.2 Fruit Trays
- 1.3.3 Disposable Plates & Cups
- 1.3.4 Industrial Packaging
- 1.3.5 Others
- 1.4 By Machine Type
- 1.4.1 Automatic
- 1.4.2 Semi-Automatic
- 1.4.3 Manual
- 1.5 By End User Industry
- 1.5.1 Food & Beverages
- 1.5.2 Electrical & Electronics
- 1.5.3 Automotive
- 1.5.4 Consumer Goods
- 1.5.5 Healthcare
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 912.2 million → 2032: USD 1,240.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pulp Molding Machine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pulp Molding Machine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pulp Molding Machine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pulp Molding Machine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pulp Molding Machine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pulp Molding Machine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pulp Molding Machine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pulp Molding Machine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 912.2 million → 2032: USD 1,240.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pulp Molding Machine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Modularity - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Rotary
- 12.3.7.2 Reciprocating
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Egg Trays & Cartons
- 12.4.7.2 Fruit Trays
- 12.4.7.3 Disposable Plates & Cups
- 12.4.7.4 Industrial Packaging
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Machine Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automatic
- 12.5.7.2 Semi-Automatic
- 12.5.7.3 Manual
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Food & Beverages
- 12.6.7.2 Electrical & Electronics
- 12.6.7.3 Automotive
- 12.6.7.4 Consumer Goods
- 12.6.7.5 Healthcare
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pulp Molding Machine End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Pulp Molding Machine Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Pulp Molding Machine Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Pulp Molding Machine Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DKM Machine Manufacturing Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Beston Group
- 18.4 BeSure Technology
- 18.5 Guangzhou Nanya Pulp Molding Equipment Co.
- 18.6 Sodaltech
- 18.7 Taiwan Pulp Moulding Co.
- 18.8 Inmaco Solutions B.V.
- 18.9 HGHY Pulp Molding
- 18.10 Southern Pulp Machinery Ltd.
- 18.11 Acorn Industry Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

