
Market Overview
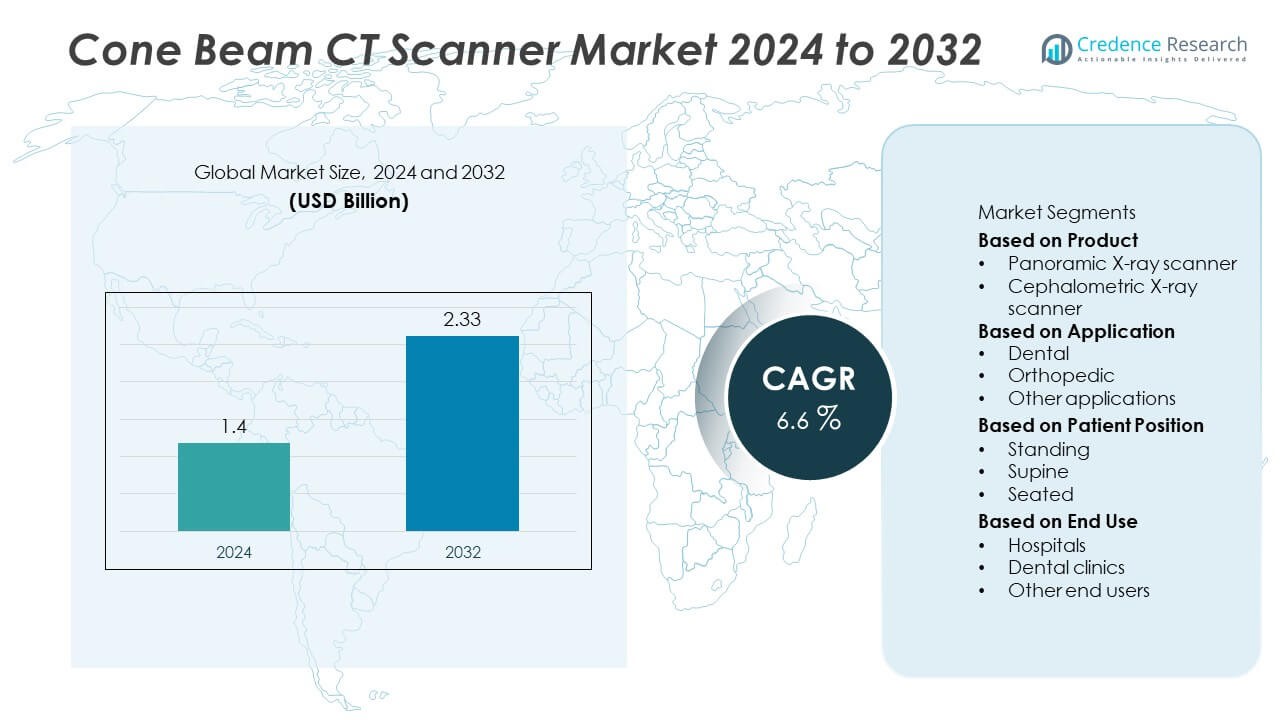
The Cone Beam CT Scanner Market was valued at USD 1.4 billion in 2024 and is projected to reach USD 2.33 billion by 2032, registering a CAGR of 6.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cone Beam CT Scanner Market Size 2024 | USD 1.4 Billion |
| Cone Beam CT Scanner Market, CAGR | 6.6% |
| Cone Beam CT Scanner Market Size 2032 | USD 2.33 Billion |
Top players in the Cone Beam CT Scanner market include Brainlab, AB-CT (Advanced Breast-CT), Hefei Meyer Optoelectronic Technology, CurveBeam AI, Carestream Health, Genoray, Dentsply Sirona, iCRco, Cefla Medical Equipment, and Asahi Roentgen, all focusing on advanced imaging quality, low-dose scanning, and AI-assisted diagnostics to strengthen their market positions. These companies expand portfolios with compact, clinic-friendly systems and enhanced software capabilities for dental, ENT, and orthopedic applications. Regionally, North America leads the market with a 38% share, supported by strong adoption of digital imaging technologies, while Europe follows with a 30% share, driven by increased demand for precision dentistry and low-dose imaging systems.
Market Insights
- The Cone Beam CT Scanner market reached USD 1.4 billion in 2024 and will grow at a 6.6% CAGR through 2032, driven by rising demand for advanced 3D diagnostic imaging.
- Market growth is supported by expanding dental implant procedures and orthodontic treatments, with dental applications holding a 64% segment share due to high need for precise anatomical evaluation.
- Key trends include AI-assisted diagnostics, low-dose imaging innovations, and increasing point-of-care adoption in dental and ENT clinics.
- Competition strengthens as leading manufacturers enhance imaging resolution, integrate automation tools, and expand into emerging regions through compact, cost-efficient CBCT systems.
- North America leads the global market with a 38% share, followed by Europe at 30% and Asia Pacific at 24%, while standing-position systems dominate patient positioning with a 49% share due to workflow efficiency and wide clinical compatibility.
Market Segmentation Analysis:
By Product
Panoramic X-ray scanners dominated the Cone Beam CT Scanner market with a 57% share in 2024, driven by their broad use in routine dental diagnostics, implant planning, and oral pathology assessment. These scanners provide wide-field imaging with lower radiation exposure, making them a preferred choice in dental practices and imaging centers. Cephalometric X-ray scanners accounted for a 43% share, supported by growing adoption in orthodontics and maxillofacial analysis. Their capability to capture craniofacial structures accurately enhances treatment planning in orthodontic care, contributing to steady demand across specialized clinics.
- For instance, Dentsply Sirona’s Orthophos S system delivers a field of view up to 11×10 cm and uses a pulsed exposure mode that cuts radiation output by 60%, supporting safer high-resolution imaging for implant workflows.
By Application
Dental applications held the leading position with a 64% share in 2024, driven by rising dental implant procedures, orthodontic treatments, and demand for precise 3D imaging. Dentists use cone beam CT for accurate surgical planning, assessment of tooth morphology, and detection of pathological conditions. Orthopedic applications accounted for a 22% share, supported by increasing use in extremity imaging and joint evaluation. Other applications such as ENT and sinus imaging represented the remaining 14%, benefiting from improved diagnostic accuracy and lower radiation exposure compared to conventional CT.
- For instance, Carestream Health’s CS 9600 platform features automated positioning with 10 facial landmarks and supports ultra-high-resolution scans at 75 µm, which enhances accuracy during implant depth and angulation planning.
By Patient Position
Standing-position systems dominated with a 49% share in 2024, driven by their space efficiency, ease of positioning, and suitability for most dental and ENT imaging procedures. These systems offer stable image quality and support faster workflow in high-volume clinical settings. Seated-position scanners accounted for a 34% share, favored for improved patient comfort and accessibility for elderly or mobility-impaired individuals. Supine-position systems held the remaining 17% share, primarily used in advanced diagnostic settings where complete immobilization and precise anatomical evaluation are required.
KEY GROWTH DRIVERS
Rising Demand for Advanced Dental Imaging
The growing number of dental implant procedures, orthodontic treatments, and maxillofacial evaluations drives strong adoption of cone beam CT scanners. Clinics prefer CBCT technology because it delivers accurate 3D imaging with lower radiation exposure than conventional CT. Increased emphasis on early diagnosis and precise treatment planning supports wider use in routine and specialized dental practices. Expanding dental tourism and rising awareness of oral health further accelerate market growth, especially in developing regions with growing private dental clinic networks.
- For instance, Planmeca’s ProMax 3D Mid system offers an endodontic imaging mode with a selectable voxel size down to 75 µm, enabling clear visualization of root canals and cortical bone. The typical anode current for the system is in the range of 1–14 mA.
Technological Advancements Enhancing Imaging Quality
Continuous innovation in imaging software, detector technology, and AI-assisted diagnostics enhances the clinical value of cone beam CT systems. Manufacturers develop scanners with faster image processing, sharper resolution, and optimized radiation dose control. AI-powered tools support automated measurements and improved diagnostic accuracy for dental and ENT applications. These advancements streamline workflows and reduce interpretation errors, making CBCT systems more attractive to clinics aiming to improve efficiency and patient outcomes.
- For instance, Dentsply Sirona’s Axeos CBCT integrates a high-definition sensor with a voxel resolution of up to 80 µm and an Intelligent Low Dose mode which uses a dedicated filter to provide 3D images at the radiation dose of a standard 2D X-ray, thereby maintaining image sharpness while minimizing patient exposure.
Growing Adoption in ENT and Orthopedic Applications
Beyond dentistry, cone beam CT systems gain traction in ENT and orthopedic diagnostics due to their ability to capture high-resolution images of sinuses, ear structures, and extremities. Their compact design and lower operational cost compared to full-size CT scanners make them suitable for clinics seeking cost-effective imaging solutions. Faster turnaround times and improved patient comfort support broader integration in outpatient settings. This diversification of clinical applications strengthens market expansion across multiple medical specialties.
Key Trends & Opportunities
Integration of AI and Automated Diagnostic Tools
AI-driven imaging analysis is becoming a key trend in the CBCT industry. Automated detection of anatomical landmarks, bone density measurement, and pathology identification enhances diagnostic accuracy and reduces clinician workload. Clinics adopt AI-supported CBCT platforms to improve precision in orthodontics, implantology, and ENT assessments. As AI capabilities evolve, integration with cloud-based imaging systems and digital workflows will create new opportunities for streamlined operations and data-driven treatment planning.
- For instance, Planmeca’s Romexis AI module analyzes CBCT datasets to perform automatic segmentation of jaws and nerve canals, a process that significantly reduces manual tracing time in implant planning workflows compared to traditional methods.
Increasing Demand for Low-Dose and Patient-Friendly Systems
Growing awareness of radiation safety drives development of low-dose CBCT systems that maintain high imaging clarity. Manufacturers introduce optimized scan modes and advanced filtration technology to reduce exposure, particularly for children and repeat imaging cases. Demand increases for compact, ergonomic systems that improve patient comfort and reduce motion artifacts. This trend supports wider adoption in dental chains, pediatric clinics, and outpatient centers seeking safer and more accessible imaging solutions.
- For instance, J. Morita’s Veraview X800 uses an automatic dose reduction function that can cut the radiation exposure by as much as 40% in areas with lower bone density, while achieving a high resolution of 80 µm voxel size in specific small field-of-view modes.
Expansion of Point-of-Care Imaging in Clinics
Smaller, portable, and clinic-friendly CBCT units are gaining popularity as point-of-care imaging becomes a priority in dental and ENT practices. These systems eliminate the need for external imaging referrals, enabling faster diagnosis and improved patient experience. Reduced installation space and simplified operation attract private clinics and mid-sized healthcare facilities. This shift toward in-house imaging supports stronger market penetration and creates opportunities for manufacturers offering compact, high-performance scanners.
Key Challenges
High Cost of Equipment and Installation
Cone beam CT scanners require significant investment in hardware, installation, and maintenance, which limits adoption among small and mid-sized clinics. Additional costs such as shielding, software licensing, and operator training increase financial burden. Many clinics rely on financing programs or shared imaging centers, slowing independent adoption. Cost pressure is more pronounced in emerging markets where healthcare budgets remain limited. Manufacturers must address affordability through efficient designs and flexible financing solutions to widen market reach.
Limited Reimbursement and Regulatory Barriers
In several regions, reimbursement for CBCT imaging remains restricted or inconsistent, discouraging investment by healthcare providers. Regulatory approvals can also be time-consuming due to strict standards for radiation-emitting devices. These barriers delay market entry for new models and reduce adoption among clinics seeking predictable revenue streams. Differences in national regulations further complicate global expansion for manufacturers. Addressing reimbursement gaps and ensuring compliance with evolving regulatory frameworks are essential for broader market penetration.
Regional Analysis
North America
North America held a 38% share of the Cone Beam CT Scanner market in 2024, driven by strong adoption of advanced dental imaging technologies and widespread use in orthodontics, implantology, and ENT diagnostics. The region benefits from high healthcare spending, a large base of dental specialists, and rapid integration of AI-enabled imaging software. Growing demand for minimally invasive procedures supports increased use of CBCT for accurate pre-operative planning. Favorable reimbursement in select applications and expanding dental chains further strengthen market growth. The presence of leading manufacturers and strong digital health infrastructure enhances adoption across clinics and hospitals.
Europe
Europe accounted for a 30% share in 2024, supported by rising emphasis on precision dentistry, growing orthodontic treatments, and adoption of low-dose imaging technologies. Strong regulatory guidelines encourage the use of safer and more efficient diagnostic tools, accelerating replacement of conventional X-ray systems with CBCT scanners. Countries such as Germany, the U.K., and France lead adoption due to well-established dental care networks and increasing demand for implant-based treatments. Investments in digital workflows and AI-driven analysis tools further support CBCT integration across dental practices, ENT clinics, and outpatient imaging centers.
Asia Pacific
Asia Pacific captured a 24% share of the Cone Beam CT Scanner market in 2024, driven by rapid growth in dental tourism, expanding private dental clinics, and rising awareness of early oral disease diagnosis. China, Japan, South Korea, and India show strong uptake due to improving healthcare infrastructure and increased focus on advanced 3D imaging. Growing disposable incomes and demand for cosmetic dentistry further boost adoption of CBCT systems. The region also benefits from local manufacturing capabilities and cost-effective product offerings, making advanced imaging more accessible to mid-sized practices and hospitals.
Latin America
Latin America held a 5% share in 2024, supported by growing dental implant procedures, rising orthodontic care demand, and expanding private dental networks. Countries such as Brazil and Mexico lead adoption as clinics modernize equipment and enhance diagnostic accuracy. Increased training programs and partnerships with global imaging manufacturers help improve clinician familiarity with CBCT technology. Despite budget constraints in public healthcare, the private sector drives market growth. Growing medical tourism and demand for high-quality dental treatments further support the expansion of CBCT systems across key regional markets.
Middle East & Africa
The Middle East & Africa region recorded a 3% share in 2024, driven by improving dental care infrastructure and rising investment in advanced diagnostic technologies. Countries such as the UAE and Saudi Arabia lead adoption due to strong private healthcare spending and growing interest in cosmetic dentistry. Clinics increasingly adopt CBCT for precise implant planning and ENT evaluations. In Africa, adoption remains limited but is gradually rising with expansions in private dental services and international partnerships. Continued investment in healthcare modernization creates long-term potential for CBCT penetration across the region.
Market Segmentations:
By Product
- Panoramic X-ray scanner
- Cephalometric X-ray scanner
By Application
- Dental
- Orthopedic
- Other applications
By Patient Position
- Standing
- Supine
- Seated
By End Use
- Hospitals
- Dental clinics
- Other end users
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the Cone Beam CT Scanner market features key players such as Brainlab, AB-CT (Advanced Breast-CT), Hefei Meyer Optoelectronic Technology, CurveBeam AI, Carestream Health, Genoray, Dentsply Sirona, iCRco, Cefla Medical Equipment, and Asahi Roentgen. These companies enhance competitiveness by developing high-resolution imaging systems, low-dose technologies, and AI-enabled diagnostic tools that support precise clinical decision-making. Many manufacturers focus on compact, workflow-friendly designs to meet the needs of dental clinics, ENT centers, and outpatient facilities. Strategic initiatives include product launches, partnerships with imaging software providers, and expansion into emerging markets with cost-effective systems. Companies also strengthen after-sales service networks and offer integrated digital platforms to improve practice efficiency. As demand for accurate 3D imaging rises across dental, orthopedic, and ENT applications, competition intensifies with ongoing innovation in software automation, radiation dose optimization, and multi-modality integration.
Key Player Analysis
- Brainlab
- AB-CT (Advanced Breast-CT)
- Hefei Meyer Optoelectronic Technology
- CurveBeam AI
- Carestream Health
- Genoray
- Dentsply Sirona
- iCRco
- Cefla Medical Equipment
- Asahi Roentgen
Recent Developments
- In July 2024, CurveBeam AI received FDA 510(k) clearance for an enhanced X-ray source for its HiRise system, enabling improved image quality in larger patients.
- In April 2024, CurveBeam AI launched a new Cone-Beam CT Imaging Orthopedics Course approved for ASRT continuing education credits.
- In March 2024, CurveBeam AI announced that the first personalized knee replacement procedure was planned using its HiRise weight-bearing CBCT system.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Patient Position, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for 3D dental imaging will rise as implant and orthodontic procedures continue to increase.
- AI-driven diagnostic tools will enhance accuracy and reduce interpretation time for clinicians.
- Low-dose CBCT systems will gain traction as radiation safety becomes a stronger priority.
- Compact and portable scanners will see higher adoption in small clinics and outpatient centers.
- Integration with digital workflows and cloud-based imaging platforms will streamline clinical operations.
- ENT and orthopedic applications will expand, supporting broader use beyond dental practices.
- Manufacturers will focus on improving image resolution and faster processing capability.
- Emerging markets in Asia Pacific and Latin America will adopt CBCT systems as healthcare infrastructure modernizes.
- Advanced software automation will support precise surgical planning and real-time assessment.
- Strategic partnerships between imaging companies and dental chains will accelerate global deployment.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cone Beam CT Scanner market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cone Beam CT Scanner market projected to grow between 2025 and 2032?
Which Cone Beam CT Scanner market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cone Beam CT Scanner market?
Who are the leading companies in the Cone Beam CT Scanner market?
Which region commanded the largest share of the Cone Beam CT Scanner market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.4 billion → 2032: USD 2.33 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cone Beam CT Scanner Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cone Beam CT Scanner Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cone Beam CT Scanner Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cone Beam CT Scanner Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cone Beam CT Scanner Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cone Beam CT Scanner Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cone Beam CT Scanner Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cone Beam CT Scanner Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.4 billion → 2032: USD 2.33 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cone Beam CT Scanner Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cone Beam CT Scanner Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cone Beam CT Scanner Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cone Beam CT Scanner Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

