
Market Overview:
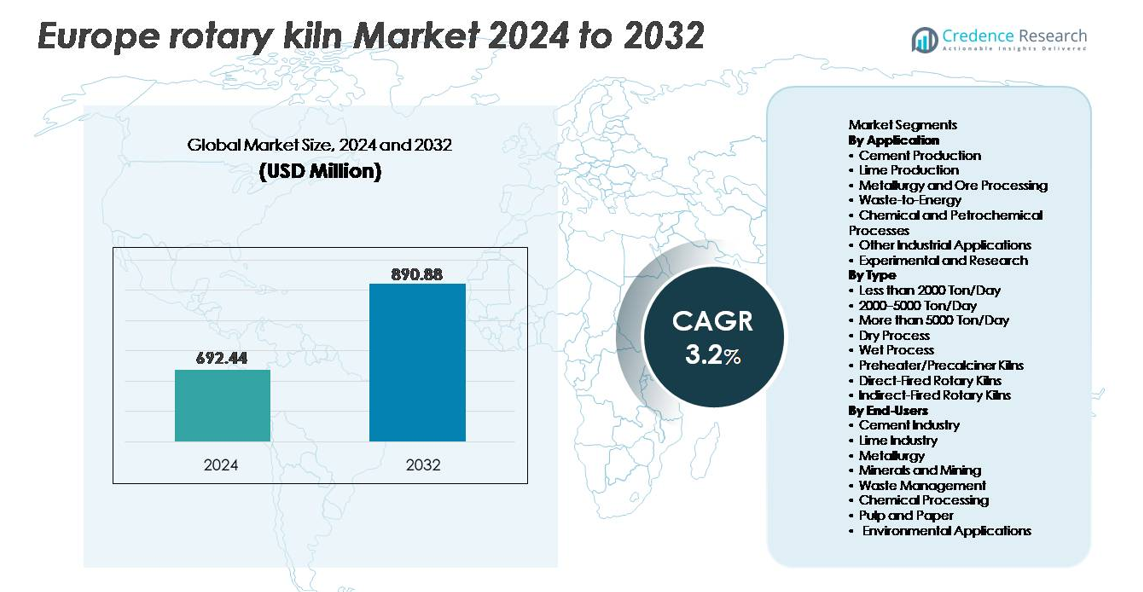
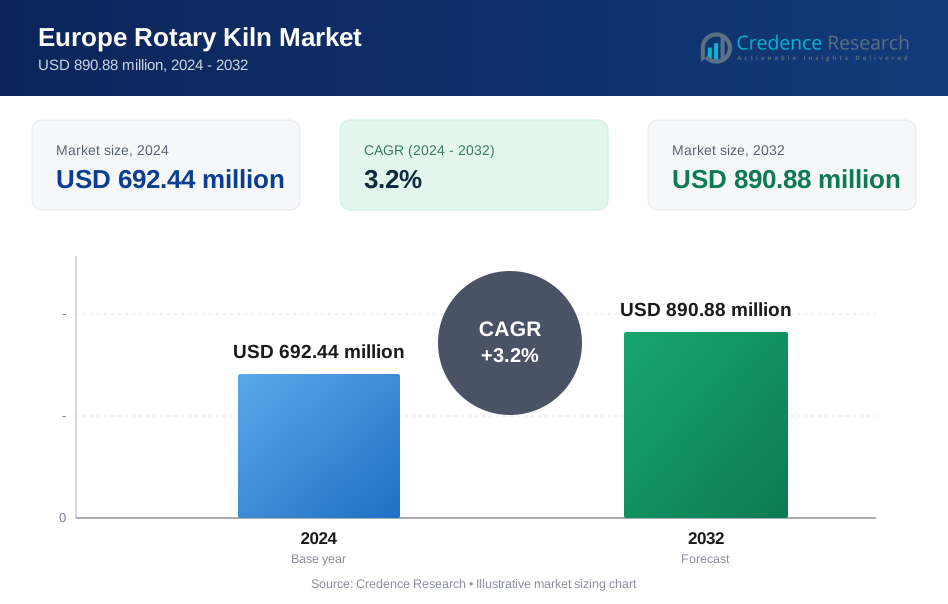
The Europe rotary kiln market was valued at USD 692.44 million in 2024 and is projected to reach USD 890.88 million by 2032, registering a CAGR of 3.2% during the forecast period (2025–2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Rotary Kiln Market Size 2024 | USD 692.44 million |
| Europe Rotary Kiln Market, CAGR | 3.2% |
| Europe Rotary Kiln Market Size 2032 | USD 890.88 million |
The Europe rotary kiln market is shaped by established global and regional manufacturers, including CITIC Heavy Industries Co., Ltd., FEECO International, Tongli Heavy Machinery, LNVT, Boardman, ANSAC PTY, Pengfei Group, Shanghai Minggong, FLSmidth, and NHI, each competing through technology integration, project execution capability, and lifecycle support. Western Europe accounts for the largest share of the market at approximately 42%, driven by advanced cement production facilities, strong waste-to-energy adoption, and continuous kiln modernization cycles. Northern Europe follows with its focus on emissions-compliant installations and automated thermal processing solutions, while Central and Eastern Europe demonstrate the fastest growth potential due to infrastructure expansion and industrial refurbishment investments.
Market Insights
- The Europe rotary kiln market was valued at USD 692.44 million in 2024 and is projected to reach USD 890.88 million by 2032, expanding at a CAGR of 3.2% during the forecast period.
- Demand is driven by infrastructure modernization, emission-compliant cement production, and the rising adoption of alternative fuels and waste co-processing in industrial plants.
- Market trends highlight rapid digitalization with predictive maintenance, combustion optimization, and IoT-based process monitoring improving asset reliability and reducing operational costs.
- Competitive activity intensifies as global players emphasize high-capacity, energy-efficient preheater/precalciner kilns, while regional manufacturers compete through custom engineering and refurbishment services; the cement production segment holds the largest share.
- Western Europe leads the market with around 38% share, followed by Northern Europe and Central & Eastern Europe, driven by strong waste-to-energy deployment, plant modernization, and expansion of lime and mineral processing capacities.
Market Segmentation Analysis:
By Application
By application, cement production represents the dominant sub-segment, accounting for the largest share of rotary kiln installations due to sustained infrastructure renewal programs, increased clinker capacity upgrades, and emission-compliant modernization across Europe. Lime production continues to expand driven by demand from construction, steelmaking, and flue-gas treatment in industrial plants. Metallurgy and ore processing adopt rotary kilns for controlled thermal reduction, while waste-to-energy applications gain traction with stricter landfill diversion policies. Chemical and petrochemical processes leverage rotary kilns for calcination and pyrolysis, whereas experimental use remains a niche but growing area among research institutions testing novel materials and thermal processes.
- For instance, FLSmidth’s modern rotary kilns for cement feature shell diameters of up to 6.5 meters and lengths exceeding 200 meters, supporting continuous clinker production at industrial scale with automated multi-channel burner systems capable of firing alternative fuels.
By Type
By type, preheater/precalciner kilns hold the dominant market share, primarily due to their superior thermal efficiency and ability to reduce fuel consumption compared to traditional designs. More than 5000 Ton/Day capacity kilns are preferred in high-volume cement operations, while the 2000–5000 Ton/Day category serves mid-scale plants optimizing output with lower operational burden. Direct-fired kilns remain essential in minerals and cement applications requiring high-temperature direct contact, whereas indirect-fired kilns serve sensitive chemical and metallurgical processes. Dry process kilns continue to replace wet process units as industry players pursue decarbonization targets and operational efficiency.
- For instance, FLSmidth’s preheater/precalciner kiln lines incorporate multi-stage cyclones capable of handling kiln gas volumes exceeding 600,000 cubic meters per hour, improving raw meal heat exchange and reducing thermal load on the main burner.
By End Users
By end user, the cement industry emerges as the dominant sub-segment, driven by investments in low-NOx burners, alternative fuel integration systems, and clinker line expansion across Europe. The lime industry contributes significantly through demand for construction-grade and environmental-grade lime for soil stabilization and emission control. Metallurgy and mining companies utilize rotary kilns for ore roasting, reduction, and pelletizing. Waste management operators deploy kilns for hazardous waste incineration and recycling. Chemical processors benefit from controlled thermal reactions, while pulp and paper, along with broader environmental applications, adopt rotary kilns for residue treatment and material recovery.
Key Growth Drivers:
Infrastructure Modernization and Expansion of Cement Capacity
Infrastructure modernization across Europe acts as a core driver for rotary kiln demand as governments prioritize renovation of transport networks, energy infrastructure, industrial facilities, and low-income housing. Regulatory pushes for sustainable cement production encourage replacement of older, inefficient kilns with upgraded energy-efficient configurations featuring automated combustion control, high-performance refractory linings, and preheater systems. Additionally, expanded use of blended cements and alternative raw materials has propelled investments in adaptable kiln designs capable of processing durable composites. Continuous clinker output growth in regions meeting post-industrial development and urban density demands supports long-term equipment cycles. The modernization wave also aligns with aging plant infrastructure nearing end-of-life and requiring full-line refurbishment to maintain output reliability.
- For instance, VDZ Germany has documented continuous operation cycles for modern dry-process kilns exceeding 330 operational days per year with planned downtime intervals under 30 days.
Increasing Adoption of Alternative Fuels and Waste Co-Processing
The rapid shift toward energy substitution in cement and lime plants serves as a significant growth catalyst, as rotary kilns enable co-processing of municipal solid waste, biomass residues, sewage sludge, and industrial byproducts. The ability to achieve complete destruction with high thermal efficiency supports compliance with carbon reduction and waste management directives. Alternative fuel-compatible kiln systems reduce fossil fuel dependence and create economic advantages amid volatile natural gas pricing. As Europe intensifies waste-to-fuel programs and circular economy frameworks, operators invest in retrofitting existing kilns to handle varied feedstock moisture and calorific values. This transition strengthens the economic and sustainability case for rotary kilns through dual-value utilization energy recovery and waste minimization.
- For instance, Heidelberg Materials has launched its "GeZero" carbon capture project at its Geseke plant in Germany, which aims to capture 700,000 tonnes of CO₂ annually from 2029.
Expansion of Lime and Chemical Processing for Environmental and Industrial Use
Demand growth for lime, caustic materials, and specialty chemical compounds drives adoption of rotary kilns in calcination and thermal decomposition applications. These materials are essential for water treatment, flue-gas desulfurization, soil stabilization, and metal refining all sectors experiencing regulatory-driven expansion. Rotary kilns provide controlled temperature gradients and consistent product quality, making them indispensable in processes producing reactants for power plants, steel smelting, and municipal waste incinerators. Increased reliance on industrial-grade lime for carbon capture sorbents and environmental purification accelerates kiln installations. The chemical sector’s shift toward specialty intermediates and advanced material synthesis further reinforces investment in precision-controlled indirect and direct-fired kilns.
Key Trends and Opportunities:
Automation, Digital Optimization, and Predictive Maintenance Technologies
Digitalization is reshaping rotary kiln operations through the integration of sensor-based process monitoring, AI-driven combustion optimization, and predictive maintenance analytics that minimize downtimes. Smart control systems evaluate flame shape, heat profiles, torque load, and emissions in real-time, ensuring fuel efficiency and consistent product characteristics. These technologies reduce operator-based variability and support regulatory compliance through continuous emissions monitoring. Opportunities emerge for OEMs offering digital retrofits and connected service models that extend asset lifespan and enhance kiln reliability. The trend aligns with the broader adoption of Industry 4.0 in cement, metallurgy, and waste sectors seeking operational certainty and cost transparency.
- For instance, FLSmidth’s ECS/ProcessExpert software uses advanced process control and AI algorithms to track and optimize a vast number of kiln and calciner operating parameters simultaneously, making real-time, continuous adjustments to manage complex process conditions and stabilize temperature fluctuations.
Waste-to-Energy and Material Recovery as High-Growth Deployment Areas
Europe’s strict waste management legislation accelerates demand for rotary kilns in waste-to-energy, hazardous waste treatment, and recycling of industrial residues. Kilns capable of achieving high-temperature oxidation and controlled atmosphere processing enable recovery of metals, heat, and usable byproducts. The move toward circular manufacturing unlocks opportunities for co-processing plants integrating fuel generation and raw material recovery. Municipalities and private waste operators increasingly deploy rotary kiln systems for incineration and pyrolysis to improve landfill diversion rates. Growth prospects strengthen as sustainability-linked investments incentivize thermal recovery technologies in chemicals, plastics, and construction waste streams.
- For instance, the FLSmidth HOTDISC system processes up to 4,500 kilograms of mixed municipal waste per hour directly in the calciner, enabling fossil fuel substitution without pre-shredding.
Key Challenges:
High Capital Expenditure and Cost of Modernization
Rotary kiln construction, installation, and operational modernization require significant capital expenditure, which constrains adoption for small and mid-sized operators. The cost burden includes refractory materials, emission control systems, automation integration, and reinforced foundations. Retrofitting existing infrastructure to handle alternative fuels or stricter emission standards increases investment complexity. Long payback cycles deter players in markets with volatile demand or limited financing access. The challenge intensifies with energy price unpredictability and maintenance costs associated with high-temperature mechanical fatigue, component replacement, and periodic overhauls.
Stringent Emission Regulations and Compliance Barriers
Compliance with Europe’s tightening environmental standards presents operational and technological challenges for rotary kiln operators. Kilns face rigorous controls on CO₂ output, NOₓ emissions, particulates, and volatile organic compounds, demanding advanced filtration, optimized combustion, and fuel switching systems. Implementation timelines and cross-border regulatory differences add complexities to capital planning. Failure to meet emission thresholds risks financial penalties, production shutdowns, or restricted operational hours. While regulations accelerate innovation, they also impose technical burdens requiring continuous monitoring, skilled personnel, and compliance cost absorption challenging operators with limited resources.
Regional Analysis:
Western Europe – 38% Share
Western Europe holds the largest market share at 38%, led by Germany, France, and the Benelux countries. Strong cement production, modern kiln lines, and mature waste co-processing networks support steady growth. High investment capacity and strict emission rules drive replacement of old wet-process units with efficient preheater and precalciner systems. Waste-to-energy projects also expand due to circular economy goals and landfill reduction laws.
Southern Europe – 22% Share
Southern Europe accounts for 22% of the market. Cement demand links to tourism-related construction, urban renovation, and seismic resilience programs in Italy, Greece, and Spain. Lime production for agriculture and steelmaking boosts rotary kiln use. Modernization moves at a moderate pace due to economic limits, while waste incineration and biomass co-firing create new opportunities for thermal recovery.
Northern Europe – 18% Share
Northern Europe holds 18% of the rotary kiln market. Sweden, Norway, and Denmark lead with advanced waste systems and carbon-neutral strategies. The pulp, paper, metals, and chemical sectors support adoption of indirect-fired and precision thermal units. Fuel substitution rules and automation upgrades create steady demand for retrofits as cement capacity remains stable.
Central & Eastern Europe – 17% Share
Central and Eastern Europe account for 17% of the market. Countries upgrade old industrial plants, increase cement output, and expand mineral processing facilities. EU-aligned emission targets encourage conversions to alternative fuels and digital combustion controls. Major infrastructure projects raise clinker demand, while cost-focused operators adopt robust, high-capacity kilns suited for long service life.
Market Segmentations:
By Application
- Cement Production
- Lime Production
- Metallurgy and Ore Processing
- Waste-to-Energy
- Chemical and Petrochemical Processes
- Other Industrial Applications
- Experimental and Research
By Type
- Less than 2000 Ton/Day
- 2000–5000 Ton/Day
- More than 5000 Ton/Day
- Dry Process
- Wet Process
- Preheater/Precalciner Kilns
- Direct-Fired Rotary Kilns
- Indirect-Fired Rotary Kilns
By End-Users
- Cement Industry
- Lime Industry
- Metallurgy
- Minerals and Mining
- Waste Management
- Chemical Processing
- Pulp and Paper
- Environmental Applications
By Geography
- Western Europe
- Southern Europe
- Northern Europe
- Central and Eastern Europe
Competitive Landscape:
The competitive landscape of the Europe rotary kiln market features a mix of global manufacturers, engineering solution providers, kiln service specialists, and regional fabrication companies competing across system design, fuel flexibility, digital optimization, and lifecycle maintenance. Large multinational players focus on supplying high-capacity, preheater and precalciner rotary kilns equipped with automation and emission control technologies, while mid-sized firms differentiate through customized configurations for lime, minerals, and chemical applications. Strategic partnerships between OEMs, refractory suppliers, and digital platform developers enhance system performance and predictive maintenance capabilities. Retrofitting and refurbishment services represent a fast-growing competitive segment as operators prioritize modernization over full replacement to reduce capital expenditure. The competitive edge increasingly depends on energy efficiency, alternative-fuel compatibility, operational reliability, and after-sales service networks that support long-term plant optimization.
Key Player Analysis:
- CITIC Heavy Industries Co., Ltd.
- FEECO International
- Tongli Heavy Machinery
- LNVT
- Boardman
- ANSAC PTY
- Pengfei Group
- Shanghai Minggong
- FLSmidth
- NHI
Recent Developments:
- FLSmidth announced a transformational divestment of its cement business in June 2025, entering into an agreement with Pacific Avenue Capital Partners for an initial consideration of EUR 75 million plus conditional deferred cash consideration of up to EUR 75 million. The transaction, expected to close in the second half of 2025, represents FLSmidth's strategic shift toward becoming a pure-play supplier to the global mining industry. Prior to this divestment, FLSmidth delivered a cutting-edge 115-meter rotary kiln to Sibanye-Stillwater's Keliber lithium refinery in May 2024, advancing sustainable lithium production technology.
- Indonesia Morowali Industrial Base Project: In January 2025, Pengfei Group was recognized as "Annual Excellent Supplier" and "Outstanding Contribution Partner for Overseas Projects in 2024" by Zhongwei New Materials Co., Ltd. This was for their work on high-capacity roasting and drying kilns for the first high ice nickel production line at the Zhongwei Indonesia Morowali Industrial Base, a project that successfully used the oxygen-enriched side-blowing furnace process for laterite nickel ore smelting industrially for the first time.
- Green Energy Strategy: Pengfei Group is implementing a strategy to integrate hydrogen energy. In March 2025, Chairman and President Zheng Peng spoke about the company's "dual carbon" initiatives at a 2025 Global South Financiers Forum event. In February 2025, they partnered with China Mobile Shanxi branch to create an AI industrial intelligence laboratory to support the hydrogen industry. The company intends to expedite the launch of two wind and solar power-to-hydrogen projects in Qinyuan and Chifeng in 2025.
- In March 2024, Pengfei secured an order with Valmet Europe for two wet-pulp caustic rotary kilns, indicating active supply of kiln systems to European clients.
- In January 2023, FLSmidth signed a contract to deliver pyro-processing technology including a rotary kiln to the lithium-hydroxide refinery project of Keliber in Finland.
Report Coverage:
The research report offers an in-depth analysis based on Application, Type, End-Users and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Adoption of energy-efficient preheater and precalciner kilns will accelerate as operators prioritize fuel cost reduction and emission compliance.
- Digital monitoring, automation, and predictive maintenance will become standard integration features across new and refurbished installations.
- Co-processing of industrial waste, biomass, and alternative fuels will expand as part of circular economy and waste-to-energy strategies.
- Retrofitting and refurbishment demand will increase as plants extend asset life instead of pursuing full replacement.
- Stricter environmental regulations will drive advanced emission control and low-NOx combustion solutions.
- Growth will strengthen in lime and mineral processing applications supporting steel, construction, and environmental treatment markets.
- Indirect-fired kilns will gain traction for chemical, specialty material, and temperature-sensitive applications.
- Regional consolidation among kiln manufacturers and service providers will intensify competition and technology partnerships.
- Financing models favoring energy-savings and operational performance contracts will emerge.
- Central and Eastern Europe will remain the most attractive expansion corridor driven by industrial upgrades and new capacity additions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Infrastructure Modernization and Cement Capacity Expansion
Ongoing infrastructure renewal and expansion of cement production facilities across Europe are driving demand for rotary kilns, as governments and private operators invest in modern, energy-efficient equipment to meet urbanization and regulatory requirements.
Adoption of Alternative Fuels and Waste Co-Processing
The shift towards alternative fuels and waste co-processing in cement and lime plants is accelerating rotary kiln upgrades and retrofits, as operators seek to reduce fossil fuel dependency, comply with carbon reduction targets, and benefit from waste-to-energy incentives.
Stringent Emission Regulations and Decarbonization Initiatives
Tightening European emission standards for CO₂, NOₓ, and particulates are compelling kiln operators to invest in advanced combustion, filtration, and process control technologies, fostering demand for new and refurbished rotary kilns with integrated emission control systems.
Digitalization, Automation, and Predictive Maintenance
The integration of digital monitoring, automation, and predictive maintenance solutions is enhancing kiln reliability, operational efficiency, and regulatory compliance, prompting both new installations and retrofits as part of Industry 4.0 adoption in cement, lime, and waste sectors.
Growth in Lime, Chemical, and Environmental Applications
Rising demand for lime in construction, steelmaking, and environmental treatment, as well as increased use of rotary kilns in chemical and specialty material processing, is broadening the market beyond cement and supporting sustained equipment investments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Europe rotary kiln market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe rotary kiln market projected to grow between 2024 and 2032?
Which Europe rotary kiln segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe rotary kiln market?
Who are the leading companies in the Europe rotary kiln market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Less than 2000 Ton/Day
- 1.2.2 2000–5000 Ton/Day
- 1.2.3 More than 5000 Ton/Day
- 1.2.4 Dry Process
- 1.2.5 Wet Process
- 1.2.6 Preheater/Precalciner Kilns
- 1.2.7 Direct-Fired Rotary Kilns
- 1.2.8 Indirect-Fired Rotary Kilns
- 1.3 By End-Users
- 1.3.1 Cement Industry
- 1.3.2 Lime Industry
- 1.3.3 Metallurgy
- 1.3.4 Minerals and Mining
- 1.3.5 Waste Management
- 1.3.6 Chemical Processing
- 1.3.7 Pulp and Paper
- 1.3.8 Environmental Applications
- 1.4 By Application
- 1.4.1 Cement Production
- 1.4.2 Lime Production
- 1.4.3 Metallurgy and Ore Processing
- 1.4.4 Waste-to-Energy
- 1.4.5 Chemical and Petrochemical Processes
- 1.4.6 Other Industrial Applications
- 1.4.7 Experimental and Research
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 692.44 million → 2032: USD 890.88 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Rotary Kiln Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Rotary Kiln Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Rotary Kiln Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Rotary Kiln Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Rotary Kiln Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Rotary Kiln Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Rotary Kiln Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Rotary Kiln Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 692.44 million → 2032: USD 890.88 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Rotary Kiln Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Less than 2000 Ton/Day
- 12.3.7.2 2000–5000 Ton/Day
- 12.3.7.3 More than 5000 Ton/Day
- 12.3.7.4 Dry Process
- 12.3.7.5 Wet Process
- 12.3.7.6 Preheater/Precalciner Kilns
- 12.3.7.7 Direct-Fired Rotary Kilns
- 12.3.7.8 Indirect-Fired Rotary Kilns
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Users - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cement Industry
- 12.4.7.2 Lime Industry
- 12.4.7.3 Metallurgy
- 12.4.7.4 Minerals and Mining
- 12.4.7.5 Waste Management
- 12.4.7.6 Chemical Processing
- 12.4.7.7 Pulp and Paper
- 12.4.7.8 Environmental Applications
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cement Production
- 12.5.7.2 Lime Production
- 12.5.7.3 Metallurgy and Ore Processing
- 12.5.7.4 Waste-to-Energy
- 12.5.7.5 Chemical and Petrochemical Processes
- 12.5.7.6 Other Industrial Applications
- 12.5.7.7 Experimental and Research
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Rotary Kiln End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Rotary Kiln Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Rotary Kiln Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Rotary Kiln Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CITIC Heavy Industries Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 FEECO International
- 18.4 Tongli Heavy Machinery
- 18.5 LNVT
- 18.6 Boardman
- 18.7 ANSAC PTY
- 18.8 Pengfei Group
- 18.9 Shanghai Minggong
- 18.10 FLSmidth
- 18.11 NHI
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

