
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Grid Modernization Market Size 2024 | USD 1,574.14 Million |
| France Grid Modernization Market, CAGR | 17.52% |
| France Grid Modernization Market Size 2032 | USD 5,728.08 Million |
Market Overview
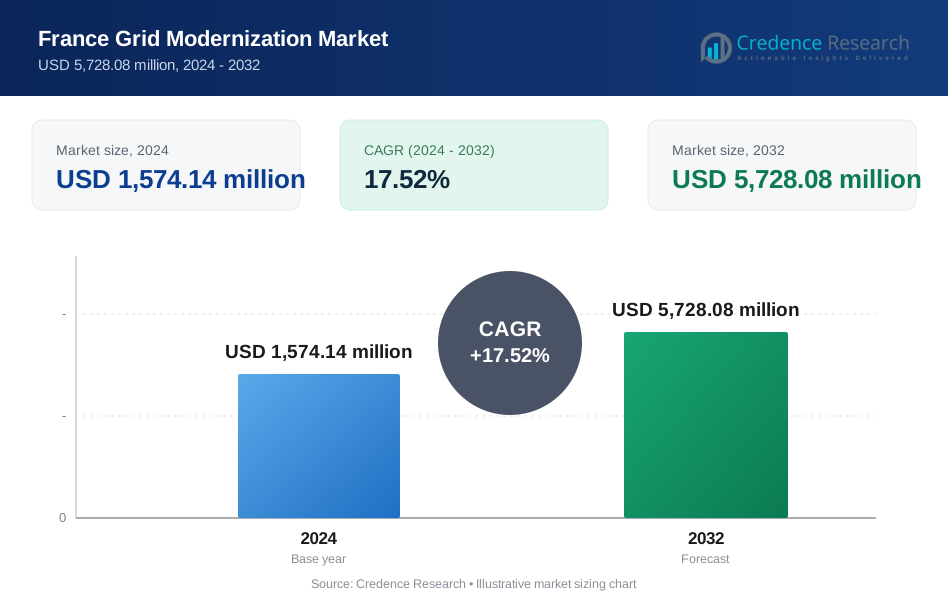
France Grid Modernization Market size was valued at USD 1,574.14 million in 2024 and is anticipated to reach USD 5,728.08 million by 2032, at a CAGR of 17.52% during the forecast period (2024-2032).
The France Grid Modernization market is driven by several key factors, including government initiatives focused on energy efficiency, sustainability, and the integration of renewable energy sources. The country's commitment to reducing carbon emissions and meeting climate targets has accelerated investments in smart grid technologies. Technological advancements, such as advanced metering infrastructure (AMI) and grid automation, enhance grid reliability and enable real-time monitoring, making the grid more responsive to fluctuating demand. Additionally, the rising adoption of electric vehicles (EVs) and decentralized energy generation systems necessitate grid modernization to ensure stability and accommodate these innovations. The growing emphasis on digitalization and data analytics within grid systems further supports efficiency and operational optimization. As France continues its transition toward cleaner energy sources, grid modernization is becoming essential for improving system resilience and ensuring a reliable power supply, ultimately driving the market’s expansion.
France’s grid modernization market is witnessing significant growth across various regions, driven by government initiatives, increasing renewable energy integration, and advancements in smart grid technologies. Northern and Southern France are at the forefront, with extensive deployments of smart meters, grid automation systems, and renewable energy infrastructure. Eastern France, with its strong industrial base, is focusing on modernizing power distribution networks to enhance efficiency, while Western France is investing in decentralized energy solutions and EV charging infrastructure. Key players driving this transformation include ABB Ltd., Siemens AG, Schneider Electric SE, Hitachi Energy, General Electric France, and Alstom SA, which are actively engaged in developing innovative grid technologies. Additionally, companies like Toshiba France, Landis+Gyr AG, Siemens Gamesa, and Eaton France are contributing to the sector through smart grid solutions, energy storage, and digitalization initiatives. These companies are continuously investing in research and strategic partnerships to support France’s transition to a more sustainable and resilient electricity network.
Market Insights
- The France Grid Modernization market was valued at USD 1,574.14 million in 2024 and is expected to reach USD 5,728.08 million by 2032, growing at a CAGR of 17.52% during the forecast period.
- Increasing government initiatives and investments in smart grid infrastructure are driving market growth.
- The rising adoption of renewable energy sources is accelerating the demand for grid modernization solutions.
- Advanced metering infrastructure (AMI) and digital grid management systems are key trends shaping the market.
- Leading players such as ABB Ltd., Siemens AG, Schneider Electric SE, and Hitachi Energy are investing in innovative grid technologies.
- High initial investment costs and cybersecurity risks pose challenges to widespread grid modernization.
- Northern and Southern France are leading in smart grid deployments, while Eastern and Western France are focusing on industrial grid upgrades and decentralized energy solutions.
Market Drivers
Government Initiatives and Regulations
Government policies and regulations play a crucial role in driving France’s grid modernization efforts. The French government has set ambitious targets to reduce carbon emissions and increase the share of renewable energy in the country’s energy mix. For instance, the Energy Transition for Green Growth Act outlines the national framework for action to develop alternative fuels and corresponding infrastructure, setting targets for public charge points and aiming for a significant increase in electric vehicle numbers by 2030. These regulations encourage the development and integration of smart grid solutions to enhance grid stability and facilitate the seamless integration of renewable sources such as solar and wind power. Through financial incentives, subsidies, and strategic frameworks, the government is fostering investments in advanced grid technologies that support energy transition and sustainability goals.
Increasing Demand for Renewable Energy
The growing reliance on renewable energy sources is another significant driver of grid modernization in France. As the country accelerates its efforts to meet its renewable energy targets, grid systems must adapt to accommodate the variable nature of these energy sources. For instance, the National Survey Report of PV Power Applications in France 2023 indicates a record growth in national photovoltaic capacity, highlighting the need for grid systems to manage the increased integration of solar power. Smart grids, energy storage systems, and enhanced grid infrastructure are necessary to integrate and manage renewable energy efficiently. These advancements help balance supply and demand, mitigate fluctuations, and ensure a steady and reliable power supply, thus supporting the energy transition.
Technological Advancements
Advancements in technology are transforming the landscape of grid modernization. Innovations such as advanced metering infrastructure (AMI), grid automation, and real-time monitoring are improving grid efficiency and reliability. These technologies enable utilities to detect faults, optimize energy flow, and manage grid operations more effectively. Moreover, digitalization and data analytics provide valuable insights for predictive maintenance and demand forecasting, reducing operational costs and enhancing system performance.
Growing Adoption of Electric Vehicles (EVs)
The increasing adoption of electric vehicles (EVs) in France is accelerating the need for grid modernization. EVs require efficient and reliable charging infrastructure, which puts additional pressure on existing grid systems. For instance, the Alternative Fuels Observatory reported a significant increase in EV registrations in May 2024, with nearly 200,000 new electric and hybrid vehicles on the roads since the beginning of the year. As the number of EVs on the road grows, the grid must be capable of handling the increased electricity demand while maintaining stability. Modernized grid solutions, including smart meters and dynamic load management, enable utilities to manage these new demands while ensuring optimal grid performance and energy distribution.
Market Trends
Increasing Investment in Smart Grid Technologies
One of the key trends driving the France grid modernization market is the increasing investment in smart grid technologies. For instance, Enedis, France's largest electricity distributor, has launched the "Linky Project" to replace 35 million residential meters with smart meters, going beyond EU requirements to set the foundation for the country's future smart grid. These systems leverage advanced sensors, communication networks, and automation to optimize energy distribution and consumption. Smart grids provide real-time data, enabling utilities to detect faults, manage energy flow, and improve overall efficiency. As a result, investments in technologies like advanced metering infrastructure (AMI), demand response systems, and grid automation are expected to grow, enhancing the operational capabilities of the grid.
Integration of Renewable Energy Sources
As France continues to pursue its renewable energy targets, the integration of renewable sources such as wind and solar power into the grid is a dominant trend. Modernizing the grid is essential for accommodating these intermittent energy sources, which require sophisticated management systems to balance supply and demand effectively. Grid modernization initiatives are focused on enhancing energy storage systems, improving grid flexibility, and developing advanced forecasting techniques to ensure a stable and reliable supply of electricity, even as renewable energy penetration increases.
Expansion of Electric Vehicle (EV) Infrastructure
The growing adoption of electric vehicles (EVs) in France is another major trend influencing grid modernization. EVs contribute to increased electricity demand, especially during peak hours, which places additional stress on traditional grid systems. To address this challenge, the integration of smart charging stations and vehicle-to-grid (V2G) technologies is gaining traction. These innovations allow for dynamic load management, enabling utilities to optimize energy distribution and reduce grid congestion. The expansion of EV infrastructure is thus closely tied to grid modernization efforts, creating a more resilient and flexible energy system.
Emphasis on Digitalization and Data Analytics
Digitalization and data analytics are playing an increasingly important role in the modernization of France’s grid. The deployment of digital technologies, including Internet of Things (IoT) devices, sensors, and data analytics platforms, enables utilities to monitor grid performance in real time and make data-driven decisions. Predictive analytics help prevent system failures, while enhanced monitoring capabilities provide insights into energy consumption patterns, enabling more efficient energy management. As digitalization continues to evolve, it is expected to drive significant advancements in grid efficiency, fault detection, and overall system resilience.
Market Challenges Analysis
High Initial Investment and Infrastructure Upgradation Costs
One of the major challenges in France’s grid modernization market is the high initial investment required for upgrading existing infrastructure. For instance, RTE, France's grid operator, has outlined a €1.88bn investment plan for 2023, which includes €448m for the reinforcement and creation of infrastructure to accommodate new electricity production and consumption facilities. Implementing smart grid technologies, such as advanced metering infrastructure (AMI), automation systems, and energy storage solutions, demands substantial financial resources. Utilities and energy providers must allocate significant capital for deploying these advanced systems while ensuring compatibility with existing grid networks. Additionally, modernizing aging infrastructure requires careful planning and execution to avoid disruptions in energy supply. The cost burden is particularly challenging for small-scale energy providers and municipalities, which may struggle to secure adequate funding. While government incentives and regulatory support help mitigate some financial barriers, the long payback periods and uncertain return on investment can deter widespread adoption of grid modernization technologies.
Cybersecurity Risks and Data Privacy Concerns
As France’s power grid becomes more digitalized, the risk of cyber threats and data breaches poses a critical challenge. Smart grids rely on interconnected networks, IoT devices, and real-time data exchange, making them vulnerable to cyberattacks. Any security breach could disrupt energy distribution, compromise sensitive consumer data, and pose national security risks. Ensuring robust cybersecurity measures, such as encryption protocols, intrusion detection systems, and regulatory compliance, is essential to safeguard the grid from potential threats. Additionally, data privacy concerns arise as smart grid technologies collect and analyze vast amounts of consumer energy usage data. Addressing these concerns through stringent data protection regulations and transparent policies will be crucial in gaining consumer trust and ensuring the successful implementation of grid modernization initiatives.
Market Opportunities
Expansion of Smart Grid Infrastructure
The modernization of France’s power grid presents significant opportunities for expanding smart grid infrastructure. With increasing government support and regulatory mandates focused on energy efficiency and sustainability, utility providers and technology firms can invest in advanced grid solutions. The integration of smart meters, automated distribution networks, and energy storage systems offers new business prospects for companies specializing in digital grid technologies. Additionally, growing consumer demand for energy management solutions and demand response programs creates opportunities for service providers to enhance grid efficiency and reliability. As France continues its transition toward a decentralized energy system, investments in microgrids and virtual power plants (VPPs) will further contribute to a more flexible and resilient electricity network.
Rising Demand for Renewable Energy Integration and EV Charging Networks
The increasing adoption of renewable energy sources and electric vehicles (EVs) in France presents lucrative opportunities for grid modernization. With a growing share of wind and solar power in the energy mix, modernized grids are essential for ensuring stability and optimizing energy distribution. Companies specializing in energy storage, grid balancing solutions, and predictive analytics can capitalize on this transition by providing innovative solutions that facilitate seamless renewable energy integration. Similarly, the rapid expansion of EV charging infrastructure requires smart grid technologies to manage fluctuating energy demands effectively. Investments in vehicle-to-grid (V2G) solutions, dynamic load management, and intelligent charging networks will be critical in supporting France’s sustainable mobility goals, positioning the grid modernization sector for substantial growth in the coming years.
Market Segmentation Analysis:
By Component:
The France Grid Modernization market is segmented into hardware, software, and services. The hardware segment holds a significant share as it includes essential components such as smart meters, sensors, advanced energy storage systems, and grid communication devices. The increasing deployment of smart meters and grid automation solutions drives demand for advanced hardware infrastructure. The software segment is experiencing rapid growth due to the adoption of digital grid management platforms, predictive analytics, and real-time monitoring systems that enhance grid reliability and operational efficiency. Utilities and energy providers are leveraging software solutions to optimize energy distribution, detect faults, and enhance grid security. Meanwhile, the services segment plays a crucial role in supporting grid modernization through system integration, consulting, and maintenance services. The need for efficient grid management and seamless implementation of modernization projects continues to drive the demand for professional services. As grid infrastructure becomes more complex, the reliance on software-driven solutions and ongoing service support is expected to rise, shaping the future growth of this market.
By Application:
Based on application, the France Grid Modernization market is segmented into residential, commercial, and industrial sectors. The residential segment is witnessing significant growth, driven by the increasing deployment of smart meters and home energy management systems that enhance energy efficiency. Consumers are adopting smart grid solutions to monitor energy consumption and reduce costs, further fueling market expansion. The commercial segment is also gaining traction, with businesses investing in energy optimization solutions, demand response programs, and smart building technologies to enhance sustainability. Additionally, commercial facilities require reliable grid systems to support renewable energy integration and EV charging infrastructure. The industrial segment remains a key driver of grid modernization due to high energy demand and the need for resilient power supply solutions. Industries are increasingly adopting smart grid technologies, automation, and advanced energy storage systems to improve efficiency, reduce operational costs, and ensure uninterrupted power supply. The growing focus on sustainability and energy transition is expected to accelerate the adoption of grid modernization solutions across all application segments.
Segments:
Based on Component:
- Hardware
- Software
- Services
Based on Application:
- Residential
- Commercial
- Industrial
Based on End-User:
- Utilities
- Independent Power Producers (IPPs)
- Government and Municipalities
Based on the Geography:
- Northern France
- Southern France
- Eastern France
- Western France
Regional Analysis
Northern France
Northern France holds the largest share of the grid modernization market, accounting for approximately 32% of the total market. This region serves as a major industrial and commercial hub, with Paris and its surrounding areas driving significant demand for advanced grid infrastructure. The high population density and concentration of businesses necessitate a stable and efficient power supply, leading to increased investments in smart grid technologies. Smart metering, grid automation, and demand response systems are widely implemented to enhance energy management and operational efficiency. Additionally, the region is witnessing strong government support for integrating electric vehicle (EV) charging stations and renewable energy sources into the grid. With continuous advancements in digital grid solutions and infrastructure upgrades, Northern France remains at the forefront of the country’s grid modernization efforts.
Southern France
Southern France accounts for around 28% of the France Grid Modernization market, experiencing rapid growth due to its strong focus on renewable energy integration. The region benefits from abundant solar and wind energy resources, driving investments in grid modernization to accommodate variable power generation. Smart grid technologies play a crucial role in balancing energy supply and demand while ensuring stability in the electricity network. Additionally, Southern France is witnessing a surge in microgrid and battery storage deployments, allowing for greater energy self-sufficiency and reduced dependency on centralized power plants. The increasing adoption of smart meters and grid automation systems enhances energy management capabilities, making the grid more responsive and efficient. With continued investments in clean energy projects and infrastructure upgrades, Southern France is poised to play a significant role in the country’s transition to a sustainable and resilient power grid.
Eastern France
Eastern France holds approximately 22% of the market share, driven by its strong industrial base and increasing energy efficiency requirements. The region is home to various manufacturing and heavy industries that require a stable and uninterrupted power supply. As industrial operations become more energy-intensive, the demand for smart grid solutions, including predictive maintenance, automation, and energy storage, continues to rise. Government incentives aimed at improving grid reliability and reducing carbon emissions further support market expansion in this region. Moreover, Eastern France is investing in digital grid technologies, allowing utilities to monitor energy flow in real time and optimize grid performance. The deployment of advanced grid infrastructure is helping industries reduce operational costs and improve sustainability, positioning Eastern France as a crucial contributor to the national grid modernization efforts.
Western France
Western France holds a market share of approximately 18%, with a strong focus on modernizing energy infrastructure to support smart cities and digital energy management solutions. The region has been actively deploying smart meters, IoT-enabled grid devices, and automation systems to enhance energy distribution efficiency. Investments in smart city projects, including intelligent street lighting and EV charging networks, are driving the adoption of modern grid technologies. Additionally, Western France is focusing on decentralized energy generation, with increased adoption of rooftop solar panels and small-scale wind farms. The emphasis on energy resilience and sustainability is encouraging utilities and local governments to modernize existing grid infrastructure. As digitalization efforts intensify, Western France is expected to play a crucial role in advancing France’s smart grid initiatives, ensuring a more efficient, reliable, and future-ready electricity network.
Key Player Analysis
- ABB Ltd.
- Siemens AG
- Schneider Electric SE
- Hitachi Energy
- General Electric France
- Alstom SA
- Toshiba France
- Landis+Gyr AG
- Siemens Gamesa
- Eaton France
Competitive Analysis
The France Grid Modernization market is highly competitive, with leading players focusing on innovation, strategic partnerships, and technological advancements to strengthen their market position. Key players include ABB Ltd., Siemens AG, Schneider Electric SE, Hitachi Energy, General Electric France, Alstom SA, Toshiba France, Landis+Gyr AG, Siemens Gamesa, and Eaton France. These companies are investing heavily in smart grid solutions, automation, and digital grid management to enhance energy efficiency and grid resilience. Industry leaders are increasingly investing in smart grid technologies, including advanced metering infrastructure (AMI), energy storage systems, and grid automation solutions. For instance, Efacec has secured a transformative contract with RTE, France's Transmission System Operator, to modernize and develop the electricity grid, involving the supply and installation of several dozen power transformers. These companies aim to enhance grid efficiency, integrate renewable energy sources, and improve energy management. To stay competitive, firms are prioritizing research and development to introduce next-generation solutions, such as predictive analytics, real-time monitoring, and cybersecurity advancements. In addition, strategic partnerships with local utilities and government bodies are being pursued to tap into the growing demand for energy-efficient grid solutions. As demand for renewable energy integration, electric vehicle (EV) charging infrastructure, and decentralized energy generation increases, companies are focusing on providing more flexible and scalable grid solutions. Furthermore, as the market grows, players are focusing on regional diversification, targeting both urban and rural areas for grid improvements. Competitive strategies like mergers, acquisitions, and expanding service portfolios are essential to securing a larger share of the rapidly evolving grid modernization market.
Recent Developments
- In October 2024, Hitachi Energy introduced Grid-enSure in India to advance the country's transition to sustainable energy. The company also announced plans to invest around INR 2,000 crore over the next four to five years in capacity expansion and upgrades for various transformer factories.
- In August 2024, Hitachi Energy called for urgent action to expand global power grids, reduce connection bottlenecks, and accelerate the energy transition. They launched Grid-enSure™ at the CIGRE 2024 Paris Session, a portfolio of solutions to enhance grid flexibility, resilience, and stability.
- In May 2024, Siemens revealed the Gridscale X software, a "co-pilot" for flexible low voltage grid management, aiming to reduce outages by up to 30%.
Market Concentration & Characteristics
The France Grid Modernization market exhibits a moderate to high level of market concentration, with a few major players dominating the sector while also witnessing increasing participation from regional and specialized companies. The market is characterized by strong competition among key players who are investing heavily in research and development to introduce advanced grid solutions, such as smart metering, grid automation, and energy storage systems. These technologies are essential for enhancing grid resilience, optimizing energy distribution, and integrating renewable energy sources. The market also has a diverse range of characteristics, with a blend of well-established companies and new entrants focusing on digital solutions and sustainable energy technologies. Companies are actively pursuing strategic partnerships with government bodies, utilities, and energy providers to meet the growing demand for smart grid technologies. The market is driven by the need to modernize aging infrastructure, improve energy efficiency, and reduce carbon emissions, which has led to an increase in investments in automation and digitalization. The growing adoption of electric vehicles and renewable energy sources is further fueling the demand for innovative grid solutions. With a focus on improving grid management, reliability, and sustainability, the France Grid Modernization market is poised for significant growth, attracting both large corporations and niche players seeking to offer specialized solutions.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-User, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The role of artificial intelligence and machine learning in grid optimization will expand, enabling more efficient energy distribution.
- The implementation of microgrids and decentralized energy systems will increase to support local energy generation and reduce transmission losses.
- As consumer awareness of energy efficiency rises, demand for smart home integration with grid systems will see notable growth.
- The focus on reducing grid congestion and improving transmission capabilities will drive the adoption of advanced grid technologies.
- Expansion of demand response programs will enhance grid flexibility by encouraging consumers to adjust their energy consumption patterns.
- The shift towards digital twins and simulation tools will allow for better planning and forecasting in grid modernization projects.
- Further penetration of the Internet of Things (IoT) in grid infrastructure will enable more seamless communication between devices and systems.
- The market will see a rise in collaboration with start-ups, as smaller innovators introduce cutting-edge solutions for grid efficiency.
- A growing emphasis on energy resilience will lead to the development of grids that can withstand extreme weather conditions and other disruptions.
- The French grid will increasingly be integrated into broader European grid initiatives, promoting cross-border electricity exchange and enhancing grid stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Initiatives and Regulations
Ambitious French government policies, such as the Energy Transition for Green Growth Act, are mandating carbon emission reductions and renewable energy integration, directly driving investments in smart grid and modernization technologies.
Increasing Demand for Renewable Energy
Rapid growth in solar and wind capacity requires grid systems to adapt to variable energy inputs, necessitating advanced grid management, storage, and automation solutions to ensure stability and reliability.
Technological Advancements
Deployment of advanced metering infrastructure (AMI), grid automation, and real-time monitoring is improving grid efficiency and reliability, enabling utilities to optimize energy flow and reduce operational costs.
Growing Adoption of Electric Vehicles (EVs)
The surge in EV adoption in France is increasing electricity demand and requiring robust, flexible grid infrastructure and smart charging solutions to maintain grid stability and support sustainable mobility.
Emphasis on Digitalization and Data Analytics
Utilities are leveraging digital platforms, IoT, and data analytics for predictive maintenance, demand forecasting, and real-time grid management, which enhances operational efficiency and supports the integration of decentralized energy resources.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the France Grid Modernization market?
What factors are driving the growth of the France Grid Modernization market?
What are the key segments within the France Grid Modernization market?
What are some challenges faced by the France Grid Modernization market?
Who are the major players in the France Grid Modernization market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Utilities
- 1.2.2 Independent Power Producers (IPPs)
- 1.2.3 Government and Municipalities
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Application
- 1.4.1 Residential
- 1.4.2 Commercial
- 1.4.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,574.14 million → 2032: USD 5,728.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 France Grid Modernization Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 France Grid Modernization Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 France Grid Modernization Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 France Grid Modernization Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 France Grid Modernization Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 France Grid Modernization Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 France Grid Modernization Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 France Grid Modernization Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,574.14 million → 2032: USD 5,728.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 France Grid Modernization Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Utilities
- 12.3.7.2 Independent Power Producers (IPPs)
- 12.3.7.3 Government and Municipalities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial
- 12.5.7.3 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 France Grid Modernization End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 France Grid Modernization Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 France Grid Modernization Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 France Grid Modernization Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens AG
- 18.4 Schneider Electric SE
- 18.5 Hitachi Energy
- 18.6 General Electric France
- 18.7 Alstom SA
- 18.8 Toshiba France
- 18.9 Landis+Gyr AG
- 18.10 Siemens Gamesa
- 18.11 Eaton France
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

