
Market Overview
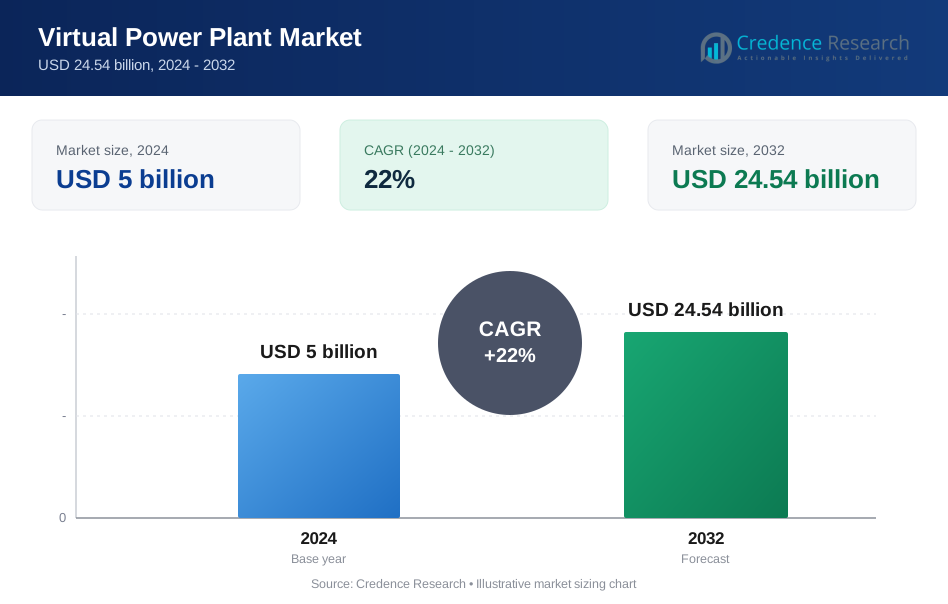
The Virtual Power Plant Market was valued at USD 5 billion in 2024 and is projected to reach USD 24.54 billion by 2032, growing at a CAGR of 22% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Virtual Power Plant Market Size 2024 | USD 5 Billion |
| Virtual Power Plant Market, CAGR | 22% |
| Virtual Power Plant Market Size 2032 | USD 24.54 Billion |
The Virtual Power Plant Market grows through rising adoption of renewable energy sources, smart grid integration, and energy storage solutions. It benefits from increasing electricity demand, need for grid stability, and efficient energy management. Technological innovations in AI, IoT, and real-time monitoring enhance operational efficiency.
North America leads the Virtual Power Plant Market with strong adoption driven by advanced grid infrastructure and supportive policies. Utilities and technology providers implement VPPs to manage distributed energy resources efficiently and improve grid resilience. Europe shows significant growth due to government incentives for renewable energy integration and decarbonization initiatives. Countries such as Germany, the UK, and France invest heavily in smart grids and energy storage projects to optimize electricity generation. Asia-Pacific records rapid expansion driven by urbanization, rising electricity demand, and renewable energy targets in China, Japan, and India. The Middle East and Africa adopt VPPs in pilot projects for microgrid and off-grid applications, while Latin America explores solar and wind-based VPP deployments. Key players shaping the market include NextEra Energy, Engie, General Electric, and Schneider Electric, which focus on technological innovations, partnerships, and project expansions to enhance distributed energy management and support grid stability globally.
Market Insights
- The Virtual Power Plant Market size was valued at USD 5 billion in 2024 and is anticipated to reach USD 24.54 billion by 2032, at a CAGR of 22%.
- Rising adoption of renewable energy sources and energy storage solutions drives market growth.
- Increasing digitalization and IoT integration enable efficient management of distributed energy resources.
- Key players such as NextEra Energy, Engie, General Electric, and Schneider Electric focus on technological innovations, strategic partnerships, and global project expansions.
- High initial investment, complex grid integration, and regulatory uncertainties pose challenges for widespread VPP deployment.
- North America leads adoption due to advanced infrastructure, while Europe and Asia-Pacific show strong growth through government incentives and renewable energy targets.
- Emerging markets in Latin America, the Middle East, and Africa create opportunities for microgrid and off-grid VPP applications.
Market Drivers
Rising Integration of Renewable Energy Sources and Distributed Generation
The Virtual Power Plant Market grows through the increasing adoption of renewable energy sources such as solar, wind, and biomass. It enables aggregation of decentralized energy assets to balance supply and demand efficiently. Utilities leverage virtual power plants to integrate intermittent energy sources without destabilizing the grid. The system supports real-time monitoring and predictive load management. It reduces reliance on conventional power plants and lowers operational costs. Growing investments in renewable energy infrastructure further strengthen its adoption. For instance, Enbala Power Networks deployed over 1,500 distributed energy resources across North America to stabilize grid fluctuations.
- For instance, Enbala Power Networks deployed over 1,500 distributed energy resources across North America to stabilize grid fluctuations and manage localized energy supply challenges.
Advancements in Energy Storage and Smart Grid Technologies
Energy storage solutions, including lithium-ion and flow batteries, enhance the capabilities of virtual power plants. It allows peak load management and ensures continuous energy supply during high demand periods. Smart grid technologies improve communication between distributed assets and central control units. Utilities use AI-based algorithms to optimize energy dispatch and reduce system losses. It also enables participation in demand response programs to earn additional revenue. For instance, Siemens Smart Energy integrated AI-driven storage management for over 200 MW of distributed assets in Germany.
- For instance, Siemens Smart Energy integrated an AI-driven storage management system that controls over 200 MW of distributed assets across Germany to streamline energy dispatch and improve forecasting accuracy.
Government Initiatives and Supportive Policies for Clean Energy
Governments promote virtual power plant deployment through incentives, subsidies, and regulatory frameworks. It aligns with renewable portfolio standards and decarbonization targets. Policy support encourages private investments in digital energy platforms and energy storage. It also accelerates adoption in regions with ambitious emission reduction goals. Local authorities prioritize grid flexibility to accommodate distributed energy resources efficiently. For instance, the UK National Grid collaborated with Kiwi Power to manage 500 MW of flexible energy capacity.
Demand for Grid Reliability and Operational Efficiency
Utilities face pressure to maintain grid stability amid rising electricity consumption and renewable penetration. Virtual power plants enhance operational efficiency by coordinating multiple energy sources and storage systems. It provides real-time visibility into energy generation and consumption patterns. Predictive analytics prevent outages and reduce maintenance costs. It also supports cost-effective integration of electric vehicles and microgrids. For instance, Next Kraftwerke operates over 10,000 energy units in Europe, delivering optimized power supply to commercial and industrial clients.

Market Trends
Growing Adoption of Artificial Intelligence and Machine Learning in Energy Management
The Virtual Power Plant Market experiences increasing integration of AI and machine learning for predictive analytics and optimization. It enables real-time forecasting of energy demand and generation patterns across distributed resources. Operators can adjust output dynamically to prevent imbalances and reduce grid stress. AI-driven platforms improve efficiency by coordinating storage, renewable, and conventional energy assets. It also supports predictive maintenance and minimizes operational downtime. For instance, AutoGrid deployed AI-based demand response software to manage over 3,000 distributed energy units in North America.
- For instance, AutoGrid deploys AI-based demand response software for utilities across North America to manage distributed energy units, enabling automated dispatch and real-time grid responsiveness.
Expansion of Microgrid and Decentralized Energy Networks
Virtual power plants gain traction through the growth of microgrids and decentralized energy systems. It allows utilities to control multiple energy sources locally while maintaining grid stability. Microgrids provide resilience during outages and support energy independence for industrial and commercial facilities. Virtual power plants coordinate these networks to optimize load distribution and minimize energy wastage. It enhances flexibility for integrating solar, wind, and storage assets. For instance, Engie’s VPP platform manages over 500 MW of distributed energy across European microgrids.
- For instance, The Swell Energy virtual power plant (VPP) contract with Hawaiian Electric aggregates over 25 MW of solar power and more than 80 MW of residential battery storage across Hawaii. It provides peak shaving and frequency regulation services to support grid reliability. In August 2024, the VPP program was paused after Swell Energy halted operations.
Integration with Electric Vehicle Charging Infrastructure
The rise of electric vehicles drives new applications for virtual power plants in managing charging loads. It enables optimized energy dispatch and peak shaving during high-demand periods. EV integration supports bidirectional energy flow, allowing vehicles to act as temporary storage. Utilities leverage virtual power plants to balance grid stress caused by large-scale EV adoption. It promotes cost-effective utilization of renewable energy during off-peak hours. For instance, Next Kraftwerke connects EV charging stations across Germany to its VPP network to stabilize local grids.
Increasing Focus on Grid Flexibility and Demand Response Programs
Virtual power plants support flexible energy management by participating in demand response initiatives. It allows consumers and businesses to adjust energy usage based on grid requirements. Advanced VPP platforms provide incentives for reducing load during peak demand periods. It enhances overall grid reliability while lowering operational costs for utilities. Real-time data analytics optimize energy dispatch and improve forecasting accuracy. For instance, Enbala Power Networks operates over 1,500 distributed resources in the US to provide automated demand response services.
Market Challenges Analysis
Complex Integration of Distributed Energy Resources and Legacy Grid Systems
The Virtual Power Plant Market faces challenges in integrating diverse distributed energy resources with existing grid infrastructure. It requires advanced communication protocols and real-time monitoring systems to synchronize multiple generation sources. Utilities encounter difficulties in managing variable outputs from solar, wind, and storage units alongside conventional power plants. It demands high investment in software platforms and hardware upgrades to ensure seamless operation. Data interoperability and cybersecurity risks add further complexity. For instance, Siemens faced challenges in coordinating over 2,000 heterogeneous assets in its European VPP deployments.
Regulatory Barriers and Limited Standardization Across Regions
Virtual power plants encounter regulatory constraints that hinder large-scale adoption. It must comply with different energy policies, grid codes, and market regulations across countries. Limited standardization in interconnection requirements and market participation rules delays project implementation. It also affects revenue streams for operators and complicates cross-border energy trading. Stakeholders need consistent guidelines to ensure predictable returns and safe integration. For instance, Next Kraftwerke experienced delays in expanding its VPP operations in multiple EU countries due to varying local energy regulations.
Market Opportunities
Expansion of Renewable Energy Integration and Grid Flexibility Solutions
The Virtual Power Plant Market benefits from the rising integration of renewable energy sources into power grids. It allows operators to aggregate distributed solar, wind, and storage assets to provide reliable electricity supply. Utilities can optimize grid performance by balancing supply and demand in real time. It supports peak load management and reduces dependency on fossil-fuel-based power generation. Energy companies invest in software platforms that enhance predictive analytics and automated dispatch. For instance, Enbala Power Networks manages over 500 MW of distributed energy resources through its cloud-based VPP solutions, improving grid flexibility and stability.
Emergence of Energy Trading and Demand Response Services
Virtual power plants create opportunities in energy trading and demand response programs. It enables operators to participate in wholesale markets and sell aggregated capacity to utilities or grid operators. Industrial and commercial consumers benefit from cost savings by adjusting consumption during peak hours. It drives investments in smart meters, IoT sensors, and AI-driven control systems. For instance, Next Kraftwerke leverages its VPP platform to trade 1,200 MW of flexible capacity across European energy markets. These capabilities strengthen the market potential for VPPs while supporting decentralized energy management.
Market Segmentation Analysis:
By Technology
The Virtual Power Plant Market segments by technology into software platforms, communication infrastructure, and energy management systems. Software platforms enable real-time monitoring, predictive analytics, and automated dispatch of distributed energy resources. Communication infrastructure ensures seamless data exchange between generation assets, storage units, and grid operators. Energy management systems optimize energy flow, enhance grid stability, and reduce operational costs. It supports integration of diverse renewable sources, allowing utilities to maximize efficiency and reliability. For instance, Siemens’ Spectrum Power platform manages multiple DERs and storage units, delivering precise load balancing across complex grids.
- For instance, Siemens' grid software, now part of Siemens Energy, does manage a large number of decentralized energy assets, including solar, wind, and battery storage systems, across multiple European projects. These platforms provide real-time dispatch and load balancing, as seen in projects with Finnish Railways and RWE.
By Type
By type, the market includes centralized VPPs and decentralized VPPs. Centralized VPPs consolidate energy resources under a single control center for coordinated operation. Decentralized VPPs distribute control across multiple nodes, offering flexibility in regional grid management. It allows operators to adjust output based on localized demand and renewable generation variability. Centralized solutions provide consistent output for large-scale industrial grids, while decentralized setups support residential and community-based energy networks. For instance, Next Kraftwerke operates a decentralized VPP managing over 1,200 MW of renewable capacity across Europe, optimizing dispatch efficiency and market participation.
- For instance, Next Kraftwerke’s decentralized virtual power plant controls more than 10,000 generating units and aggregates over 10,000 MW of capacity across Europe, actively participating in day-ahead and intraday electricity markets.
By End Use
End-use segmentation covers residential, commercial, and industrial sectors. Residential applications focus on integrating rooftop solar panels, home batteries, and smart appliances into VPP networks. Commercial users leverage VPPs to reduce energy costs, participate in demand response, and manage building energy consumption. Industrial consumers rely on VPPs for high-capacity load balancing, uninterrupted operations, and peak shaving. It enhances energy flexibility across sectors while enabling revenue generation through grid services. For instance, Enbala Power Networks collaborates with industrial clients to control distributed storage and load, providing over 500 MW of flexible energy to the North American grid.
Segments:
Based on Technology
- Demand Response
- Distributed Generation
- Energy Storage
- Renewable Energy Integration
Based on Type
- Hybrid Virtual Power Plant
- Conventional Virtual Power Plant
- Software-Defined Virtual Power Plant
Based on End Use
- Residential
- Commercial
- Industrial
Based on Control Mechanism
- Centralized Control
- Decentralized Control
- Cloud-Based Control
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds 32% market share in the Virtual Power Plant Market, driven by robust renewable integration and supportive regulations. The region leads in smart grid adoption, enabling utilities to deploy advanced VPP solutions for demand response and peak load management. It sees widespread use of distributed energy resources, including rooftop solar, wind farms, and battery storage systems. Utilities invest in software platforms that optimize grid performance and reduce operational costs. For instance, Enbala Power Networks manages over 500 MW of flexible energy from distributed sources in the U.S. It strengthens grid resilience while supporting commercial and industrial customers with energy optimization services. Government incentives and grid modernization programs further accelerate market growth.
Europe
Europe accounts for 28% market share, reflecting high renewable penetration and regulatory mandates for carbon neutrality. Countries such as Germany, the UK, and France invest in VPPs to integrate solar, wind, and hydro assets efficiently. It enables operators to participate in energy trading and balance fluctuations from intermittent renewable generation. For instance, Next Kraftwerke operates a decentralized VPP controlling over 1,200 MW of renewable capacity across Germany and neighboring countries. Grid modernization initiatives, energy storage deployment, and demand-side management programs boost adoption. The region focuses on achieving energy flexibility, reducing costs, and improving grid stability through advanced VPP solutions.
Asia-Pacific
Asia-Pacific holds 25% market share, driven by rapid urbanization, rising electricity demand, and government support for renewable energy. China, Japan, and India actively implement VPPs to manage distributed solar, wind, and battery storage systems. It helps balance local grids and optimize energy costs for residential, commercial, and industrial users. For instance, Sungrow Power Supply in China integrates large-scale solar farms into VPPs, managing over 600 MW of renewable energy. Expansion of smart cities and investments in digital energy platforms fuel growth. Increasing adoption of IoT-enabled energy management and smart meters supports efficient operation of VPP networks.
Latin America
Latin America represents 10% market share, supported by rising renewable energy projects and growing interest in grid modernization. Brazil and Chile lead regional adoption through solar and wind integration in urban and rural areas. It allows utilities to stabilize supply and enhance grid reliability while leveraging decentralized energy resources. For instance, Enel Green Power operates VPP projects in Brazil, integrating over 250 MW of distributed solar and hydro capacity. Government incentives and cross-border energy trading initiatives further promote deployment. Rising industrial demand and increasing investment in digital energy solutions also drive market growth.
Middle East & Africa
Middle East & Africa captures 5% market share, driven by pilot projects in solar-rich regions and growing energy infrastructure modernization. UAE, Saudi Arabia, and South Africa implement VPPs to manage renewable energy and enhance grid flexibility. It supports industrial and residential users in regions with variable generation and peak demand challenges. For instance, Siemens has deployed VPP solutions integrating over 100 MW of solar and battery storage across South Africa. Investment in smart grids and renewable integration projects fuels adoption, while government strategies emphasize energy efficiency and sustainable power generation.
Key Player Analysis
- Vattenfall
- Tesla
- RWE
- General Electric
- Engie
- NextEra Energy
- Orsted
- Aquila Capital
- EDF
- Schneider Electric
Competitive Analysis
Competitive Landscape, Key players in the Virtual Power Plant Market include NextEra Energy, Engie, Aquila Capital, General Electric, EDF, Vattenfall, Orsted, RWE, Schneider Electric, and Tesla. These companies focus on developing advanced energy management platforms, integrating distributed energy resources, and deploying large-scale VPP projects across multiple regions. They leverage extensive renewable portfolios, energy storage solutions, and digital platforms to optimize grid flexibility and enable real-time monitoring. Investments in software-driven energy orchestration systems improve operational efficiency and reduce downtime. Strategic initiatives include smart grid integration, energy automation technologies, vehicle-to-grid systems, and predictive analytics. Focus on sustainable energy sourcing, cross-border project execution, and regulatory compliance strengthens market positioning. Their emphasis on digitalization, renewable integration, and scalable energy solutions drives technological innovation, captures emerging opportunities, and enhances influence in the rapidly evolving Virtual Power Plant Market.
Recent Developments
- In July 2025, Tesla commissioned a 100 MW virtual power plant in South Australia, connecting residential Powerwalls to stabilize grid suppTesla was involved with the SAVPP, AGL Energy acquired the SAVPP, a network of residential Tesla Powerwalls.
- In November 2023, Engie expanded its French VPP portfolio by 60 MW, integrating industrial batteries and demand response solutions.
- In September 2023, General Electric introduced a cloud-based VPP software platform for energy providers, enabling real-time asset coordination and predictive analytics.
- In January 2023, Vattenfall launched a 50 MW virtual power plant in Sweden, integrating solar and battery assets to optimize grid flexibility.
Report Coverage
The research report offers an in-depth analysis based on Technology, Type, End Use, Control Mechanism and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Virtual Power Plant Market will expand through increased renewable energy integration.
- Growth will be driven by rising demand for grid flexibility and stability.
- Advanced AI and machine learning will enhance real-time energy management.
- Adoption of battery storage and distributed energy resources will accelerate VPP deployment.
- Industrial, commercial, and residential sectors will increasingly participate in demand-side management.
- Government policies and incentives will support VPP expansion globally.
- Digital platforms will enable efficient coordination of decentralized energy assets.
- Strategic partnerships between utilities and technology providers will strengthen market presence.
- Focus on reducing carbon emissions will promote sustainable VPP solutions.
- Continuous innovation in software and hardware will create new opportunities for market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Virtual Power Plant, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Virtual Power Plant market projected to grow between 2025 and 2032?
Which Virtual Power Plant market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Virtual Power Plant market?
Who are the leading companies in the Virtual Power Plant market?
Which region commanded the largest share of the Virtual Power Plant market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Virtual Power Plant Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Virtual Power Plant Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5 billion → 2032: USD 24.54 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Virtual Power Plant Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Virtual Power Plant Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Virtual Power Plant Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Virtual Power Plant Market Drivers
- 3.3 Virtual Power Plant Market Restraints & Challenges
- 3.4 Virtual Power Plant Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Virtual Power Plant Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Virtual Power Plant Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Virtual Power Plant category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Virtual Power Plant Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Virtual Power Plant Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Virtual Power Plant market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Virtual Power Plant Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Virtual Power Plant Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Virtual Power Plant Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Virtual Power Plant (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Virtual Power Plant Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Virtual Power Plant Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Virtual Power Plant Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Virtual Power Plant Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Virtual Power Plant Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Virtual Power Plant Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Virtual Power Plant Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Virtual Power Plant Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Virtual Power Plant Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
