
Market Overview
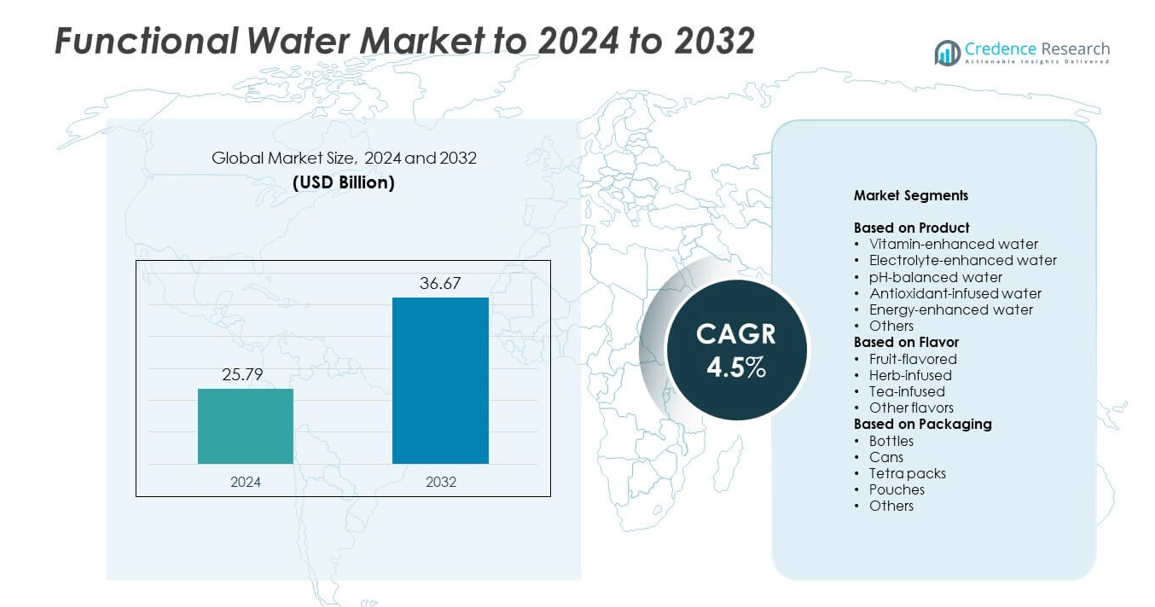
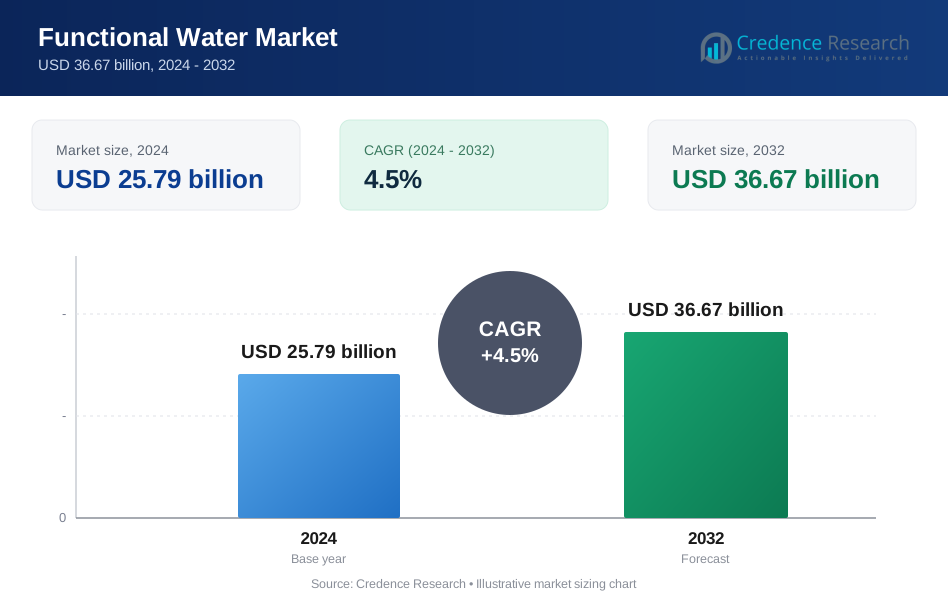
The Functional Water Market size was valued at USD 25.79 billion in 2024 and is anticipated to reach USD 36.67 billion by 2032, at a CAGR of 4.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Functional Water Market Size 2024 | USD 25.79 billion |
| Functional Water Market, CAGR | 4.5% |
| Functional Water Market Size 2032 | USD 36.67 billion |
The functional water market is shaped by leading players such as PepsiCo Inc, Nestlé Water, The Coca-Cola Company, Danone S.A, and Essentia Water LLC. These companies focus on expanding portfolios through vitamin-infused, electrolyte-balanced, and low-calorie products catering to wellness-driven consumers. Strategic investments in sustainable packaging, marketing partnerships, and retail distribution strengthen their global reach. North America emerged as the dominant region in 2024, accounting for 37% of the total market share, supported by high health awareness and strong product availability. Continuous innovation and regional expansion efforts position these players for sustained growth through 2032.
Market Insights
- The Functional Water Market was valued at USD 25.79 billion in 2024 and is expected to reach USD 36.67 billion by 2032, growing at a CAGR of 4.5%.
- Rising health consciousness and demand for nutrient-enriched beverages are driving growth, supported by innovations in clean-label and natural ingredient formulations.
- Emerging trends include the adoption of eco-friendly packaging, product diversification with botanical and probiotic infusions, and expanding e-commerce sales channels.
- The market remains moderately consolidated, with global brands focusing on innovation, sustainability, and strategic partnerships to enhance competitiveness.
- North America led with a 37% share, followed by Europe at 29% and Asia Pacific at 24%, while the vitamin-enhanced water segment dominated overall with a 41% share in 2024.
Market Segmentation Analysis:
By Product
The vitamin-enhanced water segment dominated the functional water market in 2024 with a 41% share. This segment leads due to rising consumer preference for convenient, nutrient-rich hydration options that support immunity and metabolism. The inclusion of vitamins B, C, and D has increased its popularity among fitness and health-conscious consumers. Leading brands are expanding product lines with natural ingredients and low-calorie formulations to meet clean-label demands. The strong appeal among millennials and athletes continues to strengthen the segment’s market dominance across developed and emerging economies.
- For instance, a single 20 fl oz bottle of Coca-Cola's Glacéau Vitaminwater Essential Orange provides 100 calories and contains 27 grams of added sugars.
By Flavor
Fruit-flavored functional water held the largest market share of 46% in 2024. The dominance is driven by high consumer acceptance of natural fruit-based tastes such as lemon, berry, and orange. These variants offer refreshing flavors while delivering added nutrients, aligning with the shift toward sugar-free, low-calorie beverages. Manufacturers are launching innovative combinations and seasonal variants to attract wider audiences. The popularity of fruit-flavored drinks in retail and fitness centers supports steady sales across major markets including North America and Europe.
- For instance, Bai Kula Watermelon shows 10 calories and 1 g sugar per bottle, aligning with low-sugar fruit flavors.
By Packaging
The bottles segment accounted for a 55% share of the functional water market in 2024. Bottles remain the preferred packaging format due to their convenience, portability, and compatibility with mass distribution channels. PET and recycled plastic bottles are widely used for their cost efficiency and durability. Leading companies are adopting lightweight and eco-friendly bottle designs to reduce carbon footprints. Increasing availability in retail stores, gyms, and vending machines continues to make bottles the dominant packaging choice for functional water globally.
Key Growth Drivers
Rising Health and Wellness Awareness
Growing consumer focus on health and wellness is a major growth driver for the functional water market. Consumers are shifting away from sugary carbonated drinks toward healthier hydration alternatives with added vitamins, minerals, and electrolytes. Increasing awareness of preventive healthcare and active lifestyles has boosted demand for nutrient-infused beverages. Functional water fits well within the trend of clean-label, low-calorie, and natural products, making it a preferred choice among fitness enthusiasts and urban consumers seeking convenient health benefits through everyday hydration.
- For instance, Karma Probiotic Water delivers 2 billion CFU, 100% of six vitamins, and 20 calories per bottle.
Expansion of Fitness and Sports Nutrition Sector
The rapid expansion of gyms, fitness clubs, and sporting events worldwide is fueling higher consumption of functional water. Athletes and fitness-conscious individuals prefer hydration products that help maintain energy balance and electrolyte levels. The segment benefits from partnerships between beverage brands and sports organizations, promoting product visibility. Enhanced formulations offering endurance and recovery support have further increased adoption rates. The rising culture of active living across both developed and emerging markets continues to drive steady functional water sales.
- For instance, Nestlé Pure Life launched a 700 ml bottle made with 100% recycled PET in North America.
Innovation in Product Formulation and Packaging
Ongoing innovation in flavor development, bioactive ingredients, and sustainable packaging is a crucial growth driver. Companies are introducing formulations infused with antioxidants, probiotics, and adaptogens to target specific health needs. Advances in biodegradable and recyclable packaging materials also appeal to eco-conscious consumers. Digital marketing campaigns emphasizing product transparency and clean nutrition further strengthen brand engagement. Such innovations enable differentiation in a competitive beverage landscape and attract a broader consumer base seeking functional benefits beyond hydration.
Key Trends and Opportunities
Shift Toward Natural and Clean-Label Ingredients
Consumers increasingly prefer functional waters made from natural extracts and plant-based additives over synthetic compounds. This shift presents an opportunity for manufacturers to leverage organic certifications and transparent labeling. Brands incorporating natural antioxidants, fruit essences, and botanical infusions are experiencing stronger brand loyalty. Clean-label positioning, combined with minimal sugar and preservative-free claims, supports premiumization. This trend also aligns with broader global movements toward sustainable and health-focused consumer choices, offering significant market expansion potential.
- For instance, Hint Water lists zero sugar, zero calories, and zero diet sweeteners per 16 fl oz bottle on its product pages.
Growth of E-commerce and Direct-to-Consumer Sales
Rising digitalization is opening new growth opportunities for functional water brands. E-commerce and direct-to-consumer (D2C) platforms allow brands to engage with customers directly and promote product customization. Subscription-based models and online wellness campaigns enhance repeat purchases. Social media marketing plays a key role in educating consumers about product benefits and functional ingredients. With digital convenience and targeted advertising, online channels are becoming a dominant sales driver, particularly among tech-savvy and younger demographics seeking innovative hydration options.
- For instance, Waterdrop reports 40+ stores and ~40% average year-over-year growth, reflecting strong digital and retail expansion.
Key Challenges
High Production and Distribution Costs
The functional water market faces challenges from high costs associated with ingredient fortification, quality testing, and premium packaging. Maintaining the stability of vitamins and minerals during processing increases manufacturing complexity. Additionally, cold-chain logistics and advanced packaging requirements raise transportation and storage expenses. These factors limit competitive pricing against regular bottled water. Smaller manufacturers face profitability constraints, especially in emerging markets where price sensitivity remains high, restricting wider adoption and scalability across diverse retail channels.
Regulatory and Labeling Compliance Issues
Compliance with regional food safety and labeling regulations poses significant challenges for functional water producers. Authorities closely monitor claims related to nutritional benefits, leading to frequent formulation revisions and certification costs. Mislabeling or exaggerated health claims can attract legal scrutiny, damaging brand credibility. Variations in standards across countries complicate product launches in international markets. To overcome this, manufacturers must invest in regulatory expertise and transparent communication to maintain consumer trust and ensure long-term market sustainability.
Regional Analysis
North America
North America held a 37% share of the functional water market in 2024, driven by strong consumer awareness of fitness and hydration benefits. The United States dominates due to rising demand for nutrient-rich and low-calorie beverages among health-conscious populations. Major brands focus on vitamin-enhanced and electrolyte-infused products supported by widespread retail availability. The region’s developed infrastructure and strong marketing by beverage giants such as PepsiCo and Nestlé support continued growth. Increasing interest in clean-label and organic formulations further boosts premium product adoption across the United States and Canada.
Europe
Europe accounted for a 29% share of the global functional water market in 2024, supported by the rising popularity of natural and fortified beverages. Demand is growing across Germany, the United Kingdom, and France as consumers prioritize healthier hydration choices over soft drinks. Stringent regulations on sugar content and synthetic additives are encouraging innovation in natural formulations. Companies are introducing plant-based and pH-balanced options to meet wellness trends. Expanding distribution through supermarkets and fitness centers continues to drive consistent growth in the region’s premium hydration category.
Asia Pacific
Asia Pacific captured a 24% share of the functional water market in 2024, fueled by rising disposable incomes and rapid urbanization. Consumers in China, Japan, and India are increasingly adopting functional beverages for hydration and wellness. Growing gym memberships and awareness of active lifestyles are accelerating product penetration. Regional players and global brands are expanding through convenience stores and online platforms. Innovation in local flavors such as green tea and tropical fruits enhances appeal. Government initiatives promoting health and nutrition further support steady market expansion across the region.
Latin America
Latin America held a 6% share of the global functional water market in 2024, driven by increasing urban health awareness and demand for convenient wellness beverages. Brazil and Mexico lead consumption due to growing fitness participation and changing dietary habits. Local producers are introducing affordable fortified water options to capture middle-income consumers. Rising retail investments and promotional campaigns by multinational brands strengthen market visibility. The region’s young population and growing inclination toward sugar-free drinks are expected to sustain gradual market growth over the forecast period.
Middle East and Africa
The Middle East and Africa accounted for a 4% share of the functional water market in 2024, supported by expanding retail networks and rising interest in hydration products. Increasing health awareness in Gulf countries like the UAE and Saudi Arabia is driving adoption of premium bottled and electrolyte-enhanced water. Hot climatic conditions also contribute to higher per capita water consumption. Global beverage companies are investing in local production facilities to reduce import dependency. Marketing emphasizing fitness and wellness benefits continues to create new growth opportunities across urban centers.
Market Segmentations:
By Product
- Vitamin-enhanced water
- Electrolyte-enhanced water
- pH-balanced water
- Antioxidant-infused water
- Energy-enhanced water
- Others
By Flavor
- Fruit-flavored
- Herb-infused
- Tea-infused
- Other flavors
By Packaging
- Bottles
- Cans
- Tetra packs
- Pouches
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Major players such as PepsiCo Inc, Nestlé Water, The Coca-Cola Company, Danone S.A, Essentia Water LLC, Bodyarmor, Bai Brands LLC, Neuro Brands LLC, Kyowa Hakko USA, Karma Culture LLC, and Waterdrop Inc collectively define the competitive landscape of the functional water market. The market remains moderately consolidated, with global brands focusing on innovation, ingredient enhancement, and sustainable packaging to strengthen their portfolios. Companies are investing in vitamin-enriched and electrolyte-balanced formulations to meet growing consumer demand for health-oriented hydration. Expanding digital marketing strategies, fitness partnerships, and retail distribution networks support brand visibility. Continuous R&D efforts target the development of clean-label, low-calorie, and plant-based options. Sustainability and recyclable materials have become key differentiators, while mergers and acquisitions help leading firms expand into emerging markets. Strategic product diversification, backed by strong promotional campaigns, enables these players to maintain leadership positions and attract a broad health-conscious customer base globally.
Key Player Analysis
- PepsiCo Inc
- Nestlé Water
- The Coca-Cola Company
- Danone S.A
- Essentia Water LLC
- Bodyarmor (The Coca-Cola Company)
- Bai Brands LLC
- Neuro Brands LLC
- Kyowa Hakko USA
- Karma Culture LLC
- Waterdrop Inc.
Recent Developments
- In 2024, Essentia launched its new flavored functional water line, Essentia Hydroboost.
- In 2024, Waterdrop Inc. Launched its groundbreaking X Series Reverse Osmosis system. This product features biodegradable packaging and innovative technology that simulates natural mineral water formation.
- In 2023, Kyowa Hakko USA and sparkling beverage company Centr debuted Centr Enhanced, a sparkling water that features a blend of nootropic and adaptogenic ingredients.
- In 2023, Bodyarmor (The Coca-Cola Company) launched BODYARMOR FLASH I.V., a rapid rehydration drink formulated with an optimal carb-to-electrolyte ratio
Report Coverage
The research report offers an in-depth analysis based on Product, Flavor, Packaging and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing consumer focus on preventive health will continue to boost functional water adoption.
- Innovation in nutrient blends and natural ingredients will enhance product differentiation.
- Expansion of fitness and sports nutrition markets will drive consistent consumption growth.
- Increasing preference for clean-label and low-calorie beverages will shape future product portfolios.
- Technological advancements in sustainable packaging will improve environmental performance.
- Rising e-commerce penetration will strengthen direct-to-consumer sales channels.
- Strategic partnerships between beverage brands and wellness companies will expand market reach.
- Emerging economies in Asia and Latin America will offer new growth opportunities.
- Product diversification with botanical and probiotic infusions will attract niche consumers.
- Ongoing regulatory alignment and labeling transparency will build stronger consumer trust globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Functional Water Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Functional Water Market projected to grow between 2025 and 2032?
Which Functional Water Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Functional Water Market?
Who are the leading companies in the Functional Water Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Functional Water Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Functional Water Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 25.79 billion → 2032: USD 36.67 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Functional Water Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Functional Water Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Functional Water Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Functional Water Market Drivers
- 3.3 Functional Water Market Restraints & Challenges
- 3.4 Functional Water Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Functional Water Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Functional Water Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Functional Water category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Functional Water Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Functional Water Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Functional Water market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Functional Water Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Functional Water Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Functional Water Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Functional Water (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Functional Water Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Functional Water Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Functional Water Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Functional Water Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Functional Water Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Functional Water Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Functional Water Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Functional Water Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Functional Water Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
