
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Head and Neck Cancer Market Size 2024 | USD 2398.95 Million |
| Head and Neck Cancer Market, CAGR | 6.62% |
| Head and Neck Cancer Market Size 2032 | USD 4006.18 Million |
Market Overview
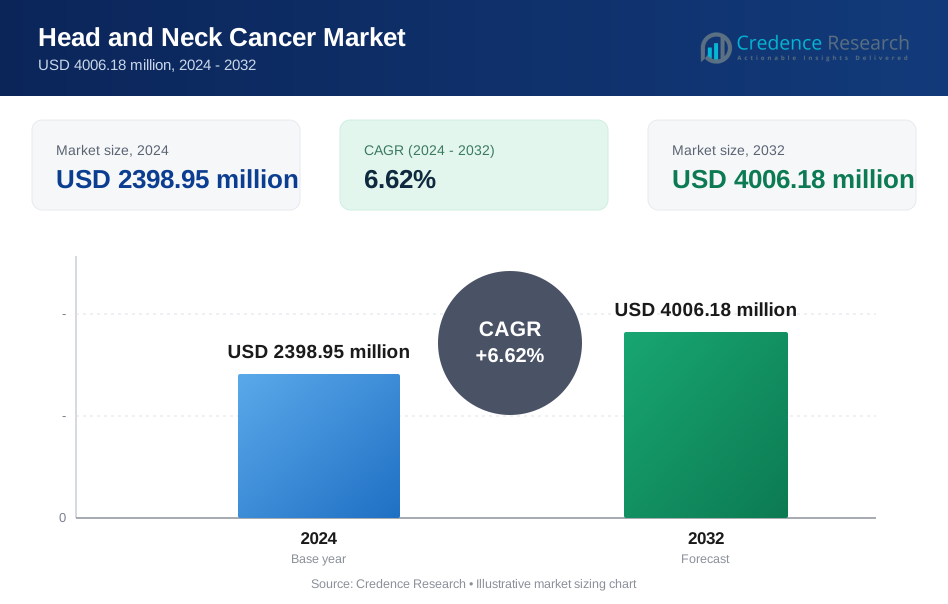
The Head and Neck Cancer Market is projected to witness substantial growth from USD 2398.95 million in 2024 to USD 4006.18 million by 2032, reflecting a compound annual growth rate of 6.62%.
The Head and Neck Cancer Market is driven by several key factors and trends. Increasing incidence rates of head and neck cancers, fueled by factors such as tobacco and alcohol consumption, are propelling market growth. Moreover, advancements in diagnostic techniques and treatment modalities, including targeted therapies and immunotherapies, are significantly influencing market dynamics. Additionally, rising awareness campaigns and government initiatives for early detection and treatment are further contributing to market expansion. Furthermore, ongoing research and development efforts aimed at identifying novel biomarkers and therapeutic targets are anticipated to continue shaping the landscape of the Head and Neck Cancer Market.
Geographical analysis reveals distinct market trends in regions such as North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa. North America holds a significant share owing to advanced healthcare infrastructure, high prevalence rates, and robust research activities. Europe follows suit due to increasing investments in cancer research and favorable reimbursement policies. The Asia-Pacific region exhibits promising growth potential driven by rising healthcare expenditure and a growing patient population. Key players in the Head and Neck Cancer Market include pharmaceutical companies such as Bristol-Myers Squibb, Merck & Co., Inc., AstraZeneca, and Novartis AG, alongside medical device manufacturers like Elekta AB and Varian Medical Systems, Inc.
Market Drivers
Rising Prevalence:
Head and Neck Squamous Cell Carcinoma (HNSCC) emerges as the most prevalent subtype, witnessing a concerning uptrend in global incidence. For instance, HNSCC is the sixth most common malignancy in humans worldwide, with 930,000 newly diagnosed cases and 467,000 deaths in 2020. This surge is attributed to multifaceted factors including but not limited to tobacco consumption, excessive alcohol intake, and Human Papillomavirus (HPV) infection. For example, in the developing world, the incidence of HNSCC is growing with increasing consumption of tobacco (smoked or chewed), alcohol, and areca nut (betel quid). Alcohol and tobacco have a synergistic effect, with the heavy consumption of both increasing HNSCC risk 40-fold. Such epidemiological shifts underscore the imperative for heightened awareness, comprehensive preventive measures, and effective therapeutic interventions to curb the burgeoning burden of head and neck cancers on a global scale. Preventive measures include lifestyle modifications, early detection methods, and vaccination against high-risk viral infections. Therapeutic interventions for HNSCC include surgery, radiation therapy, targeted therapy [epidermal growth factor receptor (EGFR)-targeting monoclonal antibody cetuximab], and chemotherapy with cytotoxic agents (such as cisplatin, methotrexate, gemcitabine, and bleomycin).
Growing Geriatric Population:
The demographic landscape is indeed undergoing a significant transition. As the global population ages, we observe a remarkable increase in the geriatric segment. For instance, by the year 2050, it is projected that one in six people will be aged 65 or older. This demographic shift brings with it unique challenges, particularly in the realm of cancer management. Head and neck cancers, which encompass malignancies affecting the oral cavity, throat, and related structures, are becoming more prevalent among the elderly. The aging process itself contributes to the heightened susceptibility to these cancers. For instance, over 90% of head and neck cancers occur in individuals aged 50 and above. Thus, there arises an urgent need for innovative strategies that address the distinct needs of elderly patients afflicted with head and neck malignancies.
Advancements in Diagnosis and Treatment:
Pioneering advancements in diagnostic modalities are revolutionizing the landscape of head and neck cancer diagnosis. For instance, high-resolution imaging techniques, minimally invasive biopsies, and biomarker testing are instrumental in facilitating early and accurate detection. These advancements are particularly significant considering that head and neck cancer accounts for about 4% of all cancers in the United States, with an estimated 66,920 people diagnosed in 2023. Worldwide, an estimated 562,328 people were diagnosed with head and neck cancer in 2020. Concurrently, therapeutic strategies are evolving in tandem with technological innovations. Precise radiation therapy, targeted drug therapies, and minimally invasive surgical procedures are reshaping treatment paradigms. These advancements promise improved survival rates and enhanced quality of life for patients battling head and neck cancers. This is crucial as head and neck cancer is the 8th most common cancer in the UK, accounting for 3% of all new cancer cases. In the UK alone, there are around 12,400 new head and neck cancer cases every year.
Integration of Immunotherapy and Personalized Medicine:
Immunotherapy stands at the forefront of transformative cancer treatment, leveraging the body's immune system to combat malignant cells. In the realm of head and neck cancers, immunotherapeutic agents demonstrate considerable efficacy, offering renewed hope for patients with advanced disease stages. Moreover, the burgeoning emphasis on personalized medicine heralds a paradigm shift in cancer care. Tailored treatment regimens, informed by individual patient characteristics and genetic profiles, optimize therapeutic outcomes while minimizing treatment-related adverse effects. Such personalized approaches epitomize the pinnacle of precision oncology, paving the way for customized interventions that resonate with the unique needs of each patient.
Market Trends
Innovative Diagnostic Approaches:
As traditional biopsies pose invasive challenges, the ascendancy of liquid biopsies emerges as a transformative trend in head and neck cancer diagnostics. For instance, liquid biopsies, which involve analyzing tumor-derived materials circulating in bodily fluids, have shown immense potential in improving treatment for head and neck cancers. This minimally invasive approach holds promise for early detection and monitoring treatment responses. In fact, head and neck cancers are the seventh most frequent malignancy worldwide, consisting of a heterogeneous group of cancers that develop in the oral cavity, pharynx, and larynx. Due to limitations with screening and physical examination, these cancers often present in advanced disease states, thus making early detection through methods like liquid biopsies crucial. Moreover, liquid biopsies offer a pathway to personalized treatment plans, potentially revolutionizing therapeutic strategies by tailoring interventions to individual cancer profiles. The burgeoning trend towards personalized medicine heralds a new era in cancer care, with genetic testing and biomarker analysis becoming commonplace to decipher the molecular intricacies of head and neck cancers. This granular understanding enables the identification of specific mutations driving cancer progression, facilitating the implementation of targeted therapies.
By aligning treatment strategies with patients’ unique genetic profiles, precision medicine endeavors to optimize therapeutic efficacy and improve treatment outcomes. For instance, head and neck cancer accounts for about 4% of all cancers in the United States, with an estimated 66,920 people diagnosed in 2023. Worldwide, an estimated 562,328 people were diagnosed with head and neck cancer in 2020. In the UK, there are around 12,400 new head and neck cancer cases every year, making it the 8th most common cancer in the country. These statistics underscore the importance of personalized medicine in improving treatment outcomes and reducing the global burden of head and neck cancer.
Advancements in Treatment Modalities:
The ascendancy of minimally invasive surgical techniques, exemplified by robotic surgery and transoral robotic surgery (TORS), signifies a paradigm shift in surgical approaches for head and neck cancers. For instance, TORS is an exciting breakthrough in the treatment of certain head and neck cancers, allowing surgeons to access challenging areas of the mouth and throat and remove tumors that once required large incisions. This technique has been particularly beneficial considering that head and neck cancer accounts for about 4% of all cancers in the United States, with an estimated 66,920 people diagnosed in 2023. Worldwide, an estimated 562,328 people were diagnosed with head and neck cancer in 2020. Offering advantages such as smaller incisions, expedited recovery times, and enhanced preservation of function and aesthetics, these techniques enhance patient experiences while maintaining treatment efficacy. In fact, patients undergoing TORS typically experience less time under general anesthesia, a lower risk of surgical complications, less surgical blood loss, less postoperative discomfort, a quicker recovery period, and a shorter hospital stay. Advancements in image-guided radiation therapy (IGRT) empower clinicians to achieve unprecedented precision in targeting tumors while minimizing radiation exposure to healthy tissues. This refined approach not only enhances treatment efficacy but also mitigates treatment-related side effects, thereby optimizing patient outcomes. IGRT is beneficial in head and neck cancer in both the definitive and adjuvant setting. Highly complex and conformal planning techniques are becoming standard practice in delivering increased doses in head and neck cancer. IGRT provides the relevant advantages of radiotherapy by precisely delivering tumoricidal doses via real-time knowledge of the target volume location and achieves maximal tumor control with minimal complications.
Market Challenges Analysis
Challenges in Treatment and Access:
The multifaceted nature of head and neck cancer treatment, encompassing surgery, radiation therapy, drug therapies, and supportive care, often translates into exorbitant financial burdens for patients, even with insurance coverage. Addressing the soaring treatment costs and expanding access to financial assistance programs are imperative strategies to alleviate the financial strain on patients and ensure equitable access to quality care. Despite significant advancements, some head and neck cancers pose formidable treatment challenges, with current therapies falling short of achieving optimal efficacy. The pursuit of more effective treatment modalities through continued research and innovation is paramount to enhance overall cure rates and alleviate the burden of treatment-resistant cancers, underscoring the pressing need for sustained investment in cancer research.
Quality of Life and Awareness Challenges:
Treatment for head and neck cancer often precipitates debilitating long-term side effects, including difficulties in speech, swallowing, and eating, profoundly impacting patients' quality of life. Efforts to mitigate these adverse effects and develop treatment modalities with fewer long-term consequences are imperative to enhance the holistic well-being of patients and optimize post-treatment recovery. Despite growing recognition, an awareness gap persists regarding the association between Human Papillomavirus (HPV) infection and head and neck cancers, particularly oropharyngeal cancer. Bridging this gap through targeted educational campaigns can foster public awareness, encourage preventive measures such as HPV vaccination, and empower individuals to make informed healthcare decisions, thereby curbing the incidence of HPV-related head and neck cancers.
Market Segmentation Analysis:
By Drug Class:
The Head and Neck Cancer Market is segmented by drug class into EGFR inhibitors, Mitotic inhibitors, Anti-PD-1 monoclonal antibodies, and others. EGFR inhibitors, such as cetuximab and panitumumab, dominate the market segment due to their widespread use in targeted therapy for head and neck cancers. Mitotic inhibitors, including paclitaxel and docetaxel, also hold a significant market share owing to their efficacy in disrupting cancer cell division. The emergence of Anti-PD-1 monoclonal antibodies, like pembrolizumab and nivolumab, represents a promising trend in immunotherapy-based treatments, offering new avenues for improving patient outcomes. Additionally, the segment encompasses other drugs, such as platinum-based chemotherapies and targeted agents, contributing to the comprehensive armamentarium available for head and neck cancer treatment.
By Distribution Channel:
The distribution channel segment of the Head and Neck Cancer Market comprises hospitals pharmacies, retail pharmacies, and e-commerce platforms. Hospitals pharmacies serve as primary distribution hubs, catering to the bulk of prescription medications and specialized treatments for head and neck cancers. Retail pharmacies play a vital role in extending access to medications for outpatient care, offering convenience and accessibility to patients. The advent of e-commerce platforms introduces a novel avenue for procuring medications and supportive care products, providing patients with the convenience of doorstep delivery and facilitating access to specialized treatments, particularly in remote or underserved areas. This diversified distribution landscape ensures widespread availability and accessibility of essential medications and supportive care products for patients battling head and neck cancers, enhancing overall treatment outcomes and patient experiences.
Segments:
Based on Drug Class
- EGFR Inhibitors
- Mitotic Inhibitors
- Anti-PD-1 Monoclonal Antibodies
- Others
Based on Distribution Channel
- Hospitals Pharmacies
- Retail Pharmacies
- E-commerce
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America currently holds the largest market share, accounting for approximately 35% of the global head and neck cancer market. The region's well-established healthcare infrastructure, the presence of major research institutions and pharmaceutical companies, and the high adoption rate of innovative cancer therapies have contributed to its dominant position. The United States, in particular, has been at the forefront of developing and adopting advanced diagnostic tools, targeted therapies, and novel treatment approaches for head and neck cancers.
Europe
Europe follows closely behind, with a market share of around 30%. Countries like Germany, France, and the United Kingdom have been proactive in promoting cancer research and the adoption of cutting-edge treatment modalities. The region's focus on improving patient outcomes, reducing mortality rates, and the availability of advanced diagnostic and therapeutic solutions have fueled market growth. Additionally, the increasing geriatric population and the rising incidence of head and neck cancers, particularly in regions with high tobacco and alcohol consumption, have further boosted the demand for reliable cancer care in Europe.
Key Player Analysis
- Sanofi
- Pfizer
- Eli Lilly and Company
- F. Hoffmann-La Roche
- AstraZeneca
- Merck KgaA
- Bayer AG
- Bristol-Myers Squibb Company
- Bayer AG
- Galera
Competitive Analysis
In the fiercely competitive landscape of the Head and Neck Cancer Market, leading players such as Sanofi, Pfizer, Eli Lilly and Company, F. Hoffmann-La Roche, AstraZeneca, Merck KgaA, Bayer AG, Bristol-Myers Squibb Company, Bayer AG, and Galera continually strive to innovate and capture market share. Sanofi, Pfizer, and Bristol-Myers Squibb Company stand out for their extensive portfolios of oncology drugs, including targeted therapies and immunotherapies, positioning them as formidable contenders in the market. Eli Lilly and Company and F. Hoffmann-La Roche are renowned for their pioneering research and development initiatives, consistently introducing novel treatment modalities and diagnostic technologies. AstraZeneca and Merck KgaA leverage their global presence and strategic partnerships to expand market reach and drive growth. Bayer AG and Galera distinguish themselves through their focus on developing innovative therapies targeting specific molecular pathways implicated in head and neck cancers, promising enhanced treatment efficacy and improved patient outcomes. Amidst intensifying competition, these leading players continue to invest in research, development, and strategic collaborations to maintain their competitive edge and address the evolving needs of patients with head and neck cancers.
Recent Developments
In April 2023, Eli Lilly presented the first clinical data on its KRAS G12 inhibitor at the American Association for Cancer Research (AACR) meeting in Orlando. KRAS G12 is a specific genetic mutation in the KRAS oncogene. The KRAS gene produces a protein called K-Ras, which helps to regulate cell growth and division. A mutation in the KRAS gene can lead to the production of a faulty K-Ras protein that is always active, causing cells to grow and divide uncontrollably, resulting in cancer.
In August 2022, Eli Lilly and Company announced a clinical trial collaboration and supply agreement (CTCSA) with Erasca, Inc. to evaluate the anti-EGFR antibody cetuximab (Erbitux), supporting the ongoing phase 1/1b FLAGSHP-1 trial (NCT04670679) examining ERAS-601, an oral SHP2 inhibitor in combinations. This includes assessment for the treatment of triple wild-type (KRAS/NRAS/BRAF wild-type) metastatic colorectal cancer (CRC) and human papillomavirus (HPV)-negative advanced head and neck squamous cell carcinoma (HNSCC).
Market Concentration & Characteristics
The Head and Neck Cancer Market exhibits characteristics of moderate to high market concentration, with a select group of pharmaceutical companies dominating the landscape. These key players, including Sanofi, Pfizer, Eli Lilly and Company, F. Hoffmann-La Roche, AstraZeneca, Merck KgaA, Bayer AG, Bristol-Myers Squibb Company, Bayer AG, and Galera, command significant market shares owing to their extensive portfolios of oncology drugs and robust research and development capabilities. This concentrated market environment is marked by intense competition fueled by continuous innovation in treatment modalities, diagnostic technologies, and supportive care solutions. Strategic alliances, mergers, and acquisitions are common strategies employed by these players to consolidate market presence and expand their product offerings. Additionally, regulatory approvals, clinical trial outcomes, and reimbursement policies significantly influence market dynamics, shaping the competitive landscape and driving strategic decision-making among industry leaders. As market players vie for prominence, differentiation through therapeutic innovation, global market expansion, and patient-centric approaches remains paramount in navigating the evolving landscape of head and neck cancer therapeutics.
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The Head and Neck Cancer Market is projected to witness sustained growth driven by increasing incidence rates and advancements in treatment modalities.
- Focus on Precision Medicine: There will be a heightened emphasis on personalized treatment approaches, leveraging genetic testing and targeted therapies to optimize patient outcomes.
- Expansion of Immunotherapy: Immunotherapy will play an increasingly prominent role in head and neck cancer treatment, offering new avenues for improving patient survival rates.
- Enhanced Diagnostics: Innovations in diagnostic technologies will facilitate earlier and more accurate detection of head and neck cancers, improving treatment efficacy.
- Adoption of Minimally Invasive Techniques: Minimally invasive surgical procedures will become more prevalent, offering patients shorter recovery times and improved quality of life.
- Rising Importance of Supportive Care: There will be a growing focus on comprehensive supportive care initiatives to address the diverse needs of patients throughout their treatment journey.
- Integration of Artificial Intelligence: Artificial intelligence will play an integral role in diagnostics, treatment planning, and drug discovery, driving efficiency and precision in patient care.
- Expansion of Telehealth Services: Telehealth platforms will be increasingly utilized for remote patient monitoring and follow-up care, enhancing access to specialized healthcare services.
- Addressing Healthcare Disparities: Efforts to reduce disparities in access to quality care and early detection will be intensified, aiming for equitable healthcare outcomes for all patient populations.
- Collaborative Research Efforts: Collaborations between industry stakeholders, research institutions, and regulatory bodies will foster innovation and accelerate the development of novel therapeutics and diagnostic tools for head and neck cancers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Head and Neck Cancers
Increasing incidence rates, particularly of head and neck squamous cell carcinoma (HNSCC), are driven by factors such as tobacco and alcohol use, as well as HPV infection, leading to greater demand for diagnostic and therapeutic solutions.
Advancements in Diagnosis and Treatment
Innovations in high-resolution imaging, biomarker testing, and minimally invasive surgical techniques are enabling earlier detection and more effective, less invasive treatments, improving patient outcomes and expanding the market.
Growing Geriatric Population
As the global population ages, the number of elderly individuals at higher risk for head and neck cancers rises, increasing the patient pool and driving demand for specialized cancer care and therapies tailored to older adults.
Integration of Immunotherapy and Personalized Medicine
The adoption of immunotherapies and precision medicine approaches, such as anti-PD-1 monoclonal antibodies and genetic profiling, is transforming treatment paradigms and offering new hope for patients with advanced or treatment-resistant disease.
Government Initiatives and Awareness Campaigns
Public health campaigns and government programs focused on early detection, HPV vaccination, and access to care are increasing awareness and screening rates, contributing to earlier intervention and market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Head and Neck Cancer Market?
What factors are driving the growth of the Head and Neck Cancer Market?
What are the key segments within the Head and Neck Cancer Market?
What are some challenges faced by the Head and Neck Cancer Market?
Who are the major players in the Head and Neck Cancer Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 EGFR Inhibitors
- 1.2.2 Mitotic Inhibitors
- 1.2.3 Anti-PD-1 Monoclonal Antibodies
- 1.2.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2398.95 million → 2032: USD 4006.18 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Head and Neck Cancer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Head and Neck Cancer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Head and Neck Cancer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Head and Neck Cancer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Head and Neck Cancer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Head and Neck Cancer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Head and Neck Cancer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Head and Neck Cancer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2398.95 million → 2032: USD 4006.18 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Head and Neck Cancer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 EGFR Inhibitors
- 12.3.7.2 Mitotic Inhibitors
- 12.3.7.3 Anti-PD-1 Monoclonal Antibodies
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Head and Neck Cancer Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Head and Neck Cancer Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Head and Neck Cancer Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Sanofi
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Pfizer
- 17.4 Eli Lilly and Company
- 17.5 F. Hoffmann-La Roche
- 17.6 AstraZeneca
- 17.7 Merck KGaA
- 17.8 Bayer AG
- 17.9 Bristol-Myers Squibb Company
- 17.10 Galera Therapeutics
- 17.11 Novartis AG
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

