
Market Overview:
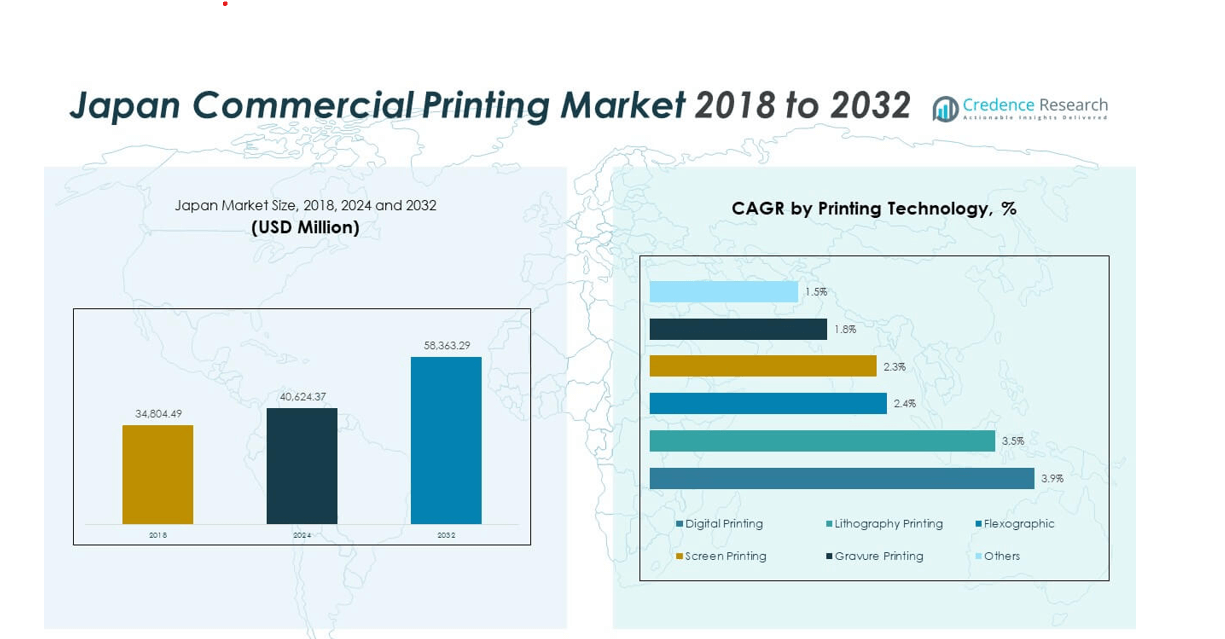
The Japan Commercial Printing Market size was valued at USD 34,804.49 million in 2018 to USD 40,624.37 million in 2024 and is anticipated to reach USD 58,363.29 million by 2032, at a CAGR of 4.63% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Commercial Printing Market Size 2024 | USD 40,624.37 million |
| Japan Commercial Printing Market, CAGR | 4.63% |
| Japan Commercial Printing Market Size 2032 | USD 58,363.29 million |
Growing digital transformation and demand for sustainable printing solutions drive market momentum. Businesses adopt automation and AI-enabled workflows to enhance accuracy, speed, and cost efficiency. Rising e-commerce activity strengthens packaging print demand, while variable data printing improves marketing personalization. The shift toward low-VOC inks and recyclable substrates aligns with national environmental goals. Digital presses reduce setup time, supporting short-run jobs and customized print campaigns across multiple industries.
The Kantō region leads the Japan Commercial Printing Market, supported by Tokyo’s strong corporate, publishing, and advertising base. Kansai follows with robust demand from industrial and consumer goods producers. Chūbu, Kyushu, and other regions maintain steady growth from packaging and local manufacturing demand. Urban areas drive premium and customized printing, while regional markets support educational, government, and retail sectors. The nation’s advanced production infrastructure sustains Japan’s leadership in quality, precision, and innovation within commercial printing.
Market Insights
- The Japan Commercial Printing Market was valued at USD 34,804.49 million in 2018, reached USD 40,624.37 million in 2024, and is projected to hit USD 58,363.29 million by 2032, registering a CAGR of 4.63%.
- The Kantō region dominates with approximately 45% share, driven by Tokyo’s concentration of publishing, corporate, and advertising industries. Kansai follows with about 16%, supported by manufacturing and consumer product printing. Chūbu contributes nearly 12% due to its strong industrial base and packaging activities.
- The Kyushu region, holding around 8% share, is the fastest-growing area due to expanding logistics, retail packaging, and investments in modern digital presses catering to regional commerce.
- By printing technology, digital printing and flexographic printing show the fastest growth rates at around 3.5% and 3.9%, supported by automation and on-demand print demand.
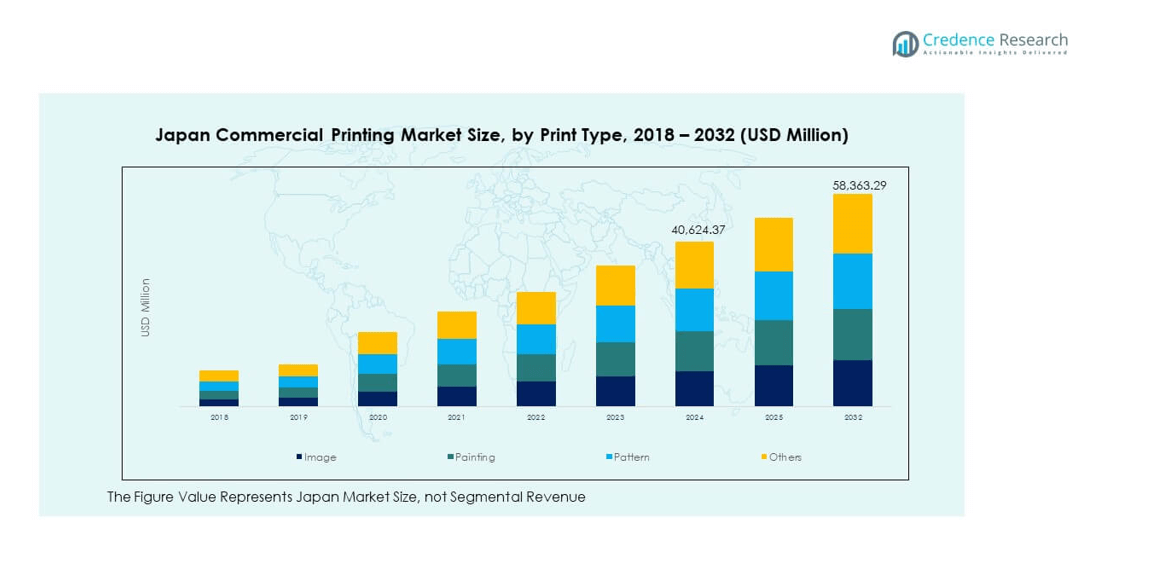
- By print type, image and pattern printing hold major revenue shares, reflecting Japan’s emphasis on design precision, branding, and high-quality visual communication across packaging and marketing materials.
Market Drivers
High Demand for Short-Run and On-Demand Printing Solutions
The Japan Commercial Printing Market benefits from rapid digitalization across enterprises and publishers. Businesses seek short-run print services for targeted marketing and flexible packaging needs. Demand for customized brochures, catalogs, and promotional materials rises with personalization campaigns. Advanced digital presses help reduce setup time and improve turnaround speed. The growing e-commerce sector increases the need for printed materials with quick delivery. Print-on-demand platforms attract SMEs seeking efficient print production without large inventories. Variable data printing drives engagement in direct mail campaigns. Automation and AI-enabled workflows optimize job sequencing and minimize waste.
- For example, Ricoh's Pro C7200X digital press, widely used in Japan, features advanced automation like an Auto Calibration System that automates color density adjustments and registration setup. This system minimizes operator errors and reduces setup time considerably, allowing operators of varying skill levels to produce jobs efficiently.
Rise of Sustainable Printing Materials and Low-Emission Inks
Growing environmental awareness pushes Japanese printers to use eco-friendly inks and recyclable substrates. The market adopts water-based, soy-based, and low-VOC inks that reduce environmental impact. Print houses gain certifications such as FSC and ISO 14001 for sustainability compliance. Packaging producers adopt biodegradable paperboard and recycled films to meet circular economy goals. Clients prefer vendors that provide carbon-neutral or low-waste print operations. Regulatory pressure from green initiatives accelerates adoption of eco-label printing. Equipment suppliers introduce energy-efficient presses that cut power use by up to 30%. The sustainability trend strengthens long-term competitiveness for printing firms.
Integration of Automation and Data-Driven Print Management Systems
Automation tools enhance production efficiency through digital workflow integration and predictive analytics. Japanese print facilities install cloud-based management systems for end-to-end monitoring. Data insights support real-time scheduling, job tracking, and preventive maintenance. Automated finishing units improve consistency across product lines. Firms adopt AI-powered layout optimization and defect detection systems. Integration with ERP platforms enables transparent cost and delivery management. Automation reduces manual errors and speeds up print runs. It also lowers operating costs, improving margins for commercial printers.
Expanding Role of Print in Brand Storytelling and Omnichannel Campaigns
Brands continue using print to enhance physical engagement with customers. The market benefits from rising demand for premium packaging and high-impact visual media. Luxury, cosmetics, and food sectors rely on tactile and personalized prints for brand differentiation. Augmented reality and QR-linked print campaigns merge digital and physical marketing. Print integrates with data-driven campaigns for personalized content delivery. Designers use advanced coatings and finishes to enhance perceived product value. Japan’s focus on craftsmanship and design precision maintains print’s cultural and marketing significance.
- For example, Shiseido has actively incorporated augmented reality in its marketing and retail strategies. For example, the company launched AR-based beauty experiences through its “Beauty AR Navigation” and immersive pop-up campaigns to enhance consumer engagement and product visualization. These initiatives highlight Shiseido’s focus on digital innovation in customer experience, though they are primarily implemented in retail and promotional settings rather than directly through product packaging.
Market Trends
Wider Adoption of Hybrid Printing Systems for Production Flexibility
Japanese printers increasingly deploy hybrid systems combining offset and digital capabilities. The approach supports faster turnaround without compromising color consistency. Print providers manage diverse jobs like packaging, advertising, and publishing with reduced setup time. Hybrid presses lower waste through digital proofing and calibration tools. Growing demand for variable data printing boosts hybrid press installations. Major vendors offer modular systems allowing easy upgrades. It enables firms to scale production efficiently across multiple job types.
- For example, Fujifilm’s Acuity Prime Hybrid, unveiled at FESPA 2023, is a mid-range LED UV wide-format printer capable of printing on both rigid and roll media up to 2.1 m wide. It reaches speeds of up to 141 m²/hr and supports up to seven ink channels including CMYK, white, clear, and primer, demonstrating high versatility for commercial and packaging print applications.
Growing Use of Automation and Robotics in Print Operations
Automation continues shaping Japan’s commercial print sector. Robotics handle repetitive workflows such as stacking, binding, and material handling. Smart sensors track print quality and reduce downtime through predictive alerts. Integration of automated inspection ensures accuracy in every print run. Robotics also improve safety in large-scale plants with heavy materials. Automation supports lean manufacturing, reducing idle time and manual labor dependence. It strengthens operational consistency for high-volume clients.
Digital Transformation of Print Supply Chains and Customer Interfaces
Print companies digitize client engagement through online ordering, remote proofing, and dynamic pricing. AI-driven print portals allow seamless coordination of artwork and specifications. Cloud-based collaboration enhances communication between design teams and production facilities. The shift enables real-time adjustments in layout or quantity before printing. Digital platforms improve transparency and shorten approval cycles. E-commerce integration allows clients to customize orders and track fulfillment easily.
Rise of Premium Finishing and Smart Print Enhancements
Japanese printers adopt advanced finishing techniques to stand out in a competitive market. Embossing, metallic foiling, and textured coatings enhance product appeal. Smart labels with NFC and QR codes link consumers to digital experiences. High-value packaging for cosmetics and confectionery relies on sophisticated visual effects. UV-curable coatings increase durability and color brilliance. Investment in 3D and lenticular printing adds depth and motion effects. The premiumization of print aligns with Japan’s focus on design excellence.
- For example, Mitsubishi Heavy Industries has long produced advanced printing and paper-converting machinery, including commercial web-offset presses and box-making systems used in Japan’s packaging sector. The company focuses on improving productivity, precision, and automation across large-scale printing operations, supporting industrial and packaging applications through its engineering expertise.
Market Challenges Analysi
Decline in Traditional Print Volumes and Rising Digital Media Competition
The Japan Commercial Printing Market faces steady decline in offset and publication print demand. Digital media channels continue diverting advertising budgets from print to online formats. Book and magazine publishers cut print volumes to manage inventory costs. Reduced demand for large-scale commercial print jobs pressures margins. Printers must balance traditional contracts with emerging digital services. Limited paper supply fluctuations also affect pricing stability. Firms seek differentiation through packaging and short-run jobs to counter volume loss.
High Equipment Costs and Skilled Labor Shortage
Advanced digital and hybrid presses demand significant investment. Small and mid-sized printers face barriers to adopt next-gen systems. Maintenance costs increase due to reliance on imported parts and software upgrades. Skilled operators capable of managing automation and color calibration are limited. Training new talent remains a challenge in Japan’s aging workforce. Labor shortages drive up wages and slow production capacity expansion. Consolidation among print houses continues as firms seek shared resources and scale efficiency
Market Opportunities
Rising Demand for Value-Added Printing and Smart Packaging Applications
The Japan Commercial Printing Market gains new opportunities from connected packaging and interactive prints. Brands use embedded QR and NFC features for real-time consumer engagement. Premium packaging designs for luxury goods and electronics drive aesthetic innovation. Value-added services such as personalization and variable imaging increase client retention. Smart print features strengthen brand authenticity and anti-counterfeit protection.
Growth of Digital Printing Exports and Cross-Regional Partnerships
Japanese print manufacturers expand by serving regional clients across Asia-Pacific. High-quality standards attract international demand for specialty prints and packaging. Collaboration with Southeast Asian print service providers reduces production costs and lead times. Export-focused printers benefit from Japan’s reputation for precision engineering. Expansion into fast-growing e-commerce packaging markets presents long-term growth potential.
Market Segmentation Analysis
By Printing Technology
Digital printing leads Japan’s commercial sector due to strong demand for short-run and customized jobs. Lithography remains vital for large-volume production requiring consistent quality. Flexographic and gravure printing maintain their role in high-speed packaging lines. Screen printing supports specialty applications such as textiles and industrial labels.
By Application
Packaging dominates due to the growth of e-commerce and premium consumer goods. Publishing continues serving educational and corporate sectors despite digital shifts. Advertising and marketing prints maintain relevance in brand campaigns. Retail and e-commerce segments use variable printing for personalized labeling and promotions.
- For example, packaging printing is exemplified by SUN PRINTING CO., LTD. in Japan, which won the Innovation Print Awards 2025 Global in the Carton Packaging category. They use advanced digital presses on FUJIFILM technology, enabling precise, high-speed printing for premium packaging applications with reduced turnaround times.
By Service Type
Printing services form the market’s foundation with value-added offerings. Packaging printing grows with demand for sustainability and visual differentiation. Large-format and promotional printing cater to events and retail branding. Transactional and direct mail printing benefit from data-driven marketing. Value-added services like finishing, lamination, and design consultancy enhance client engagement.
By Print Type
Image and pattern printing remain central for visual branding and packaging aesthetics. Painting and decorative prints cater to art reproduction and creative design sectors. Other niche types include architectural, textile, and specialty substrate printing that reflect Japan’s design-oriented economy.
- For example, Dai Nippon Printing, a leader in high-resolution image and pattern printing, offers solutions with resolutions up to 1200 dpi for luxury brand packaging, enhancing visual branding aesthetics. They also provide specialty printing services in architectural and textile sectors, leveraging technologies aligned with Japan’s design-oriented economy.
Segmentation
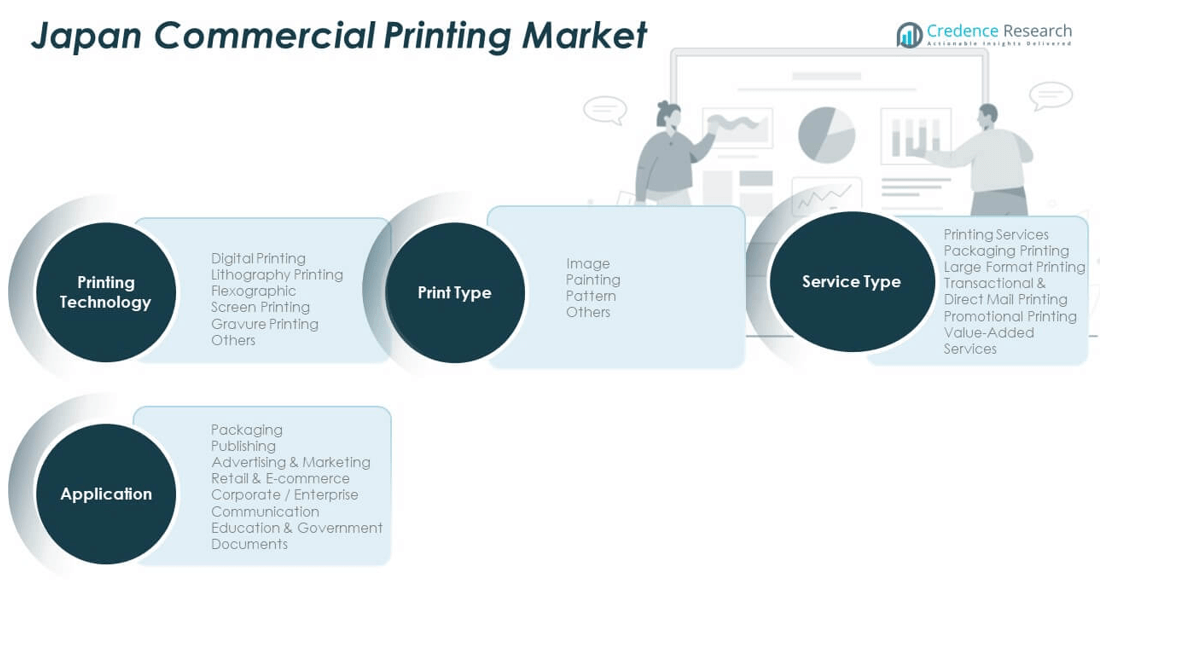
By Printing Technology:
- Digital Printing
- Lithography Printing
- Flexographic Printing
- Screen Printing
- Gravure Printing
- Others
By Application:
- Packaging
- Publishing
- Advertising & Marketing
- Retail & E-commerce
- Corporate / Enterprise Communication
- Education & Government Documents
By Service Type:
- Printing Services
- Packaging Printing
- Large Format Printing
- Transactional & Direct Mail Printing
- Promotional Printing
- Value-Added Services
By Print Type:
- Image
- Painting
- Pattern
- Others
Regional Analysis
Kantō Region - Dominant Market Share (~45 %)
Kantō, which includes the Tokyo metropolitan area, contributes roughly 45 % of Japan’s national GDP. Given its economic scale, high population density, concentration of corporations, and strong demand for corporate communication, packaging and advertising print, Kantō likely accounts for around 45 % of the commercial-printing demand in Japan. Major publishers, large-scale advertisers and e-commerce headquarters cluster here, fueling demand for high-volume printing and packaging services. High urban consumption and brand activity further push demand for premium print finishes and short-run, on-demand printing.
Kansai Region - Important Secondary Hub (~16 %)
Kansai contributes about 16 % of Japan’s GDP. This region, anchored by Osaka, Kyoto and Kobe, supports a mix of industrial, manufacturing and consumer-goods sectors that drive demand for packaging, marketing materials, and specialized commercial print. Many mid-sized enterprises and traditional manufacturers are based here. Its role in manufacturing and export industries can boost demand for printed packaging, corporate communications and promotional materials - making Kansai a significant secondary region for the printing market.
Chūbu, Kyushu and Other Regions - Remainder Share (~39 %)
The central region Chūbu, along with other regions such as Kyushu, Chūgoku, Hokkaido/Tohoku, Shikoku, likely compose the remaining share. Chūbu holds substantial industrial output and population clusters. In these regions, demand comes from manufacturing-derived packaging, regional publishing, local retail and small to mid-scale enterprises. Urbanisation outside major hubs remains lower, reducing per-capita print demand; but manufacturing and regional trade support steady demand for packaging and commercial print. Rural and less-dense prefectures yield lower volume but still contribute meaningfully due to a broad base of industries and local businesses.
Key Player Analysis
- Dai Nippon Printing Co., Ltd. (DNP)
- Toppan Printing Co., Ltd.
- Kosaido Co., Ltd.
- Kyoiku Printing Co., Ltd.
- Nissha Co., Ltd.
- Toppan Forms Co., Ltd.
- Seikosha Printing Co., Ltd.
- Mitsumura Printing Co., Ltd.
- Toyo Ink Group Holdings Co., Ltd.
- Matsuoka Printing Co., Ltd.
Competitive Analysis
The Japan Commercial Printing Market features a mix of long-standing conglomerates, specialized printers, and agile digital-print houses. Large companies hold broad service portfolios that cover publishing, packaging, direct mail, and corporate print. These firms benefit from economies of scale, established client relationships, and integrated printing workflows. Mid-size and small print providers often focus on niche segments such as short-run digital jobs, promotional printing, or value-added finishing. They win clients by offering speed, flexibility, and customized services that large houses may not handle efficiently. Increasing demand for packaging printing and on-demand printing shifts competitive pressure toward modern digital- and hybrid-printing capabilities. Print houses that invest in automation, workflow software, and sustainable materials gain an edge over those relying on traditional methods. Firms that build strong ties with e-commerce brands, retail sector clients, or luxury product manufacturers tend to secure stable, high-margin contracts. Overall competition forces all players to optimize efficiency, adopt newer technologies, and tailor services to evolving customer requirements.
Recent Developments
- In November 2025, DNP teamed with F-SAS Technologies to launch a high-precision generative-AI solution for secure, on-premises document handling. The solution aims at industries requiring high confidentiality, like government, finance and manufacturing.
- In April 2025, TOPPAN Holdings completed its acquisition of the Thermoformed & Flexibles Packaging business (TFP) from Sonoco Products Company. The deal expands Toppan’s global sustainable-packaging business and enhances its packaging and film manufacturing footprint.
Report Coverage
The research report offers an in-depth analysis based on Printing Technology, Application, Service Type and Print Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue shifting toward digital and hybrid printing as businesses demand fast, personalized production.
- Sustainable materials and low-emission inks will remain a major innovation focus among Japan’s leading print houses.
- Automation and smart workflows will reshape print operations, improving efficiency and energy management.
- Packaging printing will lead future revenue streams due to e-commerce growth and premium product branding.
- Integration of AR, QR, and NFC features will expand in marketing prints and connected packaging applications.
- Export-oriented printers will gain traction by serving premium packaging demand across Asia-Pacific markets.
- Large players will invest in next-generation inkjet and UV-curable systems to enhance print versatility.
- Talent development and digital upskilling will become critical as the market adapts to advanced production systems.
- Rising collaborations between printers and design agencies will strengthen end-to-end brand communication services.
- The Japan Commercial Printing Market will consolidate through mergers and partnerships, enabling scale and technology sharing across segments.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Japan Commercial Printing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Japan Commercial Printing Market projected to grow between 2024 and 2032?
Which Japan Commercial Printing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Japan Commercial Printing Market?
Who are the leading companies in the Japan Commercial Printing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 40,624.37 million → 2032: USD 58,363.29 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Commercial Printing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Commercial Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Commercial Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Commercial Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Commercial Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Commercial Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Commercial Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Commercial Printing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 40,624.37 million → 2032: USD 58,363.29 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Commercial Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Commercial Printing Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Japan Commercial Printing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Japan Commercial Printing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

