
Market Overview
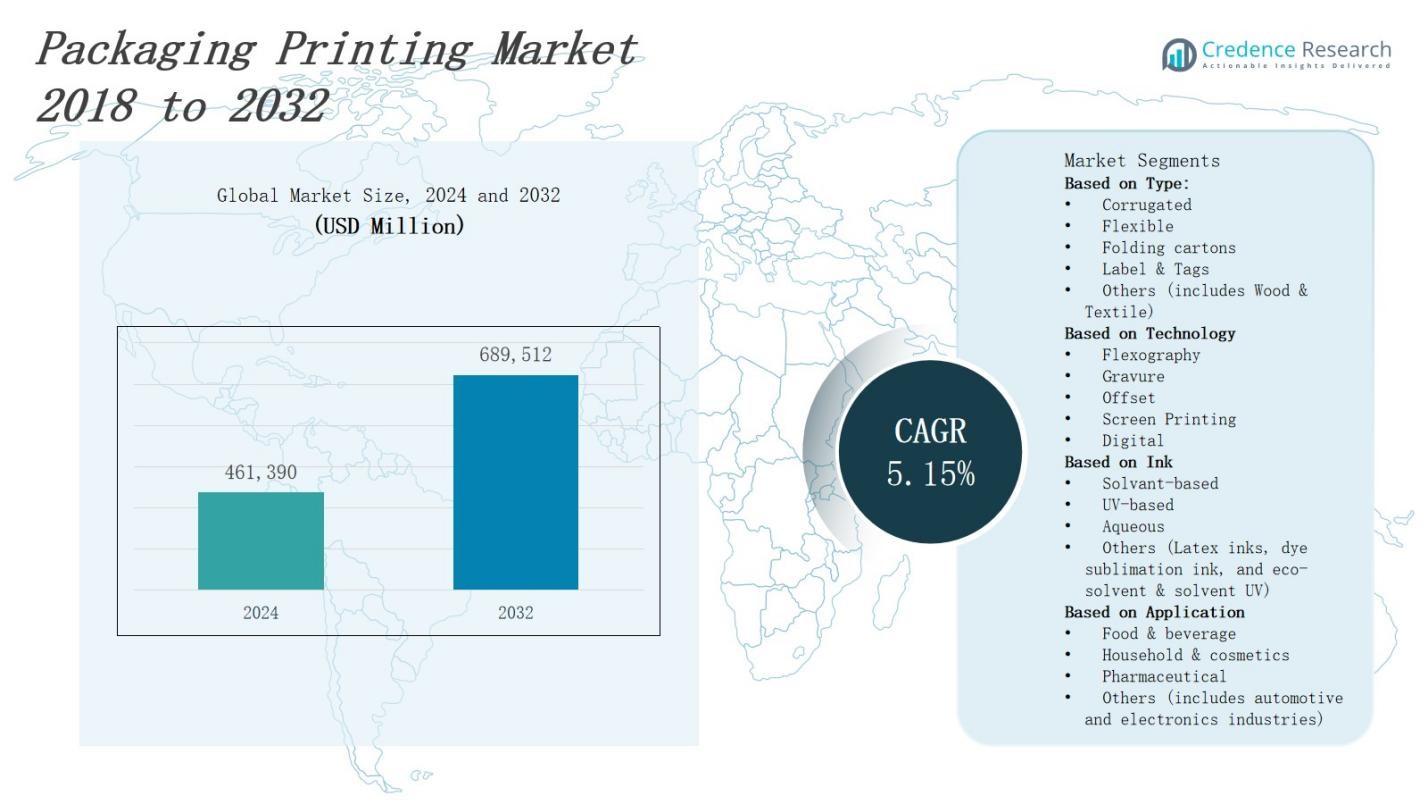
The Packaging Printing Market is projected to expand from USD 461,390 million in 2024 to USD 689,512 million by 2032, registering a CAGR of 5.15%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Packaging Printing Market Size 2024 | USD 461,390 Million |
| Packaging Printing Market, CAGR | 5.15%. |
| Packaging Printing Market Size 2032 | USD 689,512 Million |
Key drivers propelling the Packaging Printing Market include rising demand for sustainable and customizable packaging solutions, stringent regulations on labeling accuracy, and growth in e‑commerce packaging volumes. Technological advancements such as digital printing, narrow‑web presses, and UV‑curable inks enhance production efficiency and print quality. Brands leverage variable data printing to personalize packaging and improve consumer engagement. Trends in smart packaging-incorporating QR codes, NFC tags, and anti‑counterfeit features-gain traction across food, beverage, and pharmaceutical sectors. Growing emphasis on lightweight, eco‑friendly substrates drives innovation in recyclable and compostable materials. The convergence of print and digital workflows supports faster time‑to‑market and reduces waste.
North America, Europe, Asia Pacific, Latin America, Middle East & Africa drive the Packaging Printing Market. North America relies on digital press adoption by Amcor and Quad/Graphics, while Europe sees sustainable substrate innovation led by Mondi plc and Constantia Flexibles. Asia Pacific features high‑volume output from Toppan Printing and Sonoco Products Company. Latin America grows through flexible‑format solutions by Graphics Packaging Holding Company and WS Packaging Group. Middle East & Africa expands specialty printing services offered by Quantum Print and Packaging and Duncan Printing Group. It adapts to local demands.
Market Insights
- The Packaging Printing Market will grow from USD 461,390 million in 2024 to USD 689,512 million by 2032, at a 5.15% CAGR.
- Brands drive demand for recyclable and compostable substrates to meet sustainability goals and strict labeling mandates.
- Digital presses, narrow‑web flexo systems and UV‑curable inks boost throughput and elevate print quality.
- Variable data printing enables personalized campaigns that enhance consumer engagement.
- Smart packaging features-QR codes, NFC tags and anti‑counterfeit marks-gain adoption in food, beverage and pharma.
- E‑commerce growth fuels demand for corrugated, flexible and retail‑ready formats with shorter lead times.
- The convergence of print and digital workflows reduces waste and accelerates time‑to‑market.
Market Drivers
Sustainable Packaging and Regulatory Compliance
Companies drive the Packaging Printing Market through increased focus on eco-friendly substrates and compliance with strict labeling mandates. It meets consumer demand for recyclable and compostable materials while satisfying government rules on product information. Brands adopt water-based and UV-curable inks to reduce environmental impact. Regulators enforce clear ingredient listings and safety warnings. Producers invest in life-cycle assessments to verify sustainability claims. Focus supports market growth.
- For instance, Printpack introduced PRESERVE™ COMPOSTABLE, a fully compostable, heat-sealable packaging film designed for food products, certified for both home and industrial composting standards.
Advanced Digital Printing Technologies and Customization
Digital inkjet presses and narrow-web flexographic systems drive efficiency in the Packaging Printing Market. They enable short runs, flexible design updates without plate changes. Variable data printing allows brands to personalize packaging for regional campaigns and limited editions. Printers embrace ultraviolet curing and hybrid presses to accelerate production cycles. Suppliers improve print resolution and cost per unit. Innovation delivers competitive advantage to packaging converters.
- For instance, HP’s Indigo 35K Digital Press enables brands to execute short-run folding carton jobs on demand, supporting frequent design changes and personalization for targeted campaigns.
E‑Commerce Expansion and Demand for Flexible Formats
Rapid growth in online retail fuels the Packaging Printing Market for corrugated, flexible and retail-ready packaging. It addresses variable order sizes and shifts packaging styles for seasonal promotions. Brands require lightweight substrates that cut transport costs. Shorter lead times prompt investment in automated finishing and inspection. Printers adopt metallic foils and textured coatings to enhance appeal. Focus reduces waste and boosts operational agility.
Security Features and Supply Chain Traceability
Integration of anti-counterfeit elements drives the Packaging Printing Market toward higher security standards. It embeds QR codes, NFC tags and tamper-evident seals into labels. Brands implement serialization and blockchain links to verify authenticity. Printers collaborate with technology providers to embed invisible inks and microtext. Consumer trust increases through real-time tracking via mobile applications. This security focus strengthens brand protection and supply chain integrity overall.
Market Trends
Digital Integration and Workflow Automation
Manufacturers implement cloud-based platforms to optimize press setup and quality control. It accelerates production cycles for the Packaging Printing Market and reduces manual interventions. Printers integrate inline sensors to monitor print parameters in real time. They standardize data exchange across prepress and finishing processes. Firms upgrade software to manage orders and track inventory. Investment in machine learning algorithms supports predictive maintenance and minimizes downtime.
- For instance, Packsize launched the PackNet Cloud Cube-a cloud-based platform that calculates precise package dimensions and optimal box sizes for every order, reducing waste and improving production efficiency by minimizing manual interventions.
Emergence of Smart Packaging and Traceability Solutions
Brands embed QR codes, RFID chips and invisible inks into labels to enhance consumer engagement. It transforms routine packaging into interactive platforms within the Packaging Printing Market. Printers collaborate with technology firms to integrate blockchain‑backed serialization. Labels feature temperature indicators and tamper‑evident seals to secure supply chains. Manufacturers deploy digital watermarks to authenticate products. Real‑time tracking enables rapid recalls and verifies origin at each distribution point.
- For instance, Nestlé deployed QR codes on its KitKat packaging in Japan, enabling consumers to scan the wrapper and send digital messages or access real-time product information, which increased consumer engagement.
Rise of Personalization and Short‑Run Production
Clients request custom designs and variable text for regional promotions and seasonal campaigns. The Packaging Printing Market meets demand for limited‑edition labels and flexible layouts. It handles orders as small as a few hundred units without cost penalties. Printers adopt hybrid presses that switch between digital and analog workflows on demand. Short‑set runs reduce waste and support just‑in‑time delivery. Automation software assigns unique codes to each package for targeted marketing.
Premiumization through Enhanced Finishing and Decoration
Brands apply metallic foils, soft‑touch coatings and embossed textures to elevate packaging presence. The Packaging Printing Market leverages specialty finishes to differentiate premium products. It integrates laser die‑cutting to create intricate shapes and windows. Printers use cold foil and matte varnishes to achieve tactile contrast. High‑resolution screening delivers crisp graphics on film and paper. Converters deploy inline inspection to ensure color consistency and finish integrity.
Market Challenges Analysis
Volatile Raw Material Costs and Supply Chain Disruptions
The Packaging Printing Market faces pressure from fluctuating prices of paper, ink and film substrates. It struggles to absorb sudden spikes in commodity costs without eroding margins. Global supply chain bottlenecks force converters to hold higher safety stocks and negotiate longer lead times. Printers contend with shortages of specialized coatings and additives that support premium finishes. They must balance cost containment with quality demands when suppliers impose minimum order quantities. This volatility compels firms to strengthen supplier relationships and explore alternative materials to maintain stable operations.
Regulatory Pressures and Technological Adoption Hurdles
Environmental regulations drive the Packaging Printing Market toward stricter waste management and recycling mandates. It must invest in compliant inks, substrates and finishing processes that meet evolving standards. Printers encounter high capital requirements for digital presses and automation systems that improve efficiency. Limited technical expertise hinders rapid deployment of workflow software and inline inspection tools. Brands demand traceability features such as serialization and tamper‑evident seals, increasing complexity in production. Companies must train staff on new technologies while managing upgrade costs within tight budgets.
Market Opportunities
Expansion of Eco‑Friendly and Sustainable Printing Solutions
Brands accelerate investment in recyclable substrates and water‑based inks to meet consumer and regulatory demands. The Packaging Printing Market benefits from growth in bio‑based films and compostable coatings that reduce environmental impact. It presents converters with a chance to develop closed‑loop systems and promote lifecycle transparency. Printers secure long‑term contracts by offering cradle‑to‑grave print audits and carbon‑neutral certifications. Suppliers introduce novel substrates made from agricultural waste to diversify material portfolios. Collaborative pilot programs enable rapid validation of sustainable workflows. This focus on green credentials drives revenue growth and strengthens brand loyalty.
Adoption of Smart Packaging and Digital Engagement Strategies
Demand for interactive labels featuring QR codes, NFC tags and augmented‑reality triggers generates new revenue streams. The Packaging Printing Market leverages digital printing platforms to deliver variable data campaigns at scale. It empowers brands to track products through blockchain‑based serialization and real‑time analytics. Printers partner with software vendors to integrate cloud‑based asset management and order‑fulfillment dashboards. Retailers reward suppliers offering personalized packaging for loyalty‑program engagement. Emerging micro‑print and invisible‑ink technologies open niche applications in luxury and pharmaceutical segments. This shift toward connected packaging deepens consumer engagement and unlocks aftermarket marketing opportunities.
Market Segmentation Analysis:
By Type
The Packaging Printing Market divides into corrugated, flexible, folding cartons, label & tags, and other formats. It depends on corrugated boards for sturdy retail packs and e‑commerce shipments. Flexible substrates suit pouches and sachets for food and personal care applications. Folding cartons serve pharmaceutical and cosmetic sectors with high‑quality graphics. Label & tags support branding across all packaged goods. Other materials include wood and textile for specialty uses.
- For instance, Amcor specializes in printing flexible substrates for food packaging, such as snack pouches, offering high barrier properties and customization to protect product freshness and meet consumer demands.
By Technology
The Packaging Printing Market employs flexography, gravure, offset, screen printing, and digital presses. It uses flexography for high‑speed runs on corrugated and flexible films. Gravure suits long runs that need fine detail and consistent ink laydown. Offset digital printing delivers precise color reproduction on folding cartons and labels. Screen printing provides thick ink layers for specialty coatings. Digital presses handle short runs and variable data without plates.
- For instance, Mark Andy Inc. uses flexography for high-speed printing on corrugated packaging and flexible films, achieving efficient production runs with consistent quality.
By Ink Type
The Packaging Printing Market includes solvent‑based, UV‑based, aqueous, and specialty inks. It leverages solvent‑based inks for durability on outdoor labels. UV‑based inks cure instantly under UV light, which increases line speeds and scratch resistance. Aqueous inks suit food contact and eco‑friendly workflows. Specialty inks cover latex, dye sublimation, eco‑solvent, and solvent UV formulations. Printers select ink according to substrate compatibility and regulatory requirements.
Segments:
Based on Type:
- Corrugated
- Flexible
- Folding cartons
- Label & Tags
- Others (includes Wood & Textile)
Based on Technology
- Flexography
- Gravure
- Offset
- Screen Printing
- Digital
Based on Ink
- Solvant-based
- UV-based
- Aqueous
- Others (Latex inks, dye sublimation ink, and eco-solvent & solvent UV)
Based on Application
- Food & beverage
- Household & cosmetics
- Pharmaceutical
- Others (includes automotive and electronics industries)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The Packaging Printing Market in North America holds 20% share, driven by advanced manufacturing infrastructure and high e‑commerce volumes. It benefits from widespread adoption of digital presses that support just‑in‑time production. Brands demand variable data printing for personalized packaging campaigns. Sustainable materials gain traction under strict environmental regulations. Printers invest in inline quality control to reduce waste and improve throughput. Strong collaboration between converters and technology providers fuels innovation.
Europe
Europe captures 25% share of the Packaging Printing Market, supported by mature recycling systems and stringent labeling laws. It leads in compostable substrates and water‑based ink usage to meet regulatory requirements. Printers deploy narrow‑web flexographic systems for high‑quality folding cartons. Brands integrate QR codes and NFC tags for traceability across food and pharmaceutical supply chains. Investment in automation software enhances order management and inventory tracking. Cross‑border partnerships accelerate technology transfer.
Asia Pacific
Asia Pacific commands 35% share in the Packaging Printing Market, propelled by rapid industrialization and rising consumer demand. It leverages low‑cost manufacturing to execute large‑scale corrugated and flexible packaging projects. Printers scale hybrid presses to balance short runs with long‑run efficiencies. Local brands drive customization through vibrant graphic designs and specialty finishes. Government incentives promote sustainable ink formulations and renewable substrates. High population density supports growth in single‑serve and retail‑ready packaging formats.
Latin America
Latin America accounts for 10% share of the Packaging Printing Market, led by burgeoning food and beverage sectors in Brazil and Mexico. It upgrades gravure and offset presses to meet rising demand for folding cartons and labels. Printers secure cost advantages through regional raw‑material sourcing. Brands emphasize brand differentiation through metallic foils and embossed decorations. Supply chain modernization prompts investment in RFID‑enabled label production. Training programs enhance technical skills and operational efficiency.
Middle East & Africa
Middle East & Africa holds 10% share of the Packaging Printing Market, driven by growth in pharmaceutical and luxury goods exports. It relies on UV‑based inks for rapid curing and enhanced durability in arid climates. Printers adopt screen printing for specialty textiles and wood‑based packaging. Brands require tamper‑evident seals and serialization for product security. Investment in inline inspection systems ensures compliance with international standards. Government licensing reforms attract foreign converters and technology vendors.
Key Player Analysis
- Amcor Limited (Australia)
- Quad/Graphics (US)
- Mondi plc (Austria)
- WS Packaging Group (US)
- Sonoco Products Company (US)
- Toppan Printing Company (Japan)
- Graphics Packaging Holding Company (US)
- Constantia Flexibles (Austria)
- Duncan Printing Group (UK)
- Quantum Print and Packaging Limited (UK)
Competitive Analysis
Leading firms in the Packaging Printing Market compete through investments in digital press capacity, specialty inks and sustainable substrates. It intensifies competition around short‑run campaigns and personalization. Global players such as Amcor Limited, Mondi plc and Sonoco Products Company leverage distribution networks and integrated supply chains to secure high‑value contracts. Quad/Graphics and Toppan Printing Company expand digital printing footprints in North America and Asia, while Constantia Flexibles and Quantum Print and Packaging Limited concentrate on flexible packaging innovations. Private regional converters challenge incumbents by offering rapid turnaround and cost‑effective niche solutions. Companies pursue mergers and acquisitions to enhance technology portfolios and expand geographic reach. Strategic alliances with ink and substrate suppliers improve efficiency and reduce production costs. Emphasis on inline quality control, traceability and lifecycle transparency differentiates market participants. It maintains high entry barriers due to capital intensity and regulatory compliance.
Recent Developments
- In January 2025, International Paper acquired UK‑based DS Smith for $7.2 billion, expanding its recycled paper packaging and printing capabilities across North America and EMEA.
- On July 23, 2025, HEIDELBERG acquired Polar Mohr’s brand rights, technology, and IP, strengthening its position as a systems integrator in the packaging market.
- On April 1, 2025, Mondi plc completed the acquisition of Schumacher Packaging’s Western Europe assets, expanding its sustainable packaging portfolio and production capacity.
- On April 22, 2025, JUNG introduced a digital printing system for branded tissue paper and gift wrap, delivering high‑resolution graphics on paper substrates.
Market Concentration & Characteristics
The Packaging Printing Market exhibits moderate concentration, with global leaders capturing significant revenue through expansive production networks and technology investments. It relies on major players such as Amcor Limited and Mondi plc to set quality and sustainability benchmarks. It combines high capital requirements for digital and flexographic presses with regulatory compliance costs to create substantial entry barriers. It offers small and mid‑sized converters opportunities in niche segments like luxury finishes and regional packaging solutions. It demands continuous innovation in substrate development and ink chemistry to retain customer loyalty. It leverages strategic partnerships with ink and equipment suppliers to streamline supply chains. It emphasizes operational efficiency through inline inspection and automated workflows. It balances scale advantages against the agility of specialized providers in meeting customized orders. It maintains competitive intensity through mergers, acquisitions and technology licensing that reshape market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Type, Technology, Ink Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Brands adopt compostable and recycled substrates to meet consumer demands and strengthen environmental responsibility initiatives.
- Printers integrate QR codes and NFC tags into packaging to enable real‑time authentication and engagement.
- Companies leverage cloud‑based workflows and automation to streamline prepress operations and accelerate job management processes.
- Converters implement inline inspection systems to detect print defects immediately and maintain consistent quality standards.
- Manufacturers expand short‑run digital printing services to support customized campaigns and reduce material waste effectively.
- Firms secure strategic partnerships with ink and equipment suppliers to enhance capabilities and diversify offerings.
- Packaging producers invest in blockchain serialization to provide end‑to‑end traceability and strengthen supply chain transparency.
- Suppliers develop novel ink formulations that comply with environmental regulations and consistently improve print performance.
- Print shops implement agile operations to respond to market shifts and deliver value to brands.
- Industry players explore 3D printing prototypes to innovate packaging design and accelerate product development cycles.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustainable Packaging and Regulatory Compliance
Increasing consumer and regulatory demand for recyclable, compostable, and eco-friendly packaging materials is driving brands and converters to adopt new substrates and inks, fueling market growth and innovation.
Advanced Digital Printing Technologies and Customization
The adoption of digital presses, variable data printing, and hybrid workflows enables short-run, personalized, and high-quality packaging, allowing brands to engage consumers more effectively and respond rapidly to market trends.
E-Commerce Expansion and Demand for Flexible Formats
The surge in online retail is increasing the need for corrugated, flexible, and retail-ready packaging that can be produced quickly and efficiently, supporting diverse order sizes and reducing lead times.
Security Features and Supply Chain Traceability
Growing concerns over counterfeiting and supply chain integrity are prompting the integration of QR codes, NFC tags, and serialization into packaging, enhancing product authentication and consumer trust.
Digital Integration and Workflow Automation
The implementation of cloud-based platforms, inline sensors, and automated quality control systems streamlines production, reduces waste, and accelerates time-to-market, making packaging printing more efficient and responsive.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Packaging Printing Market?
What factors are driving the growth of the Packaging Printing Market?
What are the key segments within the Packaging Printing Market?
What are some challenges faced by the Packaging Printing Market?
Who are the major players in the Packaging Printing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Corrugated
- 1.2.2 Flexible
- 1.2.3 Folding Cartons
- 1.2.4 Label & Tags
- 1.2.5 Others (Wood & Textile)
- 1.3 By Ink Type
- 1.3.1 Solvent-based
- 1.3.2 UV-based
- 1.3.3 Aqueous
- 1.3.4 Others (Latex, Dye Sublimation, Eco-solvent & Solvent UV)
- 1.4 By Technology
- 1.4.1 Flexography
- 1.4.2 Gravure
- 1.4.3 Offset
- 1.4.4 Screen Printing
- 1.4.5 Digital
- 1.5 By Application
- 1.5.1 Food & Beverage
- 1.5.2 Household & Cosmetics
- 1.5.3 Pharmaceutical
- 1.5.4 Others (Automotive, Electronics)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 461,390 million → Forecast year: -
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Packaging Printing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Packaging Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Packaging Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Packaging Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Packaging Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Packaging Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Packaging Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Packaging Printing Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 461,390 million → Forecast year: - )
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Packaging Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Corrugated
- 12.3.7.2 Flexible
- 12.3.7.3 Folding Cartons
- 12.3.7.4 Label & Tags
- 12.3.7.5 Others (Wood & Textile)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Ink Type - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solvent-based
- 12.4.7.2 UV-based
- 12.4.7.3 Aqueous
- 12.4.7.4 Others (Latex, Dye Sublimation, Eco-solvent & Solvent UV)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Flexography
- 12.5.7.2 Gravure
- 12.5.7.3 Offset
- 12.5.7.4 Screen Printing
- 12.5.7.5 Digital
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast
- 12.6.4 Volume Forecast
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Food & Beverage
- 12.6.7.2 Household & Cosmetics
- 12.6.7.3 Pharmaceutical
- 12.6.7.4 Others (Automotive, Electronics)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Packaging Printing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Packaging Printing Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Packaging Printing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Packaging Printing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Quad/Graphics
- 18.4 Mondi plc
- 18.5 WS Packaging Group
- 18.6 Sonoco Products Company
- 18.7 Toppan Printing Company
- 18.8 Graphics Packaging Holding Company
- 18.9 Constantia Flexibles
- 18.10 Duncan Printing Group
- 18.11 Quantum Print and Packaging Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

