
Market Overview
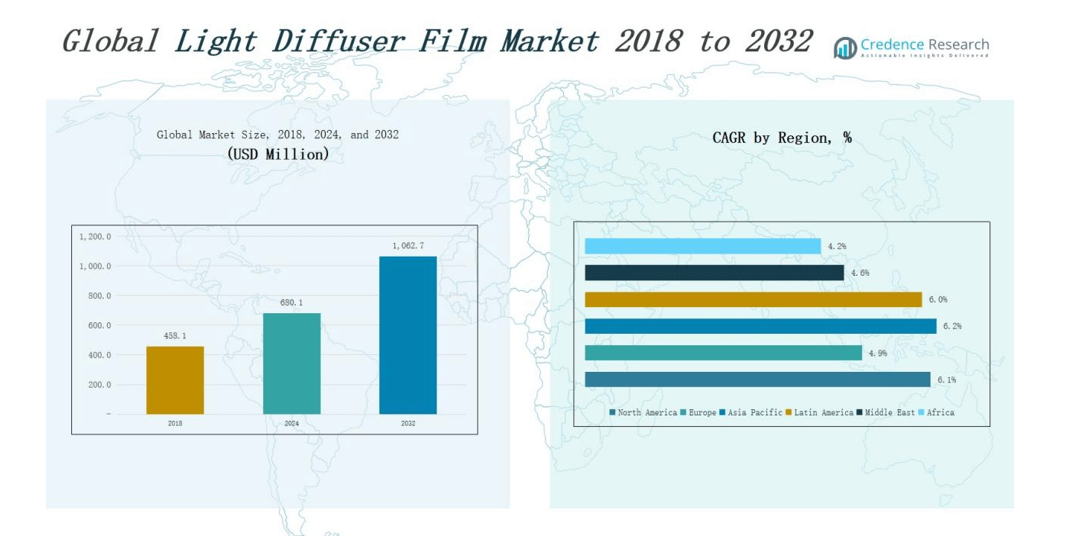
Light Diffuser Film Market size was valued at USD 458.1 million in 2018 to USD 680.1 million in 2024 and is anticipated to reach USD 1,062.7 million by 2032, at a CAGR of 5.77% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Light Diffuser Film Market Size 2024 | USD 680.1 million |
| Light Diffuser Film Market, CAGR | 5.77% |
| Light Diffuser Film Market Size 2032 | USD 1,062.7 million |
The Light Diffuser Film Market is shaped by major players such as 3M, Sumitomo Chemical, Kolon Industries, Kimoto Ltd., Daicel Corporation, Keiwa Inc., API Optix, Bright View Technologies, Fusion Optix, and Whiteoptix. These companies drive competition through advancements in film technology, enhanced light transmission, and customized applications across displays, lighting, and automotive sectors. Asia-Pacific holds the dominant position in the market with a 45 percent share, supported by robust electronics manufacturing, expanding display panel production, and rising investments in smart lighting and automotive technologies across countries like China, South Korea, and Japan.
Market Insights
- The Light Diffuser Film Market is projected to grow from USD 680.1 million in 2024 to USD 1,062.7 million by 2032, supported by a CAGR of 5.77 percent.
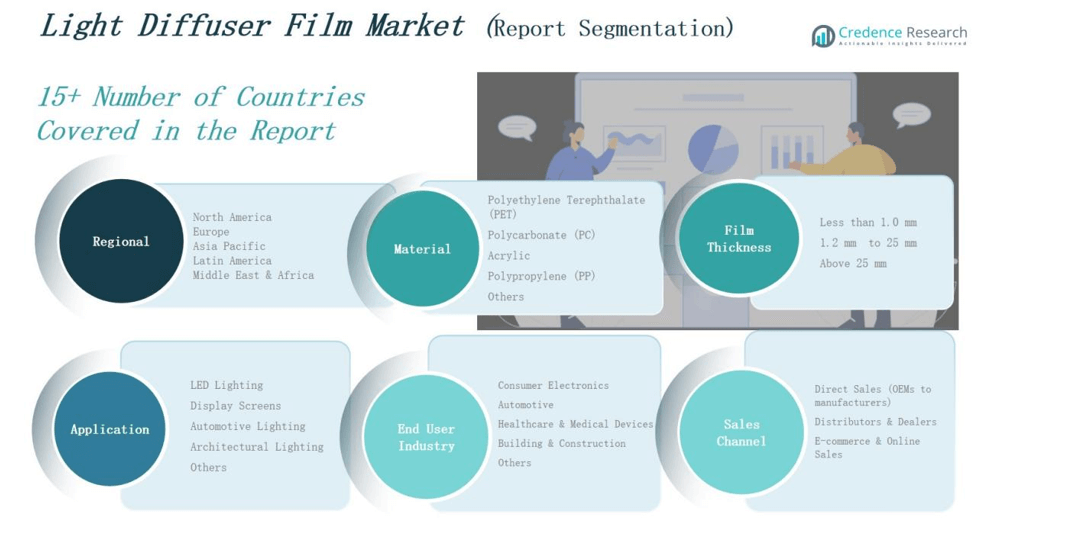
- Polyethylene Terephthalate (PET) dominates by material type with 38 percent share, driven by its optical clarity, durability, cost efficiency, and recyclability in LED lighting and display screens.
- The 1.2 mm to 25 mm film thickness segment leads with 52 percent share, offering versatility and durability, making it the preferred choice across LED luminaires and architectural lighting applications.
- LED lighting holds the largest application share at 44 percent, fueled by global energy efficiency initiatives, with display screens and automotive lighting contributing significantly to overall demand.
- Asia Pacific dominates regionally with 39 percent share, supported by strong electronics manufacturing in China, Japan, and South Korea, along with rising LED and smart city investments.
Market Segment Insights
By Material Type:
Polyethylene Terephthalate (PET) leads the light diffuser film market with a 38 percent share, supported by its superior optical clarity, durability, and cost-effectiveness in mass production. PET films are widely used across display screens and LED lighting due to their high diffusion efficiency and recyclability, making them a preferred choice in sustainable product design. Polycarbonate (PC) follows with notable demand in automotive and architectural lighting where impact resistance and thermal stability are critical. Acrylic films capture niche adoption in premium display panels for their clarity, while polypropylene (PP) gains traction in cost-sensitive applications.
- For instance, Samsung Display has used PET-based diffusion layers in its OLED panel stack-up to optimize brightness uniformity.
By Film Thickness:
The 1.2 mm to 25 mm segment dominates the market with a 52 percent share, driven by its versatility in balancing light diffusion, durability, and compatibility across multiple applications such as LED luminaires and architectural lighting. This thickness range ensures optimal performance without compromising structural integrity, making it a standard for most end-use industries. Films below 1.0 mm hold significant adoption in compact display devices, offering flexibility and thin form factor advantages, particularly in smartphones and tablets. The above 25 mm segment, though smaller, addresses specialized uses in automotive and architectural installations that require enhanced diffusion and mechanical strength.
- For instance, Signify (formerly Philips Lighting) uses diffuser panels within this thickness range for its Philips Ledinaire series, which are widely adopted in commercial and office environments for balanced light distribution.
By Application:
LED lighting represents the largest application segment with a 44 percent market share, fueled by the global shift toward energy-efficient lighting systems and the widespread adoption of LED technology in residential, commercial, and industrial settings. Light diffuser films enhance uniformity, reduce glare, and improve aesthetics in luminaires, making them indispensable in this sector. Display screens form the second-largest application, with strong demand from smartphones, televisions, and monitors, where clarity and brightness control are key. Automotive lighting continues to expand, benefiting from rising vehicle electrification and advanced headlamp designs.
Market Overview
Rising Adoption of LED Lighting:
The transition from traditional lighting to energy-efficient LED systems serves as a primary growth driver for the light diffuser film market. LED luminaires require high-quality diffuser films to ensure uniform light distribution, reduce glare, and enhance visual comfort. Growing residential, commercial, and industrial adoption of LED lighting, supported by government energy-efficiency initiatives, strengthens demand. The rising penetration of smart lighting solutions and architectural projects that prioritize energy savings further fuels the requirement for advanced diffuser films across global markets.
- For instance, Signify expanded its Philips Hue smart lighting ecosystem in early 2025 by integrating AI-powered features that optimize personalized lighting scenes, driving demand for advanced diffuser films in residential settings.
Expansion of Display and Consumer Electronics:
The proliferation of smartphones, tablets, televisions, and advanced display systems boosts demand for light diffuser films that provide clarity, color uniformity, and enhanced brightness. Manufacturers of consumer electronics increasingly integrate diffusion films to improve viewing quality and minimize visual fatigue. With the growing penetration of OLED and LCD technologies, coupled with the expansion of premium large-screen devices, the market benefits from consistent consumption in both developed and emerging economies. Rapid innovation cycles and higher replacement rates in consumer electronics accelerate segment growth.
- For instance, Apple uses diffuser films in its iPhone displays to improve color consistency and visual clarity, contributing to reduced eye strain during prolonged use.
Automotive and Architectural Applications Growth:
The expanding use of advanced lighting systems in vehicles and modern buildings drives demand for durable and efficient diffuser films. Automotive manufacturers adopt light diffuser films in headlamps, tail lamps, and interior illumination to improve safety and aesthetics. In architectural lighting, these films contribute to uniform brightness, design flexibility, and visual appeal in both commercial and residential spaces. Increasing construction activities in developing economies, along with growing investment in smart cities and modern infrastructure projects, positions this segment as a strong contributor to overall market growth.
Key Trends & Opportunities
Shift Toward Sustainable Materials:
Sustainability emerges as a prominent trend, with manufacturers focusing on recyclable and eco-friendly diffuser films. Rising environmental awareness and stricter regulations encourage the use of polyethylene terephthalate (PET) and other recyclable polymers. Companies are investing in bio-based and low-carbon footprint solutions to appeal to environmentally conscious consumers and align with global sustainability standards. This trend creates opportunities for innovation in material science, enabling differentiation and market advantage for players offering eco-friendly alternatives without compromising optical performance.
- For instance, Toray has developed the Ecouse™Lumirror™ circular recycling PET film, which is made by mechanically recycling used films collected from customers, reducing CO2 emissions by up to 50% while maintaining film quality.
Integration with Smart Technologies:
The growing adoption of IoT-enabled and smart lighting solutions creates new opportunities for diffuser film manufacturers. As connected lighting systems gain traction in commercial, industrial, and residential settings, demand rises for films that complement advanced features such as tunable brightness and color temperature control. The push for human-centric lighting and smart building integration expands the scope of applications. This technological synergy allows manufacturers to collaborate with lighting and electronics companies to deliver customized solutions tailored to evolving smart infrastructure needs.
- For instance, Covestro’s Makrofol translucent polycarbonate films have been used to optimize LED lighting by providing flexibility in design combined with durability, helping deliver smart night light solutions with integrated touch controls.
Key Challenges
High Raw Material Price Volatility:
Fluctuations in the prices of raw materials such as polycarbonate, acrylic, and PET create challenges for manufacturers in maintaining consistent profit margins. Dependency on petrochemical supply chains exposes the industry to unpredictable pricing pressures, especially during periods of geopolitical instability or supply shortages. These cost variations affect production budgets and pricing strategies, potentially reducing competitiveness. Manufacturers must focus on strategic sourcing, recycling initiatives, and process optimization to mitigate risks associated with raw material volatility.
Intense Market Competition:
The light diffuser film market faces stiff competition from global and regional players, leading to price pressures and margin challenges. Established companies compete on product performance, material innovation, and customer reach, while smaller players leverage cost advantages to capture niche markets. This competitive environment compels firms to continuously invest in research, customization, and distribution capabilities. The need for differentiation through advanced film technologies, sustainability, or tailored solutions remains critical for long-term growth and brand positioning.
Technical Limitations in Specialized Applications:
Despite widespread adoption, diffuser films face technical constraints in meeting specialized performance requirements for high-end applications. In automotive and medical devices, demands for extreme durability, high thermal resistance, or unique optical properties present manufacturing challenges. Inadequate performance under such conditions can limit product acceptance and hinder broader penetration. Continuous research in material engineering, nanotechnology, and surface treatments is necessary to overcome these limitations and expand the functional scope of light diffuser films in advanced applications.
Regional Analysis
North America:
North America holds a 26 percent share of the light diffuser film market in 2024, valued at USD 164.52 million, and is projected to reach USD 264.41 million by 2032 at a CAGR of 6.1 percent. The region benefits from strong demand in LED lighting, display technologies, and automotive applications, driven by advanced consumer electronics adoption and stringent energy-efficiency regulations. The U.S. leads the market with its robust electronics and automotive sectors, while Canada and Mexico contribute through construction and manufacturing expansion. Innovation and early adoption of sustainable materials further strengthen regional competitiveness.
Europe:
Europe accounts for a 28 percent share of the global market in 2024, valued at USD 179.77 million, and is expected to reach USD 263.35 million by 2032, registering a CAGR of 4.9 percent. The region emphasizes sustainable solutions and energy-efficient lighting, supported by strict EU environmental regulations and bans on inefficient lighting systems. Germany, France, and the UK lead in consumer electronics and automotive adoption, while Southern Europe shows strong growth in architectural applications. Investments in advanced display technologies and demand for recyclable materials position Europe as a hub for sustainable product innovation.
Asia Pacific:
Asia Pacific dominates the global market with a 39 percent share in 2024, valued at USD 249.40 million, and is forecasted to reach USD 403.84 million by 2032, growing at the highest CAGR of 6.2 percent. China, Japan, and South Korea drive regional leadership with massive display panel production, strong electronics manufacturing bases, and rising LED lighting adoption. India and Southeast Asia show increasing demand due to rapid urbanization and infrastructure development. The region’s cost-effective manufacturing capabilities, coupled with investments in smart city and automotive projects, firmly establish Asia Pacific as the largest and fastest-growing market.
Latin America:
Latin America captures a 8 percent share in 2024, valued at USD 51.31 million, and is expected to reach USD 81.51 million by 2032 at a CAGR of 6.0 percent. Brazil leads the region with widespread adoption of LED lighting and growing demand for consumer electronics, supported by government energy-efficiency initiatives. Mexico and Argentina contribute with steady growth in automotive and construction segments. Expanding infrastructure investments, rising middle-class purchasing power, and the shift toward modern lighting systems create new opportunities for diffuser film adoption in residential and commercial sectors.
Middle East:
The Middle East represents a 4 percent share of the market in 2024, valued at USD 20.66 million, and is projected to reach USD 29.54 million by 2032, growing at a CAGR of 4.6 percent. The region shows strong demand from large-scale construction projects, particularly in the GCC countries, where smart cities and architectural lighting projects dominate. Rising adoption of LED systems in both commercial and residential spaces aligns with sustainability goals and energy diversification plans. Opportunities also emerge in automotive lighting, supported by luxury vehicle adoption across Gulf markets and rising consumer preference for advanced lighting systems.
Africa:
Africa holds a 3 percent share in 2024, valued at USD 14.49 million, and is anticipated to reach USD 20.09 million by 2032, growing at a CAGR of 4.2 percent. South Africa and Egypt lead regional adoption with increasing use of LED lighting in urban development projects, while other African nations are gradually shifting from conventional lighting to energy-efficient systems. Limited penetration of advanced consumer electronics and infrastructure challenges restrict market expansion. However, government-driven electrification programs and international investments in smart grid and building projects are expected to accelerate adoption of diffuser films across the continent.
Market Segmentations:
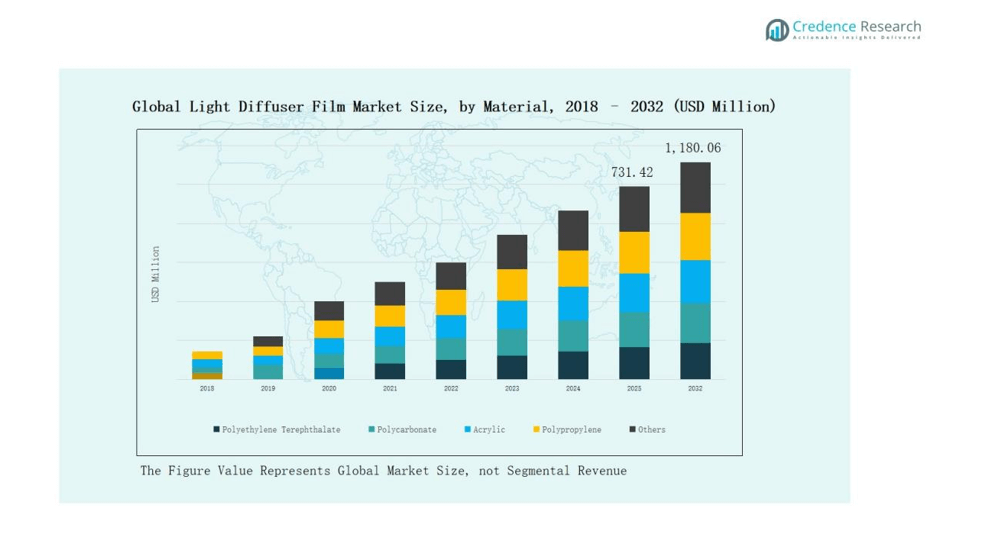
By Material Type
- Polyethylene Terephthalate (PET)
- Polycarbonate (PC)
- Acrylic
- Polypropylene (PP)
- Others
By Film Thickness
- Less than 1.0 mm
- 2 mm to 25 mm
- Above 25 mm
By Application
- LED Lighting
- Display Screens
- Automotive Lighting
- Architectural Lighting
- Others
By End User Type
- Consumer Electronics
- Automotive
- Healthcare & Medical Devices
- Building & Construction
- Others
By Sales Channel
- Direct Sales (OEMs to Manufacturers)
- Distributors & Dealers
- E-commerce & Online Sales
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
North America:
North America holds a 26 percent share of the light diffuser film market in 2024, valued at USD 164.52 million, and is projected to reach USD 264.41 million by 2032 at a CAGR of 6.1 percent. The region benefits from strong demand in LED lighting, display technologies, and automotive applications, driven by advanced consumer electronics adoption and stringent energy-efficiency regulations. The U.S. leads the market with its robust electronics and automotive sectors, while Canada and Mexico contribute through construction and manufacturing expansion. Innovation and early adoption of sustainable materials further strengthen regional competitiveness.
Europe:
Europe accounts for a 28 percent share of the global market in 2024, valued at USD 179.77 million, and is expected to reach USD 263.35 million by 2032, registering a CAGR of 4.9 percent. The region emphasizes sustainable solutions and energy-efficient lighting, supported by strict EU environmental regulations and bans on inefficient lighting systems. Germany, France, and the UK lead in consumer electronics and automotive adoption, while Southern Europe shows strong growth in architectural applications. Investments in advanced display technologies and demand for recyclable materials position Europe as a hub for sustainable product innovation.
Asia Pacific:
Asia Pacific dominates the global market with a 39 percent share in 2024, valued at USD 249.40 million, and is forecasted to reach USD 403.84 million by 2032, growing at the highest CAGR of 6.2 percent. China, Japan, and South Korea drive regional leadership with massive display panel production, strong electronics manufacturing bases, and rising LED lighting adoption. India and Southeast Asia show increasing demand due to rapid urbanization and infrastructure development. The region’s cost-effective manufacturing capabilities, coupled with investments in smart city and automotive projects, firmly establish Asia Pacific as the largest and fastest-growing market.
Latin America:
Latin America captures a 8 percent share in 2024, valued at USD 51.31 million, and is expected to reach USD 81.51 million by 2032 at a CAGR of 6.0 percent. Brazil leads the region with widespread adoption of LED lighting and growing demand for consumer electronics, supported by government energy-efficiency initiatives. Mexico and Argentina contribute with steady growth in automotive and construction segments. Expanding infrastructure investments, rising middle-class purchasing power, and the shift toward modern lighting systems create new opportunities for diffuser film adoption in residential and commercial sectors.
Middle East:
The Middle East represents a 4 percent share of the market in 2024, valued at USD 20.66 million, and is projected to reach USD 29.54 million by 2032, growing at a CAGR of 4.6 percent. The region shows strong demand from large-scale construction projects, particularly in the GCC countries, where smart cities and architectural lighting projects dominate. Rising adoption of LED systems in both commercial and residential spaces aligns with sustainability goals and energy diversification plans. Opportunities also emerge in automotive lighting, supported by luxury vehicle adoption across Gulf markets and rising consumer preference for advanced lighting systems.
Africa:
Africa holds a 3 percent share in 2024, valued at USD 14.49 million, and is anticipated to reach USD 20.09 million by 2032, growing at a CAGR of 4.2 percent. South Africa and Egypt lead regional adoption with increasing use of LED lighting in urban development projects, while other African nations are gradually shifting from conventional lighting to energy-efficient systems. Limited penetration of advanced consumer electronics and infrastructure challenges restrict market expansion. However, government-driven electrification programs and international investments in smart grid and building projects are expected to accelerate adoption of diffuser films across the continent.
Key Players
- 3M
- Yongtek
- Tilara Polyplast Private Limited
- Sun Acrylam Private Limited
- LINTEC Corporation
- KEIWA INCORPORATED
- Luminit, Inc.
- König Folienzentrum
- Ingemann Components A/S
- LG Chem
- Plextrusion India LLP
- Kimoto Ltd.
- Other Key Players
Recent Developments
- l In 2023, Lintec Corporation launched a new series of eco-friendly light diffuser films aimed at improving sustainability in lighting applications.
- l In January 2025, Dai Nippon Printing (DNP) developed a new light diffuser film specifically designed for mini-LED backlights. This film enhances screen vividness while reducing power consumption in display applications.
- l In early 2025, Dai Nippon Printing (DNP) introduced a specialized light diffuser film designed for mini-LED backlight displays that enhances screen brightness and reduces power consumption, targeting next-generation display technologies.
- l In September 2023, BrightView Technologies, Inc. launched a mini-LED display film that delivers up to 30 percent improved LED hiding performance while maintaining brightness, supporting advanced automotive display applications.
Market Concentration & Characteristics
The Light Diffuser Film Market shows a moderately concentrated structure where a mix of global leaders and regional players compete through product innovation, pricing, and distribution capabilities. It relies strongly on established companies that dominate with advanced materials such as PET, polycarbonate, and acrylic, which meet the demand for high optical performance and durability. The market is defined by close integration with consumer electronics, automotive, and lighting industries, making it sensitive to technology cycles and regulatory shifts. It continues to expand with growing LED adoption and the shift toward sustainable, recyclable materials that align with environmental standards. Competitive dynamics are shaped by investments in R&D, the ability to deliver application-specific solutions, and global reach in supply chains. It exhibits moderate entry barriers due to high capital requirements, advanced manufacturing processes, and the need for quality certifications, which allow leading companies to maintain influence while regional firms address cost-driven or niche markets.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Film Thickness, Application, End Use Type, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness rising demand from LED lighting due to global energy efficiency initiatives.
- It will expand with increasing use of diffuser films in smartphones, tablets, and large-screen displays.
- Automotive lighting adoption will grow as manufacturers integrate advanced headlamp and interior designs.
- Architectural projects will drive uptake of diffuser films to achieve aesthetic and uniform lighting solutions.
- Sustainable and recyclable materials will gain preference under strict environmental regulations.
- Regional manufacturers will strengthen their presence by offering cost-effective customized solutions.
- Smart lighting and IoT-enabled systems will create new opportunities for advanced film applications.
- Investment in research will focus on high-performance films with improved optical clarity and durability.
- Competition will intensify as global leaders and regional players pursue partnerships and acquisitions.
- Emerging economies will accelerate adoption through urbanization, infrastructure development, and rising consumer electronics demand.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of LED Lighting
The global shift from traditional lighting to energy-efficient LED systems is driving demand for high-quality light diffuser films, which are essential for uniform light distribution, glare reduction, and enhanced visual comfort in residential, commercial, and industrial settings.
Expansion of Display and Consumer Electronics
The proliferation of smartphones, tablets, televisions, and advanced display systems is boosting the need for diffuser films that improve clarity, color uniformity, and brightness, as manufacturers seek to enhance viewing quality and minimize visual fatigue.
Growth in Automotive and Architectural Applications
Increasing integration of advanced lighting systems in vehicles and modern buildings is fueling demand for durable and efficient diffuser films, which are used to improve safety, aesthetics, and uniformity in headlamps, tail lamps, and architectural lighting.
Shift Toward Sustainable and Recyclable Materials
Rising environmental awareness and stricter regulations are encouraging the use of recyclable polymers like PET in diffuser films, prompting manufacturers to innovate with eco-friendly materials that meet both performance and sustainability requirements.
Integration with Smart Technologies and IoT
The adoption of IoT-enabled and smart lighting solutions is creating new opportunities for advanced diffuser films that support features like tunable brightness and color temperature control, expanding the scope of applications in smart homes, offices, and infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Light Diffuser Film Market, and what is its projected size in 2032?
Which Light Diffuser Film Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Light Diffuser Film Market?
Who are the leading companies in the Light Diffuser Film Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 LED Lighting
- 1.2.2 Display Screens
- 1.2.3 Automotive Lighting
- 1.2.4 Architectural Lighting
- 1.2.5 Others
- 1.3 By End User Type
- 1.3.1 Consumer Electronics
- 1.3.2 Automotive
- 1.3.3 Healthcare & Medical Devices
- 1.3.4 Building & Construction
- 1.3.5 Others
- 1.4 By Material Type
- 1.4.1 Polyethylene Terephthalate (PET)
- 1.4.2 Polycarbonate (PC)
- 1.4.3 Acrylic
- 1.4.4 Polypropylene (PP)
- 1.4.5 Others
- 1.5 By Film Thickness
- 1.5.1 Less than 1.0 mm
- 1.5.2 1.2 mm to 25 mm
- 1.5.3 Above 25 mm
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 680.1 million → 2032: USD 1,062.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Light Diffuser Film Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Light Diffuser Film Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Light Diffuser Film Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Light Diffuser Film Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Light Diffuser Film Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Light Diffuser Film Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Light Diffuser Film Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Light Diffuser Film Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 680.1 million → 2032: USD 1,062.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Light Diffuser Film Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 LED Lighting
- 12.3.7.2 Display Screens
- 12.3.7.3 Automotive Lighting
- 12.3.7.4 Architectural Lighting
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User Type - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Consumer Electronics
- 12.4.7.2 Automotive
- 12.4.7.3 Healthcare & Medical Devices
- 12.4.7.4 Building & Construction
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Polyethylene Terephthalate (PET)
- 12.5.7.2 Polycarbonate (PC)
- 12.5.7.3 Acrylic
- 12.5.7.4 Polypropylene (PP)
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Film Thickness - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Less than 1.0 mm
- 12.6.7.2 1.2 mm to 25 mm
- 12.6.7.3 Above 25 mm
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Light Diffuser Film End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Light Diffuser Film Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Light Diffuser Film Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Light Diffuser Film Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sumitomo Chemical
- 18.4 Kolon Industries
- 18.5 Kimoto Ltd.
- 18.6 Daicel Corporation
- 18.7 Keiwa Inc.
- 18.8 API Optix
- 18.9 Bright View Technologies
- 18.10 Fusion Optix
- 18.11 Whiteoptix
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

