
Market Overview
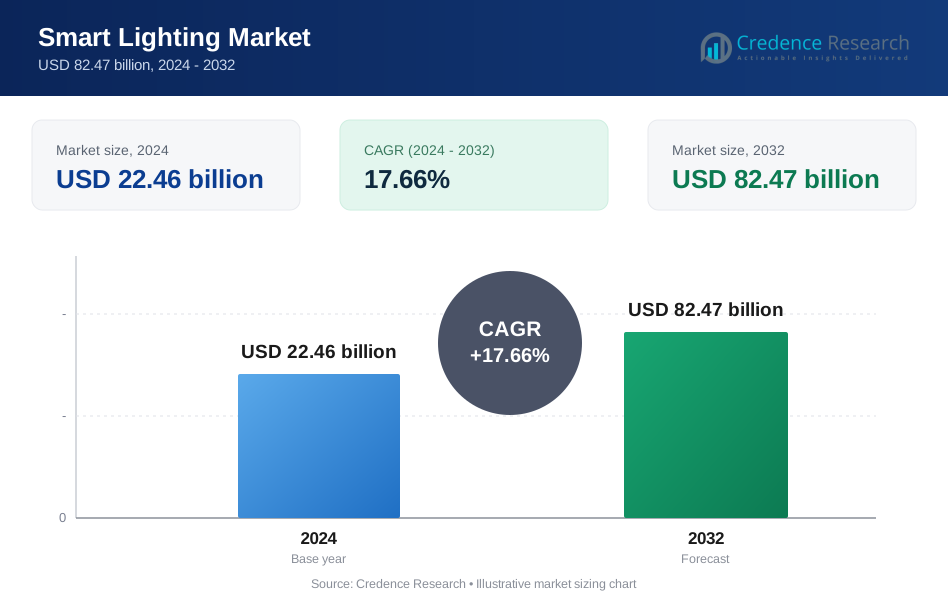
The Smart Lighting market reached USD 22.46 billion in 2024 and is projected to reach USD 82.47 billion by 2032, registering a strong 17.66% CAGR during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Lighting Market Size 2024 | USD 22.46 Billion |
| Smart Lighting Market, CAGR | 17.66% |
| Smart Lighting Market Size 2032 | USD 82.47 Billion |
Top players in the Smart Lighting market include Signify (Philips Lighting), Osram Licht AG, GE Lighting, Acuity Brands, Cree Lighting, Hubbell Incorporated, Lutron Electronics, Zumtobel Group, Legrand, and Helvar Systems. These companies drive market expansion by offering advanced LED systems, IoT-enabled lighting platforms, wireless controls, and sensor-based automation technologies for residential, commercial, and outdoor applications. Their focus on energy efficiency, smart building integration, and AI-driven lighting management strengthens global adoption. Regionally, North America leads the market with a 37% share, supported by strong smart home penetration and modern infrastructure upgrades. Europe follows with a 29% share, driven by strict energy regulations, while Asia-Pacific holds 26%, fueled by rapid urbanization and growing smart city investments.
Market Insights
- The Smart Lighting market was valued at USD 22.46 billion in 2024 and will reach USD 82.47 billion by 2032 at a 17.66% CAGR, driven by rising global adoption of connected lighting systems.
- Demand grows as LED-based hardware, which holds a 62% segment share, supports energy savings and automation across homes, offices, and industrial spaces.
- Trends include rapid adoption of wireless lighting, expansion of AI-enabled controls, and increasing use of IoT sensors for adaptive brightness, occupancy response, and real-time monitoring.
- Competition intensifies as top players enhance IoT platforms, upgrade smart fixtures, and introduce human-centric lighting while focusing on efficiency, interoperability, and cybersecurity.
- Regionally, North America leads with 37%, Europe follows with 29%, Asia-Pacific holds 26%, while Latin America accounts for 5% and the Middle East & Africa for 3%, supported by smart city programs and rising LED penetration.
Market Segmentation Analysis:
By Component
Hardware leads this segment with a 62% market share, driven by wide adoption of smart bulbs, luminaires, sensors, and control systems across residential and commercial environments. Growth accelerates as LED-based smart fixtures replace traditional lighting to reduce energy consumption and improve automation. Motion sensors, dimmers, and smart switches play a key role in enhancing building efficiency and user comfort. Software platforms grow steadily as cloud-based lighting control and analytics tools gain importance. Services expand with rising demand for installation, maintenance, and smart building integration support.
- For instance, Signify’s Interact system supports control of up to 10,000 connected luminaires in a single facility, and the platform processes more than 25 million device interactions each day.
By Connectivity
Wireless connectivity dominates this segment with a 68% market share, supported by the rapid expansion of Wi-Fi, Bluetooth, Zigbee, and Z-Wave–enabled lighting systems. Users prefer wireless solutions because they reduce installation complexity and support flexible control through mobile apps and voice assistants. Smart homes, retrofit projects, and commercial spaces use wireless systems to enable remote control, automated scheduling, and energy monitoring. Wired solutions retain demand in large industrial sites and infrastructure projects for enhanced reliability and security, though wireless continues to gain momentum globally.
- For instance, Lutron’s Caséta Wireless platform supports up to 75 connected devices per bridge and handles response times under 0.3 seconds for remote commands, enabling smooth control across diverse home setups.
By Application
Indoor applications hold a 71% market share, driven by strong adoption in homes, offices, retail spaces, hotels, and industrial facilities. Users install smart lights to optimize ambiance, improve productivity, and reduce electricity costs through automation and occupancy sensing. Corporate spaces invest in smart lighting to support wellness-focused work environments and energy compliance standards. Outdoor applications grow through smart streetlighting, parking lots, stadiums, and public infrastructure projects. Municipalities deploy sensor-based lighting to improve safety, reduce operational expenses, and support broader smart city initiatives.

Key Growth Drivers
Rising Adoption of Energy-Efficient LED and Automated Lighting Systems
The shift toward energy-efficient LED lighting and automated control systems drives strong growth in the Smart Lighting market. LEDs consume less power and last longer, making them ideal for homes, offices, and industrial facilities. Automated dimming, occupancy sensing, and daylight harvesting features further reduce energy waste. Governments support LED adoption through incentive programs and energy regulations. Businesses invest in smart lighting to cut operational costs and meet sustainability goals. Growing awareness of long-term savings continues to accelerate the transition from traditional lighting to connected, intelligent systems.
- For instance, Current (formerly GE Current, a Daintree company) lighting systems include LED lamps rated for up to 70,000 hours and connected fixtures that support system-wide automation with gateways capable of supporting over 500 nodes within a single commercial mesh network, enabling precise control and reduced maintenance cycles.
Expansion of Smart Homes and Connected Building Technologies
Smart home adoption expands rapidly as consumers embrace voice-controlled lighting, mobile app management, and personalized automation. Connected building technologies also rise in commercial settings, where smart lighting integrates with HVAC, security, and IoT platforms. These systems improve comfort, productivity, and energy optimization. Builders and facility managers prefer centralized lighting control to streamline maintenance and monitor usage patterns. Growth in smart speakers, hubs, and wireless protocols strengthens integration, making smart lighting a key component of modern connected environments across residential and enterprise spaces.
- For instance, Legrand’s Home + Control platform manages up to 120 connected lighting and IoT devices per installation and supports response times under 250 milliseconds, enabling smooth integration with building automation and voice-assistant ecosystems.
Increasing Deployment Across Smart City and Infrastructure Projects
Smart city initiatives drive large-scale deployment of intelligent outdoor lighting systems for streets, parks, and public infrastructure. These solutions use sensors, adaptive brightness, and remote monitoring to enhance safety and reduce electricity consumption. Municipalities adopt networked lighting to support traffic management, environmental monitoring, and surveillance systems. Long-term cost savings from predictive maintenance encourage governments to replace legacy lighting with smart, IoT-enabled models. Growing investments in urban modernization and smart infrastructure continue to strengthen demand worldwide.
Key Trends & Opportunities
Growing Integration of AI, IoT, and Sensor-Based Lighting Control
AI and IoT integration strengthens smart lighting capabilities through real-time analytics, automated adjustments, and improved personalization. Sensors track occupancy, daylight levels, and environmental conditions to optimize brightness and energy use. AI-driven platforms help users predict maintenance needs and analyze consumption patterns. These technologies create opportunities for advanced lighting ecosystems across offices, commercial buildings, and industrial sites. As more devices connect to cloud platforms, demand rises for intelligent, scalable lighting systems that improve convenience and operational efficiency.
- For instance, Siemens’ Enlighted IoT lighting platform manages data from over 4.6 million deployed sensors and executes automated lighting adjustments with response times below 200 milliseconds, enabling precise control across large commercial buildings.
Rising Demand for Human-Centric and Wellness-Oriented Lighting Solutions
Human-centric lighting gains momentum as consumers and employers focus on wellness, productivity, and comfort. Tunable white and circadian lighting systems adjust color temperature to align with natural rhythms. Corporate offices, hospitals, and educational institutions adopt these systems to enhance mood, focus, and sleep quality. Hospitality and retail sectors use dynamic lighting to improve customer experience. This shift creates strong opportunities for advanced LED technologies, smart controls, and personalized lighting environments tailored to human biological needs.
- For instance, Zumtobel’s Tunable White technology offers a controllable range from 2,700K to 6,500K and supports real-time adjustments across lighting zones with up to 250 fixtures per DALI line, enabling precise circadian lighting in professional environments.
Key Challenges
High Initial Installation and Upgrade Costs
Smart lighting systems require higher upfront investment due to advanced hardware, control modules, and integration needs. Many residential users and small businesses hesitate to adopt these solutions because of cost barriers. Retrofitting older buildings increases expenses, especially when involving sensors and automation components. Despite long-term savings, budget constraints slow adoption in price-sensitive regions. Manufacturers and service providers must offer scalable, cost-effective solutions to expand market penetration.
Data Privacy, Cybersecurity Risks, and Integration Complexity
Smart lighting systems connected to networks and cloud platforms face cybersecurity risks, including unauthorized access or system manipulation. Users also express concerns about data collection from sensors that monitor occupancy and movement. Integration challenges arise when combining lighting with IoT devices, building management systems, and multiple wireless protocols. Compatibility issues lead to higher installation time and maintenance complexity. Ensuring secure communication, standardized protocols, and seamless integration remains essential to maintaining user trust and supporting broader adoption.
Regional Analysis
North America
North America holds a 37% market share, driven by strong adoption of smart home technologies, advanced LED systems, and connected building solutions. Residential users widely adopt smart bulbs, wireless controls, and voice-activated lighting. Commercial spaces deploy automated lighting for energy savings and regulatory compliance. The region benefits from mature IoT infrastructure and high spending on smart cities. Large enterprises integrate AI-enabled lighting to optimize workspace efficiency, while municipalities modernize streetlighting to reduce maintenance costs. Continuous product innovation by leading manufacturers strengthens regional growth across homes, offices, and public infrastructure.
Europe
Europe accounts for a 29% market share, supported by strict energy-efficiency regulations and widespread LED adoption across commercial and industrial buildings. The region’s sustainability goals encourage rapid transition to smart, sensor-based lighting systems. Smart streetlighting expands as cities upgrade public infrastructure to lower emissions and improve safety. Residential adoption increases with rising demand for automated indoor lighting and connected home controls. Strong government incentives and advanced building standards accelerate integration of intelligent lighting across Germany, the U.K., France, and the Nordics, reinforcing Europe’s position as a key technology adopter.
Asia-Pacific
Asia-Pacific holds a 26% market share, fueled by rapid urbanization, expanding construction activity, and strong government support for smart city development. Growing smart home adoption in China, Japan, South Korea, and India drives indoor lighting installations. Commercial buildings implement automated lighting to manage rising energy costs. Expanding manufacturing capabilities improve availability of affordable smart lighting products across the region. Investments in public infrastructure, stadiums, transportation hubs, and outdoor lighting strengthen overall demand. Rising consumer awareness and increased digitalization continue to support long-term market growth.
Latin America
Latin America captures a 5% market share, driven by increasing adoption of energy-efficient lighting and gradual expansion of smart home technologies. Commercial buildings and retail spaces upgrade to automated lighting to reduce operational costs. Urban centers introduce pilot smart city and smart streetlighting projects, particularly in Brazil, Mexico, and Chile. Economic constraints slow large-scale implementation, yet demand rises steadily as LED penetration increases. Growing awareness of sustainability and rising utility costs encourage businesses and households to shift toward connected lighting solutions.
Middle East & Africa
The Middle East & Africa hold a 3% market share, supported by ongoing smart city projects, high-end residential development, and modernization of public infrastructure. The UAE and Saudi Arabia lead adoption with strong investments in intelligent streetlighting, luxury smart homes, and energy-efficient commercial buildings. Africa sees rising demand in urban regions where LED retrofitting and basic smart lighting systems gain traction. Despite limited affordability in some areas, government initiatives for energy conservation and digital transformation continue to drive gradual market expansion.
Market Segmentations:
By Component
- Hardware
- Software
- Services
By Connectivity
- Wired
- Wireless
By Application
- Indoor
- Outdoor
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the Smart Lighting market highlights major players such as Signify (Philips Lighting), Osram Licht AG, GE Lighting, Acuity Brands, Cree Lighting, Hubbell Incorporated, Lutron Electronics, Zumtobel Group, Legrand, and Helvar Systems. These companies compete by offering advanced LED fixtures, connected lighting platforms, wireless control systems, and sensor-based automation solutions. Manufacturers focus on integrating IoT, AI-driven analytics, and cloud-based lighting management to enhance energy efficiency and user experience. Product development centers on tunable lighting, human-centric solutions, and interoperable control protocols. Strategic partnerships with building automation firms, smart home specialists, and city infrastructure authorities help expand market reach. Vendors also increase investment in R&D to improve performance, reduce power consumption, and strengthen cybersecurity across connected lighting systems. As competition intensifies, companies prioritize scalability, cost-efficiency, and seamless integration to meet rising demand across residential, commercial, industrial, and outdoor lighting applications.
Key Player Analysis
- Signify (Philips Lighting)
- Osram Licht AG
- GE Lighting
- Acuity Brands
- Cree Lighting
- Hubbell Incorporated
- Lutron Electronics
- Zumtobel Group
- Legrand
- Helvar Systems
Recent Developments
- In August 2025, Acuity Brands, Inc. reported that nine of its lighting solutions were selected for the 2025 Illuminating Engineering Society Progress Report.
- In January 2025, GE Lighting (via its parent/smart-home partner) launched new Matter-compatible smart switches under its Cync™ brand at CES 2025, enhancing cross-platform smart-home compatibility.
- In December 2024, ams OSRAM AG (formerly OSRAM Licht AG) announced a cooperation with Valeo to integrate its intelligent LED (EVIYOS™) lighting into vehicle interior ambient-lighting systems.
Report Coverage
The research report offers an in-depth analysis based on Component, Connectivity, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Smart homes will accelerate demand for wireless lighting controls and automated fixtures.
- AI-driven lighting optimization will improve energy savings and enhance user personalization.
- Human-centric and circadian lighting will gain wider adoption in workplaces and healthcare.
- Smart streetlighting will expand as cities invest in intelligent infrastructure upgrades.
- Integration with IoT platforms will strengthen building automation and predictive maintenance.
- Voice control and app-based lighting management will become standard features for consumers.
- Hybrid and adaptive lighting systems will support sustainability and stricter energy regulations.
- Sensor-based outdoor lighting will improve safety and reduce operational costs for municipalities.
- Interoperability across lighting ecosystems will improve through unified protocols and open platforms.
- Manufacturers will invest more in cybersecurity to protect connected lighting networks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Smart Lighting market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Smart Lighting market projected to grow between 2025 and 2032?
Which Smart Lighting market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Smart Lighting market?
Who are the leading companies in the Smart Lighting market?
Which region commanded the largest share of the Smart Lighting market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Smart Lighting Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Smart Lighting Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 22.46 billion → 2032: USD 82.47 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Smart Lighting Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Smart Lighting Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Smart Lighting Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Smart Lighting Market Drivers
- 3.3 Smart Lighting Market Restraints & Challenges
- 3.4 Smart Lighting Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Smart Lighting Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Smart Lighting Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Smart Lighting category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Smart Lighting Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Smart Lighting Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Smart Lighting market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Smart Lighting Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Smart Lighting Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Smart Lighting Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Smart Lighting (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Smart Lighting Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Smart Lighting Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Smart Lighting Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Smart Lighting Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Smart Lighting Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Smart Lighting Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Smart Lighting Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Smart Lighting Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Smart Lighting Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
