
Peripheral Intervention Market Overview:
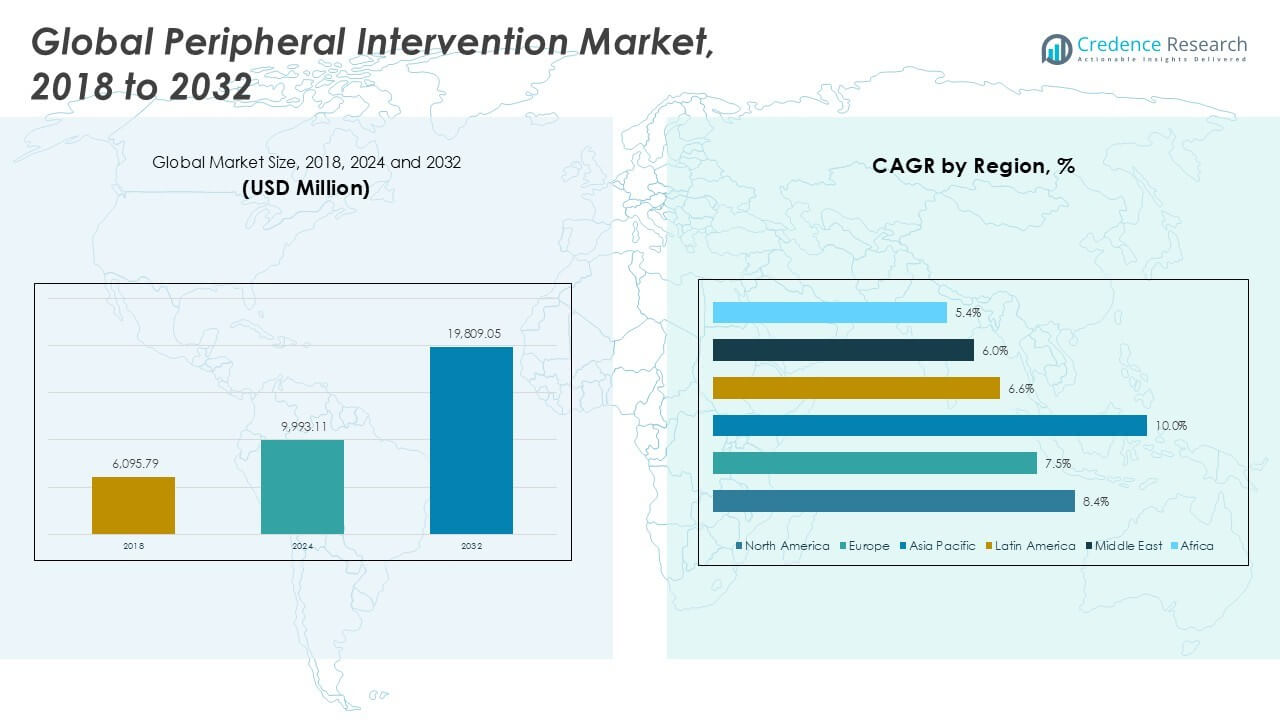
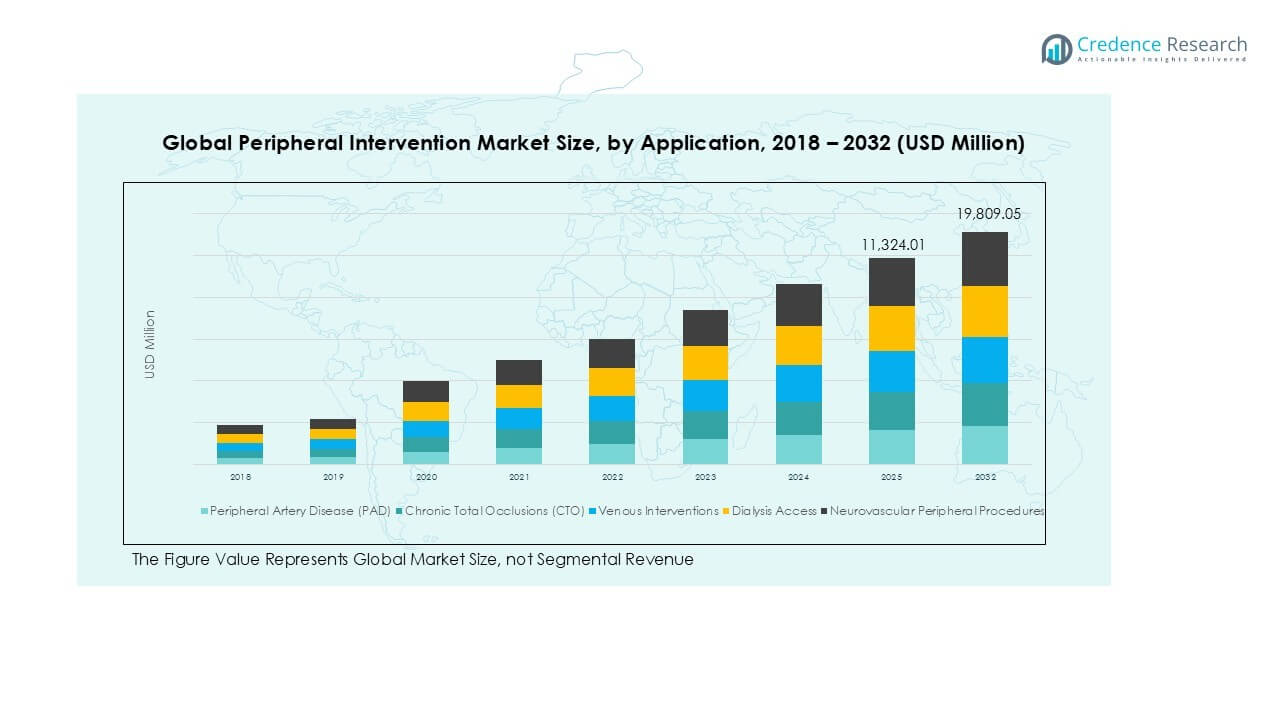
The Peripheral Intervention Market size was valued at USD 6,095.79 million in 2018 to USD 9,993.11 million in 2024 and is anticipated to reach USD 19,809.05 million by 2032, at a CAGR of 8.32% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Peripheral Intervention Market Size 2024 | USD 10,349.94 million |
| Peripheral Intervention Market, CAGR | 5.24% |
| Peripheral Intervention Market Size 2032 | USD 16,037.42 million |
Top players in the Peripheral Intervention market include Medtronic, Boston Scientific, Abbott Vascular, Terumo Corporation, and BD (Becton, Dickinson & Company). These companies dominate due to their broad product portfolios, strong global distribution networks, and continuous innovation in drug-coated and image-guided intervention technologies. Medtronic and Boston Scientific hold significant shares in angioplasty balloons and stents, while Abbott leads in guidewire and catheter technologies. Terumo and BD maintain strong positions in access and closure devices. North America remains the leading region, accounting for 43.5% of the global market in 2024, driven by advanced healthcare infrastructure, high procedure volumes, and favorable reimbursement policies. Asia Pacific, while still emerging, is the fastest-growing region due to rising PAD cases and healthcare investments. Competitive intensity remains high as companies expand into outpatient care and broaden clinical applications across arterial, venous, and dialysis access interventions.
Peripheral Intervention Market Insights
- The Peripheral Intervention Market was valued at USD 6,095.79 million in 2018, reached USD 9,993.11 million in 2024, and is expected to hit USD 19,809.05 million by 2032, growing at a CAGR of 8.32%.
- Growing cases of Peripheral Artery Disease (PAD), diabetes, and aging populations are driving demand for minimally invasive vascular procedures globally.
- Drug-coated balloons and stents are gaining traction as top product trends due to better restenosis prevention and improved patient outcomes.
- Medtronic, Boston Scientific, Abbott Vascular, Terumo, and BD dominate the market with wide product portfolios and global reach, while competition increases from regional players in Asia.
- North America leads with 43.5% share in 2024, followed by Europe at 26.4%, while Asia Pacific is the fastest-growing region; PAD remains the top application, and hospitals dominate the end-user segment.
Peripheral Intervention Market Segmentation Analysis:
By Product Type:
Angioplasty balloons lead the Peripheral Intervention market, with drug-coated balloons holding the largest share due to superior efficacy in preventing restenosis. These devices deliver localized drug therapy during the procedure, reducing the need for repeat interventions. Drug-eluting stents also capture significant market share under the stents segment, offering long-term vessel patency. Diagnostic and guiding catheters support precise delivery of therapy, driving demand in complex procedures. Guidewires, atherectomy, and thrombectomy devices show steady growth as physicians adopt advanced tools for lesion crossing and plaque removal. Accessories like closure devices enhance procedural safety and efficiency.
- For instance, Boston Scientific markets the Ranger drug-coated balloon, which delivers a paclitaxel dose density of 2 micrograms per square millimeter and uses a TransPax coating designed for controlled drug transfer during inflation.
By Application:
Peripheral Artery Disease (PAD) represents the largest application segment, driven by rising prevalence of diabetes, smoking, and aging populations. PAD procedures account for the majority of peripheral interventions due to high incidence of lower limb ischemia. Chronic Total Occlusions (CTO) follow as clinicians adopt new techniques and devices for complex vascular blockages. Venous interventions are gaining momentum, particularly for treating deep vein thrombosis. Dialysis access interventions remain vital for end-stage renal disease patients. Neurovascular peripheral procedures are niche but expanding due to innovation in minimally invasive stroke and aneurysm treatments.
- For instance, Medtronic supports PAD and CTO treatment using its HawkOne and TurboHawk directional atherectomy systems. These devices utilize internal blades that rotate at speeds up to 12,000 RPM to shave away and remove various plaque morphologies, including severely calcified lesions.
By End User:
Hospitals dominate the market with the highest share, supported by high patient volume, advanced infrastructure, and availability of skilled interventional radiologists and vascular surgeons. Most complex and emergency procedures take place in hospital settings, ensuring strong adoption of high-value devices. Ambulatory Surgical Centers (ASCs) show fast growth as cost-effective alternatives for outpatient vascular procedures. Their appeal lies in reduced hospitalization costs and quicker recovery. Specialty cardiology and vascular clinics contribute to market expansion by offering focused expertise and long-term patient monitoring, particularly for PAD and venous disorders in high-prevalence regions.
Peripheral Intervention Market Key Growth Drivers
Rising Prevalence of Peripheral Artery Disease (PAD)
The increasing global burden of PAD is a primary driver of the peripheral intervention market. With aging populations and the rising incidence of diabetes and smoking, PAD has become a widespread health concern. This condition affects blood flow in the limbs and requires timely intervention to prevent complications like limb ischemia and amputation. Healthcare providers increasingly rely on angioplasty balloons, stents, and atherectomy devices to restore circulation. Early screening initiatives and improved patient awareness also contribute to higher diagnosis rates, leading to more procedures. The growing need for minimally invasive interventions for PAD continues to expand the market significantly.
- For instance, Medtronic reported that its peripheral intervention portfolio supports treatment of millions of PAD patients globally each year, with devices like the IN.PACT Admiral drug-coated balloon used in large-scale clinical programs involving several thousand treated femoropopliteal lesions across real-world registries.
Advancements in Minimally Invasive Technology
Technological innovation is reshaping the peripheral intervention landscape. The shift from open surgery to catheter-based, image-guided interventions has improved clinical outcomes, shortened recovery times, and reduced procedural risks. Devices such as drug-coated balloons, drug-eluting stents, and precision-guided atherectomy tools enable effective treatment with fewer complications. Improvements in imaging technologies and real-time navigation support more complex procedures in outpatient settings. These advancements appeal to both patients and providers, driving higher adoption across hospitals, ASCs, and specialty clinics. As new generations of devices enter the market, procedural success rates and physician confidence continue to grow.
- For instance, Medtronic advanced minimally invasive PAD care through its IN.PACT drug-coated balloon platform, which has been used in more than 150,000 clinical cases worldwide.
Growth of Ambulatory Surgical Centers (ASCs)
The rise of ASCs as preferred treatment settings boosts the demand for peripheral intervention devices. These centers offer cost-effective, same-day procedures with lower infection risks and reduced hospital resource strain. Increasing payer support for outpatient vascular procedures—especially for PAD, CTO, and dialysis access—is accelerating this shift. ASCs typically favor compact, advanced tools that enable quick recovery and high throughput. Device manufacturers are developing tailored product lines for outpatient workflows, further supporting adoption. The rapid expansion of ASC networks across North America and parts of Europe and Asia contributes to consistent growth in device volumes and market penetration.
Peripheral Intervention Market Key Trends & Opportunities
Increasing Use of Drug-Coated Technologies
Drug-coated technologies, particularly balloons and stents, are seeing strong growth due to superior clinical outcomes. These devices reduce restenosis rates by delivering antiproliferative drugs directly to arterial walls during intervention. Physicians prefer these over traditional options, especially for treating long or complex lesions in peripheral arteries. Continuous R&D in drug-delivery mechanisms, polymer coatings, and biocompatibility is creating opportunities for premium-priced solutions. Regulatory approvals for next-gen devices are expanding market access in emerging economies. As more clinical trials confirm efficacy and safety, drug-coated devices will continue to replace standard options across key application segments.
- For instance, Becton, Dickinson and Company commercializes the Lutonix drug-coated balloon, which delivers paclitaxel at a dose density of 2 micrograms per square millimeter using a polysorbate and sorbitol coating matrix.
Expanding Applications Beyond PAD
Although PAD dominates, new application areas are unlocking future growth potential. Interventions for venous thromboembolism (VTE), neurovascular disorders, and dialysis access management are gaining traction. For example, thrombectomy and embolic protection devices are being deployed in both deep vein and cerebral vessel interventions. Dialysis access maintenance is vital for chronic kidney disease patients, and minimally invasive approaches offer repeatable, low-risk solutions. These emerging segments create demand for differentiated devices and offer vendors opportunities to expand portfolios. As clinical evidence grows and reimbursement frameworks improve, non-PAD applications will contribute meaningfully to the overall market.
Peripheral Intervention Market Key Challenges
Regulatory Hurdles and Reimbursement Gaps
Stringent regulatory pathways and inconsistent reimbursement policies remain key barriers. Approvals for new devices often require extensive clinical trials and documentation, which increases time to market and costs. In some regions, reimbursement frameworks lag behind innovation, limiting access to advanced devices. Smaller players may struggle with the financial burden of compliance, leading to limited product diversity. Reimbursement variations across countries, and even within healthcare systems, create uncertainty for hospitals and ASCs when selecting devices. These factors slow down the adoption of cutting-edge solutions and hinder market expansion, especially in price-sensitive regions.
Procedural Complexity and Operator Dependency
Despite improvements, many peripheral interventions remain technically challenging. Treating chronic total occlusions, calcified lesions, or neurovascular cases demands high operator skill and experience. Procedural success rates can vary widely based on physician proficiency, affecting patient outcomes and confidence in the technology. Training requirements, device familiarity, and steep learning curves limit widespread adoption, particularly in low-resource settings. Without standardized protocols and extensive support, newer or rural facilities may hesitate to invest in advanced tools. This gap in procedural consistency creates uneven market growth and reduces overall procedural volumes in certain areas.
Peripheral Intervention Market Regional Analysis
North America
North America leads the Peripheral Intervention market, accounting for the highest regional share of 43.5% in 2024, with market size rising from USD 2,696.41 million in 2018 to USD 4,375.03 million in 2024, and projected to reach USD 8,696.27 million by 2032, growing at a CAGR of 8.4%. The dominance stems from advanced healthcare infrastructure, high adoption of minimally invasive procedures, and strong presence of leading device manufacturers. Favorable reimbursement frameworks and increased PAD prevalence among the aging population also drive demand. The U.S. continues to dominate regional growth with aggressive investment in vascular care technologies.
Europe
Europe holds the second-largest market share at 26.4% in 2024, with revenue growing from USD 1,673.66 million in 2018 to USD 2,641.50 million in 2024, and forecasted to reach USD 4,919.23 million by 2032 at a CAGR of 7.5%. Rising PAD cases, widespread use of drug-coated technologies, and government-funded screening programs are key contributors. Germany, France, and the UK are the leading countries due to strong clinical expertise and infrastructure. The region benefits from early adoption of atherectomy and thrombectomy devices, while increased awareness and training support continued procedural growth.
Asia Pacific
Asia Pacific is the fastest-growing region with a CAGR of 10.0%, expanding from USD 1,172.50 million in 2018 to USD 2,083.36 million in 2024, and projected to reach USD 4,677.31 million by 2032, holding a 20.8% share in 2024. Rapid urbanization, rising healthcare expenditure, and growing diabetic and aging populations fuel growth. China, Japan, and India lead regional demand, supported by increasing availability of interventional radiology services. As governments strengthen non-communicable disease programs and expand access to vascular care, more patients are undergoing endovascular treatments, boosting device sales and infrastructure development across the region.
Latin America
Latin America holds a 4.6% share in 2024, with market size increasing from USD 282.51 million in 2018 to USD 457.26 million in 2024, and estimated to reach USD 800.24 million by 2032, growing at a CAGR of 6.6%. Brazil and Mexico dominate regional growth, driven by rising vascular disease burden and investments in public healthcare systems. Awareness about minimally invasive treatment options is growing, supported by training programs and expanding clinical capacity. However, slower regulatory approvals and limited reimbursement coverage in several countries still pose moderate challenges to wider adoption of advanced interventional technologies.
Middle East
The Middle East accounts for 2.6% of the market in 2024, rising from USD 171.43 million in 2018 to USD 256.99 million in 2024, and expected to reach USD 430.19 million by 2032, reflecting a CAGR of 6.0%. Growth is led by the UAE and Saudi Arabia, where modernization of healthcare infrastructure and increased investments in cardiovascular care are prominent. Rising rates of diabetes and obesity contribute to growing demand for peripheral procedures. Efforts by regional governments to expand tertiary care services and attract global medtech providers further boost the market, particularly in high-income urban centers.
Africa
Africa captures a 2.1% market share in 2024, with revenue growing from USD 99.28 million in 2018 to USD 178.95 million in 2024, and forecasted to reach USD 285.80 million by 2032, at a CAGR of 5.4%. The market is gradually expanding due to increasing awareness of PAD and availability of basic interventional procedures in urban hospitals. South Africa and Egypt lead device adoption due to better access to healthcare infrastructure. However, limited reimbursement, insufficient trained personnel, and constrained hospital budgets slow advanced device penetration. International collaborations and public-private partnerships are crucial for future growth.
Peripheral Intervention Market Segmentations:
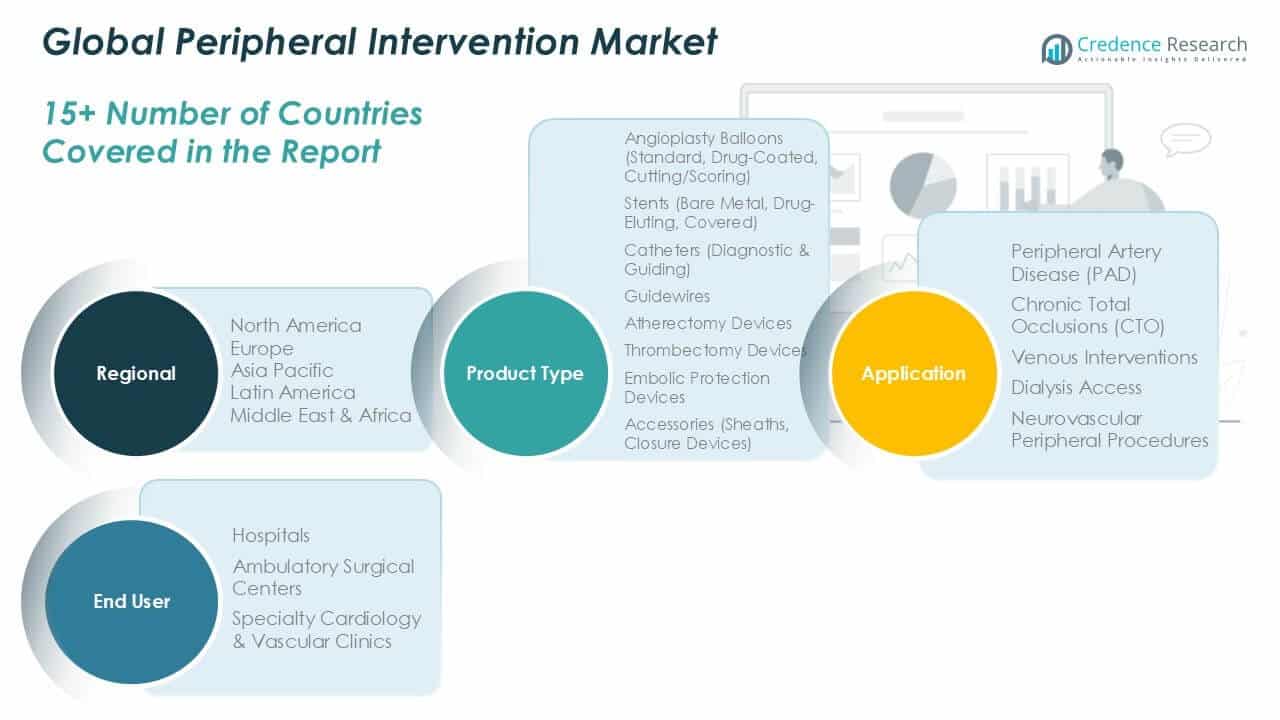
By Product Type:
- Angioplasty Balloons
- Standard
- Drug-Coated
- Cutting/Scoring
- Stents
- Bare Metal
- Drug-Eluting
- Covered
- Catheters
- Diagnostic
- Guiding
- Guidewires
- Atherectomy Devices
- Thrombectomy Devices
- Embolic Protection Devices
- Accessories
- Sheaths
- Closure Devices
By Application:
- Peripheral Artery Disease (PAD)
- Chronic Total Occlusions (CTO)
- Venous Interventions
- Dialysis Access
- Neurovascular Peripheral Procedures
By End User:
- Hospitals
- Ambulatory Surgical Centers
- Specialty Cardiology & Vascular Clinics
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Peripheral Intervention market is defined by a strong presence of global medical device giants focused on innovation, portfolio expansion, and strategic collaborations. Companies like Medtronic, Boston Scientific, Abbott Vascular, Terumo Corporation, and BD lead the market with comprehensive product offerings across angioplasty balloons, stents, guidewires, and atherectomy devices. These players invest heavily in R&D to develop next-generation drug-coated technologies and image-guided systems. Mergers, acquisitions, and partnerships are commonly used to strengthen market positioning and expand geographic reach. For example, Medtronic focuses on digital vascular solutions, while Boston Scientific continues to enhance its peripheral drug-eluting platform. Emerging players target niche segments such as thrombectomy and neurovascular interventions to differentiate themselves. Regional manufacturers in Asia and Europe are also expanding due to lower-cost devices and regulatory approvals. Overall, competition remains high, driven by technological advancements, physician demand for improved outcomes, and pressure to deliver cost-effective, minimally invasive solutions globally.
Key Player Analysis
- Medtronic
- Boston Scientific
- Abbott Vascular
- Terumo Corporation
- BD (Becton, Dickinson & Company)
Recent Developments
- In October 2025, Medtronic launched Neuroguard IEP system. Neuroguard IEP system is carotid stent system designed for the medicals across North America.
- In September 2025, ASAHI INTECC launched velouté and tellus embolization microcatheters. These microcatheters are designed for the healthcare sector of the U.S.
- In March 2025, Shockwave Medical launched Javelin Peripheral IVL Catheter. It is an intravascular lithotripsy (IVL) device designed for treating PAD patients.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for minimally invasive procedures will continue to drive market growth across all regions.
- Drug-coated technologies will gain wider adoption due to improved long-term clinical outcomes.
- Hospitals will maintain dominance as the primary treatment centers for complex vascular interventions.
- Ambulatory surgical centers will expand faster due to cost-efficiency and rising outpatient procedures.
- Asia Pacific will emerge as a key growth hub with rising healthcare investments and aging populations.
- PAD will remain the leading application, supported by growing awareness and early diagnosis rates.
- Technological innovation in imaging and navigation systems will enhance procedural accuracy.
- Thrombectomy and atherectomy devices will see rising use in treating complex lesions.
- Strategic partnerships and acquisitions will intensify among major players to expand market share.
- Reimbursement and regulatory improvements will be critical to unlocking growth in emerging markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Peripheral Intervention market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Peripheral Intervention market projected to grow between 2024 and 2032?
Which Peripheral Intervention market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Peripheral Intervention market?
Who are the leading companies in the Peripheral Intervention market?
Which region commanded the largest share of the Peripheral Intervention market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Peripheral Intervention Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Peripheral Intervention Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,993.11 million → 2032: USD 19,809.05 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Peripheral Intervention Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Peripheral Intervention Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Peripheral Intervention Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Peripheral Intervention Market Drivers
- 3.3 Peripheral Intervention Market Restraints & Challenges
- 3.4 Peripheral Intervention Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Peripheral Intervention Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Peripheral Intervention Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Peripheral Intervention category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Peripheral Intervention Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Peripheral Intervention Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Peripheral Intervention market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Peripheral Intervention Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Peripheral Intervention Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Peripheral Intervention Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Peripheral Intervention (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Peripheral Intervention Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Peripheral Intervention Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Peripheral Intervention Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Peripheral Intervention Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Peripheral Intervention Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Peripheral Intervention Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Peripheral Intervention Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Peripheral Intervention Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Peripheral Intervention Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
