
Market Overview:
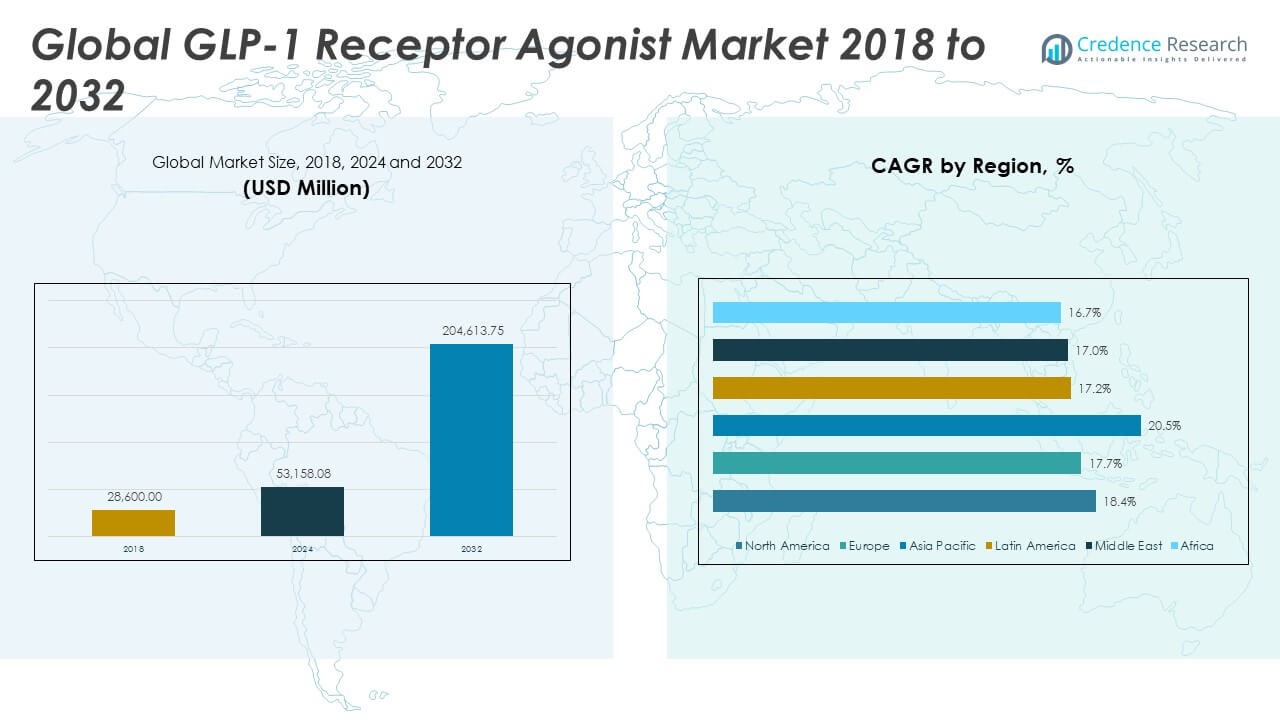
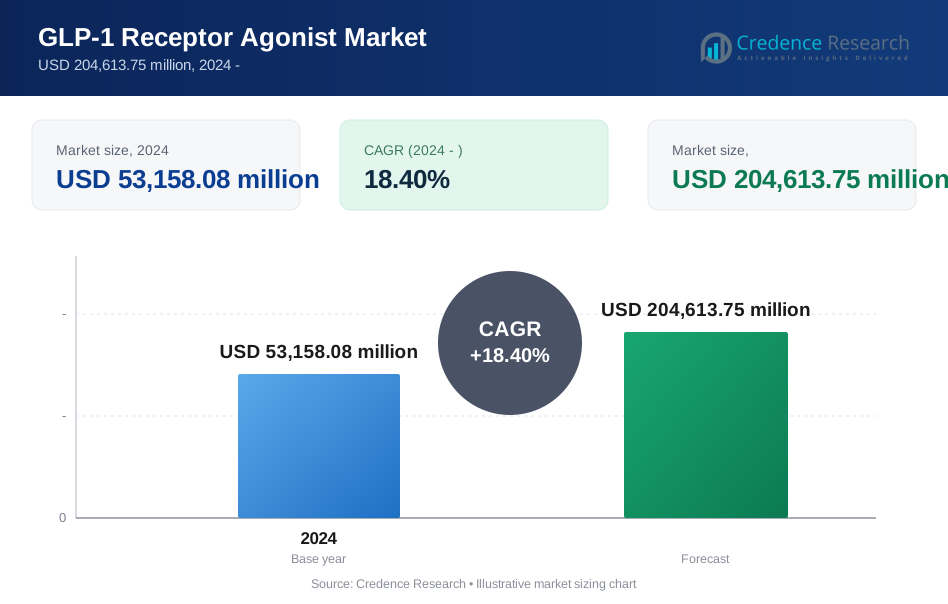
The GLP-1 Receptor Agonist Market size was valued at USD 28,600.00 million in 2018 to USD 53,158.08 million in 2024 and is anticipated to reach USD 2,04,613.75 million by 2032, at a CAGR of 18.40% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| GLP-1 Receptor Agonist Market Size 2024 | USD 53,158.08 Million |
| GLP-1 Receptor Agonist Market, CAGR | 18.40% |
| GLP-1 Receptor Agonist Market Size 2032 | USD 2,04,613.75 Million |
The market is witnessing significant growth driven by the rising prevalence of type 2 diabetes and obesity worldwide. Increasing awareness of advanced therapeutic options, growing demand for weight management drugs, and favorable clinical outcomes of GLP-1 receptor agonists over traditional treatments are accelerating adoption. Additionally, pharmaceutical companies are heavily investing in R&D for novel drug formulations, including oral and once-weekly injectables, which further supports market expansion.
North America dominates the GLP-1 receptor agonist market due to high healthcare expenditure, early access to innovative therapies, and strong presence of key pharmaceutical players. Europe follows with substantial adoption across major countries driven by robust reimbursement systems and aging population. Meanwhile, Asia Pacific is emerging as a high-growth region, particularly due to increasing diabetes burden in countries like China and India, improving healthcare infrastructure, and rising patient awareness.
Market Insights:
- The GLP-1 Receptor Agonist Market was valued at USD 53,158.08 million in 2024 and is projected to reach USD 2,04,613.75 million by 2032, growing at a CAGR of 18.40%.
- Rising global prevalence of type 2 diabetes and obesity continues to drive demand for GLP-1 receptor agonists with dual glycemic and weight management benefits.
- Innovations such as once-weekly injectables and oral formulations improve adherence and expand patient acceptance.
- High treatment costs and limited reimbursement access in low-income regions remain significant barriers to market penetration.
- North America holds the largest market share due to advanced healthcare infrastructure and early product adoption.
- Asia Pacific is the fastest-growing region, supported by expanding diabetic populations, rising healthcare awareness, and improved access to novel therapies.
- Regulatory approvals for new indications and favorable clinical outcomes in cardiovascular and metabolic conditions are broadening market scope.
Market Drivers:
Rising Global Burden of Type 2 Diabetes and Obesity Is Fueling Long-Term Demand for GLP-1 Therapies
The GLP-1 Receptor Agonist Market benefits significantly from the growing prevalence of type 2 diabetes and obesity worldwide. Increased sedentary lifestyles, unhealthy eating habits, and aging populations are key contributors to rising disease incidence. Healthcare systems are under pressure to adopt advanced therapeutics to manage these chronic conditions effectively. GLP-1 receptor agonists offer dual benefits of glycemic control and weight reduction, making them highly favorable among clinicians. Governments and public health bodies are actively promoting diabetes management awareness, encouraging earlier diagnosis and treatment. These trends support sustained demand for innovative GLP-1 therapies across diverse population groups. It is gaining traction not only among diabetics but also in overweight individuals seeking preventive care. Expanding patient populations will continue to anchor consistent market expansion.
Superior Clinical Outcomes and Cardiovascular Benefits Drive Physician and Payer Preference
GLP-1 receptor agonists have demonstrated compelling clinical evidence for improving glycemic control while reducing cardiovascular risk. Several leading products have received label expansions after demonstrating significant reduction in major adverse cardiovascular events in clinical trials. Physicians increasingly favor these agents over traditional oral antidiabetics due to their multi-faceted benefits. Payers are recognizing their long-term cost-saving potential by reducing complications and hospitalizations. These advantages are prompting healthcare systems to integrate GLP-1s into first-line or second-line therapy guidelines. Continuous product differentiation, such as extended-release versions and dual agonists, strengthens prescriber confidence. The GLP-1 Receptor Agonist Market is expected to grow as new trials continue to validate broader therapeutic benefits. It positions these therapies as cornerstone agents in modern diabetes care.
Strategic Investments by Pharmaceutical Leaders Are Expanding Therapeutic Innovation and Accessibility
Global pharmaceutical companies are committing significant resources to developing new GLP-1 receptor agonists with improved efficacy and convenience. Innovation is focused on long-acting injectables, oral formulations, and fixed-dose combinations. These advances are improving patient adherence and broadening applicability to various patient segments. Licensing deals, co-development partnerships, and technology acquisitions are accelerating innovation cycles. Companies are also expanding clinical pipelines to evaluate GLP-1s in indications beyond diabetes, such as NASH and cardiovascular conditions. The GLP-1 Receptor Agonist Market is evolving rapidly through these strategic moves. It fosters a competitive landscape that pushes pricing efficiencies and treatment personalization. Global access programs and tiered pricing strategies are further enhancing availability in emerging economies.
- For example, Nordisk’s $1.08 billion acquisition of Emisphere Technologies to secure oral delivery capabilities, and co-development agreements like the one between Pfizer and OPKO Health for oral GLP-1s, are accelerating innovation cycles and expanding access.
Regulatory Approvals and Inclusion in Treatment Guidelines Bolster Market Expansion
Regulatory bodies are playing a central role in accelerating the adoption of GLP-1 therapies by granting fast-track approvals and extended indications. Positive safety and efficacy data have led to wider inclusion of GLP-1 receptor agonists in national and international diabetes treatment guidelines. These endorsements influence prescribing behavior and facilitate payer reimbursement. Pharmaceutical companies are leveraging regulatory momentum to expand their market presence quickly across geographies. The GLP-1 Receptor Agonist Market is benefiting from regulatory alignment in major regions including the U.S., EU, and parts of Asia. It enables faster market entry and lowers commercialization risks. Regulatory clarity is also encouraging R&D investments and fostering innovation in delivery formats and dosing regimens.
- For example, in 2023, the FDA approved Wegovy® (semaglutide) for chronic weight management in adults with BMI ≥30 kg/m² or ≥27 kg/m² with comorbidities, based on robust data from the STEP trials showing up to 17.4% mean weight loss from baseline over 68 weeks.
Market Trends
Growing Use of GLP-1 Therapies in Weight Management Beyond Diabetic Indications
The GLP-1 Receptor Agonist Market is increasingly influenced by the expansion of these therapies into obesity management. Originally developed for glycemic control in type 2 diabetes, GLP-1 receptor agonists are now prescribed for weight loss in non-diabetic populations. Clinical success stories and celebrity endorsements have raised public awareness, boosting off-label demand. The FDA approval of agents like semaglutide for chronic weight management has opened new market segments. Insurers and healthcare providers are starting to acknowledge the broader health benefits of weight loss, supporting reimbursement frameworks. Pharmaceutical companies are rebranding GLP-1 therapies for dual purposes, targeting lifestyle-driven consumer segments. It reflects the market's shift toward holistic metabolic health solutions. These changes are reshaping sales strategies and expanding marketing efforts globally.
Technological Innovations in Drug Delivery Are Transforming the Patient Experience
Technological advancements in formulation and drug delivery are redefining user experience for GLP-1 therapies. Companies are introducing once-weekly, auto-injector pens and even oral tablets to increase patient compliance. Innovations in polymer-based release systems and biodegradable carriers are supporting extended drug activity with fewer side effects. The GLP-1 Receptor Agonist Market is responding to patient demand for simpler, less invasive options. It is also leveraging connected devices and mobile apps to support adherence and remote monitoring. These technology-driven developments are especially important in managing chronic conditions over long durations. Pharma companies are using human-centered design and feedback loops to tailor these advancements to patient needs. It promotes differentiation in a crowded market and supports sustained brand loyalty.
Pipeline Expansion into Cardiovascular and Liver Diseases Signals Market Diversification
Beyond diabetes and obesity, researchers are actively evaluating GLP-1 receptor agonists in other metabolic and cardiovascular conditions. Early trials have shown promise in non-alcoholic steatohepatitis (NASH), heart failure, and atherosclerosis. Leading players are investing in multi-arm clinical studies to explore these applications. It is creating new revenue pathways and therapeutic categories for the GLP-1 Receptor Agonist Market. Strategic focus on comorbidity management positions GLP-1s as comprehensive metabolic disease agents. These developments are attracting attention from cardiologists and hepatologists, expanding prescriber base. Market stakeholders are aligning R&D objectives with long-term disease burden projections. It prepares the market for future reimbursement negotiations and value-based care models.
- For example, Novo Nordisk’s SELECT trial (NCT03574597) found that semaglutide 2.4 mg reduced incidence of major adverse cardiovascular events by 20% (HR 0.80, 95% CI: 0.72–0.90, p<0.001) in 17,604 non-diabetic overweight/obese adults.
Retail and Direct-to-Consumer Models Are Reshaping Access Channels and Brand Positioning
The increasing presence of GLP-1 therapies in retail and e-pharmacy channels is transforming distribution models. Startups and health tech firms are entering the market with telehealth services offering GLP-1 prescriptions online. These direct-to-consumer platforms are simplifying patient access while promoting personalized support. The GLP-1 Receptor Agonist Market is experiencing a blending of traditional pharma with digital-first strategies. It expands market penetration among younger, tech-savvy populations seeking discreet treatment options. Companies are also building brand equity through targeted online campaigns, subscription models, and patient communities. This trend reduces dependency on hospital-centric care and strengthens customer engagement. Regulatory bodies are monitoring these models, prompting companies to maintain high compliance and safety standards.
- For example, Amazon Pharmacy added Wegovy and Zepbound to its service in Q1 2024, streamlining fulfillment, and CVS Health launched a GLP-1 weight management program for employer groups.
Market Challenges
High Cost of Treatment Limits Adoption Across Lower-Income Populations and Health Systems
Despite clinical efficacy, the high cost of GLP-1 therapies remains a significant barrier to widespread adoption. These treatments are substantially more expensive than conventional oral antidiabetics, limiting affordability for uninsured and underinsured patients. Many public health systems in low- and middle-income countries face budget constraints, making broad reimbursement unfeasible. Employers and private insurers are cautious about long-term coverage due to cumulative costs in chronic care. The GLP-1 Receptor Agonist Market faces scrutiny from policymakers pushing for pricing transparency and value-based care. It also struggles with inconsistent insurance coverage across regions, creating access disparities. Cost sensitivity influences treatment duration, adherence rates, and prescribing decisions. Companies must balance innovation with affordability to maintain growth in cost-sensitive markets.
Complex Administration Protocols and Gastrointestinal Side Effects Impair Adherence
While newer GLP-1 formulations aim to simplify dosing, many still require subcutaneous injections, deterring some patients. Injection aversion and lack of familiarity with delivery devices hinder initiation and long-term adherence. Gastrointestinal side effects like nausea, vomiting, and diarrhea are common, especially during dose escalation. These adverse effects often lead to early discontinuation or demand for supportive medications. The GLP-1 Receptor Agonist Market faces clinical challenges in optimizing dosing protocols and minimizing dropout rates. It relies on strong provider-patient communication and educational tools to address concerns proactively. Despite formulation advances, user experience gaps remain. Solving these challenges is key to sustaining therapeutic benefits and maximizing health outcomes.
Market Opportunities
Expansion into Emerging Economies Through Local Partnerships and Tiered Pricing
The GLP-1 Receptor Agonist Market holds substantial growth potential in emerging economies with large diabetic populations. Companies can leverage local partnerships with distributors, hospitals, and government health programs to expand access. Tiered pricing strategies and public procurement initiatives can improve affordability. It allows global players to penetrate untapped geographies while contributing to public health objectives. Localization of manufacturing and packaging could also support cost control.
Development of Multi-Indication Products Targeting Broader Metabolic Disorders
There is growing opportunity to position GLP-1 therapies as multifunctional agents beyond glycemic control. Combining them with other metabolic drugs or targeting diseases like NASH, cardiovascular disease, or PCOS opens new clinical pathways. The GLP-1 Receptor Agonist Market can benefit by diversifying its product portfolio and reducing dependence on a single indication. It supports a more holistic approach to managing metabolic syndrome across patient populations.
Market Segmentation Analysis:
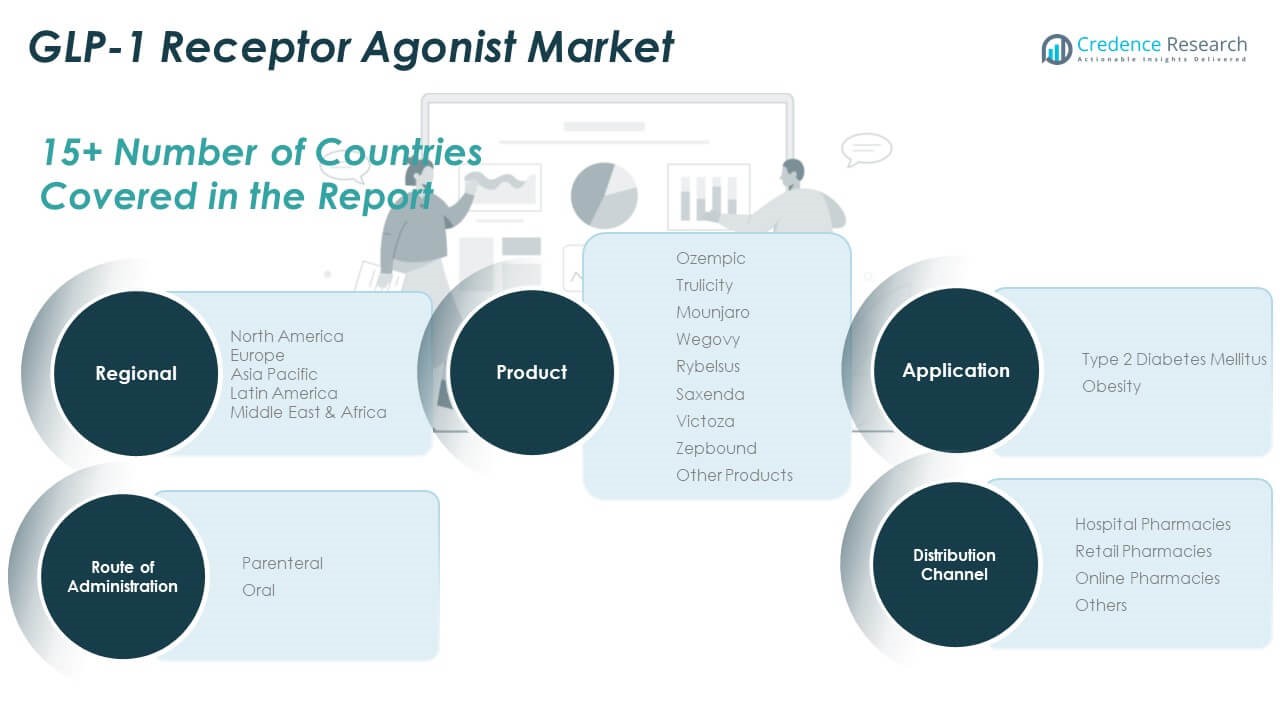
By Product, the GLP-1 Receptor Agonist Market features a diversified product landscape led by Ozempic, Trulicity, Mounjaro, and Wegovy, which collectively command a significant share due to proven efficacy in managing both glycemic levels and body weight. Rybelsus has gained traction as the first oral GLP-1 receptor agonist, while Victoza, Saxenda, and Zepbound continue to serve niche patient groups. Other products are emerging, supported by expanding clinical applications and pipeline approvals.
- For example, Mounjaro (tirzepatide)by Eli Lilly, though structurally a dual GIP/GLP-1 agonist, is classified within the GLP-1 class in major market reports, and reached $5.16 billion in sales in its first full year of launch.
By application, type 2 diabetes mellitus remains the dominant segment, driven by its global burden and strong clinical endorsement of GLP-1 therapies. The obesity segment is growing rapidly, with Wegovy and Mounjaro leading adoption due to their dual benefits and recent regulatory support.
- For instance, the American Diabetes Association Standards of Care 2024 recommend GLP-1 RAs as first-line for many T2DM populations, further reinforcing their dominant clinical role.
By Route of Administration, parenteral administration remains the standard due to widespread availability and physician preference, while oral formulations are gaining popularity for their convenience. It reflects changing patient needs and innovation in drug delivery.
By Distribution channels are led by hospital and retail pharmacies, which provide accessibility and physician-led guidance. Online pharmacies are expanding their role through direct-to-consumer models, while other channels support institutional demand and specialty clinics. The GLP-1 Receptor Agonist Market continues to evolve across all segments, aligning with shifting treatment paradigms and patient preferences.
Segmentation:
By Product
- Ozempic
- Trulicity
- Mounjaro
- Wegovy
- Rybelsus
- Saxenda
- Victoza
- Zepbound
- Other Products
By Application
- Type 2 Diabetes Mellitus
- Obesity
By Route of Administration
- Parenteral
- Oral
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America GLP-1 Receptor Agonist Market size was valued at USD 11,474.32 million in 2018 to USD 21,092.81 million in 2024 and is anticipated to reach USD 81,088.80 million by 2032, at a CAGR of 18.4% during the forecast period. North America holds the largest regional market share of 39.62%. It leads due to a well-established healthcare infrastructure, high awareness levels, and favorable reimbursement frameworks. The U.S. drives the region’s dominance through early adoption of novel therapies and strong pharmaceutical innovation. Frequent product launches and FDA approvals have supported market expansion. Insurers in the region increasingly recognize the cost-effectiveness of GLP-1 therapies in preventing long-term diabetes complications. High obesity and type 2 diabetes prevalence further fuel market growth. Patient access to advanced drug delivery technologies also supports adherence and uptake. It remains a key region for clinical trials and regulatory innovations.
Europe
The Europe GLP-1 Receptor Agonist Market size was valued at USD 8,740.16 million in 2018 to USD 15,701.44 million in 2024 and is anticipated to reach USD 57,568.62 million by 2032, at a CAGR of 17.7% during the forecast period. Europe accounts for a market share of 28.13%. The market benefits from structured national healthcare systems, which support broad access and reimbursement. Key countries including Germany, the UK, and France are witnessing increasing uptake of GLP-1 drugs. The presence of multiple global and regional pharmaceutical players accelerates competition and innovation. Government-led diabetes awareness programs and prevention strategies promote early diagnosis and therapy initiation. Clinical guidelines across Europe increasingly include GLP-1s in recommended treatment pathways. It gains further traction through investments in digital health integration and pharmacy automation. Demand is rising for long-acting, user-friendly products across patient demographics.
Asia Pacific
The Asia Pacific GLP-1 Receptor Agonist Market size was valued at USD 4,513.08 million in 2018 to USD 8,964.89 million in 2024 and is anticipated to reach USD 39,920.31 million by 2032, at a CAGR of 20.5% during the forecast period. Asia Pacific contributes 19.51% of the global market share. Rapid urbanization, changing dietary habits, and sedentary lifestyles are driving an upsurge in diabetes cases across China, India, Japan, and Southeast Asia. Governments are expanding public health infrastructure and chronic disease management programs. Local manufacturing initiatives and regional pricing models improve accessibility to GLP-1 therapies. Pharmaceutical firms are collaborating with domestic distributors and hospitals to strengthen supply chains. Rising disposable incomes and growing health awareness are shaping patient demand. It is seeing growing regulatory harmonization, accelerating product approvals. Asia Pacific remains a strategic focus for long-term market expansion and untapped patient potential.
Latin America
The Latin America GLP-1 Receptor Agonist Market size was valued at USD 1,633.06 million in 2018 to USD 3,002.90 million in 2024 and is anticipated to reach USD 10,633.77 million by 2032, at a CAGR of 17.2% during the forecast period. The region holds a 5.20% share of the global market. Brazil and Mexico are leading markets, supported by improving healthcare access and chronic disease initiatives. Demand is increasing for GLP-1 therapies due to rising obesity and diabetes rates in urban populations. Regional governments are beginning to include advanced therapies in public formularies and subsidy programs. It faces pricing pressure but benefits from the entry of biosimilars and generic versions. Clinical trial activity is expanding in Latin America, encouraging faster drug development cycles. Companies are investing in local partnerships to improve reach. Market penetration is improving through awareness campaigns and professional education.
Middle East
The Middle East GLP-1 Receptor Agonist Market size was valued at USD 1,178.32 million in 2018 to USD 2,062.19 million in 2024 and is anticipated to reach USD 7,223.99 million by 2032, at a CAGR of 17.0% during the forecast period. The market represents 3.53% of global share. Gulf countries such as Saudi Arabia and the UAE dominate the regional market, supported by government-funded healthcare and lifestyle disease management initiatives. High-income populations and a growing demand for advanced metabolic therapies are contributing to growth. Health ministries are implementing national diabetes strategies and early screening programs. Private hospitals and specialty clinics play a key role in therapy access. It is expanding through digital platforms and retail pharmacy chains offering GLP-1 medications. Healthcare digitalization and AI-driven patient engagement tools support adherence. The market is gradually shifting toward value-based care and outcomes-driven protocols.
Africa
The Africa GLP-1 Receptor Agonist Market size was valued at USD 1,061.06 million in 2018 to USD 2,333.85 million in 2024 and is anticipated to reach USD 8,178.26 million by 2032, at a CAGR of 16.7% during the forecast period. Africa contributes 3.99% to the global market. South Africa and Egypt are the key contributors, driven by rising healthcare investments and international collaborations. Urbanization and changing diets are contributing to a growing diabetes burden. Access to GLP-1 therapies remains limited in rural regions due to infrastructure gaps and affordability concerns. Global organizations and NGOs are launching awareness and screening programs across underserved communities. It is experiencing gradual penetration through donor-funded health initiatives and public-private partnerships. Local distribution networks are being strengthened to improve medication availability. The market presents a long-term opportunity with focused investment and health policy reform.
Key Player Analysis:
- Eli Lilly and Company
- Sanofi
- Novo Nordisk A/S
- AstraZeneca
- Pfizer Inc.
- Amgen, Inc.
- Innovent Biologics, Inc.
- PegBio Co., Ltd.
- Sun Pharmaceutical Industries Ltd.
- Boehringer Ingelheim International GmbH
Competitive Analysis:
The GLP-1 Receptor Agonist Market is highly competitive and dominated by a few major pharmaceutical players with strong R&D pipelines and global reach. Companies such as Novo Nordisk, Eli Lilly and Company, AstraZeneca, Pfizer, and Sanofi lead the market with patented drugs like semaglutide, dulaglutide, and liraglutide. These firms maintain market dominance through aggressive investment in clinical trials, regulatory filings, and product innovation. Strategic collaborations, co-marketing agreements, and regional expansion efforts continue to shape the competitive dynamics. It sees new entrants focusing on oral formulations and biosimilars to challenge incumbent brands. Competitive pricing strategies and technological differentiation are critical for market retention. Companies are expanding therapeutic indications and leveraging digital tools to boost patient engagement. The landscape remains dynamic with M&A activities and pipeline diversification driving long-term positioning.
Recent Developments:
- In June 2025, Eli Lilly and Company entered a high-value partnership with Camurus to develop long-acting GLP-1 and dual/triple incretin therapies using Camurus’ proprietary FluidCrystal technology, with deal terms that could reach up to $870 million. Lilly is also advancing its oral GLP-1 candidate orforglipron, which recently reported strong Phase3 results, showing significant benefits for patients with obesity and type2 diabetes.
- In June 2025, Amgen reported robust results from its Phase2 clinical study of MariTide, a monthly injectable bispecific GLP-1/GIP receptor agonist. The innovation lies in less frequent dosing, which could enhance adherence and market differentiation for weight management
- In March 2024, Novo Nordisk announced the acquisition of Cardior Pharmaceuticals, a German biotech firm, for approximately $1.1 billion. While Cardior’s primary focus is on RNA-based therapies for heart diseases, the acquisition strengthens Novo Nordisk’s capabilities in cardiometabolic disease, which is synergistic with its leadership in the GLP-1 receptor agonist space.
Market Concentration & Characteristics:
The GLP-1 Receptor Agonist Market exhibits high market concentration, with a few established players accounting for the majority of global revenue. It is characterized by strong patent protections, high development costs, and stringent regulatory requirements that create high entry barriers. The market favors companies with significant biologics expertise, robust supply chains, and capacity for global distribution. Innovation in long-acting and oral formulations defines product differentiation. Therapy adoption trends align closely with national healthcare guidelines and reimbursement structures. Market success depends on clinical trial outcomes, label expansions, and real-world evidence. It shows sustained demand due to the chronic nature of treated conditions and increasing global disease prevalence.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, Route of Administration and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global prevalence of obesity and type 2 diabetes will sustain long-term demand for GLP-1 receptor agonists.
- Expansion of clinical indications beyond diabetes, including weight management and NASH, will drive therapeutic diversification.
- Advancements in oral formulations and extended-release injectables will improve patient adherence and broaden adoption.
- Increasing regulatory approvals across emerging markets will support geographic expansion and faster market penetration.
- Strategic collaborations between pharma companies and digital health platforms will enhance treatment delivery and monitoring.
- Entry of biosimilars post-patent expiry may introduce pricing competition and expand access in cost-sensitive regions.
- Enhanced reimbursement frameworks and health policy support will increase adoption across public healthcare systems.
- Growing investment in R&D pipelines will strengthen innovation and introduce combination therapies.
- Telemedicine and e-pharmacy growth will reshape access models and patient engagement strategies.
- Focus on value-based care models and real-world outcome data will shape future market dynamics and pricing structures.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Prevalence of Type 2 Diabetes and Obesity
The increasing incidence of type 2 diabetes and obesity worldwide is fueling demand for GLP-1 receptor agonists, as these therapies offer dual benefits of glycemic control and weight reduction. This trend is further supported by aging populations, sedentary lifestyles, and unhealthy dietary habits.
Superior Clinical Outcomes and Cardiovascular Benefits
GLP-1 receptor agonists have demonstrated significant improvements in glycemic control and reductions in major adverse cardiovascular events, leading to their preference over traditional antidiabetic agents among physicians and payers. These clinical advantages are driving their inclusion in treatment guidelines and expanding their use.
Expansion into Weight Management and New Indications
Regulatory approvals for GLP-1 therapies in obesity and ongoing research into additional indications such as NASH and cardiovascular diseases are broadening the market scope. This diversification is attracting new patient populations and increasing overall market demand.
Technological Innovations in Drug Delivery
Advancements such as once-weekly injectables, oral formulations, and user-friendly auto-injector pens are improving patient adherence and expanding acceptance of GLP-1 therapies. These innovations address barriers related to administration complexity and enhance the overall patient experience.
Strategic Investments and Partnerships by Pharmaceutical Companies
Major pharmaceutical players are investing heavily in R&D, clinical trials, and strategic collaborations to develop novel GLP-1 formulations and expand global access. These efforts are accelerating innovation cycles, supporting market expansion, and fostering competitive differentiation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the GLP-1 Receptor Agonist Market?
What factors are driving the growth of the GLP-1 Receptor Agonist Market?
What are the key segments within the GLP-1 Receptor Agonist Market?
What are some challenges faced by the GLP-1 Receptor Agonist Market?
Who are the major players in the GLP-1 Receptor Agonist Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Ozempic
- 1.2.2 Trulicity
- 1.2.3 Mounjaro
- 1.2.4 Wegovy
- 1.2.5 Rybelsus
- 1.2.6 Saxenda
- 1.2.7 Victoza
- 1.2.8 Zepbound
- 1.2.9 Other Products
- 1.3 By Application
- 1.3.1 Type 2 Diabetes Mellitus
- 1.3.2 Obesity
- 1.4 By Route of Administration
- 1.4.1 Parenteral
- 1.4.2 Oral
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 53,158.08 million → 2032: USD 204,613.75 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global GLP-1 Receptor Agonist Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global GLP-1 Receptor Agonist Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global GLP-1 Receptor Agonist Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global GLP-1 Receptor Agonist Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global GLP-1 Receptor Agonist Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global GLP-1 Receptor Agonist Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global GLP-1 Receptor Agonist Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global GLP-1 Receptor Agonist Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 53,158.08 million → 2032: USD 204,613.75 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global GLP-1 Receptor Agonist Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Ozempic
- 12.3.7.2 Trulicity
- 12.3.7.3 Mounjaro
- 12.3.7.4 Wegovy
- 12.3.7.5 Rybelsus
- 12.3.7.6 Saxenda
- 12.3.7.7 Victoza
- 12.3.7.8 Zepbound
- 12.3.7.9 Other Products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Type 2 Diabetes Mellitus
- 12.4.7.2 Obesity
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Parenteral
- 12.5.7.2 Oral
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global GLP-1 Receptor Agonist End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global GLP-1 Receptor Agonist Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global GLP-1 Receptor Agonist Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global GLP-1 Receptor Agonist Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Eli Lilly and Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Novo Nordisk A/S
- 18.4 Sanofi
- 18.5 AstraZeneca
- 18.6 Pfizer Inc.
- 18.7 Amgen, Inc.
- 18.8 Boehringer Ingelheim International GmbH
- 18.9 Sun Pharmaceutical Industries Ltd.
- 18.10 Innovent Biologics, Inc.
- 18.11 PegBio Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

