Canadian Natural to Acquire Advantage Energy for C$2.53 Billion in Montney Gas Deal
Canadian Natural Resources Ltd. has agreed to buy Montney producer Advantage Energy Ltd. in an all-cash deal valued at about C$2.53 billion, including debt, the two Calgary-based companies said on Nov. 16, 2026. The transaction hands Canada's largest oil and gas producer another block of gas-weighted production and processing capacity in northwest Alberta, nine months after Advantage's board ended a strategic review without a sale.
Key developments
- Canadian Natural will pay C$13.55 in cash for each Advantage share, an equity value of about C$2.255 billion on a fully diluted basis and a total transaction value of about C$2.53 billion including net debt and convertible debentures.
- Advantage said the price is a 25% premium to both its Nov. 13 closing price on the Toronto Stock Exchange and its 30-day volume-weighted average price, and exceeds the highest price its shares have traded at in 18 years.
- Canadian Natural said the deal adds about 79,000 barrels of oil equivalent per day (boe/d) from Montney and Charlie Lake assets, at an implied value of roughly C$32,000 per flowing boe/d.
- The assets include the owned and operated Glacier Gas Plant, rated at 425 million cubic feet per day (mmcf/d), the newly commissioned 75 mmcf/d Progress Gas Plant and more than 2,200 drilling locations, according to Advantage.
- Closing is expected in the first quarter of 2027, subject to an Advantage shareholder vote planned for January, Competition Act clearance and approval from the Court of King's Bench of Alberta.
Deal background
Advantage has built one of the larger natural gas businesses in the Montney, a tight-rock formation that straddles the Alberta and British Columbia border. In the third quarter of 2026 the company averaged 86,964 boe/d, including 452 million cubic feet per day of natural gas and about 11,600 barrels per day of crude oil, condensate and natural gas liquids. Production rose 23% from the second quarter after the Progress plant came online, even as Advantage sold its Wembley assets for about C$325 million in cash.
The sale follows a review that went the other way. In February, Advantage said a special committee of independent directors had weighed a sale, a merger and other options and unanimously concluded that none served shareholders, so the company would stay on its standalone plan. At the time, Advantage guided for second-half 2026 production of about 90,000 boe/d and listed debt reduction as its priority. Board chair John Festival is now also serving as interim chief executive, according to the Nov. 16 release.
For Canadian Natural, the purchase extends a run of large acquisitions. In December 2024 it closed the purchase of Chevron's Alberta assets, which added a further interest in the Athabasca Oil Sands Project and Duvernay light oil acreage. The company said Advantage's lands sit next to its Grande Prairie operations and build on its existing Montney and Charlie Lake positions. It will fund the deal with cash on hand and existing bank credit lines.
Industry implications
The agreement shows senior Canadian producers are willing to pay a premium for gas inventory that comes with owned processing. Advantage's two plants give it close to 500 mmcf/d of company-controlled processing, which removes one of the main bottlenecks in the Montney, where third-party plant capacity and pipeline access often limit how fast new wells can be brought on. Canadian Natural President Scott Stauth called Advantage an excellent strategic fit and said the deal is accretive and consistent with the company's disciplined approach to acquisitions.
The timing also matters. Western Canadian gas producers have been looking past the domestic AECO price toward export demand, with LNG Canada at Kitimat, British Columbia, shipping its first cargo in 2025 and other West Coast projects in development. Advantage said in October that its market diversification work had cut its direct AECO price exposure to about 12% for the fourth quarter of 2026. A larger owner with Canadian Natural's balance sheet is better placed to sign long-term transport and supply commitments that a mid-cap producer might struggle to carry.
Competitive and supply chain implications
The deal continues consolidation in the Montney and Duvernay, where well-capitalized operators have been adding contiguous acreage to run longer laterals, share facilities and cut per-unit costs. Canadian Natural said the transaction brings additional synergies of scale that should improve area efficiencies, though it did not put a dollar figure on them. Remaining independent Montney producers may now face more pressure from investors to either grow scale or consider a sale.
For service and equipment suppliers, fewer and larger operators typically mean consolidated contracts for drilling rigs, completion crews, compression and water handling. Advantage's inventory of more than 2,200 locations, of which 309 are booked as proved, provides years of drilling for whoever operates it. Canadian Natural's practice of running assets on a cost-focused, factory-style basis could change how that inventory is paced, particularly if gas prices stay weak in the near term.
Regional implications
The assets sit in northwest Alberta, an area whose local economy relies heavily on drilling and processing activity. Bringing the Glacier and Progress plants under a company that already runs Grande Prairie operations could allow shared field staff and infrastructure across neighboring lands. For Alberta, the deal keeps the assets with a Canadian-headquartered owner at a time when governments in Edmonton and Ottawa are promoting energy exports and new pipeline and LNG capacity.
The deal also needs approval under Canada's Competition Act. Advantage expects to mail its management information circular in December 2026, ahead of a special shareholder meeting in January. All Advantage directors and executive officers have signed voting support agreements, and the board unanimously recommends that shareholders vote in favor.
Credence Research analysis
The price signals how Canadian Natural values Montney gas production with built-in processing. At about C$32,000 per flowing boe/d for a gas-heavy asset, the acquirer is paying for production as well as the plants and drilling inventory. The 25% premium, paid only months after Advantage's own board found no attractive outside offer, suggests Canadian Natural sees value that the market had not priced in, most likely in the adjacency to its Grande Prairie operations and the ability to fill owned plants with lower-cost wells.
The bigger shift is strategic. Canadian Natural built its reputation on long-life oil sands and heavy oil assets, and the Chevron purchase deepened that base. Adding a gas-weighted Montney producer gives the company more exposure to Canadian LNG exports and gas-fired power demand while keeping its pledge to direct all free cash flow to share buybacks after closing. The key questions are how quickly it integrates the assets, whether it slows Advantage's growth to protect returns and whether rivals respond with deals of their own.
What comes next
- December 2026: Advantage expects to mail and file its management information circular on SEDAR+.
- January 2027: Advantage shareholders vote on the plan of arrangement at a special meeting.
- Regulatory review under the Competition Act (Canada) and a final order from the Court of King's Bench of Alberta.
- First quarter of 2027: targeted closing of the transaction, subject to customary conditions.
- After closing: Canadian Natural's first operating guidance that includes the Advantage assets, including any update on area synergies and capital plans.
Sources
- Advantage Energy: Agreement to be acquired by Canadian Natural Resources (Nov. 16, 2026)
- Canadian Natural Resources: Agreement to acquire Advantage Energy (Nov. 16, 2026)
- Advantage Energy: Third quarter 2026 results (Oct. 29, 2026)
- Advantage Energy: Conclusion of strategic review (Feb. 12, 2026)
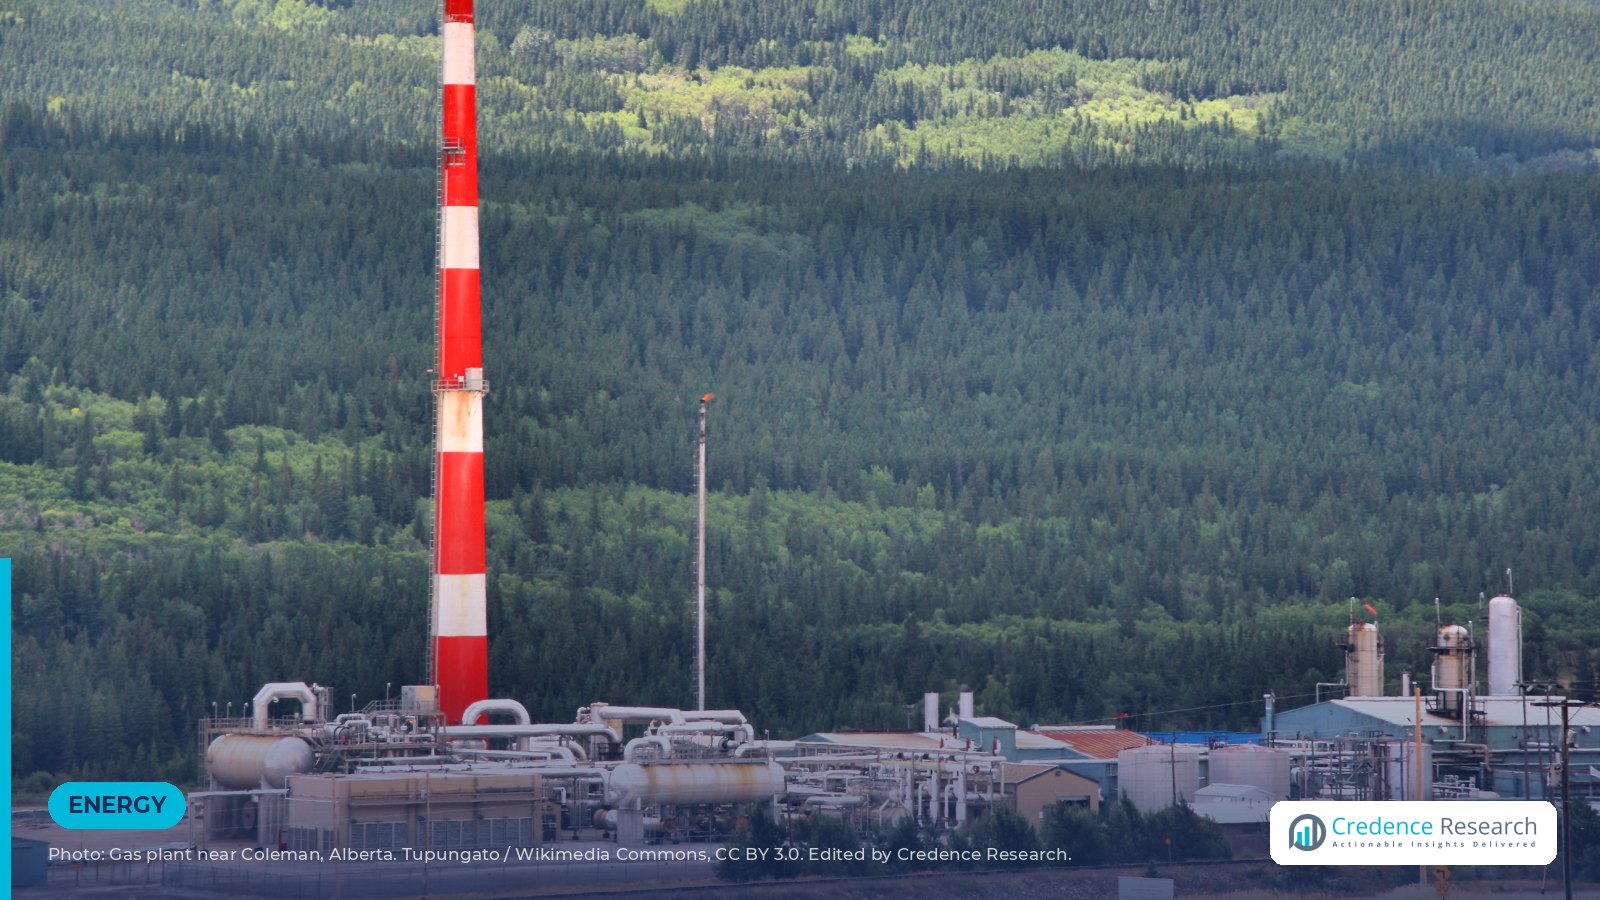
Image: Natural gas plant near Coleman, Alberta, by Marek Ślusarczyk (Tupungato) via Wikimedia Commons, CC BY 3.0. Cropped and edited by Credence Research.

About the Author
Senior News Editor at Credence Research Inc