
Bio- and e-methanol plants start up to supply ships
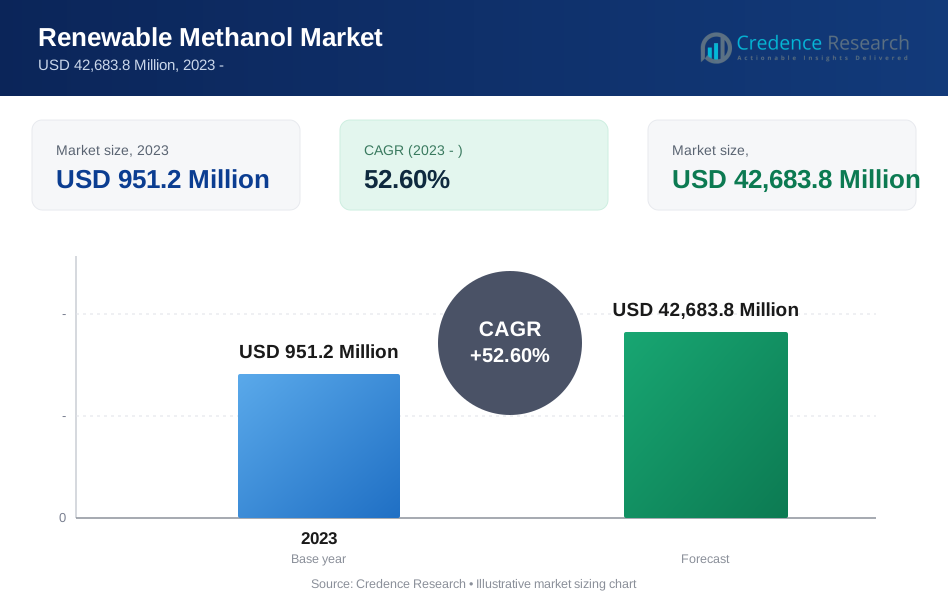
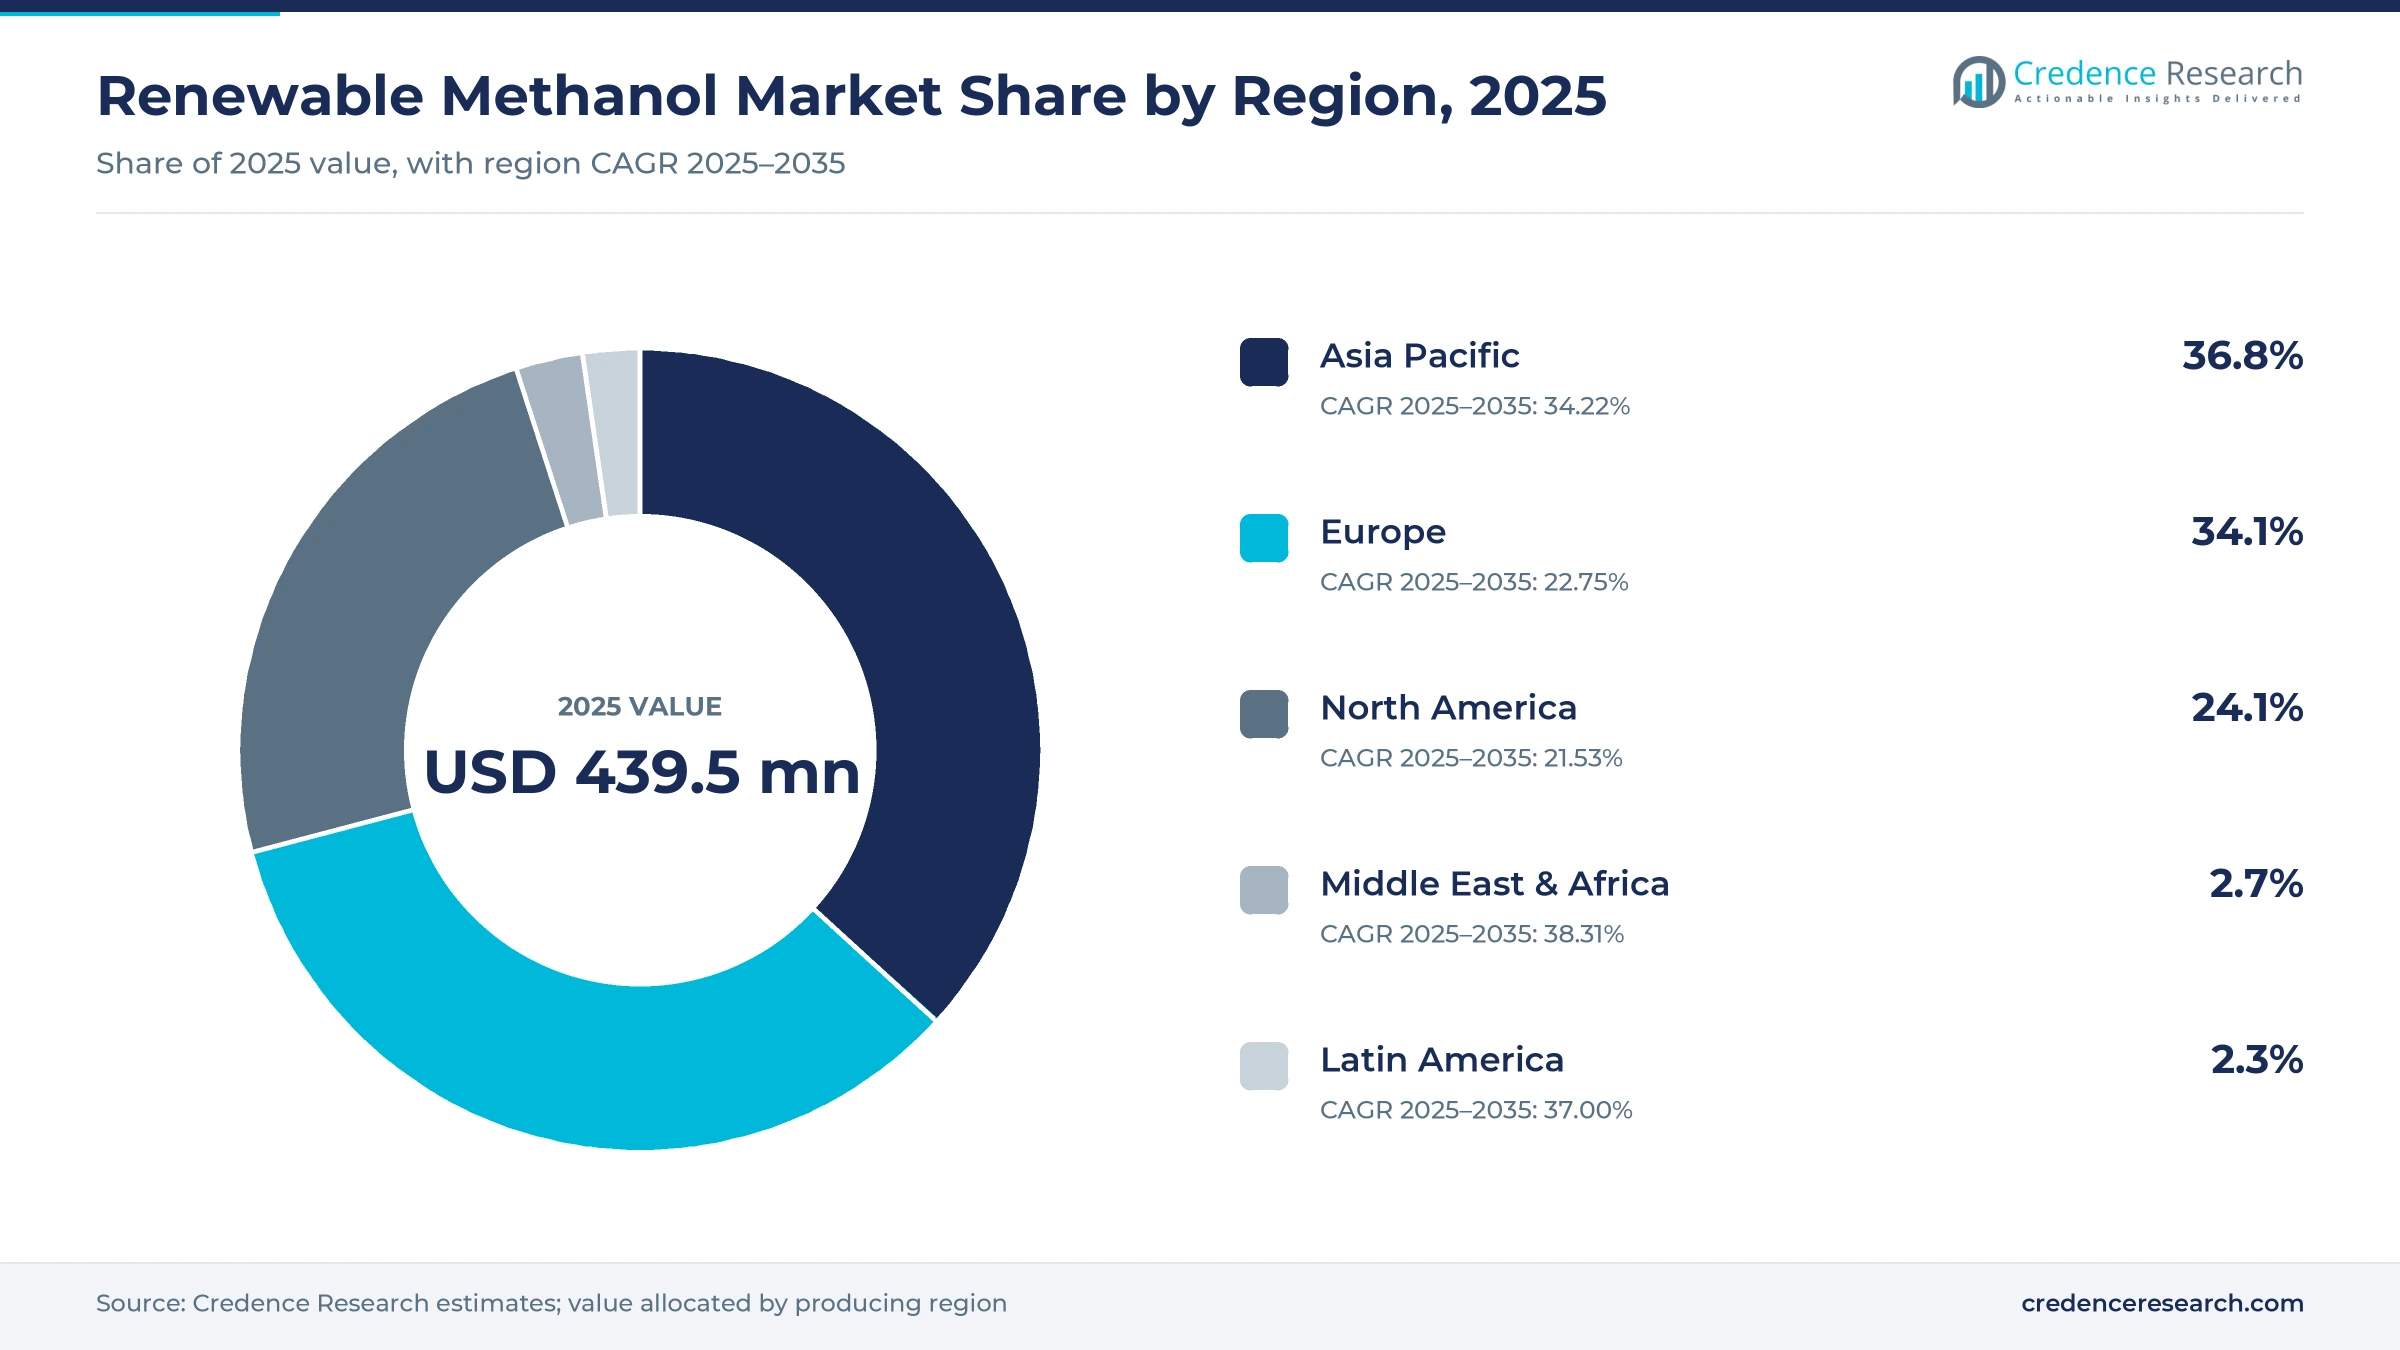
The renewable methanol market was valued at USD 439.5 million in 2025 and is projected to increase from USD 635.5 million in 2026 to USD 5,518.0 million by 2035, registering a CAGR of 28.79% during 2025–2035. Demand comes from container lines that have ordered methanol-capable ships, from FuelEU Maritime and from chemical buyers and consumer brands seeking lower product footprints. Asia Pacific held the largest regional share, 36.8% in 2025, as plants in Jilin and Inner Mongolia came on line, while the Middle East & Africa grows fastest at 38.31% a year. The main commercial change is the arrival of commercial e-methanol, with Kassø inaugurated in May 2025.
Which molecules count as renewable methanol?
Renewable methanol is chemically identical to fossil methanol, so it uses the same tanks, terminals and chemical plants. Bio-methanol comes from gasified biomass, biogas or biomethane, including certified mass-balance volumes, and from sorted waste or pulp-mill crude methanol, while e-methanol combines captured carbon dioxide with electrolytic hydrogen from renewable power. Value is counted at the producer's realized price in the year of production.
The scope excludes low-carbon methanol from natural gas or coal with carbon capture and methanol made with grid power or fossil carbon dioxide that misses a renewable fuel standard. Electrolyzers, gasifiers, bunkering vessels and engines are also outside the market.
Renewable Methanol Market Insights
- Credence Research projects the renewable methanol market to rise from USD 635.5 million in 2026 to USD 5,518.0 million by 2035, a 28.79% CAGR, as new plants reach full output.
- Asia Pacific held 36.8% of 2025 value, the largest regional share, because China's new biomass plants in Jilin and Inner Mongolia began commissioning in 2025.
- Biomass-based methanol accounted for 71.6% of 2025 value, the largest feedstock route, as gasified residues and certified biomethane sell at a smaller premium than e-methanol.
- Kassø in Denmark, inaugurated in May 2025 as the first large-scale commercial e-methanol plant, moved e-methanol from pilot units into commercial supply for shipping and brands.
- Methanex completed its acquisition of OCI Global's methanol business in June 2025, bringing a low-carbon production and marketing arm into the largest independent methanol supplier.
Biomass routes and chemicals lead as ship fuel grows fastest
Biomass routes lead while CCU e-methanol grows fastest
Based on feedstock type, the market is categorized into biomass-based methanol, CCU e-methanol and waste-to-methanol. Biomass-based methanol led with 71.6% of 2025 value, as Chinese straw-gasification plants and certified biomethane routes supply most of today's volume at a smaller premium. CCU e-methanol grows fastest at 40.31% a year, supplied by Kassø, the George Olah plant in Iceland and new Chinese units and rewarded by EU rules for fuels of non-biological origin.
Chemical intermediates lead while ship fuels grow fastest
Based on application, the market is categorized into chemical intermediates, fuel blending, marine and shipping fuels, industrial and other applications, and power generation and energy storage. Chemical intermediates led with 38.0% of 2025 value, as buyers of formaldehyde, resins, acetic acid and olefins pay for certified grades to cut product footprints. Marine and shipping fuels grow fastest at 40.01% a year on dual-fuel container ships, FuelEU Maritime and contracted Chinese supply arriving from 2026.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Feedstock Type | Biomass-based Methanol | 71.6% | CCU E-Methanol | 40.31% |
| By Application | Chemical Intermediates | 38.0% | Marine and Shipping Fuels | 40.01% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Methanol-ready ships, offtake and EU rules pull plants in
Dual-fuel container ships create a ready buyer base
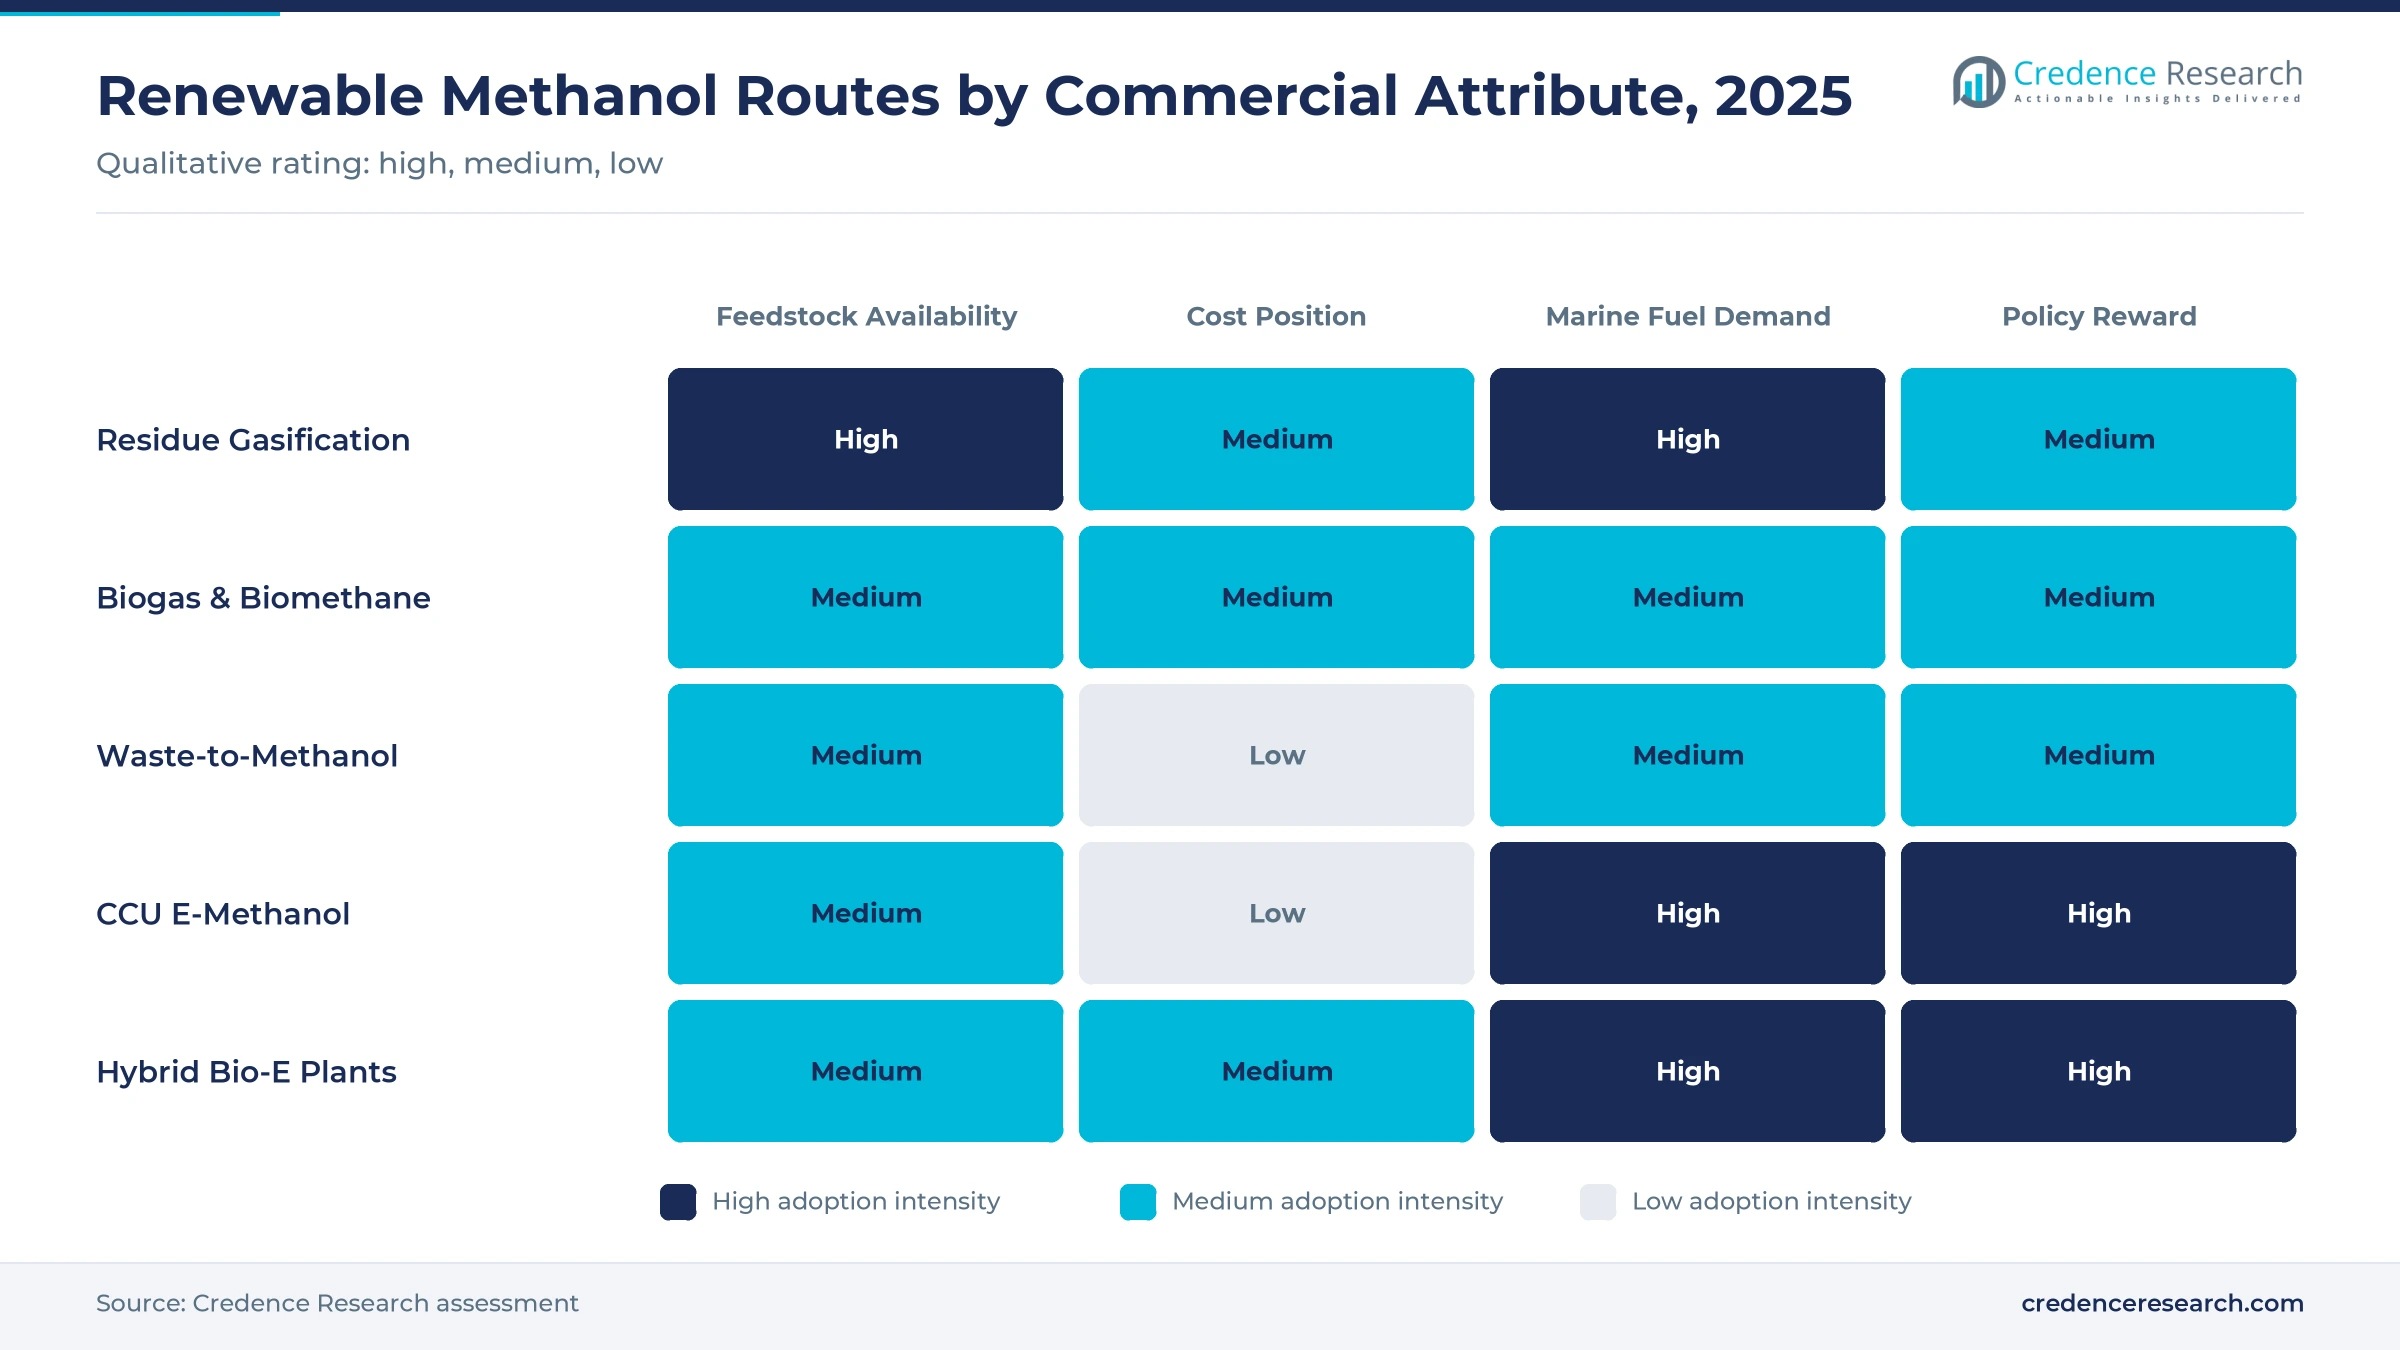
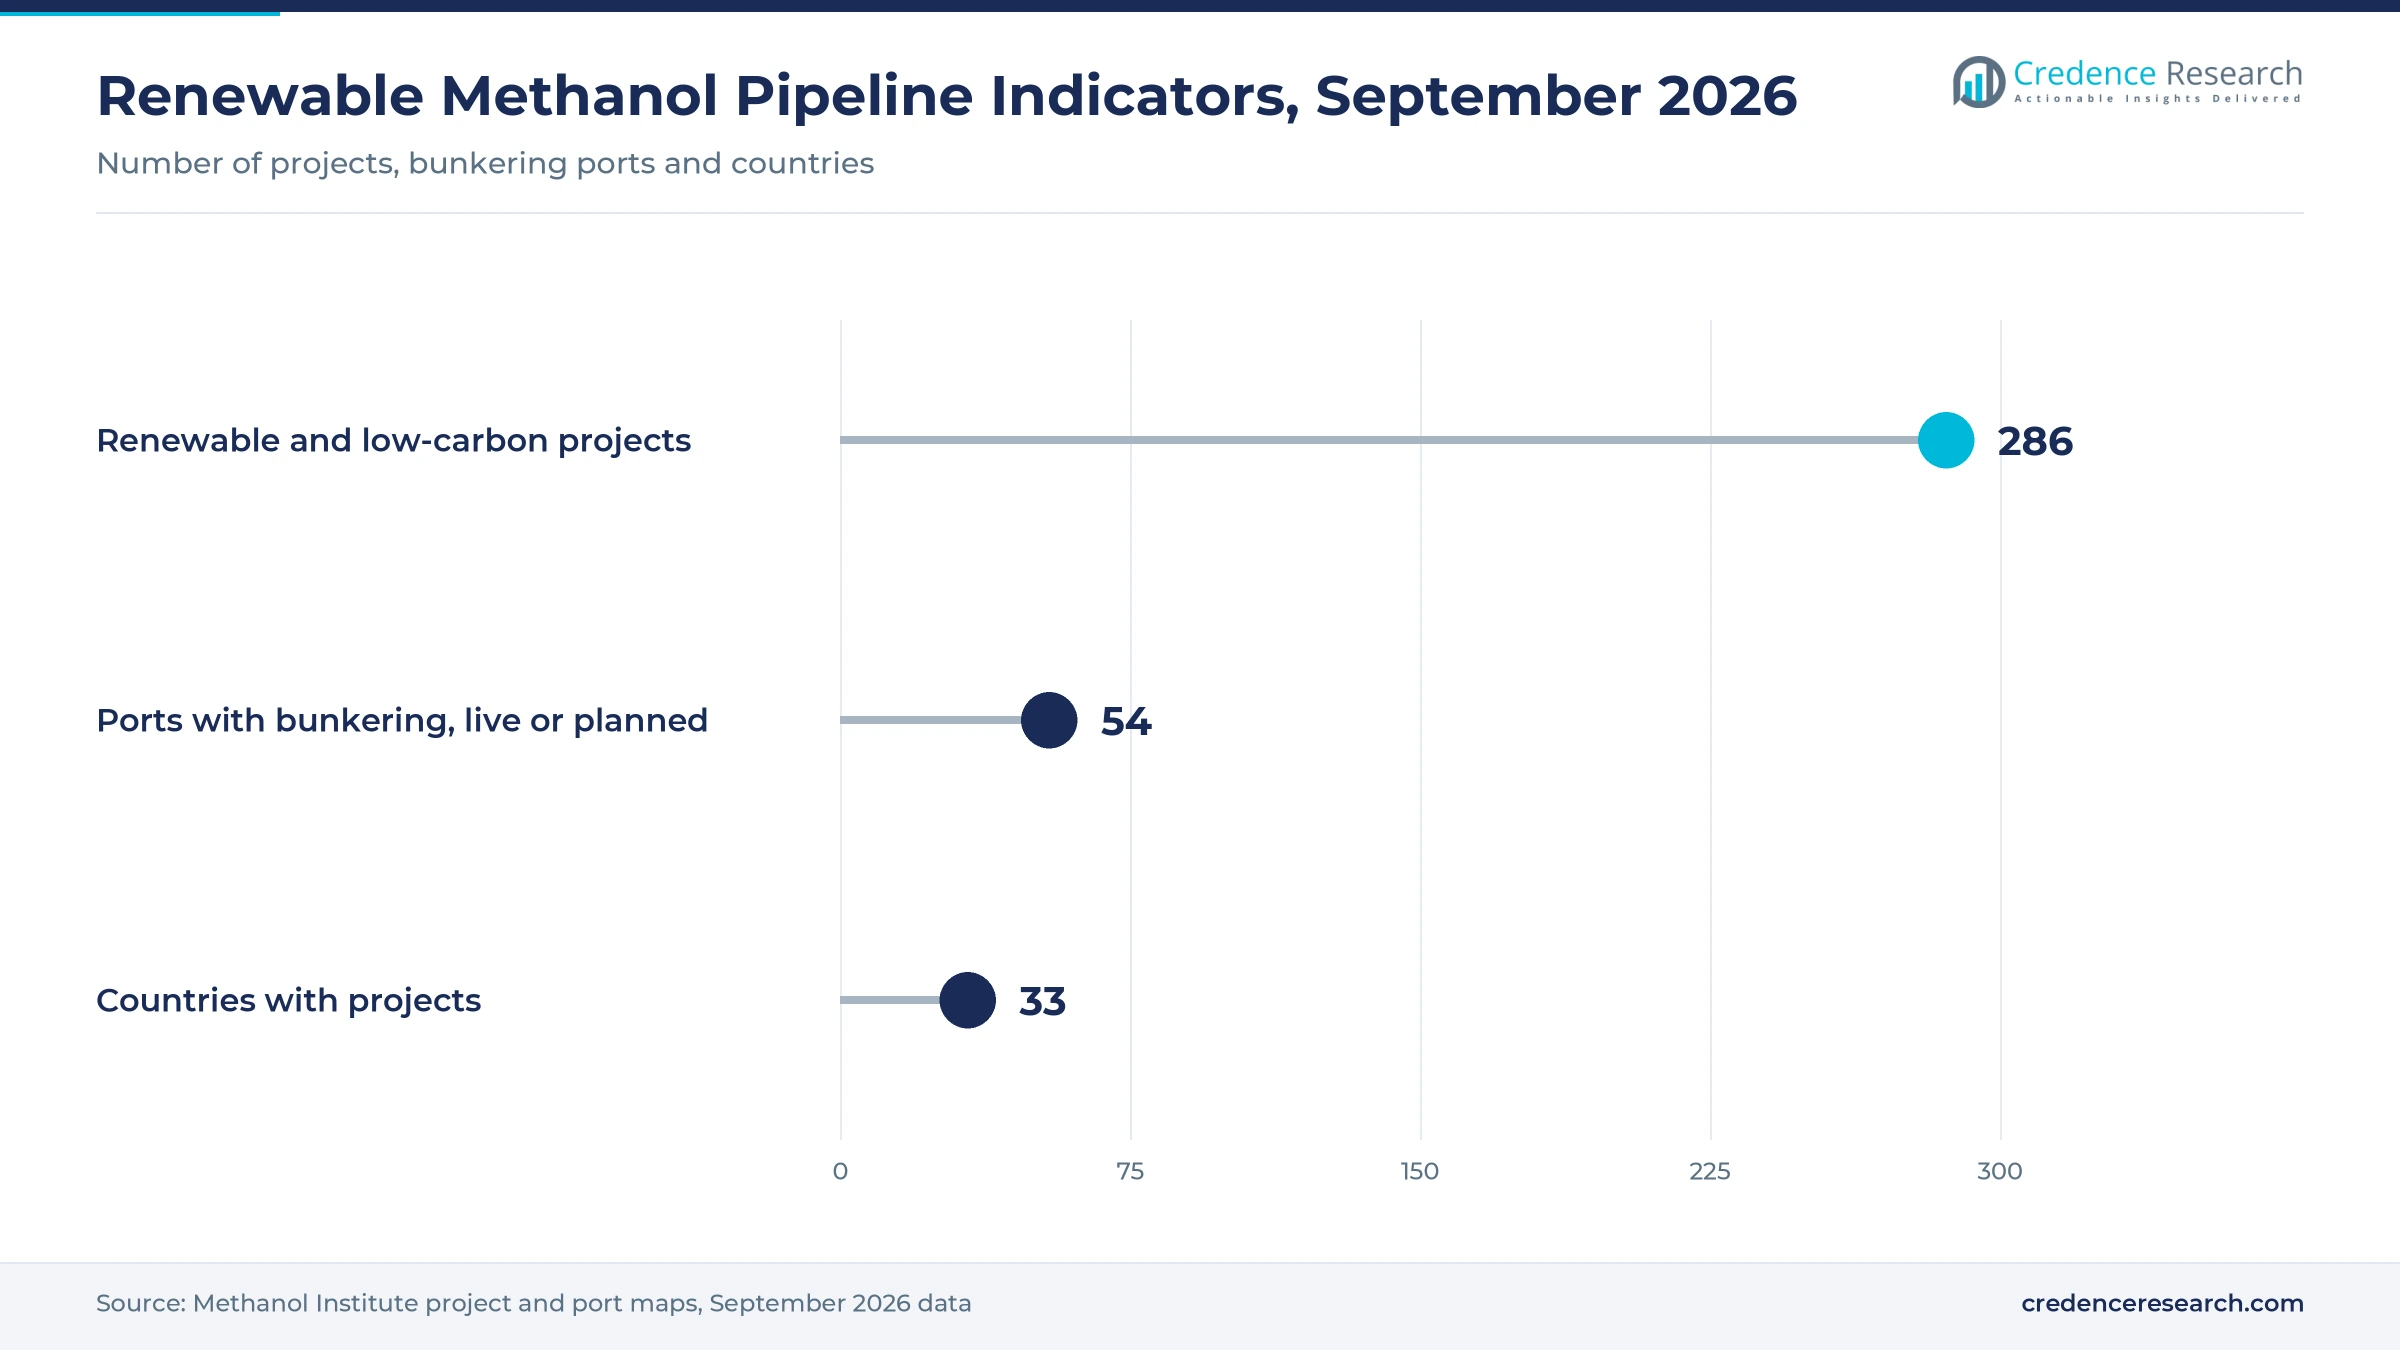
Methanol is liquid at room temperature, needs no cryogenic tanks and can be bunkered with modest port changes, which made it the first choice for container lines wanting renewable-fuel ships. On DNV's tracking, methanol was the second most-ordered alternative fuel after LNG in the first half of 2025, when alternative-fuel orders by gross tonnage rose 78% on 2024. That order book is matched by port readiness, as 54 ports offer or are developing methanol bunkering, so owners can plan routes around existing supply. Because each ship needs fuel for 20 years or more, marine fuel grows fastest at 40.01% a year.
Long-term offtake turns plans into construction
On Nov. 22, 2023, Maersk signed an offtake agreement with Goldwind for bio-methanol and e-methanol from a new plant in Hinggan League, northeast China, with first volumes due in 2026. That single contract covers more renewable methanol per year than the world produced in 2025, and a named buyer for a decade gives lenders the certainty Chinese developers have used to reach construction quickly, lifting Asia Pacific growth to 34.22% a year.
FuelEU Maritime puts a price on carbon-intensive ship fuel
FuelEU Maritime has applied in full since January 2025 and requires the average greenhouse gas intensity of ship energy used at EU ports to fall by 2% in 2025 and 80% by 2050, measured well-to-wake. Owners that miss the target pay penalties, while those that beat it can pool surplus, so one bio-methanol ship can offset several conventional ones, helping early buyers in European trades recover the fuel premium.
Consumer brands and chemical makers buy certified grades
Companies that report product footprints can cut emissions by switching part of their methanol supply to a renewable grade without changing a plant. LEGO and Novo Nordisk took that route as offtakers of e-methanol from Denmark's Kassø facility. That plant cuts the carbon footprint by up to 97% against fossil-based products, a reduction these brands can report directly. This demand keeps chemical intermediates the largest application at 38.0% of 2025 value and gives producers a second buyer group beside shipping lines.
China scales bio-methanol while hybrid plants emerge
Production shifts to wind-rich northeast China
Jilin and Inner Mongolia combine large wind farms, crop residues and cheap land. The Shanghai municipal government reported in June 2025 that Shanghai Electric's Taonan project in Jilin, launched in March 2024, would deliver its first batch in July 2025 and supply bunkering fuel at Shanghai Port. A Goldwind subsidiary then completed biomass gasifier tests in Hinggan League in October 2025, and this shift has made Asia Pacific the largest producing region.
Hybrid plants combine biomass carbon and electrolytic hydrogen
Adding electrolytic hydrogen to biomass syngas raises methanol yield from the same carbon. For example, Carbon Recycling International signed a cooperation agreement on Aug. 19, 2025, for a combined bio- and e-methanol plant in Yushu, Jilin and a technology license with Jilin Huajin Energy on Oct. 23, 2025, and Goldwind's Hinggan League output also mixes both routes. Credence Research expects hybrid plants to blur feedstock lines after 2030, favoring licensors skilled in both gasification and synthesis.
Methanol majors open global distribution for renewable grades
Methanex completed its acquisition of OCI Global's methanol business on June 27, 2025, adding a low-carbon production and marketing business to its renewable natural gas contracts in North America. Its global tanker fleet and terminal network give renewable grades wider reach, so producers selling through Methanex reach chemical and marine customers faster.
Export hubs form where cheap power meets deep-water ports
Export hubs are likely to form where cheap renewable power meets a deep-water port and a carbon source, such as Oman, Egypt, Morocco and Saudi Arabia for e-methanol and Brazil and Chile for biomass routes. The Methanol Institute project map, on September 2026 data, lists 286 renewable and low-carbon methanol projects across 33 countries, and 54 ports offer or are developing methanol bunkering. That pipeline, tied to green hydrogen supply, makes the Middle East & Africa the fastest-growing region and lifts Latin America to 37.00% a year.
Cost gaps, biomass limits and an IMO delay hold back demand
A wide cost gap against fossil methanol
Fossil methanol is a commodity made in huge plants with long-paid-off assets, so renewable grades start at a large premium. IRENA's Innovation Outlook notes that volumes are low and costs high, and that policy support is needed to make renewable methanol cost-competitive by 2050 or earlier. E-methanol carries the biggest premium because electricity is most of its cost, so producers narrow the gap through long-term offtake and cheaper Chinese electrolyzers.
The IMO delay removes the global signal shipowners wanted
At an extraordinary session from Oct. 14 to 17, 2025, the IMO adjourned adoption of its Net-Zero Framework for one year. Without a global fuel standard and carbon price, owners outside EU trades have little reason to burn renewable methanol, so many dual-fuel ships run on fuel oil today and marine demand outside Europe slips into the 2030s. Producers limit the risk by contracting European and consumer-brand buyers first, with chemical sales as a fallback.
Sustainable biomass is limited and contested
Biomass-based methanol, 71.6% of 2025 value, competes for residues with bioenergy, biochar and second-generation ethanol, and collection costs rise fast beyond a plant's local catchment. Certification rules also limit which feedstocks count, so developers without secured residue contracts risk under-used plants. They respond by siting plants inside dense farming regions, adding electrolytic hydrogen to stretch each ton of carbon and turning to waste streams.
Other renewable alcohols cap the premium methanol can earn
Engines built for methanol can burn other alcohols, so shipowners can switch to whichever renewable molecule is cheapest. On Sept. 28, 2026, Maersk announced the first U.S. ethanol bunkering of a deep-sea container vessel, the alcohol-enabled Tangier Maersk, using corn ethanol. That flexibility caps the premium producers can charge, so they protect margins through long-term contracts with price formulas, EU-compliant certification and larger, lower-cost plants.
Asia Pacific produces most as Europe pays top prices
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Asia Pacific | 36.8% | 34.22% |
| Europe | 34.1% | 22.75% |
| North America | 24.1% | 21.53% |
| Middle East & Africa | 2.7% | 38.31% |
| Latin America | 2.3% | 37.00% |
Asia Pacific becomes the largest producer on Chinese biomass plants
Asia Pacific held 36.8% of 2025 value and grows at 34.22% a year. China supplies almost all of it, mainly from biomass plants, with e-methanol units such as China Tianying's Liaoyuan project following. Shanghai, Singapore and Chinese coastal ports are building bunkering supply, and cheaper equipment and provincial support speed Chinese investment decisions.
Strict rules and high prices anchor European demand
Europe held 34.1% of 2025 value and grows at 22.75% a year. Kassø in Denmark, which cuts the carbon footprint by up to 97% against fossil-based products, pulp-mill methanol in Sweden and certified biomethane routes form the base, and European buyers pay the highest prices because FuelEU Maritime and EU renewable fuel rules reward certified supply. However, high power costs slow new e-methanol plants such as Liquid Wind's projects in Sweden, so Europe is expected to import more over time.
North America draws most volume from renewable natural gas routes
North America held 24.1% of 2025 value and grows at 21.53% a year, the slowest regional pace. Renewable natural gas routes at large U.S. methanol plants, including those of Methanex, supply most of it, and waste-to-methanol developers in Canada such as Enerkem add smaller volumes. Chemical buyers lead demand, while marine use grows as U.S. ports test alcohol bunkering.
Middle East & Africa and Latin America build export hubs
The Middle East & Africa held 2.7% of 2025 value and is the fastest-growing region at 38.31% a year, as Gulf and North African e-methanol projects aim at European and Asian ship fuel buyers. Latin America held 2.3% and grows at 37.00% a year, with Brazil's sugarcane and forestry residues and Chile's wind and solar resources supporting biomass and e-methanol projects.
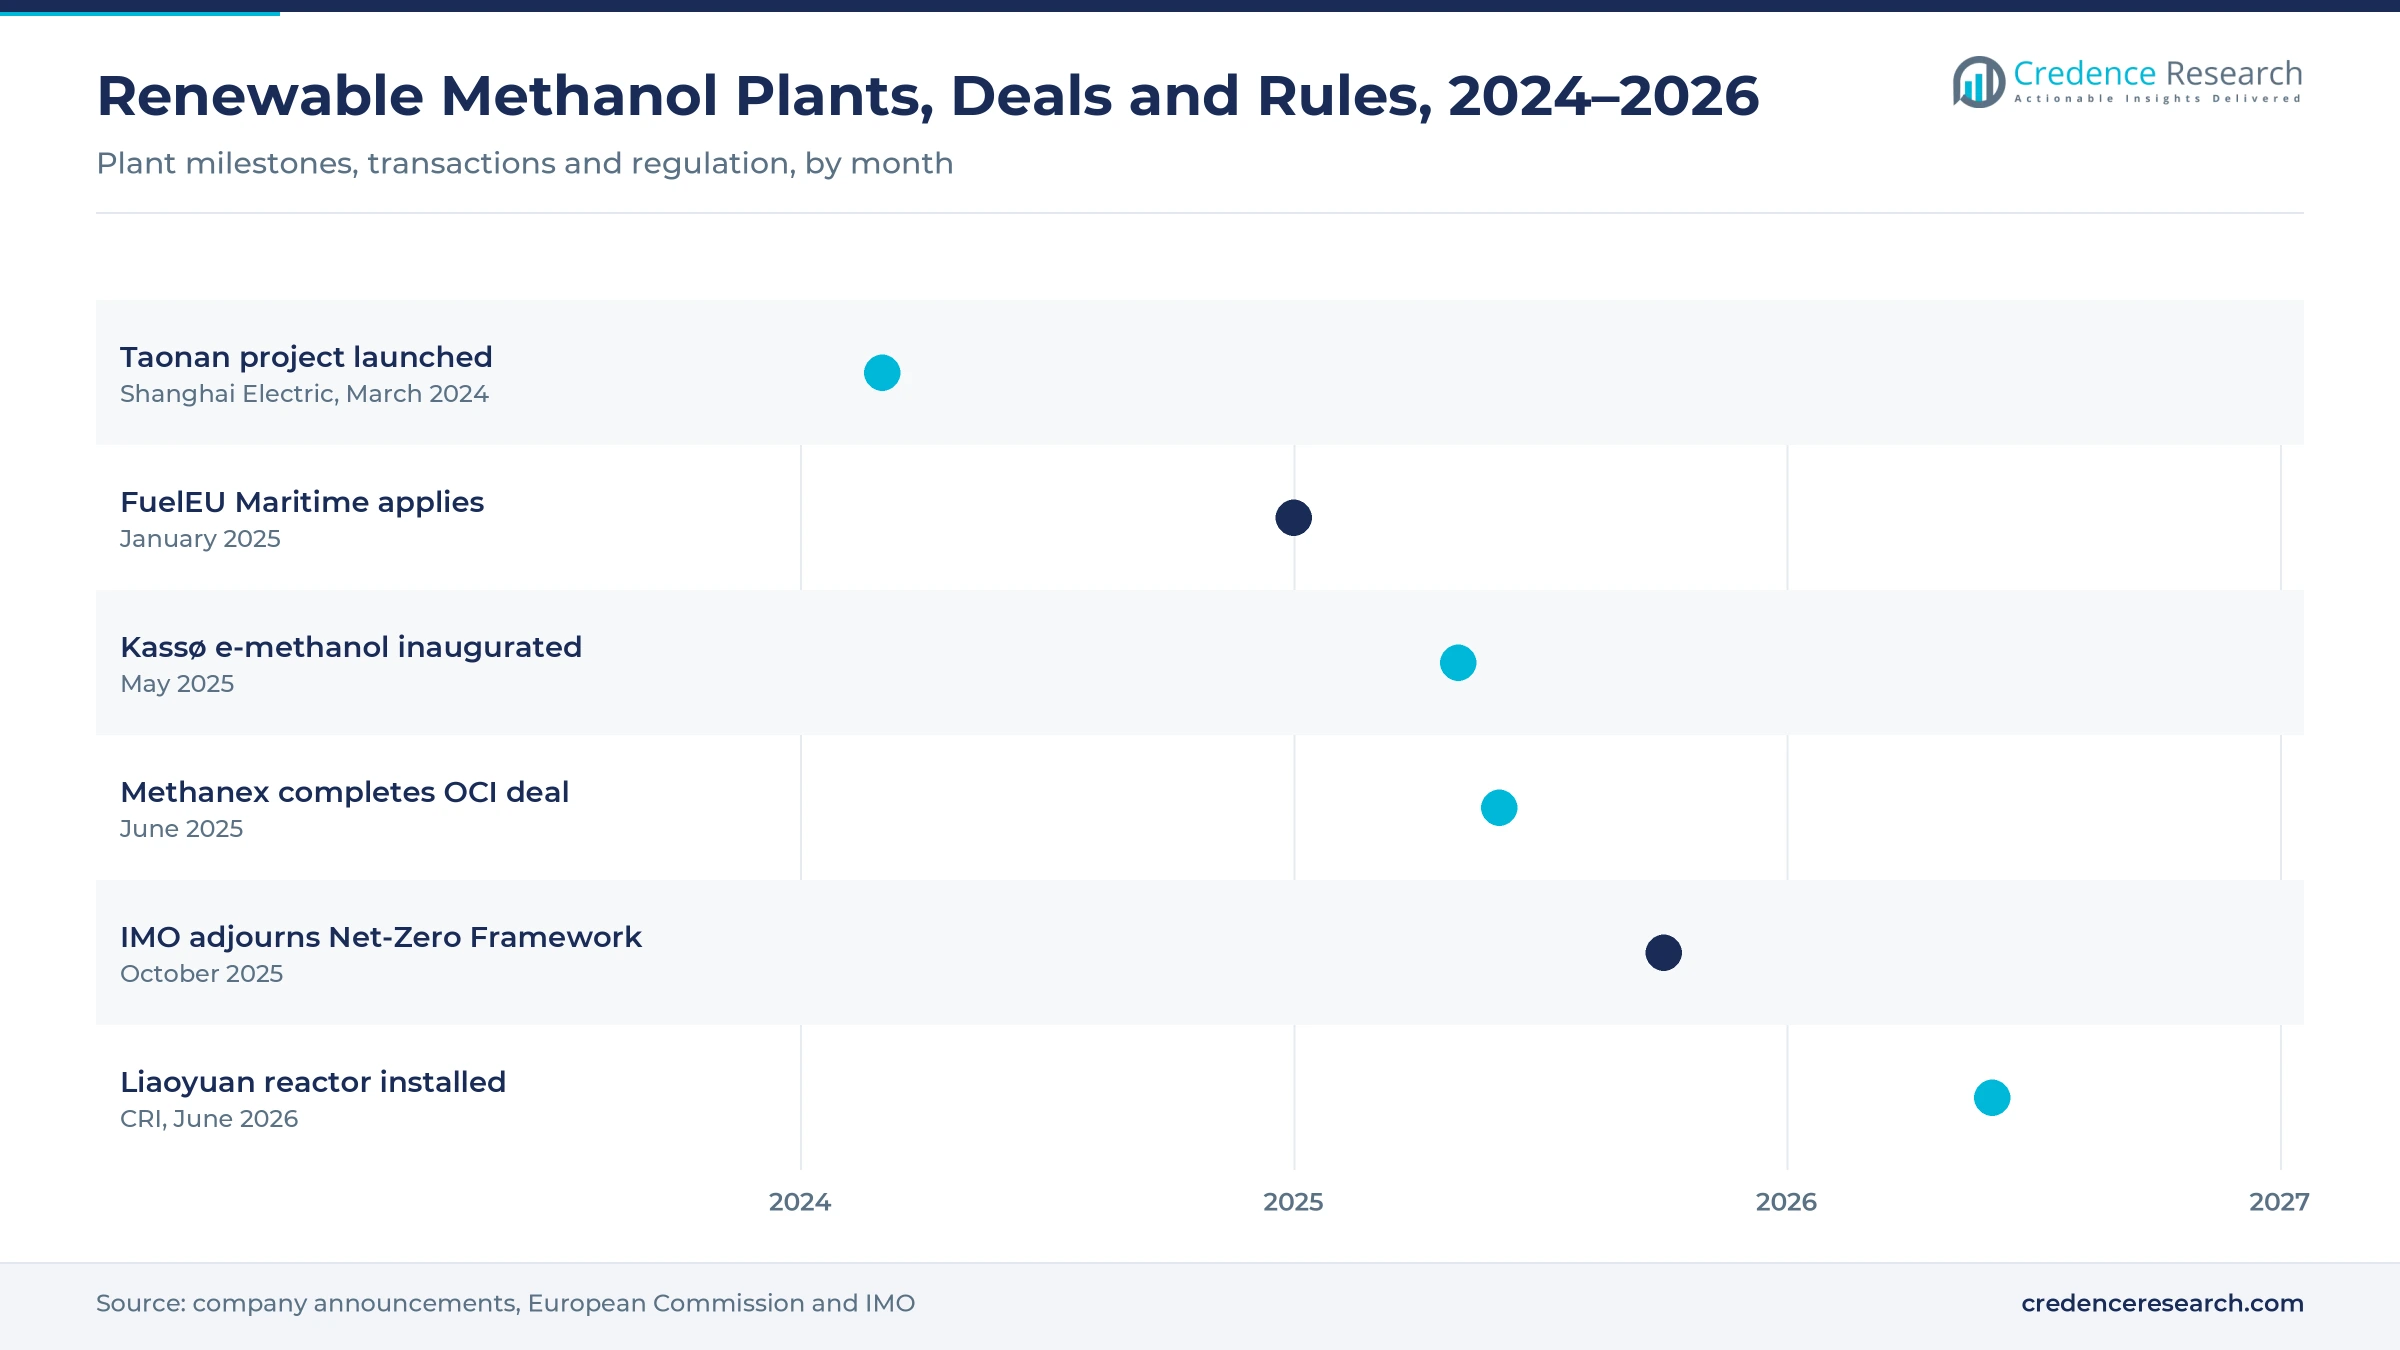
Plant openings, a Methanex deal and an IMO delay, 2025–2026
| Development | Status and market relevance |
|---|---|
| In September 2026, Maersk announced the first U.S. ethanol bunkering of a deep-sea container vessel, the alcohol-enabled Tangier Maersk. | Announced. Shows dual-fuel ships can switch between renewable alcohols. |
| In June 2026, Carbon Recycling International delivered and installed its reactor for the Liaoyuan e-methanol project in Jilin. | Installed. Start-up planned later in 2026. |
| In October 2025, the IMO adjourned adoption of its Net-Zero Framework for one year at an extraordinary session. | Delayed. Postpones the global fuel standard for shipping. |
| In June 2025, Methanex completed its acquisition of OCI Global's methanol business, which included a low-carbon methanol production and marketing business. | Completed. Brings renewable grades into the largest independent supplier's portfolio. |
| In May 2025, European Energy and Mitsui inaugurated the Kassø e-methanol facility at Aabenraa, Denmark. | Operating. First large-scale commercial e-methanol plant. |
Gasification, electrolysis and hybrid synthesis lead
- Biomass gasification of straw and forestry residues, tested in Hinggan League in 2025, turns crop waste into methanol syngas.
- Carbon dioxide synthesis from Carbon Recycling International, proven at the George Olah plant in Iceland, is now licensed into Chinese projects such as Liaoyuan.
- Hybrid plants add electrolytic hydrogen to biomass syngas for higher methanol yield.
- Certification under mass-balance rules and EU rules for fuels of non-biological origin decides which volumes earn a premium.
- New uses include methanol-to-jet routes linked to sustainable aviation fuel demand and methanol fuel cells for remote power and storage.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Plant builders, licensors and shipping buyers shape supply
Chinese energy and equipment groups, led by Goldwind and Shanghai Electric, run the largest new biomass plants in Inner Mongolia and Jilin, while European Energy and Mitsui & Co. own Kassø, the first large-scale commercial e-methanol plant. Licensors such as Carbon Recycling International sell synthesis know-how, and developers such as Enerkem in Canada and Liquid Wind in Sweden add waste and e-methanol projects. Methanex markets low-carbon grades worldwide, and Maersk is the largest single buyer. Price, certification and a long-term buyer decide who wins, not plant size alone, and Credence Research expects concentration to fall as listed projects reach operation.
Companies profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Goldwind | Chinese energy group | Bio- and e-methanol complex in Hinggan League with Maersk as anchor buyer |
| Shanghai Electric | Chinese equipment group | Taonan green methanol project in Jilin, aimed at Shanghai Port bunkering |
| European Energy | European developer | Majority owner of the Kassø e-methanol plant in Denmark |
| Mitsui & Co. | Trading house | Co-owner of Kassø |
| Methanex | Methanol major | Low-carbon methanol business from OCI and renewable natural gas contracts |
| Carbon Recycling International | Technology licensor | E-methanol synthesis, George Olah plant and the Liaoyuan reactor |
| China Tianying | Project owner | Liaoyuan e-methanol project in Jilin |
| Enerkem | Technology developer | Waste-to-methanol gasification in Canada |
| Liquid Wind | Project developer | E-methanol projects in Sweden |
| A.P. Moller - Maersk | Shipping buyer | Offtake with Goldwind and a share of Kassø output |
A small product with a large, visible buyer
Credence Research's view is that supply, not demand, sets the market's value through 2035, because buyers are lined up but output remains a tiny slice of global methanol. Producers pairing low-cost feedstock or power with long-term buyers and recognized certification are best placed. The main risk is a prolonged IMO delay, so investors should watch Chinese plant ramp-ups, European investment decisions and IMO talks in 2026.
How Credence Research sized bio- and e-methanol sales
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's plant-by-plant model of output, start dates, ramp-up and certification status, tested against IRENA analysis and the Methanol Institute project database, and segment and regional splits are Credence Research estimates.
Ship fuel becomes the largest use as plants reach full rates
Through 2035, marine fuel overtakes chemical intermediates as the largest use as Chinese plants contracted to shipping lines reach full rates, while CCU e-methanol, growing 40.31% a year, gains value share under EU rules for fuels of non-biological origin. Asia Pacific remains the largest producer, the Middle East & Africa and Latin America, with just 2.7% and 2.3% of 2025 value, grow into export hubs, and Europe, growing 22.75% a year, imports more.
Frequently Asked Questions
What was the size of the renewable methanol market in 2025?
What is the forecast value and CAGR of the renewable methanol market?
What counts as renewable methanol?
Which feedstock type leads the renewable methanol market?
What is renewable methanol mainly used for?
Which region holds the largest share of the renewable methanol market?
Who are the major companies in the renewable methanol market?
What challenges could slow the renewable methanol market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Feedstock Type
- 1.2.1 Biomass-based Methanol
- 1.2.2 CCU E-Methanol
- 1.2.3 Waste-to-Methanol
- 1.3 By Application
- 1.3.1 Chemical Intermediates
- 1.3.2 Fuel Blending
- 1.3.3 Marine and Shipping Fuels
- 1.3.4 Industrial and Other Applications
- 1.3.5 Power Generation and Energy Storage
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 439.5 million → 2035: USD 5,518.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Renewable Methanol Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Renewable Methanol Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Renewable Methanol Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Renewable Methanol Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Renewable Methanol Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Renewable Methanol Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Renewable Methanol Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Renewable Methanol Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 439.5 million → 2035: USD 5,518.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Renewable Methanol Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Feedstock Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Biomass-based Methanol
- 12.3.7.2 CCU E-Methanol
- 12.3.7.3 Waste-to-Methanol
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Chemical Intermediates
- 12.4.7.2 Fuel Blending
- 12.4.7.3 Marine and Shipping Fuels
- 12.4.7.4 Industrial and Other Applications
- 12.4.7.5 Power Generation and Energy Storage
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Renewable Methanol End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Renewable Methanol Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Renewable Methanol Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Renewable Methanol Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Goldwind
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Shanghai Electric
- 18.4 European Energy
- 18.5 Mitsui & Co.
- 18.6 Methanex
- 18.7 Carbon Recycling International
- 18.8 China Tianying
- 18.9 Enerkem
- 18.10 Liquid Wind
- 18.11 A.P. Moller - Maersk
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

