
NTT DATA Picks Bloom Energy Fuel Cells for 900 MW of Data Center Power, With Shipments From 2027
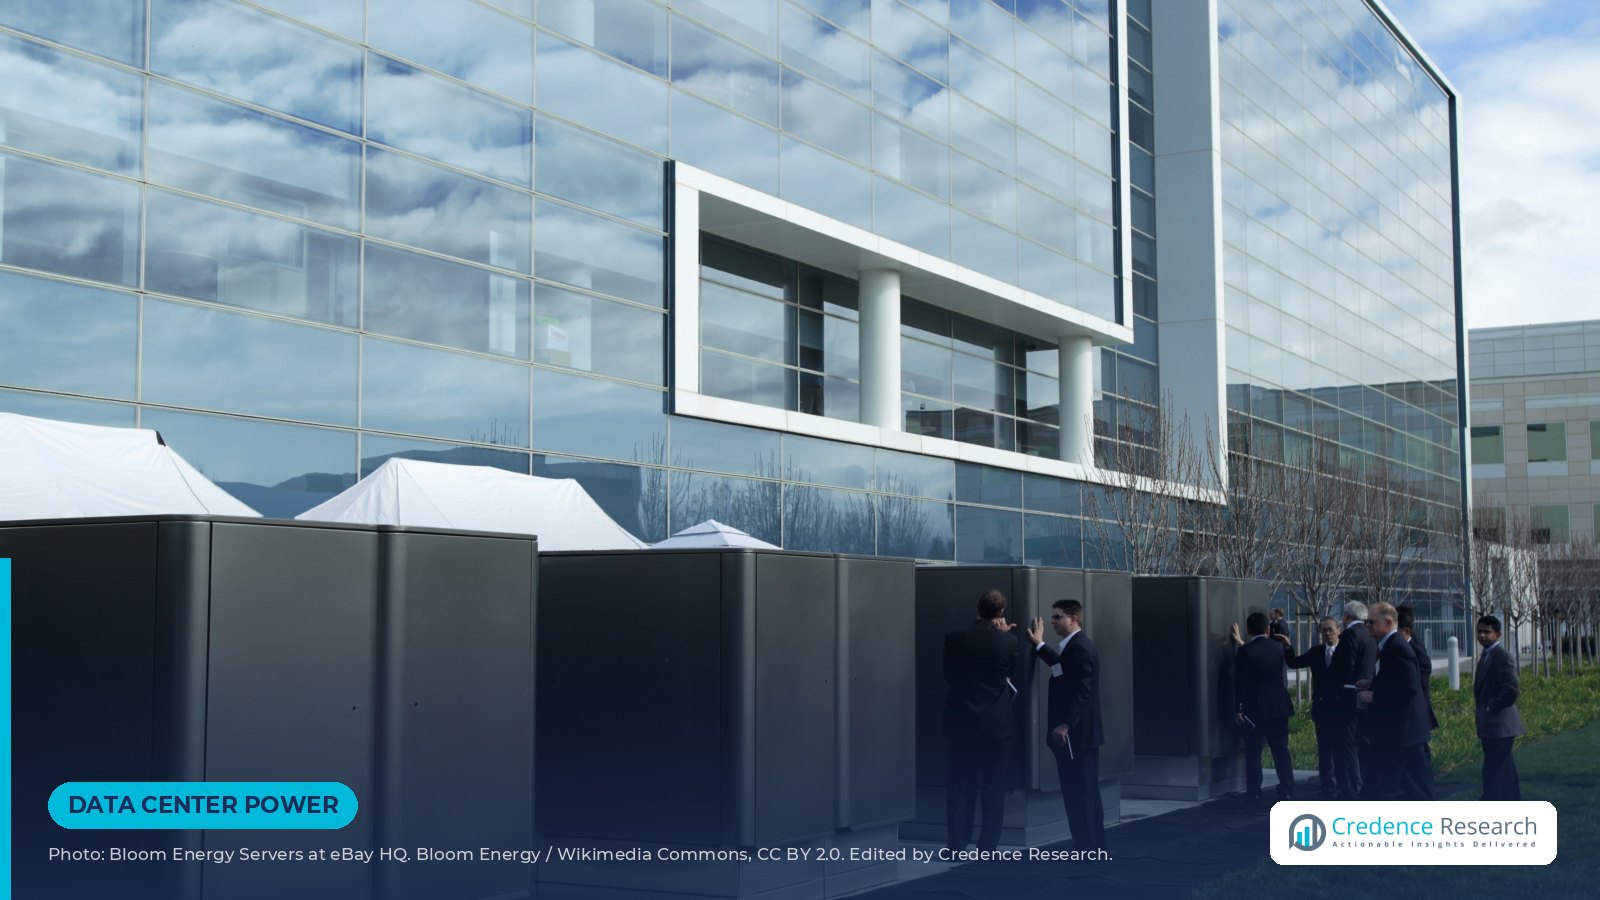
NTT Global Data Centers will use Bloom Energy fuel cells as primary power across 900 megawatts of data center projects worldwide, under an agreement the companies announced Thursday from London and San Jose, California. Initial shipments are due to start in 2027, and Bloom described the agreement as its largest international project to date.
Key developments
- Bloom will deploy 900 MW of onsite power across multiple projects of NTT Global Data Centers, NTT DATA's data center unit, according to the Nov. 5 release.
- The fuel cells will serve as primary power, with initial shipments starting in 2027.
- The companies said the relationship is designed to extend across NTT DATA's global data center portfolio and reach gigawatt scale.
- The modular systems can be installed in phases alongside data center construction, according to the release.
- The release does not disclose a contract value, named sites or countries, the fuel to be used, a final delivery date, or whether NTT will buy the systems or purchase their power.
How onsite fuel cell power fits data center builds
Bloom's solid oxide fuel cells produce electricity through an electrochemical reaction instead of combustion. The companies cite low local air emissions, minimal water use and quiet operation as benefits. Because the systems are factory-built and modular, an operator can add capacity in blocks as a campus grows, rather than waiting for a single large generation or grid project to finish.
Timing is the central argument for the deal. Doug Adams, CEO of NTT Global Data Centers, said in the release that clients are building AI capabilities "at a pace the grid alone cannot always match," and he described speed to power as a defining factor in delivering capacity. Aman Joshi, Bloom's executive vice president and chief commercial officer, said companies able to secure power quickly gain a differentiated advantage and a faster path to revenue.
A survey Bloom commissioned and published in January, based on 152 decision-makers polled in November 2025, found that utilities projected power delivery about 1.5 to 2 years later than hyperscalers and colocation providers expected. That gap comes from a vendor with a stake in the outcome, but it describes the planning problem NTT is now addressing with onsite generation.
Industry implications
The agreement extends large-scale fuel cell procurement further into the colocation business and beyond the United States. Other recent Bloom commitments are large as well. Oracle said in April that it intends to procure up to 2.8 gigawatts of Bloom systems, with 1.2 GW contracted at that point. American Electric Power said on Oct. 14 that it plans a 702 MW Bloom fuel cell plant near Cheyenne, Wyoming, to supply Google under a 20-year contract.
NTT's use of the phrase primary power matters here. Onsite generation has often been discussed as a bridge until a grid connection arrives. The release frames the fuel cells as the main source for capacity in power-constrained markets, which raises the bar for reliability, maintenance and fuel supply at each site.
For a colocation operator, the commercial logic differs from that of a hyperscaler building for its own workloads. NTT sells capacity to clients on delivery schedules, so a site that can energize earlier may be able to win or keep contracts it would otherwise lose.
Competitive and supply chain implications
Bloom competes for this demand with gas turbine makers, reciprocating engine suppliers and newer entrants. AEP agreed on Oct. 13 to buy up to 1.6 GW of linear generators from Mainspring Energy, with first deliveries in 2027, the same year NTT's fuel cell shipments begin. Operators now have more options for onsite power, and delivery dates are a primary point of comparison among them.
The stacking of orders places pressure on Bloom's factories and installation crews. The company said its systems are made in the United States, so the NTT agreement will test an export supply chain as well as domestic output. Bloom reported third-quarter revenue of $1.24 billion on Oct. 22, up 138.1% from a year earlier, and its chief financial officer said the company continues to invest in capacity to scale the business. The results release did not give a specific capacity expansion figure.
Fuel is the dependency the release leaves unaddressed. It names no fuel, although AEP's Wyoming plant will consume natural gas, and AEP plans to add carbon capture there. If NTT's projects also run on gas, pipeline access and gas pricing will influence which sites can proceed. They may also complicate operators' emissions reporting, since avoiding combustion cuts local air pollutants but does not eliminate carbon dioxide from a fossil fuel.
Regional implications
Neither company named a country, though Joshi referred to key strategic markets and the international label indicates that work will extend beyond the United States. Converge Digest reported in May that NTT DATA had about 1,630 MW of operating data center capacity as of March 31, with about 675 MW in the Americas, 430 MW in EMEA, 425 MW in India and 100 MW in other Asia-Pacific markets. It also reported about 770 MW planned and a target of more than 3 GW by fiscal 2030.
NTT DATA's land acquisitions announced in May 2025 included Milan, Frankfurt, London, Osaka and Tochigi, Japan, as well as Hillsboro, Oregon, and Mesa, Arizona. Those markets carry different permitting regimes, gas availability and grid constraints. Any site would need secure fuel and local approvals. The 900 MW figure is large relative to NTT's reported planned capacity, which suggests the agreement could cover a meaningful part of its pipeline, though the companies have not stated that allocation.
Credence Research analysis
We read this agreement as a sign that onsite primary power is moving from a U.S. workaround to a design choice for global colocation portfolios. Colocation providers have less flexibility than hyperscalers to wait for grid connections, because client delivery dates are contractual. Paying for dedicated generation can make sense when it protects those dates, and a phased, modular system lets an operator match spending to leasing.
The announcement is firmer on capacity than on terms. Without a contract value, site list, ownership model or fuel plan, it is hard to judge what share of the 900 MW is firm by year and location, or how the economics compare with waiting for the grid. Bloom's claim of a largest international project is meaningful, but its significance depends on how quickly sites outside the United States clear permitting and secure fuel. The first named location will say more about the strategy than the headline number does.
What comes next
- Initial fuel cell shipments to NTT projects are scheduled to begin in 2027.
- Either company may name the first sites and countries, which the release does not identify.
- Investors can look for contract structure and fuel details in Bloom's future filings and earnings calls.
- Permitting decisions at any non-U.S. site will show how regulators treat fuel cells as primary data center power.
- Further agreements would be needed to move the relationship from 900 MW to the gigawatt scale the companies describe.
Sources
- NTT DATA and Bloom Energy: 900 MW onsite power agreement release
- Bloom Energy: Oracle partnership expansion
- NTT DATA: land acquisitions across seven markets
- Converge Digest: NTT DATA data center capacity
Image: Bloom Energy Servers at eBay headquarters, by Bloom Energy via Wikimedia Commons, CC BY 2.0. Cropped and edited by Credence Research.

About the Author
Senior News Editor at Credence Research Inc