
Market Overview
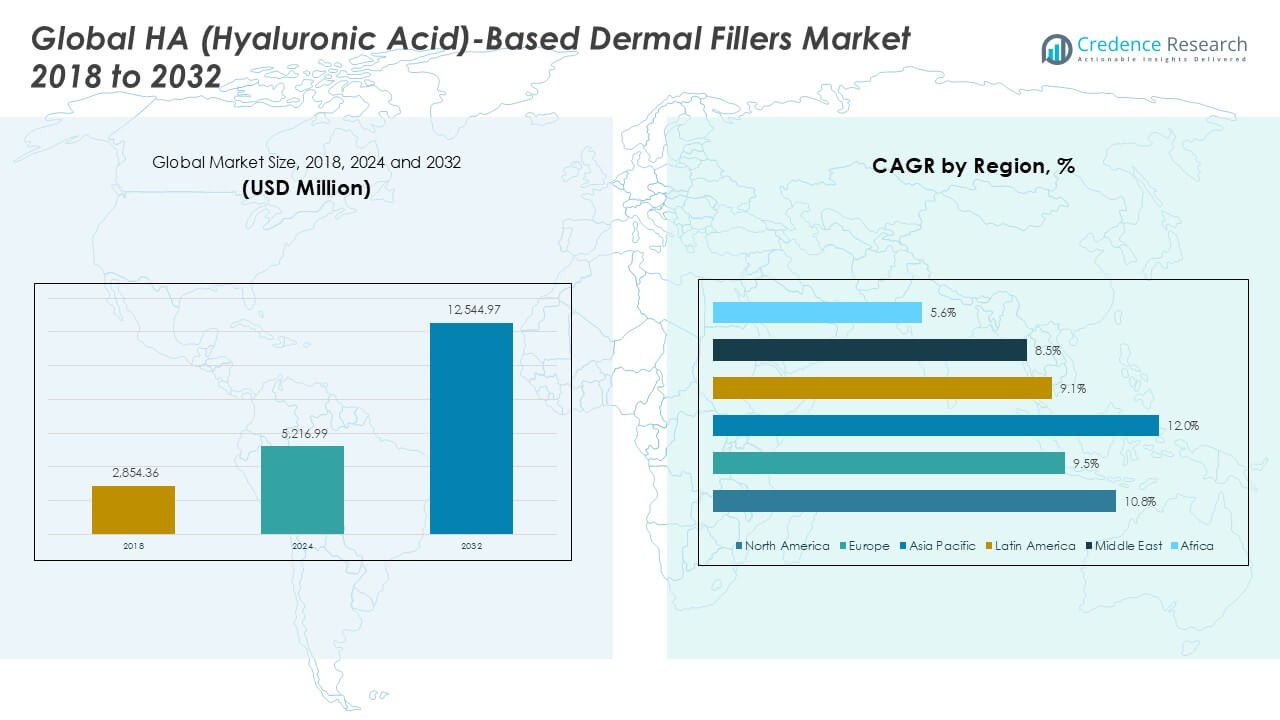
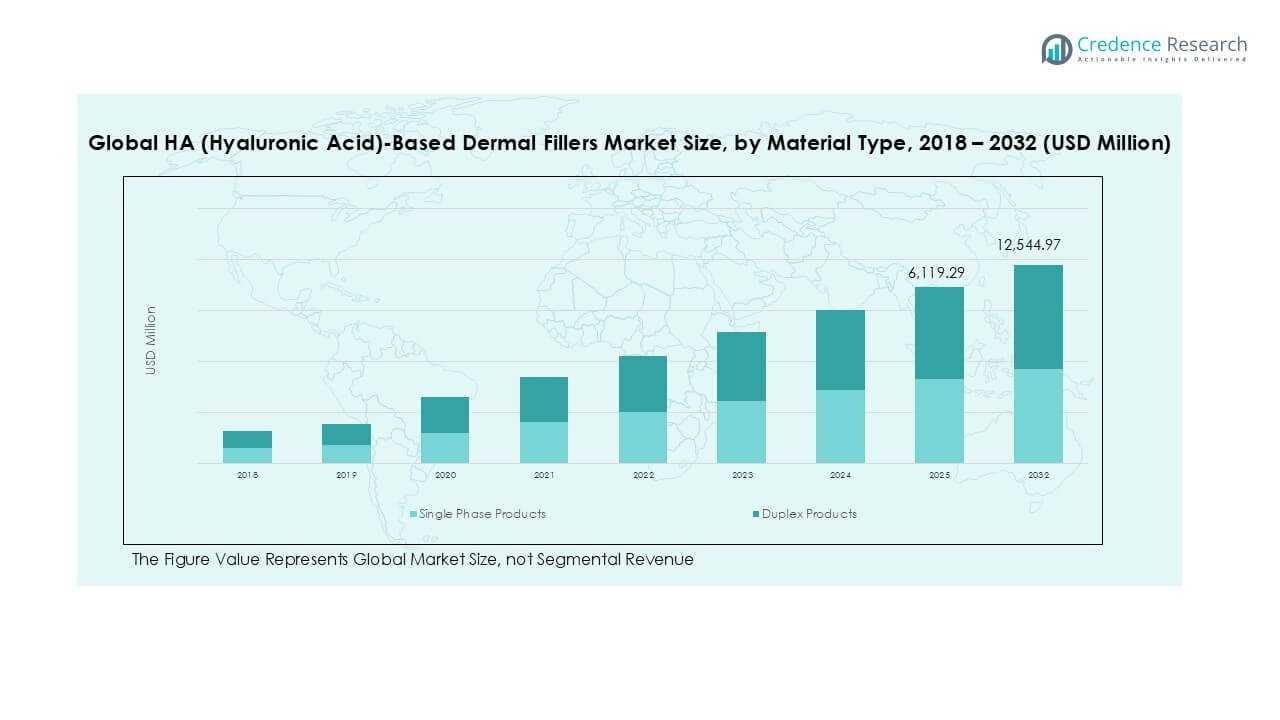
The Hyaluronic Acid-Based Dermal Fillers Market size was valued at USD 2,854.36 million in 2018 and reached USD 5,216.99 million in 2024. It is anticipated to grow significantly, reaching USD 12,544.97 million by 2032, expanding at a CAGR of 10.80% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hyaluronic Acid-Based Dermal Fillers Market Size 2024 | USD 5,216.99 Million |
| Hyaluronic Acid-Based Dermal Fillers Market , CAGR | 10.80% |
| Hyaluronic Acid-Based Dermal Fillers Market Size 2032 | USD 12,544.97 Million |
The HA (Hyaluronic Acid)-based dermal fillers market is led by key players such as Allergan, Galderma Laboratories, Merz Pharmaceuticals, LG Chem, and Anika Therapeutics, each offering a broad portfolio of advanced aesthetic products. These companies maintain strong market positions through continuous innovation, global distribution networks, and physician-focused marketing strategies. Allergan and Galderma, in particular, dominate with established flagship brands and widespread practitioner adoption. North America emerges as the leading region, accounting for 43.3% of the global market share in 2024, driven by high consumer awareness, demand for minimally invasive procedures, and the strong presence of certified dermatology clinics. Europe and Asia Pacific follow, with Asia Pacific registering the fastest growth due to rising aesthetic consciousness and expanding healthcare infrastructure. The market’s competitive dynamics are shaped by technological advancement, regulatory approvals, and strategic partnerships aimed at expanding both product capabilities and regional footprints.
Market Insights
- The HA-based dermal fillers market was valued at USD 5,216.99 million in 2024 and is projected to reach USD 12,544.97 million by 2032, growing at a CAGR of 10.80% during the forecast period.
- Market growth is driven by the rising demand for minimally invasive aesthetic procedures, aging populations seeking anti-aging solutions, and increasing awareness of facial aesthetics globally.
- A key trend includes the growing preference for personalized treatment plans and combination therapies, along with technological advancements in filler formulations offering longer-lasting and natural-looking results.
- The competitive landscape features dominant players such as Allergan, Galderma Laboratories, and Merz Pharmaceuticals, while new entrants are focusing on niche innovations; however, market growth is restrained by high treatment costs, regulatory complexities, and safety concerns with untrained practitioners.
- North America holds the largest regional share at 43.3%, while the Single Phase Products and Wrinkle Removal segments lead by product and application, respectively, due to their wide usage and patient preference.
Market Segmentation Analysis:
By Product
In the HA-based dermal fillers market, Single Phase Products dominate the product segment, accounting for the largest market share in 2024. These fillers offer smoother consistency and easier injection properties, making them highly preferred by dermatologists and aesthetic practitioners. The demand for single-phase fillers is further driven by their extended durability, reduced risk of allergic reactions, and natural-looking results. Moreover, the increasing adoption of minimally invasive cosmetic procedures and technological advancements in filler formulations continue to support the growth of this sub-segment over duplex products, which are still gaining traction.
- For instance, Galderma’s Restylane® Kysse utilizes XpresHAn Technology™, enabling enhanced tissue integration with over 95% patient satisfaction reported in clinical trials.
By Application:
Wrinkle Removal holds the dominant share within the application segment of the HA-based dermal fillers market. This dominance is attributed to the rising aging population and the growing demand for non-surgical solutions to address facial lines and wrinkles. Consumers increasingly seek safe, effective, and quick recovery options to maintain youthful appearances, which has boosted the use of HA fillers in wrinkle treatment. Additionally, strong marketing campaigns, growing social acceptance of aesthetic enhancements, and innovations in filler technologies have contributed to the expanding use of HA-based fillers in wrinkle correction over other applications like lip augmentation or scar treatment.
- For instance, Allergan’s Juvéderm® Ultra XC demonstrated significant wrinkle improvement in over 80% of patients at the 24-week clinical evaluation mark.
By End User:
Dermatology Clinics represent the leading end-user segment in the HA-based dermal fillers market, capturing the highest revenue share in 2024. This dominance is driven by the accessibility, specialization, and trusted expertise these clinics provide in cosmetic dermatology. Patients often prefer clinics for personalized consultations and skilled professionals capable of performing advanced aesthetic procedures. The rise in outpatient aesthetic treatments, coupled with the growing number of certified dermatology clinics globally, further supports this segment’s growth. In comparison, medical spas and ambulatory surgical centers are emerging but have yet to match the procedural volume and patient trust associated with dermatology clinics.
Key Growth Drivers
Rising Demand for Minimally Invasive Aesthetic Procedures
The growing consumer inclination toward non-surgical and minimally invasive aesthetic treatments significantly drives the HA-based dermal fillers market. These procedures offer shorter recovery times, lower risks, and cost-effective alternatives to traditional plastic surgeries. With increasing awareness of facial aesthetics and advancements in injection techniques, demand has surged globally. Millennials and Gen Z populations, influenced by social media and beauty standards, are increasingly opting for these treatments to enhance appearance, thereby boosting the adoption of HA-based fillers across clinics and medical spas.
- For instance, Merz Aesthetics launched Belotero Revive in over 20 countries within two years of CE mark approval, reflecting swift procedural uptake among younger demographics.
Aging Population and Growing Focus on Anti-Aging Solutions
Global demographic shifts, especially in developed nations, have led to a rapidly aging population seeking effective anti-aging treatments. HA-based dermal fillers help restore volume, reduce wrinkles, and rejuvenate skin, making them highly popular among individuals aged 40 and above. As longevity increases and older populations remain socially and professionally active, the demand for non-invasive aesthetic enhancements is accelerating. The preference for natural-looking, temporary yet effective results positions HA-based fillers as a leading solution in age-related cosmetic correction.
- For instance, LG Chem’s Yvoire Volume S achieved over 1.2 million annual syringes sold globally, largely driven by patients aged 45 and above seeking volume restoration.
Advancements in Filler Technology and Product Customization
Technological innovations in filler formulation and delivery methods have improved product performance, safety, and longevity. Cross-linking technologies have extended filler durability and enhanced their elasticity and integration into skin tissues. Moreover, manufacturers are introducing tailored solutions for specific facial areas-such as lips, cheeks, and under-eyes-offering practitioners better precision and results. The availability of customized, targeted fillers catering to varied aesthetic goals has broadened the consumer base and enhanced patient satisfaction, driving further market penetration.
Key Trends & Opportunities
Expansion of Aesthetic Procedures in Emerging Markets
Emerging economies in Asia-Pacific, Latin America, and the Middle East are witnessing a surge in demand for aesthetic procedures, including HA-based dermal fillers. Rising disposable income, increased awareness of cosmetic enhancements, and growing access to aesthetic clinics have contributed to this expansion. Medical tourism, particularly in countries like South Korea, Thailand, and Brazil, also plays a pivotal role. Global brands are investing in local partnerships and marketing strategies to tap into these high-growth regions, unlocking significant opportunities for future market expansion.
- For instance, BioPlus Co. Ltd. increased its overseas shipments of Dermalax® fillers by 48,721 units to Southeast Asian clinics within a single fiscal year.
Integration of Combination Therapies and Personalized Treatments
A growing trend in aesthetic medicine is the integration of dermal fillers with other cosmetic treatments such as botulinum toxin injections, laser resurfacing, and skin tightening procedures. This multimodal approach delivers more comprehensive and long-lasting results, attracting consumers seeking holistic rejuvenation. Additionally, there is rising demand for personalized treatment plans tailored to individual facial anatomy and aesthetic goals. This trend encourages practitioners to use data-driven assessments and targeted product selections, improving patient outcomes and satisfaction levels.
Key Challenges
Stringent Regulatory Requirements and Approval Delays
HA-based dermal fillers fall under medical device regulations in many countries, requiring thorough safety and efficacy evaluations before market approval. Varying regulatory frameworks across regions often lead to delayed product launches and increased compliance costs. Additionally, obtaining clinical trial data and securing approvals from regulatory agencies such as the U.S. FDA or the European Medicines Agency can be time-consuming. These hurdles limit rapid innovation and global expansion, especially for smaller or new market entrants.
- For instance, Anika Therapeutics faced a 13-month delay in U.S. market entry for its HA-based filler due to extended FDA review and additional post-market surveillance requirements.
Concerns Over Adverse Effects and Practitioner Expertise
While HA-based fillers are generally considered safe, concerns over side effects such as allergic reactions, vascular complications, or improper placement continue to affect consumer confidence. The outcome of filler treatments is highly dependent on practitioner expertise, and unqualified or poorly trained professionals can lead to suboptimal or harmful results. This risk underlines the need for proper training, certification, and patient education. As a result, regulatory bodies are placing increasing emphasis on safety protocols and practitioner qualifications.
High Treatment Costs and Limited Insurance Coverage
Despite growing demand, the relatively high cost of HA-based dermal filler treatments can restrict accessibility, particularly in cost-sensitive or uninsured populations. Most aesthetic procedures are considered elective and thus not covered by health insurance plans, requiring full out-of-pocket payment by patients. This financial barrier limits the frequency and adoption rate of such procedures, especially in developing markets. Providers must strike a balance between quality, affordability, and value to broaden patient reach and market adoption.
Regional Analysis
North America:
North America held the largest share of the HA-based dermal fillers market in 2024, accounting for approximately 43.3% of the global market with a value of USD 2,257.94 million, up from USD 1,248.33 million in 2018. This dominance is driven by the widespread adoption of minimally invasive cosmetic procedures, high consumer spending on aesthetics, and strong presence of key market players. With a projected CAGR of 10.8%, the market is expected to reach USD 5,444.58 million by 2032, supported by continuous product innovations, regulatory approvals, and growing demand for anti-aging solutions across dermatology clinics and medical spas.
- For instance, Allergan’s U.S.-based training network supported over 39,000 aesthetic professionals through the Allergan Medical Institute, significantly strengthening product application expertise in the region.
Europe:
Europe captured a significant market share of 17.5% in 2024, with the HA-based dermal fillers market reaching USD 913.01 million, up from USD 528.72 million in 2018. The region is marked by high awareness of aesthetic enhancements and an aging population seeking non-surgical rejuvenation treatments. With a CAGR of 9.5%, the market is projected to grow to USD 1,994.73 million by 2032. European countries such as Germany, France, and the UK are leading contributors, driven by robust healthcare infrastructure, favorable reimbursement scenarios in selective cases, and growing demand for facial enhancement procedures.
- For instance, Teoxane Laboratories, headquartered in Switzerland, reported distribution of over 2.4 million syringes across 90 European clinics in a single year through its Teosyal® range.
Asia Pacific:
Asia Pacific is the fastest-growing regional market, registering a CAGR of 12.0%. In 2024, it reached USD 1,609.89 million, rising from USD 834.76 million in 2018, and is projected to reach USD 4,217.93 million by 2032, holding a 30.9% share of the global market. Growth is propelled by rising disposable incomes, increasing popularity of aesthetic treatments, and the influence of social media beauty trends, especially in countries like South Korea, China, and Japan. Additionally, the expansion of medical tourism and affordable cosmetic procedures in the region continue to attract both local and international consumers.
Latin America:
Latin America accounted for 4.7% of the HA-based dermal fillers market in 2024, with a value of USD 243.94 million, growing from USD 135.14 million in 2018. The region is expected to expand at a CAGR of 9.1%, reaching USD 519.33 million by 2032. The market is primarily driven by increasing urbanization, rising awareness about aesthetic procedures, and the growth of cosmetic medical tourism, particularly in Brazil and Mexico. Improved access to skilled professionals and the rising influence of Western beauty standards are further fueling the adoption of HA-based dermal fillers across the region.
Middle East:
The Middle East region captured a 2.6% market share in 2024, with the market reaching USD 134.15 million, up from USD 80.26 million in 2018. Projected to grow at a CAGR of 8.5%, the market is expected to attain USD 272.40 million by 2032. The rising interest in cosmetic procedures among affluent consumers, increasing investment in aesthetic clinics, and cultural acceptance of aesthetic enhancement contribute to regional growth. Countries such as the UAE and Saudi Arabia are witnessing a surge in demand due to improved healthcare infrastructure and growing medical tourism in cosmetic dermatology.
Africa:
Africa accounted for a modest 1.1% share of the global HA-based dermal fillers market in 2024, with the market valued at USD 58.08 million, increasing from USD 27.15 million in 2018. The region is forecasted to grow at a CAGR of 5.6%, reaching USD 95.99 million by 2032. Growth is gradually improving due to rising urbanization, increasing awareness of aesthetic procedures, and expanding access to cosmetic treatments in urban centers. However, limited healthcare infrastructure, affordability issues, and lower disposable income continue to pose challenges for rapid market penetration across the continent.
Market Segmentations:
By Product:
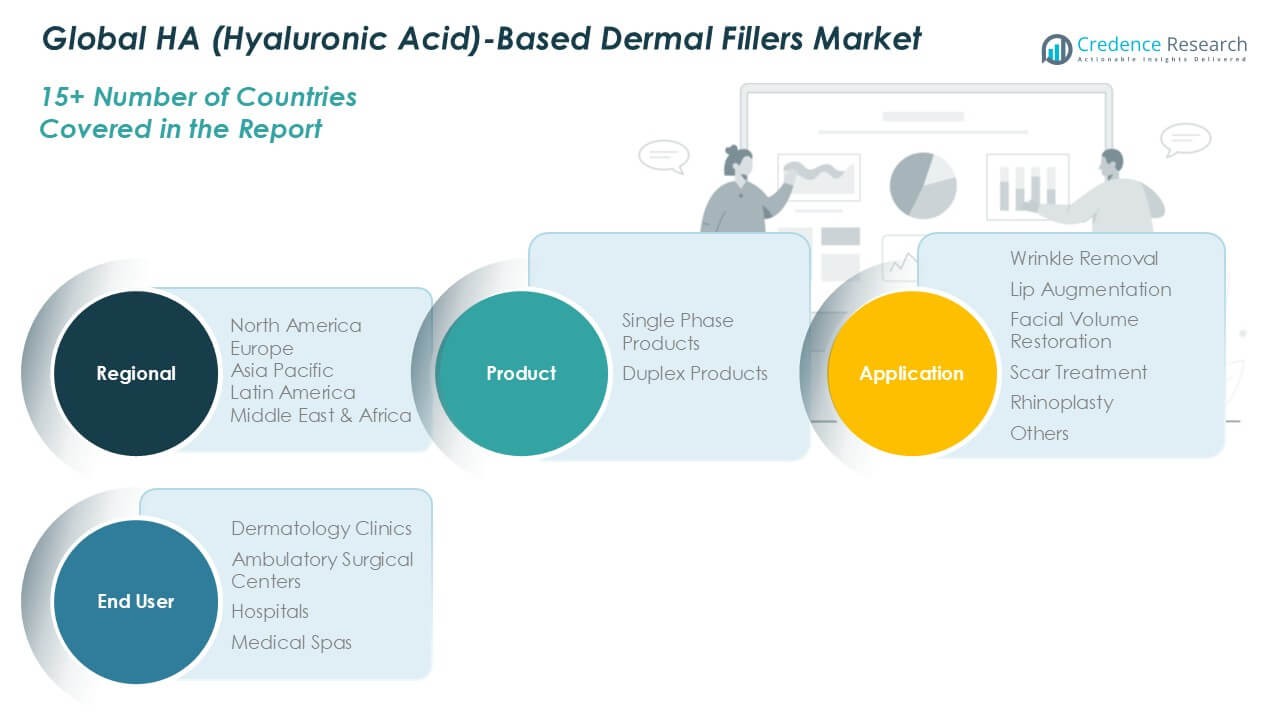
- Single Phase Products
- Duplex Products
By Application:
- Wrinkle Removal
- Lip Augmentation
- Facial Volume Restoration
- Scar Treatment
- Rhinoplasty
- Others
By End User:
- Dermatology Clinics
- Ambulatory Surgical Centers
- Hospitals
- Medical Spas
By Geography:
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Competitive Landscape
The competitive landscape of the HA (Hyaluronic Acid)-based dermal fillers market is characterized by the presence of several prominent players focused on innovation, global expansion, and product differentiation. Key companies such as Allergan, Galderma Laboratories, Merz Pharmaceuticals, and LG Chem dominate the market with extensive product portfolios, robust distribution networks, and strong brand recognition. These firms continually invest in R&D to develop advanced formulations that offer longer-lasting effects, improved safety profiles, and targeted applications for facial aesthetics. Strategic collaborations, mergers, and acquisitions are frequently employed to enhance market presence and expand geographic reach. New entrants and smaller companies, including Bioxis Pharmaceutical and Anika Therapeutics, are leveraging niche innovations and localized strategies to gain traction. Additionally, companies are focusing on physician training and awareness campaigns to strengthen customer loyalty and procedure adoption. As consumer demand for minimally invasive aesthetic treatments grows, competition is expected to intensify, driving further advancements and pricing strategies across global markets.
- For instance, Galderma conducted over 3,800 clinical workshops globally under its AART program to ensure standardized injection techniques and physician proficiency.
Key Player Analysis
- Allergan
- Galderma Laboratories
- Genzyme Corporation
- Anika Therapeutics Inc.
- Sculpt Luxury
- Dermal Fillers Ltd.
- Bioxis Pharmaceutical
- Merz Pharmaceuticals
- LG Life Sciences
- LTD (LG Chem)
- Bio plus Co. Ltd.
Recent Developments
- In June 2025, Allergan's SKINVIVE by JUVÉDERM received FDA review for neck appearance improvement, potentially becoming the first hyaluronic acid (HA) microdroplet injectable approved for this specific use in the U.S.
- In June 2023, Galderma Laboratories launched Restylane Eyelight, a hyaluronic acid dermal filler utilizing NASHA Technology specifically designed for treating undereye hollows. This filler is intended to reduce shadows and improve the overall appearance of the under-eye area, with results potentially lasting up to 18 months. It's the first and only product in the U.S. to use NASHA Technology for this purpose.
- In August 2022, AbbVie received FDA approval for JUVÉDERM VOLUX XC, as a hyaluronic acid based filler to improve jawline definition. It is the first product to receive this certification.
- In June 2022, Prollenium Medical Technologies acquired SoftFil for an undisclosed amount. SoftFil is a France-based aesthetic medicine company.
- In April 2022, Sinclair Company introduced Perfectha Lidocaine, a hyaluronic acid-based dermal filler for wrinkle removal, facial contouring, and facial volume restoration.
Market Concentration & Characteristics
The HA (Hyaluronic Acid)-Based Dermal Fillers Market demonstrates a moderately concentrated structure, with a few key players holding a significant share of global revenue. Companies such as Allergan, Galderma Laboratories, and Merz Pharmaceuticals lead the market through established product lines, widespread physician adoption, and strong geographic reach. It reflects high brand loyalty among dermatologists and end users, largely due to clinical performance, safety profiles, and practitioner support. The market favors companies that invest in research and development to create advanced formulations with improved longevity and targeted applications. Entry barriers remain high due to regulatory requirements, product approval timelines, and the need for medical expertise in administration. It shows a strong preference for products that deliver natural-looking results with minimal downtime. Consumer trust in practitioner skill and product quality shapes purchasing behavior. Established regions like North America and Europe contribute the most to global revenues, while Asia Pacific shows the fastest growth in procedure volumes and product adoption.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow steadily driven by rising demand for non-surgical aesthetic procedures.
- Aging populations across developed regions will increase the use of HA-based fillers for wrinkle reduction and facial volume restoration.
- Technological advancements will lead to the development of longer-lasting and more natural-looking dermal filler products.
- North America will maintain its leading market position due to strong consumer spending and high practitioner expertise.
- Asia Pacific will experience the fastest growth due to expanding medical tourism, increasing awareness, and growing disposable income.
- Single phase products will remain the preferred choice among practitioners due to ease of use and consistent outcomes.
- Wrinkle removal will continue to lead among applications, supported by broad consumer demand across age groups.
- Dermatology clinics will retain dominance among end users due to trusted expertise and growing procedural volumes.
- Companies will increase focus on physician training and safety protocols to enhance treatment outcomes and brand loyalty.
- Regulatory clarity and market expansion into underserved regions will shape long-term industry growth strategies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Preference for Minimally Invasive Aesthetic Procedures
Consumers are increasingly opting for non-surgical, minimally invasive treatments like HA-based dermal fillers due to shorter recovery times, lower risks, and cost-effectiveness compared to traditional surgery. This trend is especially strong among younger demographics influenced by social media and beauty standards.
Aging Population and Demand for Anti-Aging Solutions
The global rise in the aging population, particularly in developed regions, is fueling demand for HA-based fillers to address wrinkles, volume loss, and other age-related facial changes. Older adults are seeking effective, natural-looking, and temporary solutions to maintain a youthful appearance.
Technological Advancements and Product Customization
Innovations in filler formulations, such as improved cross-linking technologies and targeted products for specific facial areas, have enhanced the safety, longevity, and natural results of HA-based fillers. This has broadened the appeal and increased adoption among both practitioners and patients.
Expansion in Emerging Markets and Medical Tourism
Rising disposable incomes, greater awareness of aesthetic procedures, and the growth of medical tourism in regions like Asia Pacific and Latin America are expanding the market. Global brands are investing in local partnerships and marketing to tap into these high-growth regions.
Strong Practitioner Training and Brand Loyalty
Leading companies invest heavily in physician training and support, ensuring safe and effective product use. This builds strong brand loyalty among dermatologists and clinics, further driving market penetration and repeat procedures.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for HA (Hyaluronic Acid)-Based Dermal Fillers, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the HA (Hyaluronic Acid)-Based Dermal Fillers market projected to grow between 2025 and 2032?
Which HA (Hyaluronic Acid)-Based Dermal Fillers market segment held the largest share in 2024?
What are the primary factors fueling the growth of the HA (Hyaluronic Acid)-Based Dermal Fillers market?
Who are the leading companies in the HA (Hyaluronic Acid)-Based Dermal Fillers market?
Which region commanded the largest share of the HA (Hyaluronic Acid)-Based Dermal Fillers market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Single Phase Products
- 1.2.2 Duplex Products
- 1.3 By End User
- 1.3.1 Dermatology Clinics
- 1.3.2 Ambulatory Surgical Centers
- 1.3.3 Hospitals
- 1.3.4 Medical Spas
- 1.4 By Application
- 1.4.1 Wrinkle Removal
- 1.4.2 Lip Augmentation
- 1.4.3 Facial Volume Restoration
- 1.4.4 Scar Treatment
- 1.4.5 Rhinoplasty
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,216.99 million → 2032: USD 12,544.97 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hyaluronic Acid-Based Dermal Fillers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hyaluronic Acid-Based Dermal Fillers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hyaluronic Acid-Based Dermal Fillers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hyaluronic Acid-Based Dermal Fillers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hyaluronic Acid-Based Dermal Fillers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hyaluronic Acid-Based Dermal Fillers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hyaluronic Acid-Based Dermal Fillers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hyaluronic Acid-Based Dermal Fillers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,216.99 million → 2032: USD 12,544.97 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hyaluronic Acid-Based Dermal Fillers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single Phase Products
- 12.3.7.2 Duplex Products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dermatology Clinics
- 12.4.7.2 Ambulatory Surgical Centers
- 12.4.7.3 Hospitals
- 12.4.7.4 Medical Spas
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Wrinkle Removal
- 12.5.7.2 Lip Augmentation
- 12.5.7.3 Facial Volume Restoration
- 12.5.7.4 Scar Treatment
- 12.5.7.5 Rhinoplasty
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hyaluronic Acid-Based Dermal Fillers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hyaluronic Acid-Based Dermal Fillers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hyaluronic Acid-Based Dermal Fillers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hyaluronic Acid-Based Dermal Fillers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Allergan
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Galderma Laboratories
- 18.4 Merz Pharmaceuticals
- 18.5 LG Chem
- 18.6 Anika Therapeutics
- 18.7 Bioxis Pharmaceutical
- 18.8 Genzyme Corporation
- 18.9 Sculpt Luxury
- 18.10 Dermal Fillers Ltd.
- 18.11 Bio plus Co. Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

