
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aesthetic Medicine Market Size 2024 | USD 1006.5 million |
| Aesthetic Medicine Market , CAGR | 7.2% |
| Aesthetic Medicine Market Size 2032 | USD 1755.38 million |
Market Overview
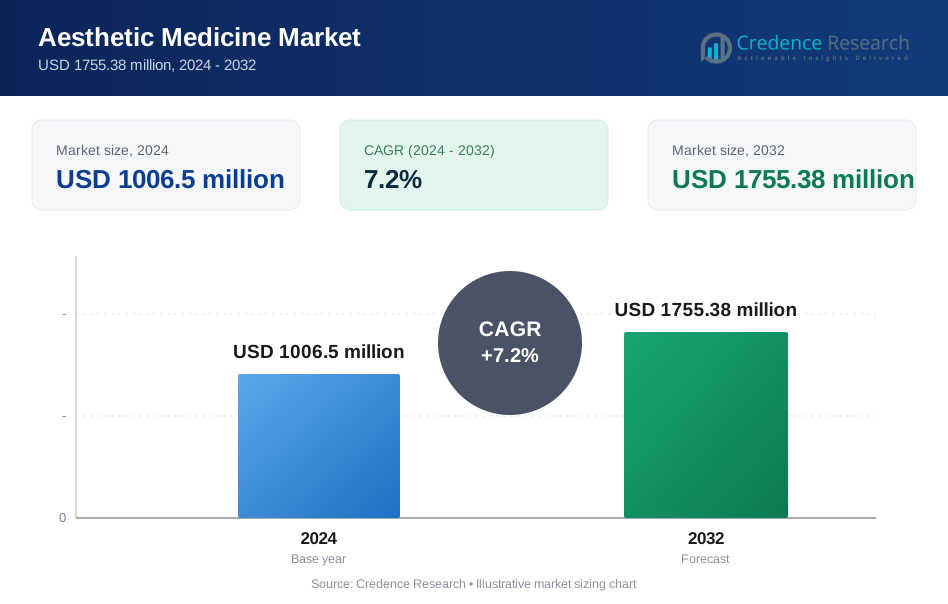
The global aesthetic medicine market is poised for substantial growth, with its value projected to rise from USD 1006.5 million in 2024 to an estimated USD 1755.38 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.2%.
Several key factors are driving this market expansion. A primary driver is the increasing demand for non-invasive cosmetic procedures, as individuals seek safer, less intrusive alternatives to traditional surgery. Additionally, there is a growing emphasis on physical appearance, coupled with heightened awareness of the benefits of aesthetic treatments. These factors are fuelling demand for services such as dermal fillers, botulinum toxin injections, and laser therapies. Technological advancements are also playing a crucial role in propelling market growth. The development of minimally invasive procedures, alongside innovations in aesthetic treatments, has made cosmetic procedures more accessible and efficient. As a result, these treatments are becoming increasingly popular, particularly for anti-ageing and rejuvenation purposes. The ageing population in developed regions further accelerates demand for such services. Social media also significantly impacts the aesthetic medicine market. As beauty standards evolve, many individuals are turning to cosmetic procedures to align with trends set by influencers and celebrities. This societal influence is driving the widespread adoption of aesthetic treatments.
Geographically, North America holds a dominant position in the market due to a high adoption rate of aesthetic procedures, a concentration of key industry players, and an increasing number of cosmetic surgery centres. Europe follows closely, with rising demand for anti-ageing treatments. The Asia Pacific region is expected to see substantial growth, particularly in countries like South Korea, Japan, and China, due to a combination of rising disposable incomes and a growing beauty-conscious population. Other regions, including Latin America and the Middle East & Africa, are also experiencing growth, thanks to affordable treatment options and increasing consumer interest in aesthetic procedures.
Market insights
- The Aesthetic Medicine Market is expected to grow from USD 1006.5 million in 2024 to USD 1755.38 million by 2032, with a CAGR of 7.2% from 2024 to 2032.
- Rising demand for non-invasive cosmetic procedures, driven by a growing emphasis on appearance and the desire for youthful looks, is fuelling market growth.
- Technological advancements in minimally invasive treatments, such as botulinum toxin injections, dermal fillers, and laser therapies, are contributing significantly to market expansion.
- Increasing popularity of anti-ageing and rejuvenation treatments, especially among ageing populations in developed regions, is a key market trend.
- Social media’s influence on beauty standards is driving demand for aesthetic treatments, as more individuals seek enhancements to align with trends.
- North America leads the market due to high adoption rates of aesthetic procedures, along with a strong presence of cosmetic surgery centres and key industry players.
- Asia Pacific, especially countries like South Korea, Japan, and China, is experiencing rapid market growth, driven by rising disposable incomes and growing beauty-conscious populations.
Market Drivers
Growing Demand for Non-Invasive Procedures
The aesthetic medicine market is experiencing significant growth, driven by a combination of societal, technological, and economic factors. One of the primary drivers of market expansion is the increasing demand for non-invasive and minimally invasive cosmetic procedures. As patients seek more accessible and less risky alternatives to traditional surgery, treatments such as Botox injections, dermal fillers, and laser skin resurfacing have gained considerable popularity. For instance, a 2023 survey showed that 78% of cosmetic patients preferred non-invasive treatments over surgical ones. The desire for quick recovery times and minimal discomfort has also fuelled the preference for these procedures, enhancing their appeal among a broader demographic.
Increased Awareness and Acceptance of Aesthetic Procedures
Another key driver is the growing awareness and acceptance of aesthetic procedures across different age groups. With the rise of social media and digital platforms, individuals are increasingly exposed to beauty and wellness trends, resulting in a higher willingness to undergo aesthetic treatments. For example, social media platforms like Instagram and TikTok have seen a 25% increase in posts related to aesthetic procedures in 2023. Both younger and older generations are adopting aesthetic procedures, driven by the desire to enhance their appearance or maintain a youthful look. The number of individuals aged 65 and older is projected to reach 1.5 billion by 2050, increasing the demand for anti-ageing treatments.
Technological Advancements in Aesthetic Medicine
Technological advancements in aesthetic medicine are also playing a crucial role in the market's expansion. Innovations in non-invasive technologies, including high-intensity focused ultrasound (HIFU), cryolipolysis, and advanced laser technologies, have enhanced the effectiveness and safety of aesthetic procedures. For instance, HIFU treatments have been shown to improve skin laxity by 45% after just one session. These breakthroughs allow for more targeted treatments with fewer side effects and shorter recovery times. AI algorithms can analyse a patient's skin type and recommend the optimal treatment settings, leading to a 95% satisfaction rate.
Economic Factors and Growing Disposable Income
Economic factors, such as rising disposable income and the willingness to spend on cosmetic treatments, are supporting the market's growth. As economic conditions improve in emerging markets and the affordability of aesthetic procedures increases, more individuals are opting for treatments to improve their physical appearance. For instance, disposable income in emerging markets like India saw a rise of over 10% in the last decade, allowing more individuals to access these treatments. Medical tourism in countries like Thailand and South Korea has increased by 30% in the past five years, attracting international patients seeking affordable, high-quality aesthetic treatments. These economic shifts are expanding the customer base for aesthetic medicine, reinforcing the sector’s ongoing expansion.
Market Trends:
Rise in Non-Invasive Procedures
A dominant trend in the aesthetic medicine market is the continued shift toward non-invasive and minimally invasive procedures. As patients increasingly seek alternatives to traditional surgical methods, non-invasive treatments such as Botox injections, dermal fillers, and laser therapies have become more popular. For instance, a survey conducted in 2023 indicated a 30% increase in the number of patients opting for non-invasive treatments over the past five years. These procedures offer significant aesthetic benefits with minimal downtime, making them more attractive to individuals looking for quicker, safer, and less disruptive solutions. As technology continues to evolve, these treatments are becoming more effective, precise, and accessible, contributing to the expansion of the market.
Technological Advancements in Treatment Modalities
Advancements in technology are playing a key role in shaping current trends within the aesthetic medicine market. New technologies, such as high-intensity focused ultrasound (HIFU), radiofrequency (RF) devices, and advanced laser systems, have significantly enhanced treatment outcomes. For instance, HIFU treatments have been shown to improve skin laxity by 45% after just one session. These innovations allow for more efficient and targeted treatments, addressing a wide range of aesthetic concerns, including skin rejuvenation, body contouring, and acne scar removal. The integration of artificial intelligence (AI) and machine learning into treatment planning and patient management is also emerging as a trend, enabling more personalised, data-driven approaches to aesthetics.
Increased Demand for Anti-Ageing Solutions
As the global population ages, there is a growing demand for aesthetic treatments aimed at combating the visible signs of ageing. Anti-ageing procedures, including wrinkle treatments, skin tightening, and pigmentation reduction, are increasingly popular among older adults seeking to maintain a youthful appearance. For instance, the number of individuals aged 65 and older is projected to reach 1.5 billion by 2050, further driving the demand for anti-ageing treatments. The demand for these treatments is particularly prominent in developed regions, where ageing populations are more prevalent. Non-surgical facelifts using HIFU can improve skin elasticity by up to 35% in just one session. The rising acceptance and accessibility of these treatments have led to a surge in demand for aesthetic procedures that offer both preventive and corrective solutions for ageing-related concerns.
Social Media Influence and Consumer Awareness
Social media platforms have become powerful drivers of trends in the aesthetic medicine market. Celebrities, influencers, and even everyday users share their experiences with aesthetic procedures, which has helped normalise cosmetic treatments and reduce the stigma associated with them. For example, the hashtag #skinrejuvenation saw a 25% increase in posts on Instagram in 2023, reflecting the rising interest in these treatments. This growing visibility on social media has led to heightened consumer awareness and a broader acceptance of aesthetic treatments. As consumers become more informed about the range of available options and their potential benefits, they are increasingly seeking treatments to enhance their appearance and align with contemporary beauty standards.
Market Challenge Analysis:
Regulatory and Compliance Challenges
One of the significant challenges facing the aesthetic medicine market is the complex and evolving regulatory landscape. Different countries have varying regulations governing the approval, marketing, and use of aesthetic treatments and products. For instance, in the U.S., the FDA requires rigorous clinical trials and documentation before granting approval for treatments like dermal fillers or Botox, which can delay market entry for new innovations. Additionally, with the rapid growth of the market, there is an increasing risk of non-compliant practitioners and unregulated products, leading to concerns about safety and treatment quality. This necessitates continuous monitoring and adherence to regulatory standards, placing an operational burden on manufacturers and practitioners to ensure compliance, especially in emerging markets where regulations might be less stringent.
Consumer Awareness and Ethical Concerns
Another challenge is addressing consumer awareness and the ethical concerns surrounding aesthetic procedures. Despite growing acceptance, some potential patients remain sceptical of the risks involved with aesthetic treatments, such as complications or unsatisfactory results. For instance, adverse events related to non-surgical procedures, such as facial disfigurement or allergic reactions, can undermine consumer trust. Furthermore, there is an ongoing debate about the ethics of promoting beauty standards that may foster unrealistic expectations, particularly among younger generations. As a result, practitioners must invest in educating clients about the risks, benefits, and realistic outcomes of aesthetic procedures to build trust and manage expectations. Ensuring patient safety and addressing ethical concerns around body image also remain a critical challenge in fostering long-term market growth.
Market Opportunities
The aesthetic medicine market presents several opportunities driven by technological advancements and evolving consumer preferences. Non-invasive treatments continue to gain traction as patients increasingly seek procedures with minimal recovery times and reduced risks compared to traditional surgery. With innovations in laser technologies, injectables like Botox and dermal fillers, and fat reduction treatments, the market is poised for further growth. Moreover, advancements in personalised treatments, such as AI-driven skin analysis, enable practitioners to offer highly tailored solutions, enhancing patient satisfaction and expanding the scope of aesthetic treatments. These innovations provide a significant opportunity for both established players and new entrants to differentiate themselves in a competitive market by offering cutting-edge, effective treatments.
Additionally, the growing acceptance of aesthetic procedures across diverse age groups and demographics represents a valuable opportunity. The ageing global population, particularly in developed countries, is driving demand for anti-ageing treatments, while younger generations are becoming more proactive about maintaining their appearance. Markets in emerging economies also present significant growth potential due to rising disposable income, increasing awareness of aesthetic options, and a growing desire for beauty enhancements. As consumer access to financing options, such as payment plans and medical tourism, improves, more individuals are seeking high-quality aesthetic procedures. This broadening customer base, combined with technological innovation, offers ample opportunities for growth and expansion in the aesthetic medicine sector.
Market Segmentation Analysis:
By Product and Device The market includes a diverse range of products and devices such as botulinum toxins, dermal fillers, chemical peels, body contouring devices, gluteal implants, hair removal devices, and breast implants. These products cater to various patient needs, from wrinkle reduction to body shaping and skin rejuvenation. Botulinum toxin and dermal fillers dominate the non-invasive segment, while devices like body contouring and hair removal are seeing rising demand due to their effectiveness and minimal recovery time.
By Procedure Type
The aesthetic medicine market is also divided into non-invasive, minimally invasive, and invasive procedures. Non-invasive treatments, including Botox and dermal fillers, lead the market due to their convenience, cost-effectiveness, and reduced recovery time. Minimally invasive procedures, such as liposuction or laser treatments, also have a strong market presence due to a balance of effectiveness and less risk compared to fully invasive surgeries. Invasive procedures, including breast and gluteal implants, continue to cater to patients seeking more dramatic, permanent changes.
By End-User
The primary end-users of aesthetic treatments include hospitals, clinics, med spas, and dermatology or cosmetology centres. Hospitals are generally more focused on invasive surgeries, while clinics and med spas cater to both non-invasive and minimally invasive treatments.
Segmentation:
Based on the type of product and/or device offered
- Botulinum Toxin
- Dermal Fillers
- Chemical Peels
- Body Contouring
- Gluteal Implants
- Hair Removal
- Breast Implants
- Other Products/Devices
Based on Type of Procedure
- Non-Invasive
- Minimally Invasive
- Invasive
Based on End User
- Hospitals
- Clinics/Med Spas and Dermatology/Cosmetology Centres
- Other End Users
Based on Gender
- Male
- Female
Based on Distribution Channel
- Direct Distribution
- Indirect Distribution
Based on Regions
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America dominates the aesthetic medicine market, holding 38% of the global share. The region’s growth is fuelled by high consumer spending on cosmetic procedures, a well-developed healthcare infrastructure, and the widespread availability of advanced aesthetic treatments. The United States leads the market, driven by the strong presence of dermatology clinics, plastic surgery centres, and medical spas. Additionally, the increasing adoption of non-invasive and minimally invasive procedures, such as Botox, dermal fillers, and laser-based skin treatments, is further boosting market expansion. For instance, the rising popularity of body contouring and skin tightening procedures has led to the increased demand for energy-based aesthetic devices. Canada and Mexico are also witnessing steady market growth, supported by increasing awareness of aesthetic medicine and the growing influence of social media on beauty trends.
Europe
Europe holds a significant 30% market share, driven by an ageing population, rising aesthetic consciousness, and technological advancements in aesthetic procedures. Countries such as Germany, France, the UK, Italy, and Spain are leading contributors, benefiting from the increasing number of aesthetic clinics and well-established medical tourism industries. The region’s demand for non-surgical treatments, including laser skin resurfacing, anti-ageing therapies, and body sculpting procedures, continues to grow. For instance, the adoption of regenerative aesthetics, such as stem cell-based skin rejuvenation, is gaining traction across European markets. Furthermore, regulatory approvals for advanced aesthetic devices and the growing preference for personalised treatments are strengthening market expansion. Additionally, the increasing affordability of aesthetic procedures is encouraging a larger consumer base to seek cosmetic enhancements.
Asia-Pacific
Asia-Pacific is emerging as the fastest-growing region in the aesthetic medicine market, holding 25% of the global share. The region’s growth is driven by increasing disposable incomes, rising aesthetic awareness, and a booming medical tourism industry. Countries such as South Korea, Japan, China, and India are at the forefront, offering cost-effective and high-quality aesthetic treatments. For instance, South Korea has established itself as a global hub for aesthetic medicine, attracting international patients seeking advanced skincare, laser treatments, and cosmetic surgeries. Additionally, the influence of social media and changing beauty standards are driving younger demographics to opt for preventative aesthetic treatments. The expansion of dermatology clinics and the availability of innovative technologies, including AI-driven skin analysis and energy-based devices, are further propelling market growth across the region.
Key Player Analysis:
- AbbVie Inc. (US)
- Alma Lasers (Israel)
- Cynosure (US)
- Lutronic (US)
- Johnson & Johnson Services, Inc. (US)
- Bausch Health Companies Inc. (Canada)
- Cutera, Inc. (US)
- Galderma (Switzerland)
- En. S.p.A. (Italy)
- InMode Ltd. (Israel)
Competitive Analysis:
The aesthetic medicine market is highly competitive, with key players focusing on innovation, product differentiation, and expanding their geographic reach. Major companies, including Allergan, Galderma, and Revance Therapeutics, dominate the injectables and dermal filler segments, while others like Cynosure and Cutera lead the laser technology space. These companies invest heavily in research and development to introduce cutting-edge, non-invasive treatments that cater to the growing demand for minimally invasive procedures. Additionally, smaller, emerging players are increasingly entering the market with specialised devices and niche products, offering competition through targeted solutions and competitive pricing. To maintain a competitive edge, companies are also focusing on strategic partnerships, mergers, and acquisitions. With rising consumer awareness, digital marketing strategies, and a shift toward personalised treatments, maintaining customer loyalty and building trust remain crucial. As the market continues to grow, competition will intensify, driving further innovation and advancements in aesthetic medicine.
Recent Developments:
- In October 2024, Allergan Aesthetics, a division of AbbVie Inc. (US), received FDA approval for BOTOX Cosmetic to treat moderate to severe platysma bands, the vertical bands running from the jaw to the neck.
- In January 2024, Galderma (Switzerland) gained regulatory approval for Restylane SHAYPE, a hyaluronic acid injectable designed to enhance the chin area, providing a bone-like effect to shape the lower face. It uses NASHA HD technology to deliver natural-looking, long-lasting results for up to 12 months.
- In May 2023, AbbVie Inc. secured FDA approval for SKINVIVE by JUVÉDERM, an innovative hyaluronic acid (HA) intradermal microdroplet injection aimed at improving cheek skin smoothness in adults aged 21 and older.
- In April 2023, Galderma announced the FDA approval of Sculptra, an injectable poly-L-lactic acid (PLLA-SCA), to correct fine lines and wrinkles in the cheek area.
Market Concentration & Characteristics:
The aesthetic medicine market is moderately concentrated, with a few dominant players holding significant market share, particularly in injectables, dermal fillers, and laser technologies. Major companies such as Allergan, Galderma, and Merz Pharmaceuticals lead the market, benefiting from strong brand recognition, extensive product portfolios, and established distribution networks. However, the market also features a growing number of smaller, specialised companies that focus on niche treatments and innovative technologies. These players often compete on product differentiation, technological advancements, and targeted solutions, particularly in non-invasive treatments like fat reduction and skin rejuvenation. The market is characterised by rapid innovation, with companies investing heavily in research and development to meet evolving consumer demands for minimally invasive, safe, and effective treatments. As the market expands globally, particularly in emerging economies, there is an increasing trend toward strategic partnerships and acquisitions, shaping the competitive landscape and fostering further industry consolidation.
Report Coverage:
The research report offers an in-depth analysis based on product type, procedure, end-user, gender, distribution channel and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, a SWOT analysis, and current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The aesthetic medicine market will continue to expand as demand for non-invasive procedures increases globally.
- Technological advancements in lasers, injectables, and energy-based devices will drive innovation, improving treatment outcomes and patient satisfaction.
- Rising disposable income in emerging markets will provide new growth opportunities for aesthetic treatments.
- Personalised treatments powered by artificial intelligence and advanced diagnostics will become more prevalent, offering tailored solutions for individual patients.
- An ageing population in developed countries will fuel demand for anti-ageing treatments, particularly among the 50+ demographic.
- Social media platforms will continue to influence consumer decisions, increasing awareness and demand for aesthetic procedures.
- Regulatory frameworks will become more standardised globally, improving patient safety and treatment reliability.
- Strategic partnerships and acquisitions will become common as companies seek to expand their portfolios and reach new markets.
- As medical tourism grows, countries like Thailand, South Korea, and Mexico will become key destinations for affordable, high-quality aesthetic treatments.
- Ethical considerations and patient education will play an increasingly significant role in shaping industry standards and consumer trust in aesthetic medicine.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the aesthetic medicine market?
What are the key segments within the aesthetic medicine market?
Who are the major players in the aesthetic medicine market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aesthetic Medicine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aesthetic Medicine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1006.5 million → 2032: USD 1755.38 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aesthetic Medicine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aesthetic Medicine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aesthetic Medicine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aesthetic Medicine Market Drivers
- 3.3 Aesthetic Medicine Market Restraints & Challenges
- 3.4 Aesthetic Medicine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aesthetic Medicine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aesthetic Medicine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aesthetic Medicine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aesthetic Medicine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aesthetic Medicine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aesthetic Medicine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aesthetic Medicine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aesthetic Medicine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aesthetic Medicine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aesthetic Medicine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aesthetic Medicine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aesthetic Medicine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aesthetic Medicine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aesthetic Medicine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aesthetic Medicine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aesthetic Medicine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aesthetic Medicine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aesthetic Medicine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aesthetic Medicine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
