
Market Overview:
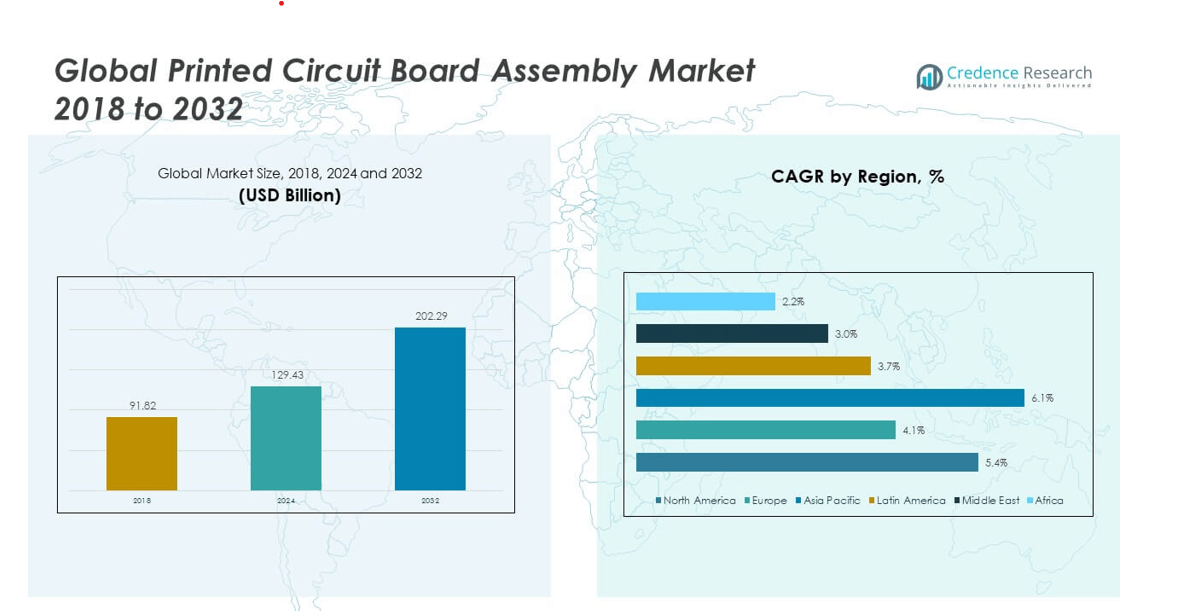
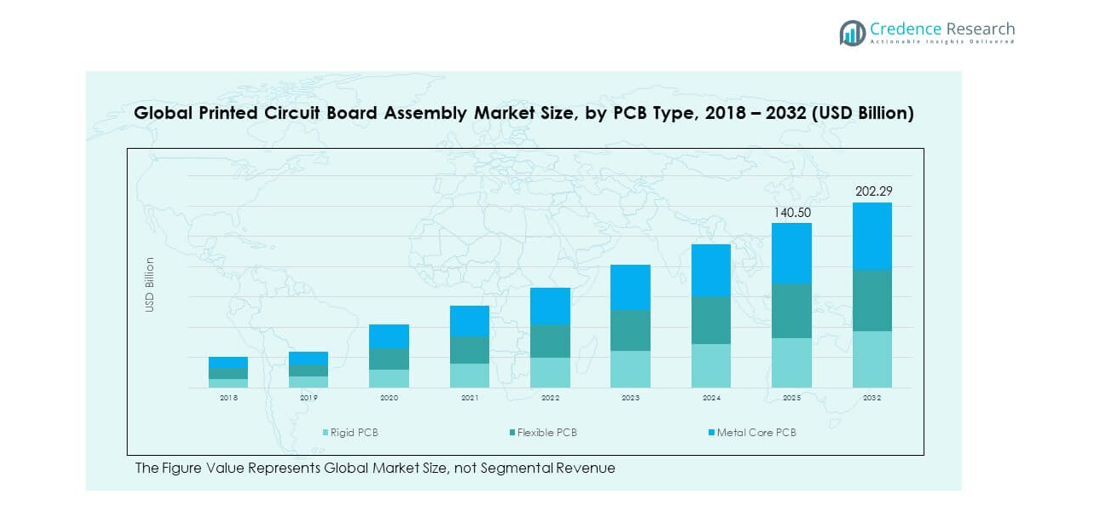
The Global Printed Circuit Board Assembly Market size was valued at USD 91.82 million in 2018, increased to USD 129.43 million in 2024, and is anticipated to reach USD 202.29 million by 2032, at a CAGR of 5.34% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Printed Circuit Board Assembly Market Size 2024 | USD 129.43 million |
| Printed Circuit Board Assembly Market, CAGR | 5.34% |
| Printed Circuit Board Assembly Market Size 2032 | USD 202.29 million |
Rising demand for compact, high-performance electronic devices drives strong growth in the Global Printed Circuit Board Assembly Market. The expansion of consumer electronics, automotive electronics, and industrial automation fuels widespread adoption of advanced PCB technologies. Increasing miniaturization, higher circuit density, and the use of multilayer designs enhance performance and efficiency. Rapid technological advancements in IoT devices, 5G infrastructure, and renewable energy systems further boost production. Manufacturers are also emphasizing lead-free and eco-friendly assembly processes to align with global environmental regulations.
Asia Pacific leads the market due to large-scale electronics manufacturing hubs in China, Japan, and South Korea. North America shows steady growth supported by innovation in aerospace, defense, and medical electronics. Europe follows with strong automotive electronics and industrial automation applications. Emerging regions such as Southeast Asia and Latin America are gaining traction with expanding industrial bases and rising consumer electronics demand. The global ecosystem remains dynamic, driven by technology upgrades and regional manufacturing competitiveness.
Market Insights:
- The Global Printed Circuit Board Assembly Market was valued at USD 91.82 billion in 2018, reached USD 129.43 billion in 2024, and is projected to reach USD 202.29 billion by 2032, growing at a CAGR of 5.34% during the forecast period.
- Asia Pacific holds the largest regional share of 45%, driven by strong manufacturing capacity in China, Japan, and South Korea. North America follows with 28%, supported by advanced automation and aerospace demand, while Europe captures 17%, benefiting from automotive electronics and sustainable manufacturing.
- Asia Pacific is the fastest-growing region, expanding at a 1% CAGR. The growth is fueled by increasing production of consumer electronics, electric vehicles, and semiconductor integration across major economies.
- Rigid PCBs dominate the market with an estimated 55% share, favored for their strength and wide industrial and automotive use.
- Flexible and metal core PCBs together account for roughly 45% share, driven by their rising use in compact devices, LED systems, and power electronics applications.
Market Drivers:
Rising Demand for Miniaturized and High-Performance Electronic Devices
The Global Printed Circuit Board Assembly Market is driven by the growing need for compact and efficient electronic components. Consumer devices such as smartphones, tablets, and wearables require dense circuitry to support faster processing and multifunctional capabilities. Manufacturers are adopting advanced PCB assembly technologies like surface-mount technology to meet these requirements. Integration of microchips and high-speed connectors enhances power efficiency and system reliability. IoT expansion across industries further accelerates adoption of miniaturized assemblies. The push for smaller yet powerful devices boosts multilayer PCB demand. Continuous innovation in semiconductors and packaging increases design complexity. These developments strengthen the role of PCB assemblies in modern electronics.
- For instance, recent flagship mobile phones utilize HDI PCBs featuring 8 to 12 layers within boards less than 1 mm thick, with fine trace widths as small as 0.075 mm, promoting faster signal transmission and enhanced reliability in compact spaces.
Expansion of Automotive Electronics and Advanced Driver Assistance Systems (ADAS)
Rising integration of electronic control units and sensors in vehicles fuels market growth. Automakers depend on PCBs for infotainment, engine control, and safety systems. The transition toward electric and hybrid vehicles intensifies the use of complex multilayer boards. Increasing adoption of ADAS features like lane detection and collision avoidance enhances demand for high-reliability PCB assemblies. Manufacturers are focusing on thermal management and vibration resistance to support harsh automotive conditions. Automotive-grade PCBs ensure consistent performance under fluctuating temperatures and electrical loads. The growing use of autonomous technologies further pushes electronic content per vehicle. This trend solidifies the automotive segment’s contribution to the market.
- For instance, autonomous vehicle designs integrate multi-layer HDI boards and flexible PCB assemblies to support advanced sensors, high-speed data transfer, and durability under extreme automotive conditions, distinguishing them from conventional PCBs by supporting larger layer counts, denser wiring, and higher environmental resistance.
Growing Investments in Industrial Automation and Smart Manufacturing
Automation in production systems and smart factories drives PCB assembly utilization. Industries use advanced PCBs in robotics, control systems, and industrial IoT networks. The need for real-time communication between machines and control units increases electronic component density. PCB assemblies enable seamless operation in high-speed automated environments. It supports precise signal transmission, low latency, and enhanced reliability in manufacturing processes. Demand for durable boards with high thermal stability grows in industrial machinery. Companies are modernizing operations through predictive maintenance and digital connectivity. These advancements amplify market opportunities within the industrial automation sector.
Rising Adoption of Renewable Energy Systems and Power Electronics
Increasing global investment in solar, wind, and electric power infrastructure stimulates PCB assembly demand. Power conversion, inverter control, and battery management systems rely heavily on robust PCB designs. It enables efficient energy flow and system protection under variable loads. Growth in electric vehicles and charging infrastructure boosts high-voltage PCB requirements. Manufacturers develop boards capable of withstanding extreme temperature and current fluctuations. The shift toward sustainable power generation accelerates demand for environmentally compliant materials. Renewable energy integration into grids creates new application areas for PCB assemblies. These factors collectively strengthen market expansion in energy and power electronics.
Market Trends:
Rising Use of Flexible and Rigid-Flex PCB Assemblies for Advanced Applications
The Global Printed Circuit Board Assembly Market is witnessing a surge in flexible PCB usage across compact devices. Flexible and rigid-flex boards allow high circuit density while reducing space and weight. Their ability to bend and conform to complex device shapes supports innovation in wearables and medical electronics. Manufacturers prioritize these designs for improved reliability and vibration resistance. Aerospace and defense sectors increasingly deploy flexible circuits for lightweight system integration. Demand for high-frequency and flexible substrates is expanding rapidly. Enhanced performance and design freedom drive continuous adoption. These trends underline the shift toward versatile PCB architectures.
- For instance, Panasonic’s Felios® flexible copper-clad laminate (FCCL) utilizes polyimide base films to provide lightweight, highly durable, and flexible substrates, favorably used in wearable technology and medical sensors where circuit density and mechanical strength are required.
Integration of 5G Infrastructure and High-Frequency PCB Assemblies
Telecom operators are investing in 5G networks that require low-loss and high-frequency PCB assemblies. High-speed communication equipment depends on precise signal routing and thermal stability. PCB materials with low dielectric loss improve data transmission accuracy. The expansion of base stations, antennas, and optical modules fuels strong market growth. Manufacturers develop specialized laminates for RF and microwave applications. It supports faster connectivity and reliable network performance. The transition to 5G accelerates demand for advanced multilayer boards. This technological evolution is transforming PCB design standards globally.
- For instance, Rogers Corporation's RO4835 laminate exhibits a dielectric constant of 3.48 ± 0.05 with a dissipation factor of 0.0037 at 10 GHz, supporting high-frequency circuit stability and improved oxidation resistance for reliable RF applications in advanced telecom infrastructure.
Increasing Adoption of AI, IoT, and Edge Computing Devices
Rapid proliferation of IoT devices and AI-enabled systems drives the need for intelligent PCB assemblies. These technologies require compact, high-speed, and energy-efficient circuitry. Integration of processors, memory units, and communication modules enhances functionality. It supports predictive analytics, automation, and remote monitoring applications. PCB designers focus on integrating sensors and power management components for connected ecosystems. Growth in smart homes, healthcare devices, and industrial IoT systems sustains this momentum. Edge computing adoption demands PCBs that support high data throughput. The expanding AI and IoT landscape continues to influence design complexity.
Focus on Sustainability and Lead-Free Manufacturing Practices
Growing environmental awareness is reshaping PCB production standards. Companies are investing in lead-free soldering, halogen-free laminates, and recyclable materials. Compliance with RoHS and REACH regulations remains a major priority. It encourages adoption of green manufacturing methods that reduce hazardous waste. Renewable energy use within PCB facilities is increasing globally. Sustainable supply chains improve brand reputation and ensure long-term viability. Eco-friendly practices align with consumer and industry sustainability goals. The transition toward green production processes strengthens responsible growth across the market.
Market Challenges Analysis:
High Manufacturing Costs and Supply Chain Disruptions Affecting PCB Production
The Global Printed Circuit Board Assembly Market faces high production costs due to complex manufacturing processes. Precision assembly, fine-pitch soldering, and testing increase operational expenses. Rising raw material costs and limited substrate availability create financial strain. Dependence on global supply chains exposes producers to delays and shortages. It impacts lead times, pricing stability, and component sourcing. Energy consumption during fabrication adds further cost burdens. Smaller manufacturers struggle to remain competitive under fluctuating input prices. These factors collectively hinder scalability and profit margins for many industry participants.
Increasing Design Complexity and Thermal Management Challenges
Modern electronics require dense, high-speed PCBs with efficient thermal dissipation. Complex multilayer boards create difficulties in maintaining electrical integrity and heat resistance. The miniaturization trend leaves limited space for heat sinks and conductive paths. It increases risk of signal interference and component failure. Design verification and testing consume significant time and resources. Maintaining quality standards under compact configurations demands advanced tools and expertise. High-power applications like EVs and data centers intensify these challenges. Addressing these technical issues remains critical to sustaining product reliability.
Market Opportunities:
Rising Demand from Emerging Sectors such as Electric Vehicles and Medical Electronics
The Global Printed Circuit Board Assembly Market is poised for expansion across emerging applications. Electric vehicles, battery systems, and medical devices create new opportunities for advanced PCB designs. Increasing reliance on smart diagnostics, imaging systems, and power modules boosts specialized assembly demand. It enables greater efficiency and miniaturization in complex electronic systems. Innovation in wearable health monitoring and telemedicine devices further accelerates adoption. Collaboration between OEMs and PCB manufacturers strengthens industry integration. These developments broaden growth potential across multiple high-tech sectors.
Expansion of Local Manufacturing and Regional Electronics Hubs
Countries are investing in domestic PCB production to reduce import dependence. Governments offer incentives for electronics manufacturing under national initiatives. It enhances regional supply resilience and technology transfer. Asia Pacific maintains leadership through strong infrastructure and skilled labor. North America and Europe increase focus on reshoring advanced electronic production. Localized assembly reduces logistics costs and improves customization. Growing support for semiconductor and electronics ecosystems drives sustained investment. These factors collectively create long-term opportunities for global market expansion.
Market Segmentation Analysis:
By PCB Type
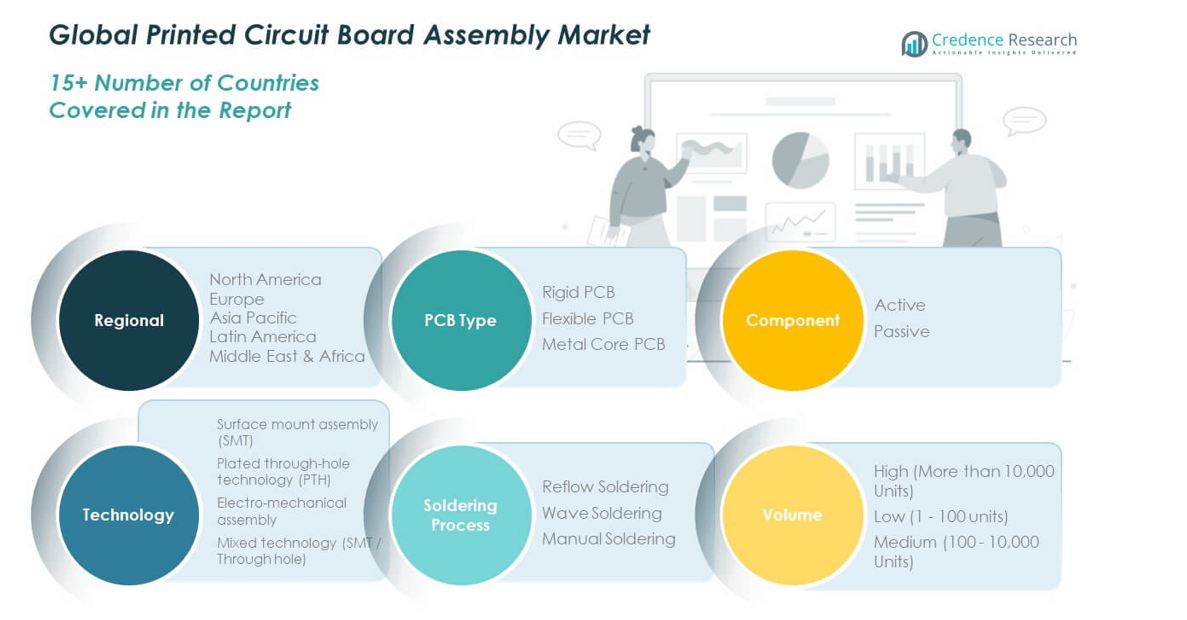
The Global Printed Circuit Board Assembly Market includes rigid, flexible, and metal core PCBs. Rigid PCBs dominate due to their durability and use in industrial, automotive, and consumer electronics. Flexible PCBs gain traction in wearables, smartphones, and medical devices because of their compact and lightweight design. Metal core PCBs find demand in LED lighting and power electronics, driven by superior thermal management and reliability under high-load conditions. These categories reflect growing application diversity across performance-critical environments.
- For instance, aluminum base PCBs are widely employed in LED lighting systems to ensure effective thermal dissipation, providing durability and reliable electrical connections even in compact device layouts, which enhances energy efficiency and supports longer component lifespans in lighting applications.
By Component and Technology
Active and passive components together form the backbone of PCB assemblies. Active components like transistors and ICs drive functionality, while passive ones such as resistors and capacitors ensure stability and performance. Surface mount technology (SMT) leads the market for its high-speed assembly and space efficiency. Plated through-hole (PTH) technology retains demand in high-reliability applications, while mixed technology supports hybrid configurations. Electro-mechanical assemblies integrate mechanical functions into compact systems for complex designs.
- For instance, advanced SMT production lines now routinely achieve hundreds of thousands of component placements per hour, with rates influenced by component size and type, supporting high-speed manufacturing for complex electronics and improving throughput in PCB assembly facilities.
By Soldering Process, Volume, and End-Use Industry
Reflow soldering dominates due to automation compatibility and precision, followed by wave soldering for large-scale production. Manual soldering remains relevant in prototyping and small batches. High-volume assemblies lead due to mass manufacturing in consumer and automotive electronics. Medium-volume production serves industrial and healthcare needs, while low-volume caters to custom and defense systems. Key end-use industries include consumer electronics, automotive, IT & telecom, healthcare, and industrial equipment.
Segmentation:
- By PCB Type
- Rigid PCB
- Flexible PCB
- Metal Core PCB
- By Component
- Active Components
- Passive Components
- By Technology
- Surface Mount Assembly (SMT)
- Plated Through-Hole Technology (PTH)
- Electro-Mechanical Assembly
- Mixed Technology (SMT / Through Hole)
- By Soldering Process
- Reflow Soldering
- Wave Soldering
- Manual Soldering
- By Volume
- High (More than 10,000 Units)
- Medium (100 – 10,000 Units)
- Low (1 – 100 Units)
- By End-Use Industry
- Consumer Electronics
- Automotive
- Healthcare
- IT & Telecom
- Industrial
- Others
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
The North America Global Printed Circuit Board Assembly Market size was valued at USD 26.12 million in 2018, increased to USD 36.23 million in 2024, and is anticipated to reach USD 56.87 million by 2032, at a CAGR of 5.4% during the forecast period. North America holds a 28% share of the global market, driven by strong demand for advanced electronics and industrial automation. The United States leads regional growth with high investments in aerospace, defense, and healthcare electronics. It benefits from robust R&D capabilities and advanced manufacturing infrastructure. Companies emphasize product innovation, precision assembly, and high-reliability PCBs for critical applications. The expansion of EV production and 5G network deployment strengthens market penetration. Canada and Mexico contribute through industrial electronics and contract manufacturing. The region’s technological maturity and focus on automation sustain long-term competitiveness.
Europe
The Europe Global Printed Circuit Board Assembly Market size was valued at USD 17.10 million in 2018, increased to USD 22.78 million in 2024, and is anticipated to reach USD 32.37 million by 2032, at a CAGR of 4.1% during the forecast period. Europe accounts for a 17% share of the global market, supported by its strong automotive and industrial sectors. Germany, France, and the UK lead in production, focusing on high-quality and energy-efficient PCB assemblies. The region emphasizes compliance with environmental standards and sustainability in manufacturing. It drives innovation through automation and IoT-based electronics systems. Demand from electric vehicles, renewable energy, and industrial automation enhances market growth. It benefits from advanced design capabilities and technological partnerships. Ongoing R&D investments in flexible and multilayer PCB technologies enhance Europe’s manufacturing resilience.
Asia Pacific
The Asia Pacific Global Printed Circuit Board Assembly Market size was valued at USD 40.51 million in 2018, increased to USD 59.20 million in 2024, and is anticipated to reach USD 98.11 million by 2032, at a CAGR of 6.1% during the forecast period. Asia Pacific dominates with a 45% share, driven by large-scale electronics manufacturing in China, Japan, and South Korea. It serves as the global hub for PCB production due to cost efficiency and integrated supply chains. Rapid expansion of consumer electronics, automotive electronics, and telecommunication systems strengthens regional leadership. Government incentives and smart manufacturing initiatives in China and India encourage domestic production. Japan’s precision engineering and South Korea’s semiconductor expertise further support technological advancement. Growing adoption of IoT, AI, and 5G networks fuels demand for complex PCB designs. Continuous infrastructure upgrades and export growth ensure Asia Pacific’s sustained dominance.
Latin America
The Latin America Global Printed Circuit Board Assembly Market size was valued at USD 4.25 million in 2018, increased to USD 5.91 million in 2024, and is anticipated to reach USD 8.15 million by 2032, at a CAGR of 3.7% during the forecast period. Latin America captures a 5% share of the global market, led by Brazil and Mexico’s expanding electronics sectors. The region experiences steady demand from automotive, telecommunications, and consumer electronics. It benefits from nearshoring trends and supply chain diversification strategies. Growing focus on renewable energy and digital transformation supports market expansion. Manufacturers are gradually investing in localized production facilities and automation systems. It faces challenges related to component sourcing and skilled labor availability. However, government incentives for electronics assembly encourage capacity building. The region’s improving industrial infrastructure enhances long-term market potential.
Middle East
The Middle East Global Printed Circuit Board Assembly Market size was valued at USD 2.49 million in 2018, increased to USD 3.20 million in 2024, and is anticipated to reach USD 4.19 million by 2032, at a CAGR of 3.0% during the forecast period. The region represents a 3% share of the global market, driven by industrial modernization and defense electronics. The UAE and Saudi Arabia lead growth, supported by investments in technology manufacturing. It benefits from increasing demand for automation and communication infrastructure. Energy-efficient PCB solutions gain traction in renewable and oilfield applications. Strategic partnerships with Asian manufacturers strengthen supply capabilities. Regional governments emphasize digital transformation and smart city initiatives. Slow diversification of the manufacturing base remains a key challenge. The Middle East continues to evolve into a niche electronics assembly hub.
Africa
The Africa Global Printed Circuit Board Assembly Market size was valued at USD 1.35 million in 2018, increased to USD 2.11 million in 2024, and is anticipated to reach USD 2.60 million by 2032, at a CAGR of 2.2% during the forecast period. Africa accounts for a 2% share of the global market, showing gradual development driven by South Africa, Egypt, and Nigeria. It witnesses rising demand for communication electronics and renewable energy systems. Local assembly operations remain limited but are expanding through government-led industrial programs. It depends on imports for high-precision PCB components. Efforts to build regional manufacturing ecosystems are gaining momentum. Digital infrastructure growth and startup innovation hubs are emerging across key economies. The market’s progress aligns with broader economic and technological reforms across the continent.
Key Player Analysis:
- Foxconn Technology Group
- Flex Ltd.
- Jabil Inc.
- Sanmina Corporation
- Celestica Inc.
- Benchmark Electronics
- Plexus Corp.
Competitive Analysis:
The Global Printed Circuit Board Assembly Market is highly competitive, featuring both large multinational corporations and specialized regional manufacturers. Leading players such as Foxconn Technology Group, Flex Ltd., Jabil Inc., Sanmina Corporation, and Celestica Inc. dominate through extensive production capacity, advanced automation, and diversified product portfolios. It focuses on delivering high-precision, high-reliability assemblies across electronics, automotive, and industrial applications. Companies invest heavily in R&D and supply chain integration to improve speed, quality, and cost efficiency. Strategic collaborations and technology partnerships strengthen their global positioning and customer reach.
Recent Developments:
- Foxconn Technology Group entered a significant strategic partnership with TECO Electric & Machinery, announced on July 30, 2025. This alliance is designed to boost AI data center solutions and involves a share exchange, with Foxconn acquiring a 10% stake in TECO and TECO holding a 0.519% stake in Foxconn.
- Flex Ltd. revealed a strategic manufacturing partnership with Husqvarna on February 4, 2025, aimed at improving Husqvarna's supply chain flexibility and expanding Flex’s Lifestyle portfolio into outdoor and power equipment.
- Jabil Inc. completed the acquisition of Pharmaceutics International Inc. (Pii), a contract development and manufacturing organization, on February 3, 2025. This move strengthens Jabil’s pharmaceutical solutions, adding new capabilities in aseptic filling and oral solid dose manufacturing.
- Sanmina Corporation announced on May 19, 2025, the acquisition of the data center infrastructure manufacturing business of ZT Systems from AMD for up to $3 billion. This transformational deal dramatically increases Sanmina’s exposure to cloud and AI infrastructure, positioning it as a preferred partner for hyperscale cloud and OEM clients and providing new capabilities in advanced liquid cooling and systems integration.
Report Coverage:
The research report offers an in-depth analysis based on PCB type, component, technology, soldering process, volume, end-use industry, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of miniaturized, high-performance PCB assemblies in smart electronics.
- Expansion of electric and autonomous vehicle electronics driving PCB demand.
- Growth in flexible and rigid-flex PCB applications across multiple sectors.
- Rising automation and AI integration in PCB manufacturing processes.
- Stronger focus on sustainability and lead-free production standards.
- Expansion of regional production hubs in Asia Pacific and North America.
- Increasing investment in power electronics and renewable energy systems.
- Development of advanced materials for high-frequency and heat-resistant PCBs.
- Strengthening collaboration between OEMs and PCB manufacturers for design optimization.
- Ongoing innovation in multilayer and hybrid PCB technologies to support complex systems.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Miniaturization and High-Performance Device Demand
The proliferation of compact, high-performance consumer electronics such as smartphones, wearables, and tablets is driving the need for advanced PCB assemblies with higher circuit density and multilayer designs, enabling faster processing and multifunctionality in smaller form factors.
Automotive Electronics and ADAS Expansion
The integration of electronic control units, sensors, and advanced driver assistance systems (ADAS) in vehicles is increasing the demand for reliable, multilayer PCB assemblies that can withstand harsh automotive environments and support complex functionalities in electric and autonomous vehicles.
Industrial Automation and Smart Manufacturing
The rise of automation, robotics, and industrial IoT in manufacturing is fueling demand for PCB assemblies that enable real-time communication, precise control, and high reliability in automated production systems, supporting the shift toward smart factories.
Growth in Renewable Energy and Power Electronics
Investments in solar, wind, and electric power infrastructure are boosting demand for robust PCB assemblies used in power conversion, inverter control, and battery management systems, requiring boards that can handle high voltages and fluctuating loads.
Adoption of Flexible and Rigid-Flex PCB Technologies
The increasing use of flexible and rigid-flex PCBs in compact devices, medical electronics, and aerospace applications is enabling innovative product designs that require lightweight, space-saving, and vibration-resistant circuit solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Printed circuit board assembly market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Printed Circuit Board Assembly Market projected to grow between 2025 and 2032?
At what Compound Annual Growth Rate is the Printed circuit board assembly market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Printed circuit board assembly market?
Who are the leading companies in the Printed circuit board assembly market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By PCB Type
- 1.2.1 Rigid PCB
- 1.2.2 Flexible PCB
- 1.2.3 Metal Core PCB
- 1.3 By Technology
- 1.3.1 Surface Mount Assembly (SMT)
- 1.3.2 Plated Through-Hole Technology (PTH)
- 1.3.3 Electro-Mechanical Assembly
- 1.3.4 Mixed Technology (SMT / Through Hole)
- 1.4 By End-Use Industry
- 1.4.1 Consumer Electronics
- 1.4.2 Automotive
- 1.4.3 Healthcare
- 1.4.4 IT & Telecom
- 1.4.5 Industrial
- 1.4.6 Others
- 1.5 By Soldering Process
- 1.5.1 Reflow Soldering
- 1.5.2 Wave Soldering
- 1.5.3 Manual Soldering
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 129.43 billion → 2032: USD 202.29 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Printed Circuit Board Assembly Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Printed Circuit Board Assembly Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Printed Circuit Board Assembly Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Printed Circuit Board Assembly Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Printed Circuit Board Assembly Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Printed Circuit Board Assembly Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Printed Circuit Board Assembly Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Printed Circuit Board Assembly Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 129.43 billion → 2032: USD 202.29 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Printed Circuit Board Assembly Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By PCB Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Rigid PCB
- 12.3.7.2 Flexible PCB
- 12.3.7.3 Metal Core PCB
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Surface Mount Assembly (SMT)
- 12.4.7.2 Plated Through-Hole Technology (PTH)
- 12.4.7.3 Electro-Mechanical Assembly
- 12.4.7.4 Mixed Technology (SMT / Through Hole)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consumer Electronics
- 12.5.7.2 Automotive
- 12.5.7.3 Healthcare
- 12.5.7.4 IT & Telecom
- 12.5.7.5 Industrial
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Soldering Process - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Reflow Soldering
- 12.6.7.2 Wave Soldering
- 12.6.7.3 Manual Soldering
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Printed Circuit Board Assembly End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Printed Circuit Board Assembly Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Printed Circuit Board Assembly Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Printed Circuit Board Assembly Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Foxconn Technology Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Flex Ltd.
- 18.4 Jabil Inc.
- 18.5 Sanmina Corporation
- 18.6 Celestica Inc.
- 18.7 Benchmark Electronics
- 18.8 Plexus Corp.
- 18.9 Venture Corporation
- 18.10 Zhen Ding Technology
- 18.11 TTM Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

