
Market Overview:
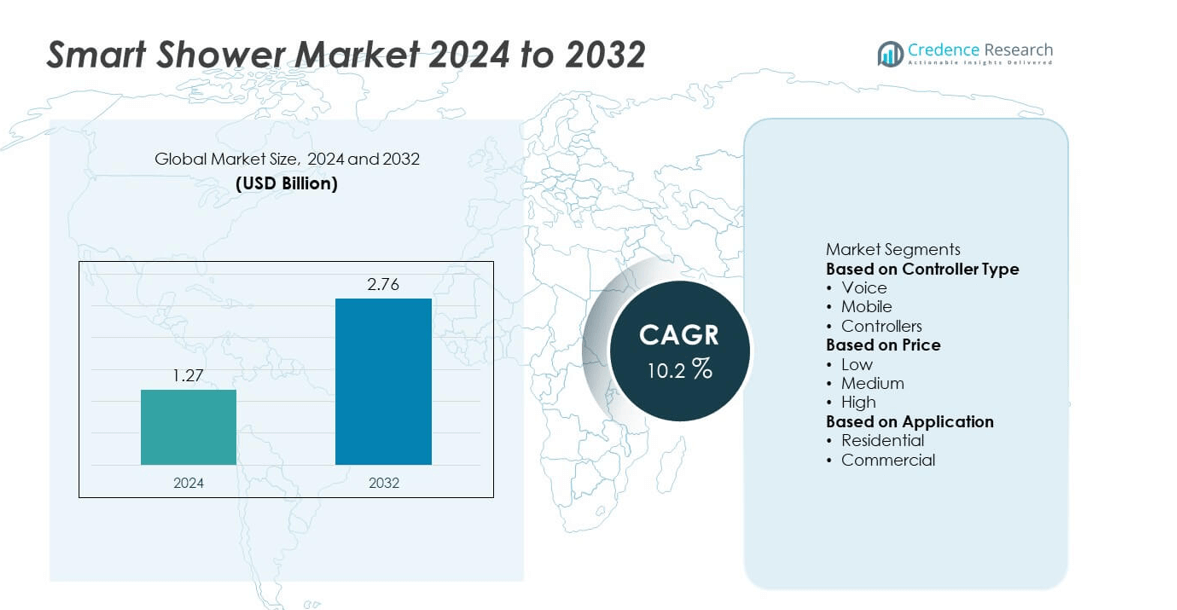
The Smart Shower market was valued at USD 1.27 billion in 2024 and is projected to reach USD 2.76 billion by 2032, registering a CAGR of 10.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Shower Market Size 2024 | USD 1.27 billion |
| Smart Shower Market, CAGR | 10.2% |
| Smart Shower Market Size 2032 | USD 2.76 billion |
The smart shower market is led by major companies such as Hansgrohe, Moen Incorporated, Jaquar, GetHai Inc., Dornbracht Deutschland GmbH & Co. KG, Kohler Co., Masco, LIXIL Corporation, Grohe, and Cera. These players focus on digital innovation, smart connectivity, and energy-efficient design to strengthen their market presence. Product development emphasizes voice and app-based controls, water conservation, and enhanced user customization. Regionally, North America dominated the market in 2024 with a 34.2% share, supported by high adoption of smart home systems and sustainability initiatives, followed by Europe with 29.8% and Asia-Pacific with 25.7%, driven by rapid urbanization and smart infrastructure growth.
Market Insights
- The smart shower market was valued at USD 1.27 billion in 2024 and is projected to reach USD 2.76 billion by 2032, growing at a CAGR of 10.2%.
- Rising demand for connected home technologies and water-efficient solutions drives market expansion, with voice-controlled systems holding a 47.6% share in 2024.
- Increasing integration of IoT, AI, and smartphone applications enhances customization, comfort, and energy efficiency, shaping market trends.
- Leading players such as Hansgrohe, Moen Incorporated, Jaquar, Kohler Co., and LIXIL Corporation focus on innovation, sustainability, and smart automation to strengthen their global presence.
- Regionally, North America leads with a 34.2% share, followed by Europe at 29.8% and Asia-Pacific at 25.7%, supported by rapid urbanization and growth in smart city infrastructure.
Market Segmentation Analysis:
By Controller Type
The voice-controlled segment dominated the smart shower market in 2024 with a 47.6% share. Growth is driven by the integration of AI assistants such as Alexa and Google Home, which enhance user convenience and energy efficiency. Voice-enabled systems allow hands-free operation for temperature, water flow, and duration adjustments, supporting accessibility and smart home automation. Increasing consumer demand for luxury and personalized bathing experiences is accelerating adoption, while mobile app–based controls continue to gain traction among tech-savvy households seeking remote shower management and usage analytics.
- For instance, Moen's TS3302TB Smart Shower allows users to customize settings like temperature and water flow through voice commands with Alexa or Google Assistant, providing hands-free control.
By Price
The medium-priced segment held the largest share of 52.3% in 2024, balancing affordability and advanced functionality. Consumers increasingly prefer mid-range smart showers that offer digital temperature control, water-saving features, and smartphone compatibility without premium costs. Manufacturers focus on energy-efficient models with smart sensors and Wi-Fi integration to attract middle-income households. The segment benefits from growing awareness of sustainable water use and expanding availability through online retail channels, making smart shower systems more accessible for residential renovations and new urban developments.
- For instance, Aqualisa's Quartz Touch Smart Shower integrates Wi-Fi with voice control via Amazon Alexa or Google Assistant, offering personalized temperature and water flow settings, and emphasizing water-saving features.
By Application
The residential segment accounted for a dominant 68.4% share of the smart shower market in 2024. Rising adoption of smart home ecosystems and connected bathroom technologies is fueling demand among homeowners. Enhanced hygiene, water efficiency, and customizable comfort settings are key drivers of residential installations. Expanding urban housing projects and the trend toward modern, energy-efficient bathrooms further support growth. The commercial segment, including hotels and wellness centers, is also increasing adoption to improve guest experiences and reduce operational costs through automated water management systems.
Key Growth Drivers
Rising Integration of IoT and Smart Home Ecosystems
The growing adoption of IoT-enabled home automation is a major driver for the smart shower market. Integration with voice assistants and mobile apps allows users to customize temperature, water pressure, and duration settings. These features enhance comfort, safety, and energy efficiency. As connected homes gain popularity, manufacturers expand interoperability with platforms like Alexa and Google Home. The increasing demand for seamless connectivity and personalized experiences continues to accelerate smart shower installations across residential and commercial projects.
- For instance, U by Moen Smart Shower," featuring a mobile app that allows users to set precise water temperatures and use features like a "warm up and pause" function to conserve water in residential settings.
Growing Demand for Water and Energy Conservation
Sustainability concerns and global water scarcity are fueling demand for smart showers equipped with efficient flow and temperature control systems. These showers use built-in sensors to minimize water wastage while maintaining comfort. Government incentives and green certification programs encourage adoption of eco-friendly plumbing technologies. Real-time monitoring and consumption data further support sustainable use. This shift toward conservation-focused design strengthens the role of smart showers in smart homes and environmentally responsible construction.
- For instance, Hansgrohe's EcoSmart technology enables its showers to use up to 60% less water than conventional models, significantly reducing energy consumption and CO2 emissions.
Rising Consumer Inclination Toward Luxury and Wellness
Increasing disposable income and lifestyle upgrades are driving consumer interest in high-end, wellness-oriented bathroom technologies. Smart showers deliver spa-like experiences through digital temperature control, LED lighting, and aromatherapy functions. They blend convenience, hygiene, and comfort, appealing to modern households. Hotels and wellness resorts are adopting these systems to enhance guest satisfaction. As luxury living and wellness awareness grow, demand for intelligent shower systems continues to rise globally.
Key Trends & Opportunities
Integration with Artificial Intelligence and Predictive Controls
Manufacturers are incorporating AI-based systems to enhance personalization and operational efficiency. These solutions learn user preferences and automatically adjust settings for temperature, pressure, and flow. Predictive maintenance alerts minimize service disruptions, improving reliability. The integration of AI aligns with the broader shift toward intelligent, data-driven home systems. As advancements continue, AI-enabled smart showers will deliver adaptive performance and superior water management.
- For instance, Aquaelite has developed digital showers with smart sensors that automatically regulate temperature and water flow, preventing scalds and reducing waste with features like anti-drip technology.
Expansion in Hospitality and Commercial Infrastructure
The hospitality industry presents strong growth opportunities for smart shower adoption. Hotels, gyms, and wellness centers are investing in intelligent water systems to improve sustainability and guest comfort. Centralized management platforms enable remote temperature control and usage monitoring. These systems help reduce water and energy costs while aligning with eco-certification standards. The trend supports wider adoption in commercial infrastructure and luxury real estate projects.
- For instance, the Sheraton Tel Aviv implemented SmarTap’s fully automated smart shower system, achieving a 30% reduction in water use and 8% energy savings, which translates to significant cost reductions and improved guest experience.
Key Challenges
High Installation and Maintenance Costs
High upfront costs remain a major barrier to smart shower adoption, especially in developing markets. Advanced sensors, electronic controls, and IoT integration raise installation expenses. Skilled labor is also required for setup and maintenance. Over time, software updates and system calibration add to ownership costs. To overcome this, manufacturers are developing affordable and modular designs that balance performance with cost efficiency.
Connectivity and Compatibility Limitations
Compatibility issues with diverse smart home systems and inconsistent internet infrastructure hinder widespread adoption. Some devices struggle to integrate seamlessly with regional networks or outdated plumbing setups. Connectivity failures can interrupt automated functions, impacting user satisfaction. Manufacturers are addressing these limitations through improved cross-platform support and secure wireless protocols. However, ensuring consistent performance across varied environments remains a technical and infrastructural challenge.
Regional Analysis
North America
North America held a 34.2% share of the smart shower market in 2024, driven by high adoption of connected home technologies and sustainability initiatives. The U.S. leads regional demand due to strong consumer preference for luxury bathroom products and integration with IoT platforms such as Alexa and Google Home. Water conservation regulations and green building certifications further support market expansion. Major manufacturers focus on advanced, energy-efficient designs tailored for premium housing and hotel renovations, while increasing renovation activities across Canada and the U.S. continue to boost regional market growth.
Europe
Europe accounted for a 29.8% share of the smart shower market in 2024, supported by rising investments in smart homes and eco-friendly infrastructure. Countries such as Germany, the UK, and France lead adoption due to strong sustainability policies and energy efficiency standards. Growing awareness of water conservation and rising disposable incomes in urban areas enhance market penetration. Leading manufacturers focus on hybrid systems combining water-saving features with digital comfort controls. Continuous R&D in smart bathroom technologies and increasing consumer preference for advanced home automation strengthen Europe’s market position.
Asia-Pacific
Asia-Pacific captured a 25.7% share of the smart shower market in 2024 and is projected to record the fastest growth through 2032. Rapid urbanization, expanding middle-class income, and government-backed smart city programs drive demand across China, India, and Japan. Rising construction of modern residential complexes and hospitality infrastructure supports strong market potential. Local and international brands are focusing on cost-effective and energy-efficient smart showers to meet growing consumer expectations. Technological innovation and expanding awareness of water-saving solutions further accelerate regional adoption, positioning Asia-Pacific as a key growth hub.
Latin America
Latin America represented a 6.1% share of the smart shower market in 2024, driven by growing modernization of residential and hospitality infrastructure. Brazil and Mexico lead regional demand due to expanding urban housing projects and rising adoption of smart home technologies. Increasing focus on water conservation and eco-friendly living also supports market growth. However, high installation costs and limited consumer awareness restrict widespread adoption. Manufacturers are collaborating with regional distributors to improve accessibility, while smart bathroom innovations continue to gain traction among upper-middle-income households.
Middle East & Africa
The Middle East & Africa region accounted for a 4.2% share of the smart shower market in 2024, supported by large-scale real estate developments and luxury housing projects. Countries such as the UAE, Saudi Arabia, and South Africa are integrating smart showers into premium residential and commercial spaces. Rising tourism and hotel construction stimulate product demand, particularly for water-efficient and temperature-controlled systems. Harsh climatic conditions drive interest in advanced water management technologies. Despite limited affordability in some areas, strong infrastructure investments and sustainability goals continue to support steady market expansion.
Market Segmentations:
By Controller Type
- Voice
- Mobile
- Controllers
By Price
- Low
- Medium
- High
By Application
- Residential
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The smart shower market is dominated by key players such as Hansgrohe, Moen Incorporated, Jaquar, GetHai Inc., Dornbracht Deutschland GmbH & Co. KG, Kohler Co., Masco, LIXIL Corporation, Grohe, and Cera. These companies compete through continuous innovation, expanding product portfolios, and integration of advanced technologies like IoT, AI, and voice control. Leading manufacturers focus on enhancing user experience through energy-efficient, water-saving, and customizable smart shower systems. Strategic collaborations, digital connectivity, and sustainable design are central to their growth strategies. Global players invest heavily in R&D to develop AI-driven temperature regulation and eco-friendly materials, while regional participants target affordability to expand in emerging markets. Growing competition and evolving consumer preferences for connected bathroom systems drive ongoing product differentiation and market consolidation.
Key Player Analysis
- Hansgrohe
- Moen Incorporated
- Jaquar
- GetHai, Inc.
- Dornbracht Deutschland GmbH & Co. KG
- Kohler Co.
- Masco
- LIXIL Corporation
- Grohe
- Cera
Recent Developments
- In September 2025, Kohler Co. launched its Anthem+ smart showering system integrated with Control4’s home automation platform, enabling users to manage shower settings through voice commands and mobile app control.
- In March 17 2025, GROHE introduced at ISH 2025 its new shower innovations including the “Purefoam” foam shower technology and the “Rapido Heat Recovery” smart shower system reinforcing its push into smart/wellness-centric showering experiences.
- In February 24 2025, TOTO LTD. unveiled next-generation smart bathroom technology, focusing on smart showers, sustainability and luxury design at the KBIS 2025 show.
- In October 2024, Kohler Co. partnered with Samsung Electronics to integrate its smart showers into the SmartThings ecosystem, allowing users to monitor and control water usage via SmartThings and the SmartThings Map View feature
Report Coverage
The research report offers an in-depth analysis based on Controller Type, Price, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for smart, connected bathroom systems will continue to grow globally.
- Integration of AI and IoT will enhance personalization and water efficiency.
- Voice and app-based controls will become standard in residential installations.
- Eco-friendly and water-saving technologies will dominate product development.
- Manufacturers will focus on hybrid designs combining luxury and sustainability.
- The hospitality sector will increasingly adopt smart showers for guest comfort.
- Affordable smart shower models will expand market reach in emerging economies.
- Advancements in sensor technology will improve precision and user experience.
- Partnerships between tech firms and sanitary manufacturers will drive innovation.
- Asia-Pacific will emerge as the fastest-growing market due to smart city expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Smart Shower Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Smart Shower Market projected to grow between 2025 and 2032
Which Smart Shower Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Smart Shower Market?
Who are the leading companies in the Smart Shower Market?
Which region commanded the largest share of the Smart Shower Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Smart Shower Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Smart Shower Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.27 billion → 2032: USD 2.76 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Smart Shower Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Smart Shower Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Smart Shower Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Smart Shower Market Drivers
- 3.3 Smart Shower Market Restraints & Challenges
- 3.4 Smart Shower Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Smart Shower Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Smart Shower Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Smart Shower category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Smart Shower Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Smart Shower Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Smart Shower. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Smart Shower Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Smart Shower Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Smart Shower Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Smart Shower (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Smart Shower
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Smart Shower Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Smart Shower Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Smart Shower Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Smart Shower Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Smart Shower Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Smart Shower Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Smart Shower Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Smart Shower Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
