
Market Overview
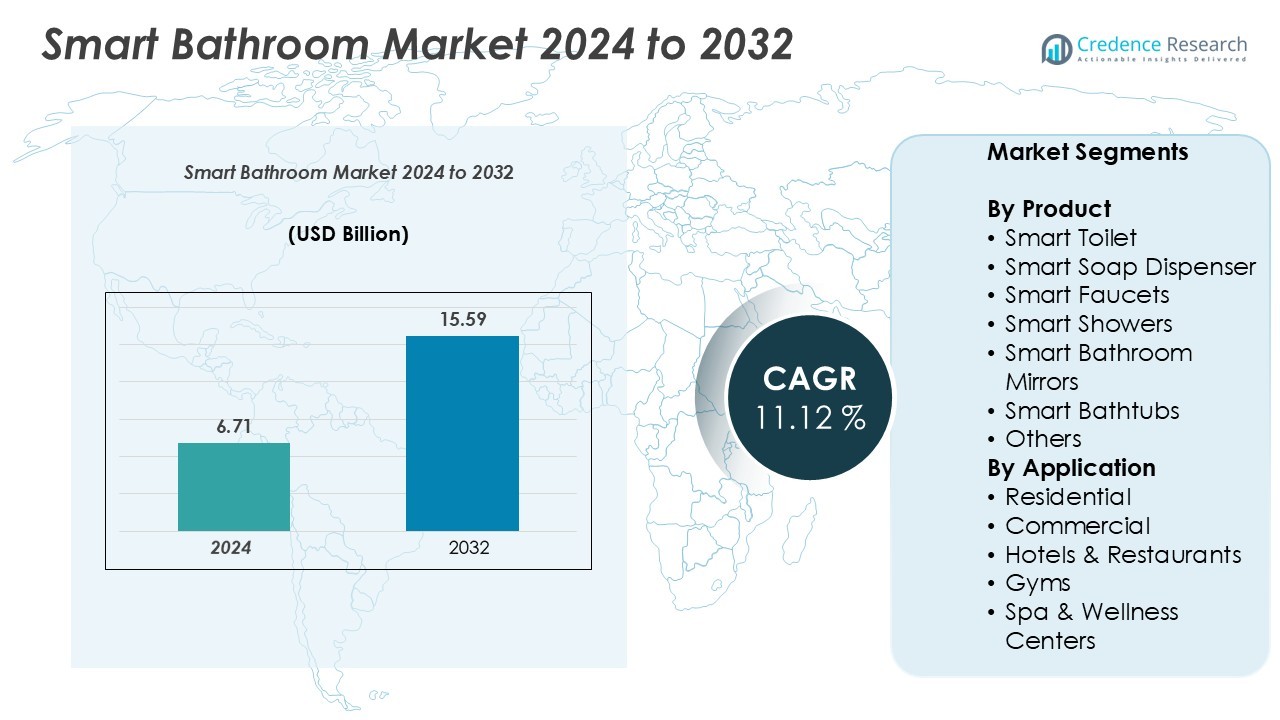
The Smart Bathroom Market size was valued at USD 6.71 billion in 2024 and is anticipated to reach USD 15.59 billion by 2032, at a CAGR of 11.12% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Bathroom Market Size 2024 | USD 6.71 Billion |
| Smart Bathroom Market, CAGR | 11.12% |
| Smart Bathroom Market Size 2032 | USD 15.59 Billion |
The smart bathroom market is led by major players such as Moen Incorporated, Kohler Co., GROHE AMERICA, INC. (LIXIL Corporation), TOTO LTD., Roca Sanitario S.A., and Duravit AG. These companies dominate through strong product portfolios, continuous innovation, and advanced automation technologies. They focus on smart toilets, connected faucets, and voice-controlled systems that enhance user experience and sustainability. North America leads the global market with a 36% share, supported by early smart home adoption and high consumer spending. Europe follows with 29%, driven by sustainable building initiatives and luxury bathroom upgrades, while Asia Pacific holds 24%, emerging as the fastest-growing region due to urbanization and rising disposable incomes.
Market Insights
- The Smart Bathroom Market was valued at USD 6.71 billion in 2024 and is projected to reach USD 15.59 billion by 2032, growing at a CAGR of 11.12% during the forecast period.
- Rising demand for hygiene-focused and water-efficient bathroom solutions is driving market growth, with smart toilets leading the product segment due to their advanced automation and comfort features.
- Integration of AI, IoT, and voice-assistant technologies is shaping key market trends, enabling predictive maintenance and personalized user experiences across residential and commercial spaces.
- The market is highly competitive, with companies like Kohler Co., Moen Incorporated, GROHE AMERICA, INC., and TOTO LTD. investing in R&D to expand connected product lines and strengthen global reach.
- North America leads with 36% share, followed by Europe (29%) and Asia Pacific (24%), while the smart toilet segment remains dominant across both residential and hospitality applications worldwide.
Market Segmentation Analysis:
By Product
The smart toilet segment dominates the smart bathroom market with the largest market share. Its leadership is driven by increasing demand for hygiene-focused and water-efficient solutions. Smart toilets offer features such as automatic flushing, seat warming, and bidet functionality that enhance user convenience and sanitation. Growing adoption in premium residential and commercial spaces supports this segment’s expansion. Advancements in IoT-enabled controls and energy-efficient designs further contribute to market growth, making smart toilets the most preferred product category among consumers seeking luxury and sustainability.
- For instance, TOTO Ltd. introduced the Neorest NX2, which uses Actilight UV light technology in the lid and a special photocatalytic glaze on the bowl to break down waste particles. The toilet also employs EWATER+, which is electrolyzed water, to mist the bowl and wand to suppress the accumulation of bacteria. The combination of these features helps keep the toilet hygienic and reduces the need for manual cleaning.
By Application
The residential segment holds the dominant share of the smart bathroom market, driven by rising smart home integration and consumer inclination toward personalized comfort. Growing urbanization and higher disposable incomes are fueling adoption of connected bathroom devices in modern households. Consumers prefer smart showers, mirrors, and faucets for convenience, energy efficiency, and enhanced user experience. Home renovation trends and sustainability initiatives, including water and energy conservation, also support residential demand. Continuous product innovation by manufacturers ensures better connectivity and user control, strengthening this segment’s dominance.
- For instance, Moen launched the U by Moen Smart Shower, which allows users to preset temperature and duration via Wi-Fi and a mobile app. This system has a water-saving feature that pauses water flow once the desired temperature is reached.
Key Growth Drivers
Rising Adoption of Smart Home Technologies
The growing integration of smart home ecosystems is a major driver of the smart bathroom market. Consumers are increasingly embracing connected devices that enhance comfort, efficiency, and hygiene. Smart mirrors, showers, and toilets can now be controlled through voice assistants and mobile applications, allowing users to personalize temperature, lighting, and water flow. Rapid advancements in IoT connectivity and wireless communication have further simplified installation and interoperability among devices. The trend is particularly strong in developed regions, where high disposable incomes and smart home penetration rates are accelerating adoption. As automation becomes mainstream, the demand for intelligent bathroom solutions continues to expand across residential and hospitality sectors.
- For instance, Multiple sources confirm that Kohler Co. introduced its Kohler Konnect platform to enable voice-controlled interaction with various smart bathroom fixtures, including toilets, mirrors, and showers, via Amazon Alexa and Google Assistant.
Increasing Focus on Water and Energy Efficiency
Rising environmental concerns and government initiatives promoting sustainable infrastructure are driving demand for water- and energy-efficient bathroom systems. Smart faucets and showers feature flow sensors and automatic shut-off mechanisms that minimize waste while maintaining performance. Advanced systems can monitor consumption patterns and provide analytics for optimized usage. These innovations align with green building standards such as LEED and BREEAM, which emphasize resource efficiency. Manufacturers are also investing in R&D to create products with minimal standby power and improved durability. As consumers become more environmentally conscious, smart bathroom solutions offering tangible resource savings are gaining rapid traction, supporting long-term market growth.
- For instance, Moen's Flo Smart Water Monitor and Shutoff device is specifically designed to detect abnormal water flow patterns (indicative of leaks) and can automatically shut off the water supply to the home to prevent water damage.
Growing Demand for Hygiene and Contactless Solutions
The global focus on hygiene, intensified by recent health crises, is a strong driver for the smart bathroom market. Contactless systems such as sensor-based faucets, soap dispensers, and toilets reduce germ transmission and improve user safety. These features are becoming standard in public spaces, hotels, and modern homes. Touchless technology also enhances convenience, offering automatic operations powered by motion detection and AI. Major manufacturers are introducing antibacterial materials and self-cleaning surfaces to complement these systems. Rising awareness regarding hygiene in high-traffic environments like hospitals, restaurants, and gyms continues to drive investments in smart sanitary infrastructure worldwide.
Key Trends & Opportunities
Integration of AI and IoT for Predictive Maintenance
The adoption of artificial intelligence (AI) and Internet of Things (IoT) technologies is transforming smart bathroom functionality. Sensors embedded in toilets, showers, and faucets collect real-time data to predict maintenance needs, detect leaks, and manage water temperature. Predictive maintenance reduces downtime and extends product life, benefiting both residential and commercial users. AI-driven interfaces also enable users to create personalized profiles for temperature, lighting, and music preferences. Manufacturers are capitalizing on this trend by integrating smart bathroom systems with cloud-based analytics, opening new opportunities for connected ecosystem development.
- For instance, Overdrive IoT’s Smart Toilet Management System uses BLE sensors with a battery life of 2–3 years to monitor usage, consumable levels and leaks in real-time.
Expanding Luxury and Wellness-Oriented Bathroom Concepts
Growing consumer preference for wellness-focused lifestyles has created significant opportunities for luxury smart bathroom solutions. Features such as chromotherapy lighting, steam control, and smart bathtubs with hydrotherapy are gaining popularity. Wellness-integrated designs transform traditional bathrooms into personalized spa-like environments. The trend is supported by rising disposable incomes and urban housing modernization. Leading companies are introducing products that merge aesthetics with technology, such as voice-activated mirrors and temperature-regulating surfaces. The fusion of health, relaxation, and connectivity is driving manufacturers to innovate premium solutions that enhance user experience while adding property value.
- For instance, GROHE’s SmartControl shower system lets users store preferred spray patterns and water flow settings via a push-and-turn dial and memory function.
Key Challenges
High Installation and Maintenance Costs
Despite technological benefits, high initial investment remains a major challenge in the smart bathroom market. The integration of sensors, controllers, and connectivity modules increases installation expenses, limiting adoption among cost-sensitive consumers. Maintenance and software updates also add to the total ownership cost. Retrofitting existing infrastructure requires professional installation and can lead to compatibility issues. In developing regions, these expenses restrict widespread adoption, confining demand to luxury housing and commercial establishments. Overcoming this challenge requires cost optimization, modular product designs, and mass production efficiencies to make smart bathroom systems more affordable and scalable.
Data Privacy and Cybersecurity Concerns
As smart bathrooms become increasingly connected, data privacy and cybersecurity risks have emerged as critical concerns. IoT-enabled systems collect user information such as water usage, temperature preferences, and activity patterns. Without robust encryption and data protection, these systems become vulnerable to unauthorized access or data breaches. Manufacturers face the challenge of ensuring secure data transmission and compliance with international privacy regulations like GDPR. Consumers are increasingly cautious about connected devices, which can slow adoption rates. Strengthening security architecture, incorporating regular software updates, and adopting transparent data policies are essential to mitigate this challenge and build consumer trust.
Regional Analysis
North America
North America dominates the smart bathroom market with a 36% share, driven by strong smart home adoption and advanced infrastructure. Consumers in the U.S. and Canada increasingly prefer connected devices that improve hygiene, efficiency, and comfort. The region benefits from early technology adoption, high disposable incomes, and favorable energy efficiency regulations. Key players invest heavily in R&D to integrate AI and IoT capabilities into bathroom fixtures. Growing awareness of water conservation and demand for luxury amenities in residential and hospitality sectors further reinforce North America’s leadership in the global smart bathroom market.
Europe
Europe holds a 29% market share, supported by government initiatives promoting sustainable and energy-efficient building solutions. Countries such as Germany, the U.K., and France are leading adopters of smart toilets, showers, and faucets. Strict environmental standards and increasing retrofitting activities in smart homes fuel market expansion. European consumers favor products combining design aesthetics with intelligent automation. The hospitality industry also contributes significantly, integrating advanced fixtures to enhance guest experience. Continuous innovation in water-saving technologies and integration with renewable energy systems strengthen Europe’s competitive position in the global market.
Asia Pacific
Asia Pacific accounts for a 24% market share, emerging as the fastest-growing regional market. Rapid urbanization, rising disposable incomes, and smart city projects in China, Japan, South Korea, and India are driving adoption. Increasing awareness of hygiene and the popularity of high-tech residential developments boost demand for smart toilets and mirrors. Local manufacturers are expanding production to meet regional needs while global brands are forming partnerships to enhance market access. The region’s growing focus on home automation and infrastructure modernization continues to create lucrative opportunities for market expansion.
Latin America
Latin America represents a 6% market share, with gradual growth fueled by urban housing modernization and hospitality sector upgrades. Brazil and Mexico are leading markets, witnessing growing adoption of automated faucets and showers in premium homes and commercial facilities. Rising consumer awareness of hygiene and sustainability supports demand. Although cost sensitivity limits large-scale installations, government-backed smart infrastructure programs are improving affordability. Strategic partnerships between local distributors and international brands are expected to strengthen the region’s presence, gradually increasing penetration across mid-range housing projects and luxury developments.
Middle East & Africa (MEA)
The Middle East & Africa hold a 5% share in the global smart bathroom market, driven by increasing construction of luxury hotels, commercial complexes, and smart homes. The UAE and Saudi Arabia are leading adopters, supported by government initiatives promoting smart city development. High investment in infrastructure modernization and tourism boosts demand for intelligent bathroom fixtures. Consumers prefer smart toilets and mirrors that enhance luxury and hygiene standards. Despite slower adoption in parts of Africa due to limited infrastructure, expanding real estate projects are expected to accelerate regional market growth.
Market Segmentations:
By Product
- Smart Toilet
- Smart Soap Dispenser
- Smart Faucets
- Smart Showers
- Smart Bathroom Mirrors
- Smart Bathtubs
- Others
By Application
- Residential
- Commercial
- Hotels & Restaurants
- Gyms
- Spa & Wellness Centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The smart bathroom market is highly competitive, with key players focusing on innovation, connectivity, and sustainability to gain market share. Leading companies such as Moen Incorporated, Kohler Co., GROHE AMERICA (LIXIL Corporation), TOTO LTD., and Roca Sanitario S.A. dominate through continuous product advancements and strategic partnerships. These players invest heavily in smart technologies, integrating AI, IoT, and sensor-based automation to enhance hygiene, comfort, and water efficiency. For instance, Kohler’s Numi 2.0 intelligent toilet and Moen’s Smart Water Network exemplify innovation in connected bathroom systems. Emerging brands like Duravit AG, Villeroy & Boch AG, and Signature Hardware focus on design-driven smart fixtures and energy-saving products. Strategic mergers, digital integration, and sustainability-focused manufacturing practices are shaping the competition, while global expansion and product diversification remain core strategies driving long-term market positioning.
Key Player Analysis
- Moen Incorporated
- GROHE AMERICA, INC. (LIXIL Corporation)
- Roca Sanitario, S.A
- Delta Faucet Company
- Kohler Co.
- Duravit AG
- TOTO LTD.
- Villeroy & Boch AG
- American Standard (LIXIL Corporation)
- Jacuzzi Brands, LLC
- Kraus USA Plumbing LLC
- Pfister (Spectrum Brands, Inc.)
- Signature Hardware (Ferguson Enterprises, LLC)
Recent Developments
- In March 2023, Roca introduced the In-Wash Insignia shower toilet, which incorporates Roca Connect technology to provide unparalleled comfort and hygiene. Through the accompanying mobile app, called In-Wash Insignia, users can conveniently customize and regulate various operational modes and daily functionalities. Additionally, the app provides valuable insights into water usage and toilet utilization, empowering users with informative data.
- In January 2023, Kohler launched the Sprig Shower Infusion System, during the CES 2023 event. This groundbreaking aromatherapy shower infusion system introduces the Sprig Shower Pods, which have the ability to infuse the water stream with an array of delightful scents such as lavender and eucalyptus. These pods also contain skin-friendly ingredients, ensuring a rejuvenating and luxurious spa-like experience that can be enjoyed on a daily basis.
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of smart home ecosystems will continue to drive demand for connected bathroom fixtures.
- Integration of AI and IoT technologies will enhance automation, personalization, and remote monitoring.
- Water and energy-efficient smart systems will gain more importance under sustainability initiatives.
- Touchless and voice-controlled products will expand in both residential and commercial settings.
- The hospitality and wellness industries will increasingly adopt smart bathroom solutions to enhance guest experiences.
- Manufacturers will focus on developing affordable smart fixtures to penetrate mid-range markets.
- Advancements in predictive maintenance and self-cleaning technologies will improve product lifespan and convenience.
- Regional expansion in Asia Pacific will accelerate due to rising urbanization and smart infrastructure growth.
- Strategic collaborations among global and regional players will strengthen product innovation and distribution networks.
- Enhanced cybersecurity measures will become essential as connectivity and data exchange in bathrooms increase.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Smart Bathroom Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Smart Bathroom Market projected to grow between 2025 and 2032?
Which Smart Bathroom Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Smart Bathroom Market?
Who are the leading companies in the Smart Bathroom Market?
Which region commanded the largest share of the Smart Bathroom Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6.71 billion → 2032: USD 15.59 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Bathroom Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Bathroom Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Bathroom Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Bathroom Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Bathroom Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Bathroom Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Bathroom Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Bathroom Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6.71 billion → 2032: USD 15.59 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Bathroom Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Bathroom Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Smart Bathroom Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Smart Bathroom Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

