
Quick answer
A potato processing plant, modeled here as a frozen french fry line producing 2.5 tonnes per hour (about 15,000 tonnes a year), costs about USD 11–17 million to build at an Asian industrial site in 2026, including land, raw potato cold storage and IQF freezing. Gross margin is estimated at 28–38%, driven mainly by delivered potato cost of USD 0.16–0.18 per kg, and simple payback is 4–7 years at 75–85% utilization.
Feasible for promoters who lock in contract-farmed fry-grade potatoes and QSR or export offtake before construction; risky without both, as new capacity in Asia and South America sharpens price competition.
Potato plant: key highlights
| Parameter | Indicative value | Note |
|---|---|---|
| Plant capacity | 2.5 t/h finished fries | About 15,000 tonnes a year at 6,000 operating hours |
| Total CapEx | USD 11–17 million | Greenfield, Asian cost region; U.S. or EU sites cost roughly two to three times as much |
| Raw material share of operating cost | 54–60% | Contract fry-grade potatoes incl. storage shrink |
| Gross margin | 28–38% | At USD 1.00–1.15 per kg ex-factory |
| Payback period | 4–7 years | Simple, pre-tax, at 75–85% utilization |
| IRR | Available in report | Post-tax, 10-year model |
| Break-even | Available in report | Capacity utilization basis |
Ranges assume a 2.5 t/h greenfield frozen french fry plant (about 15,000 tonnes a year), an Asian industrial park cost region, 2026 prices, 75–85% utilization, 2.2–2.3 kg of potato per kg of fries, potatoes at USD 0.16–0.18 per kg delivered, ex-factory price USD 1.00–1.15 per kg and 88 rupees per USD where Indian costs are converted. The full report can be customized to any country.
What is potato processing?
Potato processing turns raw tubers into shelf-stable foods such as frozen french fries, potato specialties (wedges, hash browns, coated shapes), dehydrated flakes and fried chips. This prefeasibility overview models the configuration that attracts most new commercial investment worldwide, a frozen french fry line, sized at 2.5 tonnes of finished fries per hour. That is an entry-to-mid-scale line; world-scale plants in North America and Europe run 15–30 tonnes per hour. Chip plants are more numerous but are mostly captive to snack brands, and flake plants remain few.
Fry-grade processing needs long oval tubers with 20–24% dry matter and low reducing sugars, so plants contract varieties such as Russet Burbank, Innovator, Fontane, Santana or Kufri Frysona instead of buying table potatoes. Products are graded by cut size (6–7 mm shoestring, 9–10 mm regular, 12–14 mm steak), by coating (plain or batter-coated) and by finish (par-fried for fryers or oven-ready). Frozen fries are classified under HS 2004.10 (potatoes prepared or preserved, frozen), chips under 2005.20 and potato flakes under 1105.20. Buyers are quick-service restaurant (QSR) chains, hotels and caterers, retail freezer aisles and importers in Asia, the Middle East and Latin America.
Potato processing market overview and global demand
Credence Research estimates the global processed potato market at about USD 72 billion in 2025, based on its USD 68.6 billion for 2024 and a 4.95% CAGR, reaching USD 101.0 billion by 2032. Within that total, the frozen potato fries market was valued at USD 25.97 billion in 2024 and is projected to grow 4.17% a year. Demand comes from QSR expansion in Asia, the Middle East and Latin America, plus rising retail sales of oven and air-fryer formats.
Raw material supply is broad but uneven. World potato output reached about 383 million tonnes in 2023, led by China at 93.5 million tonnes, India at 60.1 million and Ukraine at 21.4 million, according to FAOSTAT data. Only a fraction of that is fry-grade, which ties processing to regions with contract farming and storage.
Trade is concentrated in a few exporters. In 2023, Belgium shipped about 2.91 million tonnes of frozen potatoes worth USD 3.97 billion, the Netherlands 1.95 million tonnes worth USD 2.79 billion, Canada 1.35 million tonnes and the United States 0.89 million tonnes, UN Comtrade data on WITS show. Implied unit values ran about USD 1.35–1.65 per kg. Newer exporters such as China, India and Egypt compete on price in Asia and the Gulf; India alone shipped about 277,000 tonnes of value-added potato products in 2025-26. QSR chains buy on annual contracts with tight length and color specifications, so the main commercial risk is price pressure as new capacity in Asia and South America comes online.
Frozen potato fries manufacturing process
A frozen fry line is a continuous wet process in which yield, color and oil uptake are largely fixed within the first hour after peeling. The steps below describe a plant with 2.5 tonnes per hour of finished output that draws about 5.5 tonnes of raw potatoes per hour.
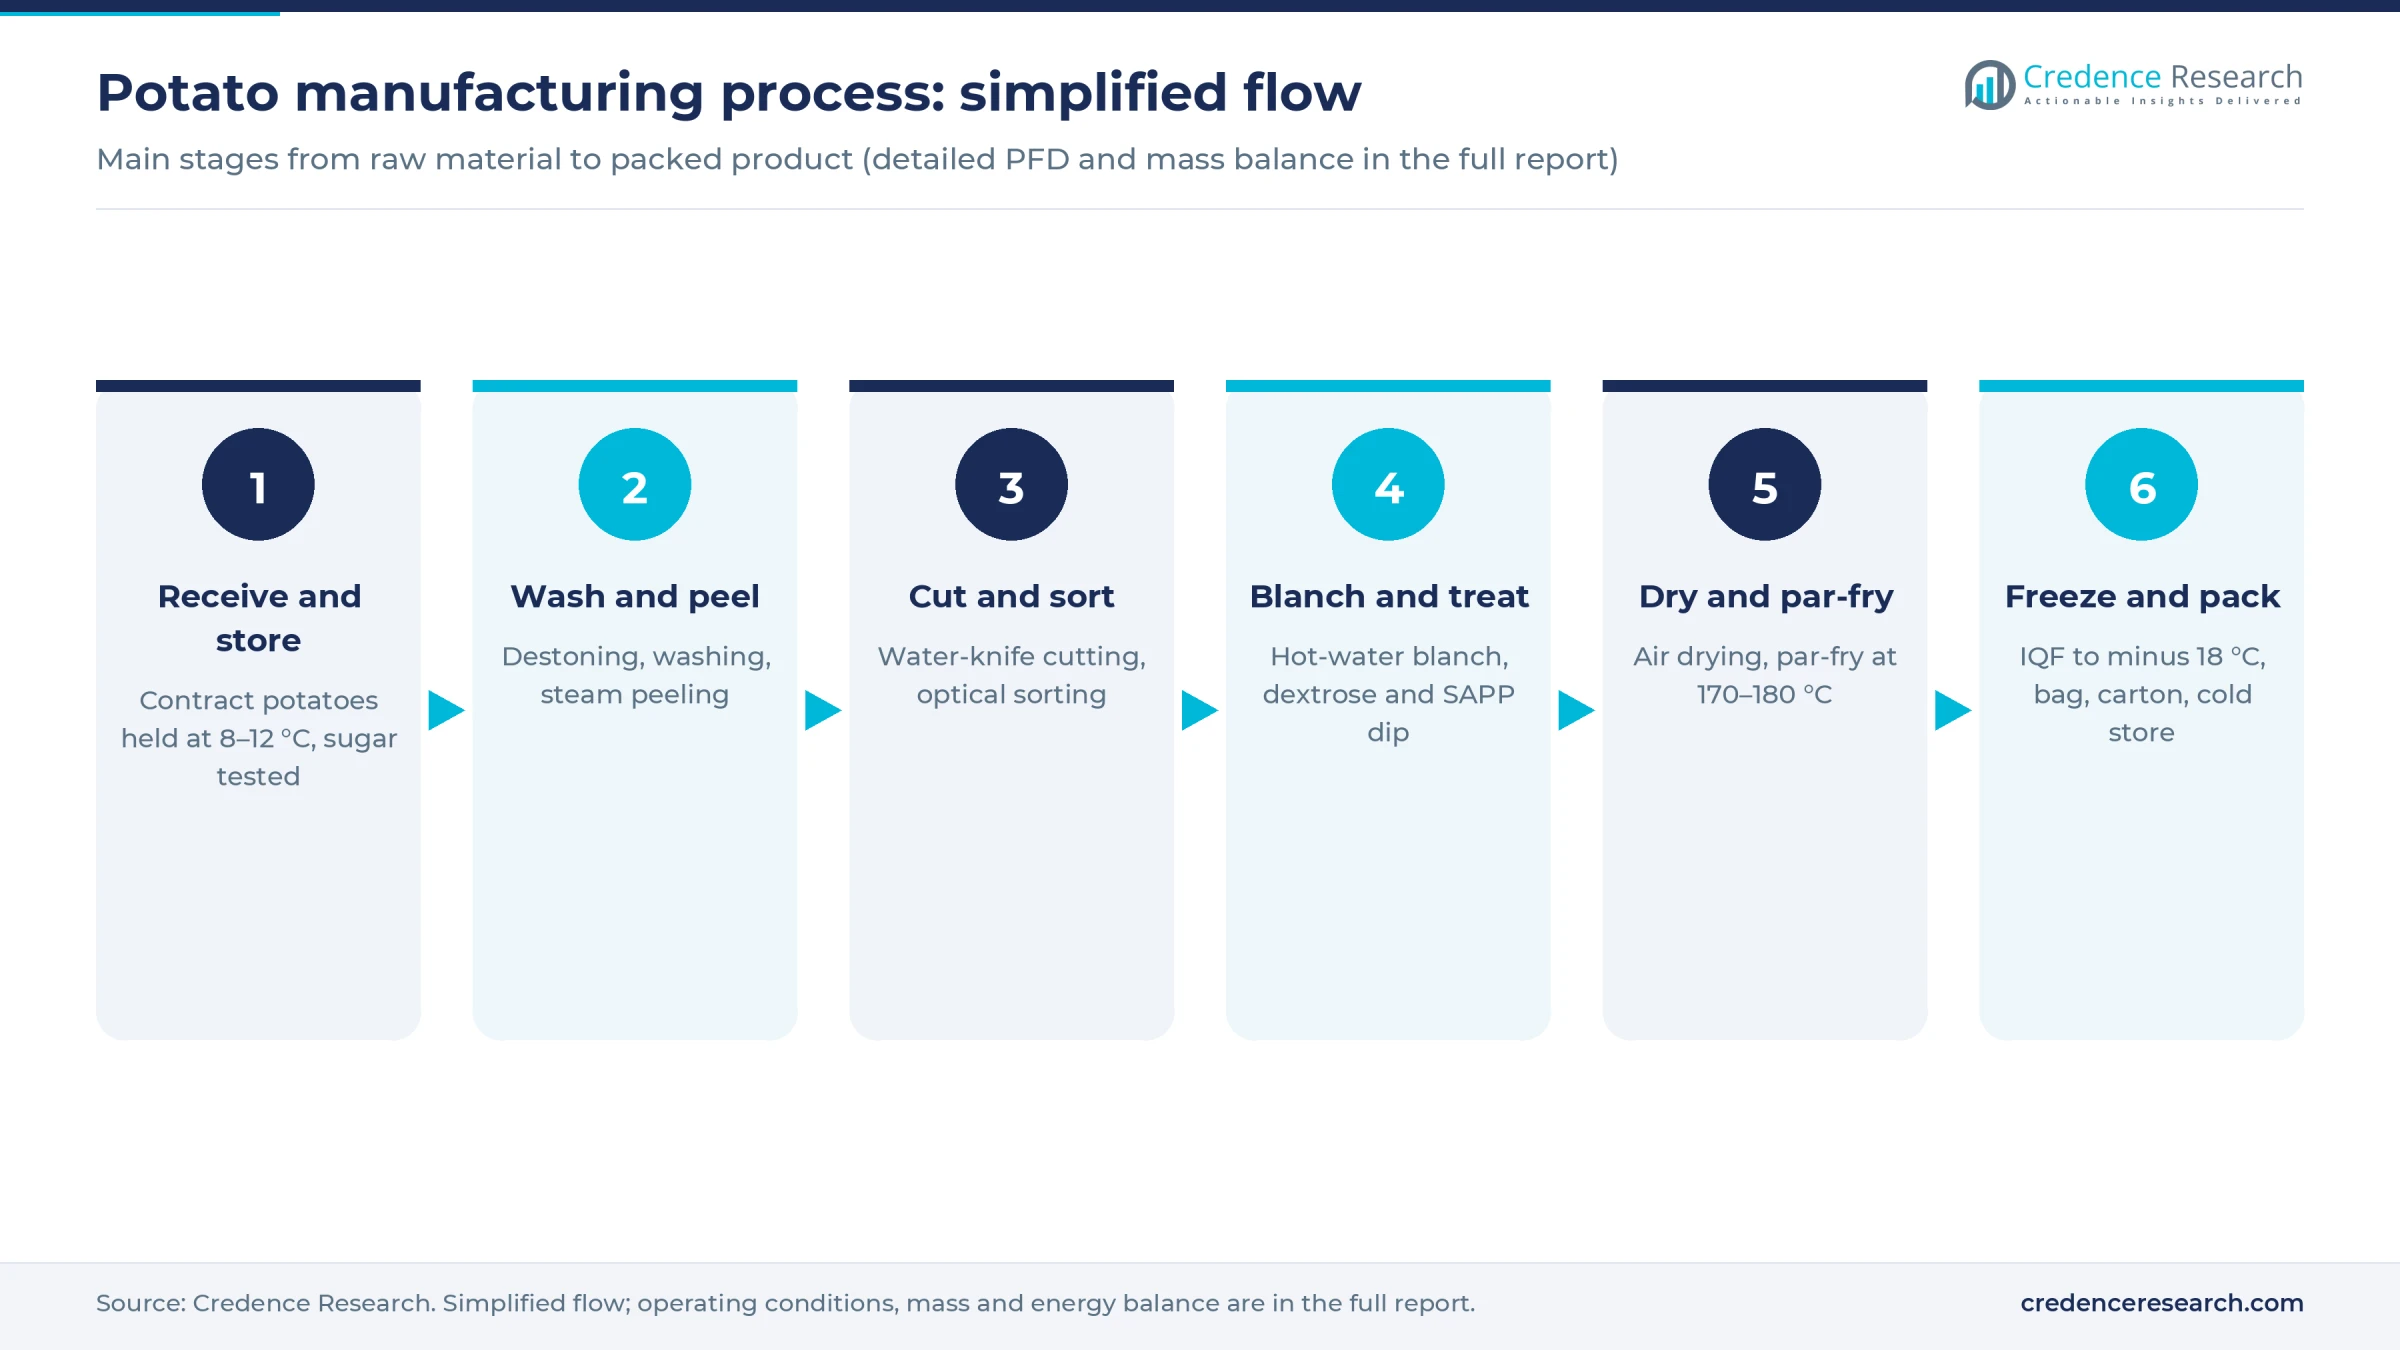
- Receiving and reconditioning. Potatoes arrive over a harvest window of two to four months and are held at 6–12 °C, depending on variety. Colder storage triggers sugar build-up that darkens fries, so each lot is reconditioned and tested for reducing sugars and dry matter before it enters the line.
- Washing, destoning and steam peeling. A high-pressure steam peeler removes the skin with roughly 8–12% weight loss, far less than abrasive peeling.
- Cutting and sorting. A hydraulic water-knife system pumps tubers through a blade grid at the target strip size, and optical sorters reject slivers, defects and green or bruised strips.
- Blanching and treatment. Strips are blanched in hot water at 70–85 °C to inactivate enzymes, leach excess sugar and gelatinize surface starch, then dipped in dextrose and sodium acid pyrophosphate (SAPP) to standardize color and prevent graying. Blanching also cuts acrylamide formation, which EU rules now benchmark.
- Drying and par-frying. Air drying removes surface water before a 45–70 second par-fry at about 170–180 °C in palm, sunflower or canola oil, which sets the crust and oil content.
- Freezing, packing and frozen storage. Cooled fries pass through a spiral or tunnel IQF freezer to a core temperature of minus 18 °C, are weighed into 2.5 kg food-service bags or retail packs, cartoned and held at minus 20 °C until dispatch in reefer containers.
Overall recovery runs about 43–46% of raw potato weight to finished fries, so every point of dry matter or peel loss shows up directly in cost per kilogram. Byproducts such as peel, slivers, short strips and starch recovered from cutting water sell as cattle feed, starch or flake feedstock, and starch recovery also cuts the effluent load.
Potato processing plant setup cost
For a greenfield plant producing 2.5 tonnes of frozen fries per hour, about 15,000 tonnes a year at 6,000 operating hours, with its own raw potato cold store, total capital cost is estimated at USD 11–17 million at 2026 prices in an Asian industrial park. The range is built from disclosed Indian projects converted at 88 rupees per U.S. dollar: Banas Dairy's 2026 expansion added 3 tonnes per hour of fry capacity for about USD 5.9 million, to which a greenfield site adds land, buildings, storage and utilities, and Allana Consumer Products budgeted about USD 34 million for 40,000 tonnes a year across two units. A U.S. or EU site costs roughly two to three times as much per tonne; Lamb Weston's USD 415 million line in Idaho added about 159,000 tonnes a year, or about USD 2,600 per annual tonne against USD 750–1,150 here. The full report can be customized to any country.
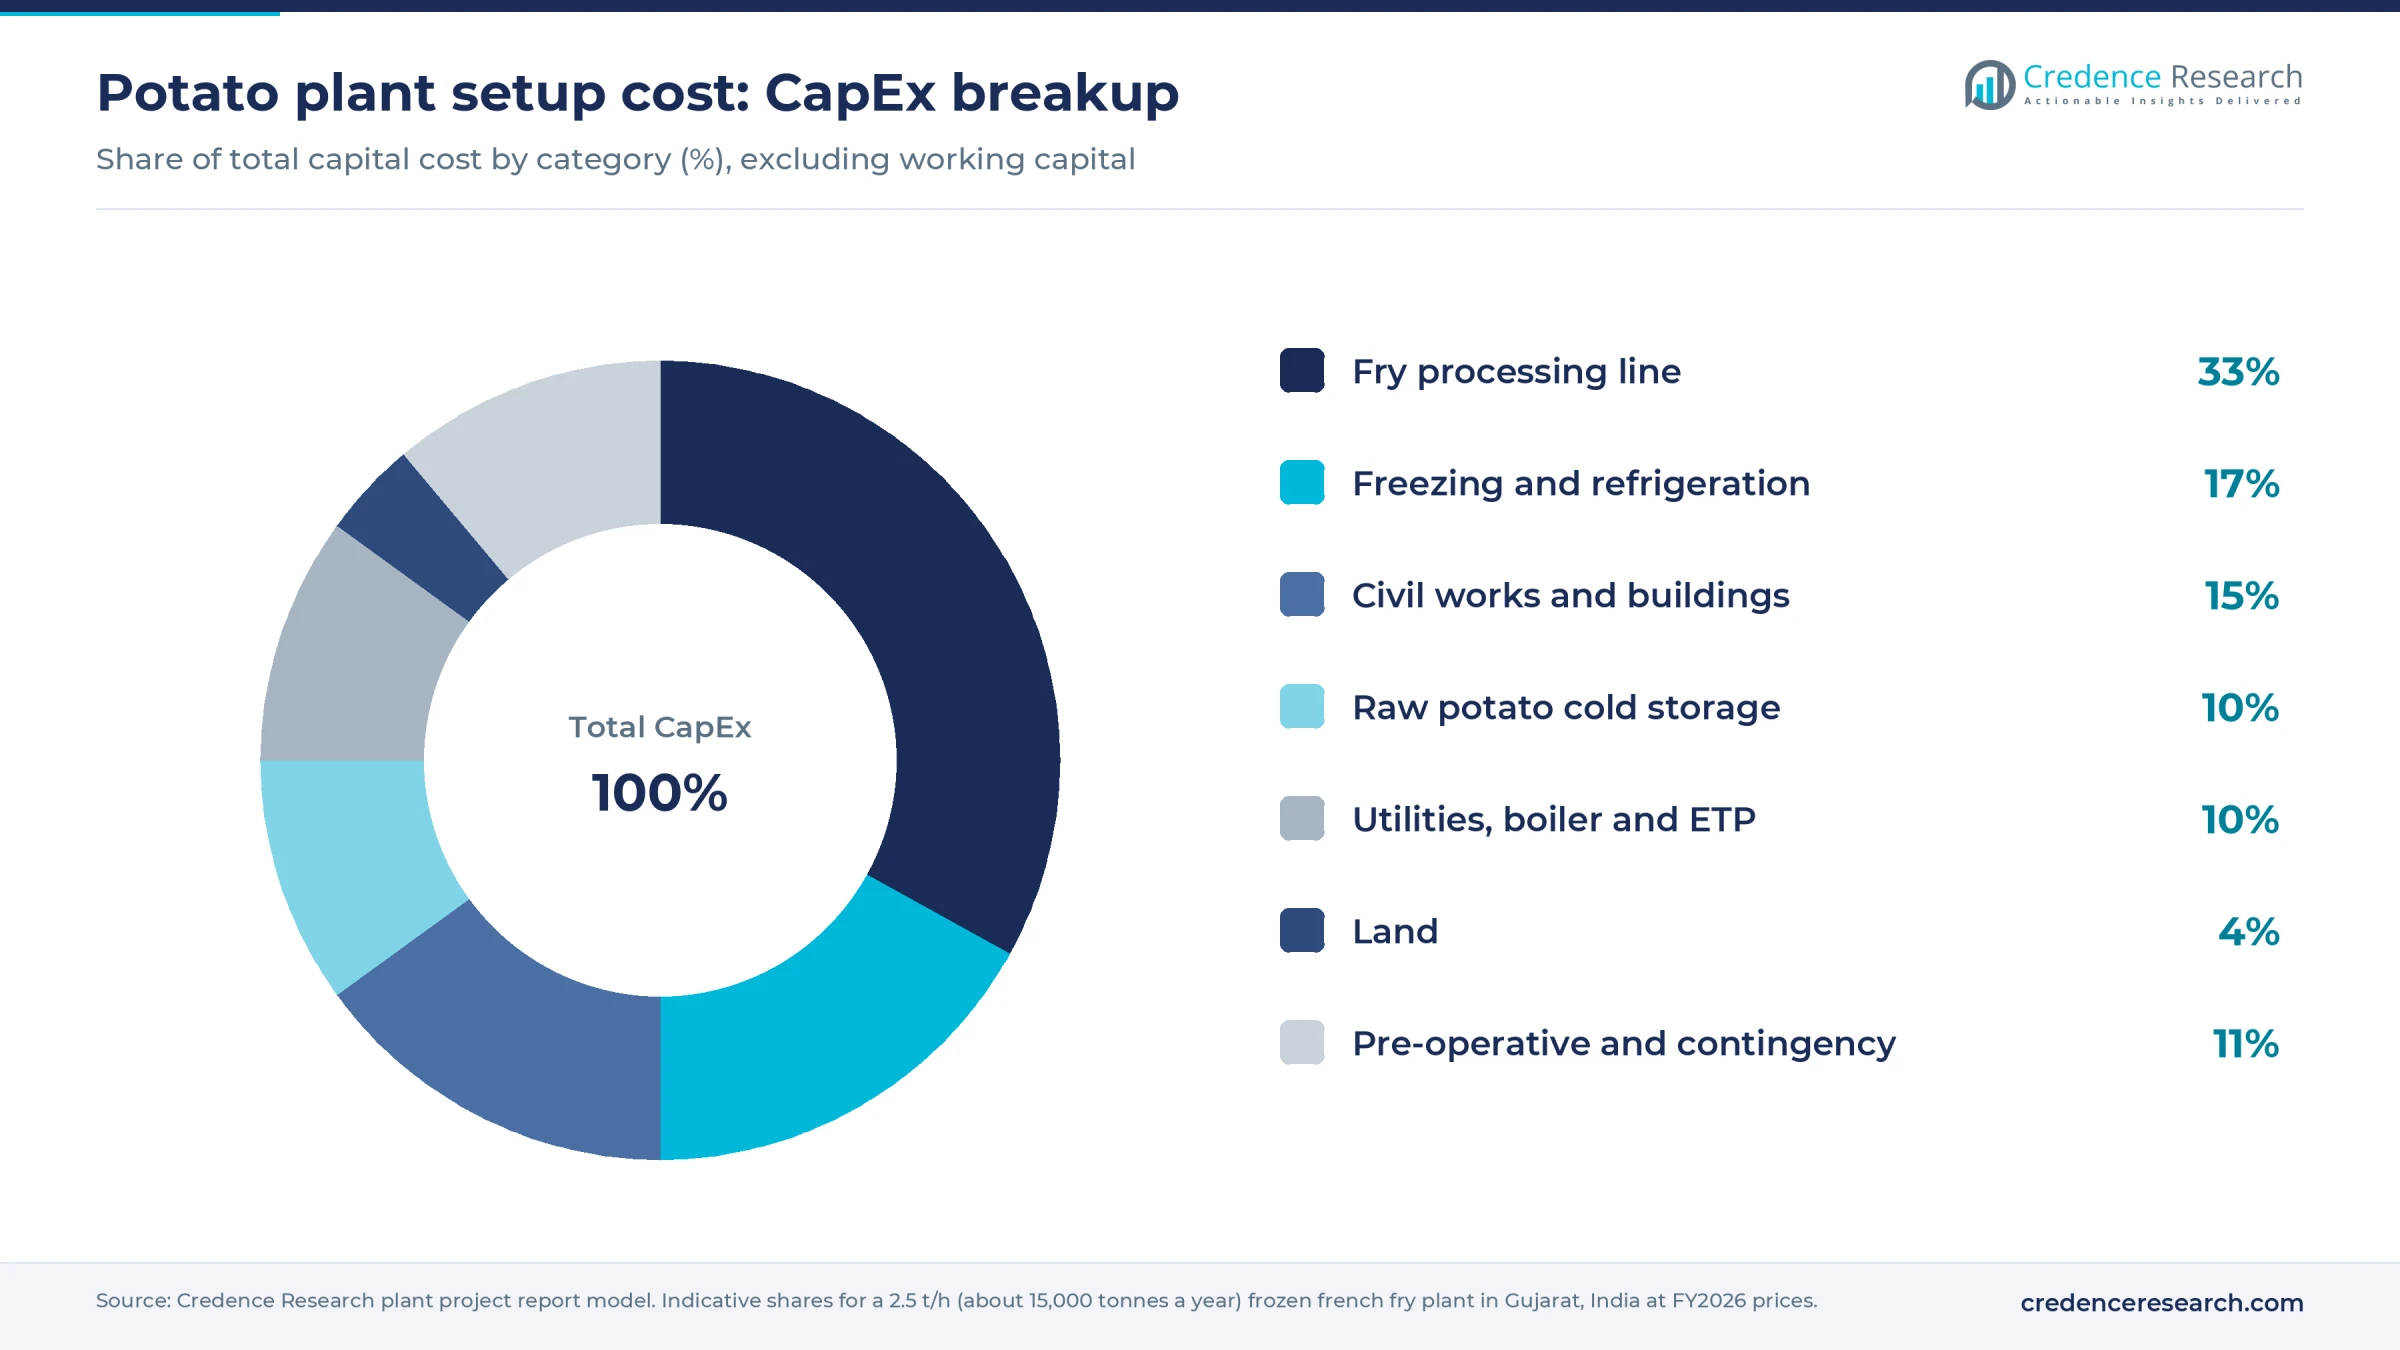
Land is the clearest worked example. A fry plant with raw storage, frozen storage, an effluent plant and truck circulation needs 8–10 acres, or about 32,000–40,000 square meters. In Gujarat, a leading Asian processing cluster, state industrial estate allotment prices for FY2026-27 run about USD 17–43 per square meter, so the plot costs about USD 0.55–1.7 million, or about 4% of project cost at the lower price and up to 10% at the higher. At an assumed USD 50–150 per square meter for a U.S. or EU industrial site, the same plot would cost USD 1.6–6 million. Raw potato storage of about 15,000 tonnes is budgeted at USD 90–115 per tonne of capacity.
Operating cost is dominated by potatoes. At 75–85% utilization, raw potatoes including storage shrink account for 54–60% of cash operating cost, followed by power and fuel for steam, frying and refrigeration, frying oil, packaging and labor.
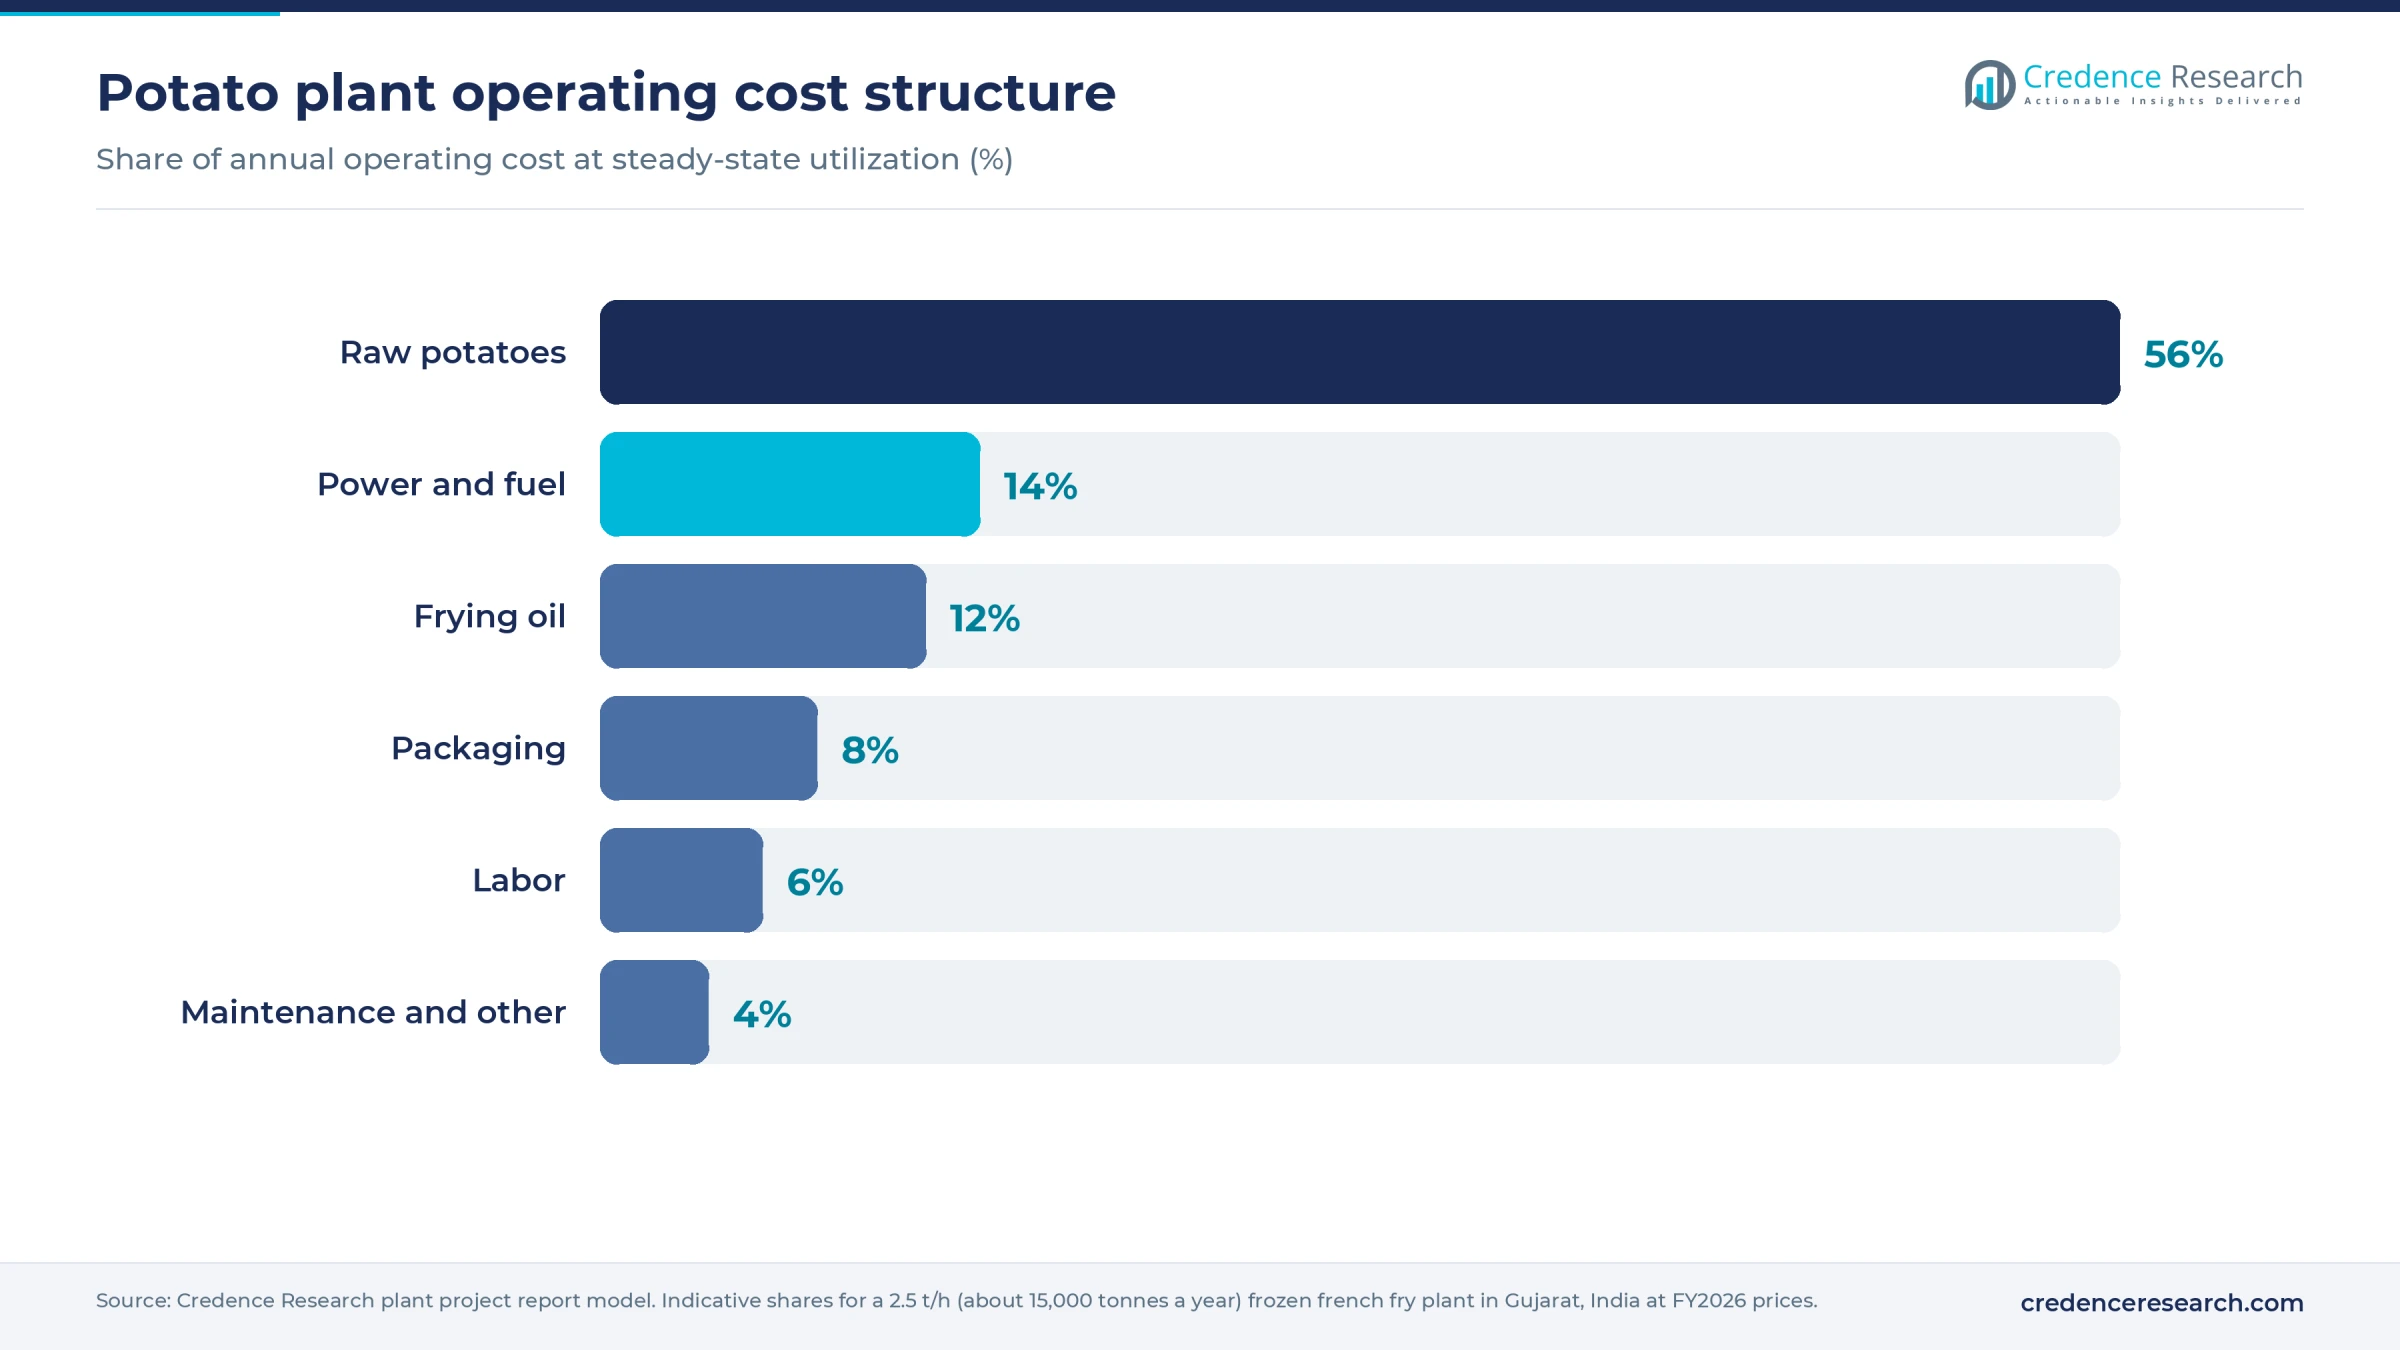
Machine-wise costs, the construction schedule and the working capital build, which must finance six to eight months of stored potatoes, are available in the full report.
Machinery and raw materials for a potato processing plant
Main plant machinery
- Receiving hoppers, destoners and barrel washers
- Steam peeler with brush scrubber
- Hydraulic water-knife cutting system
- Optical and laser sorters
- Blancher, dextrose and SAPP dip, and belt dryer
- Continuous par-fryer with oil filtration and thermal oil heater
- Spiral or tunnel IQF freezer with ammonia refrigeration plant
- Multihead weighers, baggers and case packers
- Boiler, starch recovery unit and effluent treatment plant
Raw materials and sourcing regions
A plant of this size needs about 26,000–29,000 tonnes of fry-grade potatoes a year, which at 30–45 tonnes per hectare means roughly 600–1,000 hectares under contract. The main fry-grade belts are northwest Europe (Belgium, the Netherlands, northern France and Germany), the U.S. Pacific Northwest and Idaho, Canada's prairies and Maritime provinces, north China (Inner Mongolia, Gansu), Gujarat in western India, Egypt's Nile Delta and the Buenos Aires province of Argentina. Processors usually supply certified seed and fix contract prices before planting, which shields them from table-potato swings but locks in cost when spot prices fall. Other inputs are palm, sunflower or canola oil at about 5–7% of fry weight, dextrose, SAPP, food-service poly bags, corrugated cartons and ammonia refrigerant.
Potato processing business profit margin and ROI
Revenue depends on the QSR and export price of frozen fries. Major Western exporters averaged USD 1.35–1.65 per kg in 2023, while Asian suppliers sell nearer USD 1.00–1.15 per kg ex-factory for regular cuts, the price band used here. At 75–85% utilization, the modeled plant would sell 11,250–12,750 tonnes a year for about USD 11–15 million. Gross margin after potatoes, oil, packaging, energy and direct labor is estimated at 28–38%. Contract potato prices have risen sharply in the newer Asian belts; Gujarat growers report about USD 0.15–0.16 per kg for Frysona, up from USD 0.06–0.07 at local markets a few years earlier. After selling, freight and overhead costs of 8–10% of revenue, simple payback falls in the 4–7 year range.
Each USD 0.01 per kg change in delivered potato cost moves gross margin by about 2 percentage points, more than any other input. Export price, first-two-year utilization and reefer freight rates rank next.
| Metric | Indicative value |
|---|---|
| Gross margin | 28–38% |
| Payback period | 4–7 years |
| Project IRR | Available in report |
| NPV | Available in report |
| ROI | Available in report |
| DSCR | Available in report |
| Break-even utilization | Available in report |
How to start a potato processing business, licenses and approvals
A frozen fry plant typically needs business registration and tax registration, land-use and building permits, an environmental permit covering wastewater discharge and boiler emissions, food business registration or licensing with the national food safety authority, occupational safety compliance for ammonia refrigeration and boilers, and export registration where product is shipped abroad. Fry plants generate large volumes of starchy wastewater, so effluent permits usually set the timeline.
Examples by market
| Market | Key regulator and permits |
|---|---|
| United States | FDA food facility registration and FSMA preventive controls rule (21 CFR Part 117); EPA or state NPDES or local pretreatment permit for wastewater; OSHA Process Safety Management and EPA Risk Management Program where ammonia exceeds 10,000 lb |
| European Union | Food business operator registration with the national authority under Regulation (EC) No 852/2004; national environmental and water discharge permits; acrylamide mitigation and benchmark levels under Regulation (EU) 2017/2158 |
| India | FSSAI central license; state pollution control board consent to establish and operate (Orange category under the CPCB 2016 classification); APEDA registration for exports |
No mandatory product certification applies to frozen fries in these markets beyond food safety rules, though QSR buyers require audited schemes such as BRCGS or FSSC 22000.
Key potato processing companies and recent developments
Global frozen fry supply is led by McCain Foods of Canada, Lamb Weston and J.R. Simplot of the United States, and Aviko, Agristo, Clarebout and Farm Frites in Belgium and the Netherlands. Regional makers include HyFun Foods and Iscon Balaji Foods in India, and a growing group of processors in China, Egypt and Argentina. PepsiCo leads the separate potato chip segment worldwide.
- October 2026: McCain Foods agreed to acquire Falcon Agrifriz Foods' frozen potato business in Gujarat, India, a fully automated plant with more than 450 employees and over 1,000 contract farmers.
- May 2026: Advent International agreed to invest USD 150 million in Iscon Balaji Foods as part of a USD 215 million Series A round, as the company builds a new facility.
- January 2026: Lamb Weston said it would close its Munro, Argentina plant and consolidate Latin American production at a new facility in Mar del Plata, with about 100 Munro employees affected.
Western leaders are buying into fast-growing Asian supply bases and closing older plants, which shows that potato access and freight position, more than equipment, now separate leaders from new entrants.
What's inside the Potato project report PDF
The report runs to 21 chapters. Open a chapter to see its sections.
1. Preface
2. Scope and Methodology
- 2.1 Objectives of the Study
- 2.2 Stakeholders
- 2.3 Research Methodology
- 2.4 Data Sources and Key Assumptions
3. Executive Summary
- 3.1 Market Snapshot
- 3.2 Project at a Glance (Capacity, CapEx, OpEx)
- 3.3 Key Financial Indicators (IRR, NPV, Payback, Break-even)
- 3.4 Feasibility Verdict
4. Product Overview
- 4.1 Potato Definition and Properties
- 4.2 Grades and Specifications (BIS / ISO / ASTM)
- 4.3 HS Code and Classification
- 4.4 Key Applications
- 4.5 Substitutes
5. Global Potato Market
- 5.1 Market Overview
- 5.2 Historical and Current Market Performance (Volume and Value)
- 5.3 Market Breakup by Grade / Type
- 5.4 Market Breakup by End-Use Industry
- 5.5 Market Breakup by Region
- 5.6 Market Drivers, Restraints and Trends
- 5.7 Value Chain Analysis
- 5.8 Market Forecast
6. Target Country Potato Market Analysis
- 6.1 Demand and Supply Analysis
- 6.2 Installed Capacity vs Demand Gap
- 6.3 Import Dependence
- 6.4 Demand Forecast by End-Use
7. Trade Analysis
- 7.1 Imports by Volume, Value and Country
- 7.2 Exports by Volume, Value and Country
- 7.3 Trade Balance and Opportunities
8. Price Analysis
- 8.1 Historical Potato Price Trends by Region
- 8.2 Raw Material / Feedstock Price Trends and Linkage
- 8.3 Price Forecast
- 8.4 Margins Across the Value Chain
9. Competitive Landscape
- 9.1 Market Structure
- 9.2 Key Players and Installed Capacities
- 9.3 Profiles of Key Players
- 9.4 Recent Developments (Expansions, M&A, New Plants)
10. Manufacturing Process and Technology
- 10.1 Comparison of Technology Routes
- 10.2 Selected Route and Process Flow Diagram
- 10.3 Unit Operations Involved
- 10.4 Chemical Reactions Involved
- 10.5 Mass Balance and Raw Material Requirements
- 10.6 Energy Balance
- 10.7 Quality Assurance Criteria and Technical Tests
- 10.8 By-products and Waste Handling
- 10.9 Technology Licensors / Providers
11. Project Details, Requirements and Costs
- 11.1 Land, Location and Site Development
- 11.1.1 Site Selection Criteria
- 11.1.2 Location Analysis
- 11.1.3 Land Requirement and Costs
- 11.1.4 Site Development Costs
- 11.2 Plant Layout
- 11.2.1 Layout Principles
- 11.2.2 Proposed Layout
- 11.2.3 Factors Influencing Layout
- 11.3 Civil Works and Buildings
- 11.4 Plant Machinery
- 11.4.1 Machinery Requirements and Specifications
- 11.4.2 Machinery Costs
- 11.4.3 Machinery Suppliers
- 11.5 Raw Materials
- 11.5.1 Requirements per Tonne of Output
- 11.5.2 Procurement and Sourcing
- 11.5.3 Costs
- 11.5.4 Suppliers
- 11.6 Packaging
- 11.6.1 Packaging Requirements
- 11.6.2 Packaging Costs
- 11.6.3 Packaging Suppliers
- 11.7 Storage and Material Handling
- 11.8 Transportation Requirements and Costs
- 11.9 Utilities
- 11.9.1 Power Requirements and Costs
- 11.9.2 Water Requirements and Costs
- 11.9.3 Steam, Fuel and Other Utilities
- 11.10 Manpower Requirements and Wages
12. Environment, Health, Safety and Sustainability
- 12.1 Effluent and Emissions Management
- 12.2 Hazard Classification and Safety Measures
- 12.3 Carbon Footprint
- 12.4 Green / Low-Carbon Process Options
13. Regulatory Procedures, Approvals and Certifications
- 13.1 Licences and Registrations
- 13.2 Environmental Clearances
- 13.3 Product Certifications (BIS, REACH, etc.)
- 13.4 Approval Timeline
14. Project Implementation Schedule
15. Project Economics
- 15.1 Capital Cost of the Project
- 15.2 Techno-Economic Parameters
- 15.3 Capacity Utilization and Ramp-up
- 15.4 Product Pricing and Margins
- 15.5 Income Projections
- 15.6 Expenditure Projections
- 15.7 Working Capital Requirement
- 15.8 Taxation
- 15.9 Depreciation
16. Financial Analysis
- 16.1 Projected Profit and Loss Account
- 16.2 Projected Cash Flow Statement
- 16.3 Projected Balance Sheet
- 16.4 Liquidity Analysis
- 16.5 Profitability Analysis (Payback, NPV, IRR, ROI)
- 16.6 Break-even Analysis
- 16.7 Debt Service Coverage Ratio (DSCR)
- 16.8 Sensitivity Analysis
- 16.9 Scenario and Uncertainty Analysis
17. Funding and Incentives
- 17.1 Means of Finance and Debt-Equity Structure
- 17.2 Loans and Financial Assistance
- 17.3 Government Schemes and Subsidies (PLI, State Policies)
18. Risk Assessment
- 18.1 Key Success Factors
- 18.2 Key Risk Factors
- 18.3 Risk Mitigation
19. Strategic Recommendations
20. Case Study of a Successful Venture
21. Appendix
- 21.1 Detailed Assumptions
- 21.2 Abbreviations
- 21.3 List of Tables and Figures
- 21.4 Sources
This page vs. the full report
| Data point | On this page (free) | In the full report |
|---|---|---|
| Total CapEx | One rounded range at one capacity | Exact figure at three capacities with a line-item breakup |
| CapEx breakup | Category shares (%) only | Cost, quantity and supplier for every machine |
| Operating cost | Share of raw materials, utilities and labor | Per-unit cost sheet with each input price and consumption |
| Profitability | Gross margin range and payback band | Exact IRR, NPV, ROI, break-even and DSCR |
| Financial statements | List of what is included | 10-year P&L, cash flow, balance sheet and Excel model |
| Sensitivity | One directional line | Full sensitivity and scenario tables |
| Process | Simplified flow diagram | Detailed process flow, mass and energy balance, operating conditions |
| Machinery | Names of the main machines | Specifications, capacity, cost and supplier list |
| Market | Headline size, growth and India demand trend | Segment, region, trade and price forecast tables |
| Suppliers and buyers | Supplier types and sourcing hubs | Named suppliers and buyers |
Potato project report: FAQs
How much does it cost to set up a potato processing plant?
Which potato varieties are used for french fries?
What is the profit margin in a potato processing business?
How many potatoes does a french fry plant need?
Which licenses are needed to start a potato processing business?
What is the payback period for a french fry plant?
Which countries are the largest frozen fries exporters?

About the analyst
Priyanka Mor, Senior Consultant
Senior Consultant at Credence Research Inc directing strategic market advisory, cross-border commercial due diligence and enterprise intelligence frameworks for global B2B clients. Combines quantitative modeling with executive advisory, translating macroeconomic variables and supply chain data into go-to-market blueprints, M&A screenings and competitive war-gaming strategies.
Related market research
- Frozen French Fries Market Size, Growth, Share and Forecast 2032
- French Fries Market Size, Growth, Share and Forecast 2032
- Frozen Potato Market Size, Share, Growth and Forecast 2032
- Dehydrated Potato Products Market Size, Share and Growth Report 2032
- Seed Potato Market Size, Growth, Share and Forecast 2032
- Potato Protein Market Size, Growth, Share and Forecast 2032
More plant project reports
- Corn Starch Manufacturing Plant Project Report (DPR) 2026
- Cassava Starch Manufacturing Plant Project Report (DPR) 2026
- Cassava Processing Plant Project Report (DPR) 2026
- Copper Sulphate Manufacturing Plant Project Report (DPR) 2026
- Ceiling Fan Manufacturing Plant Project Report (DPR) 2026
- Avocado Processing Plant Project Report (DPR) 2026