
Europe Prescription Drugs Market Overview:
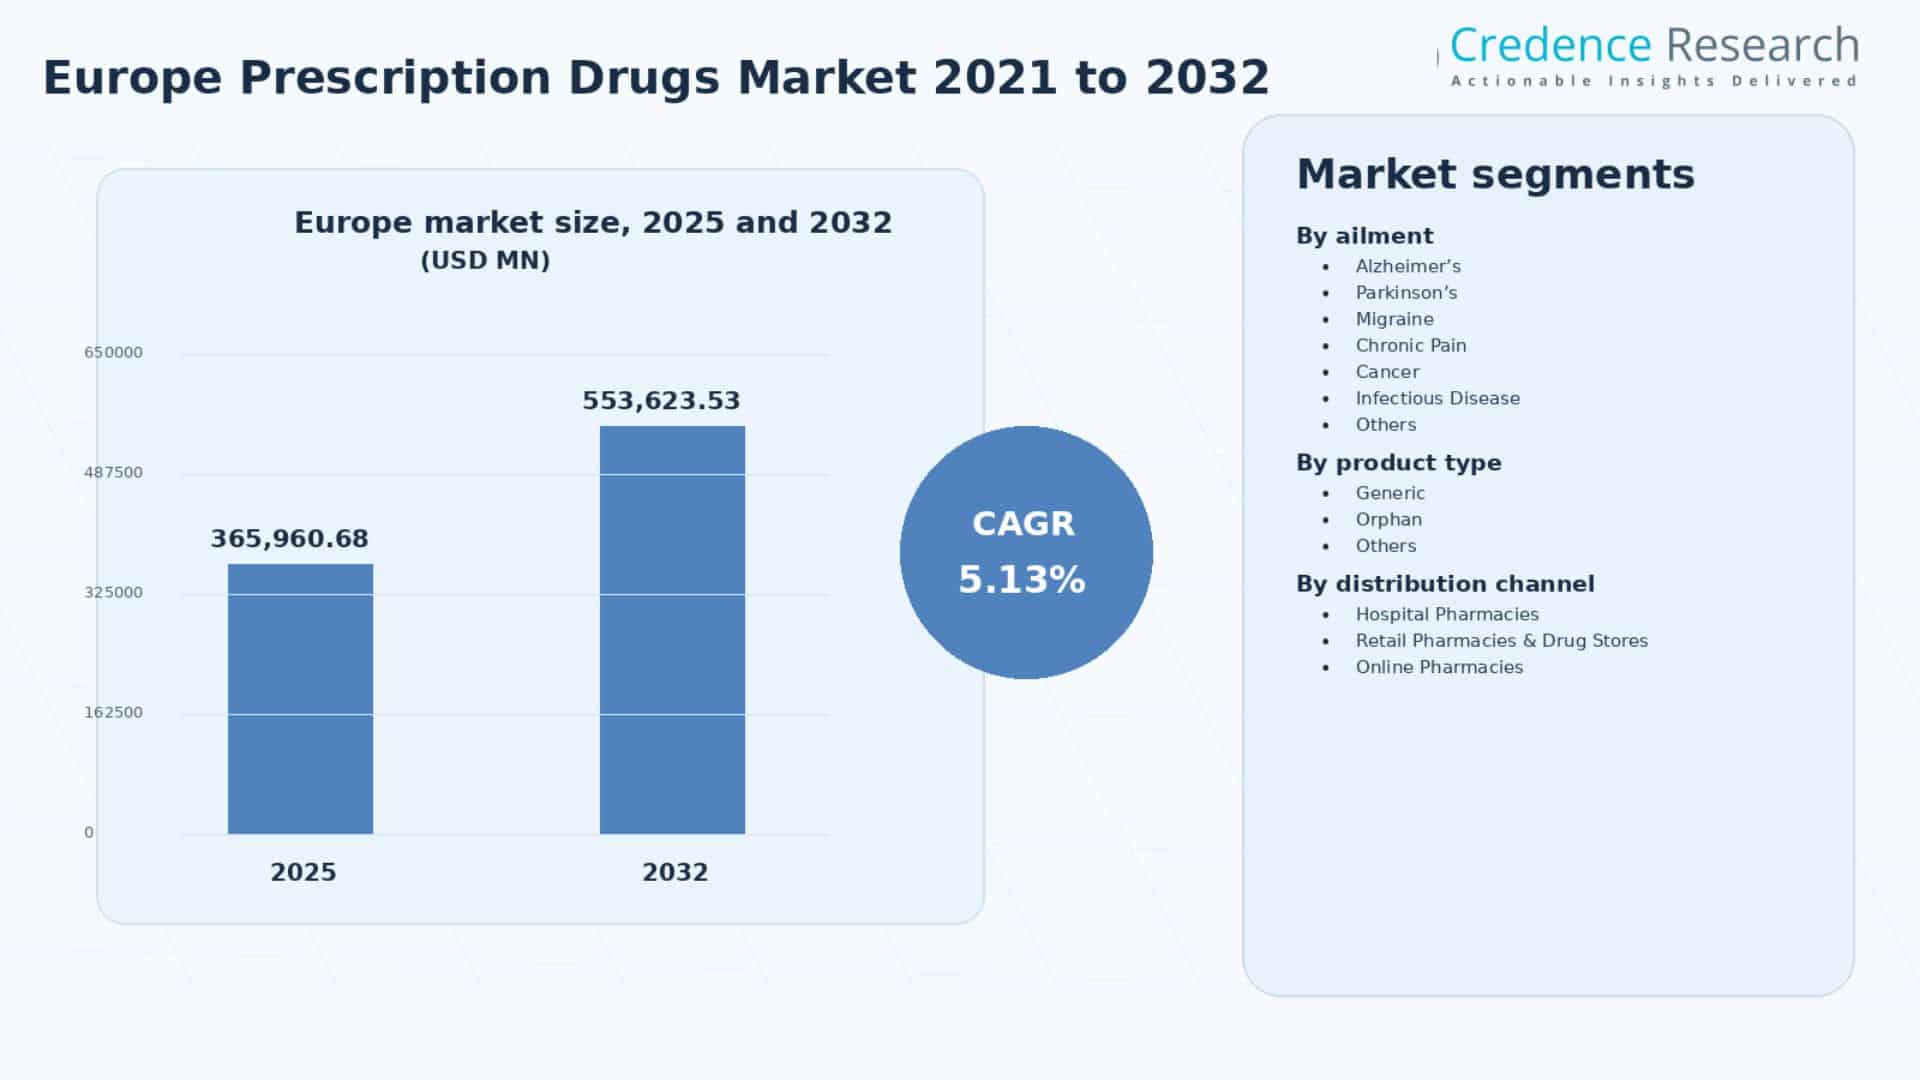
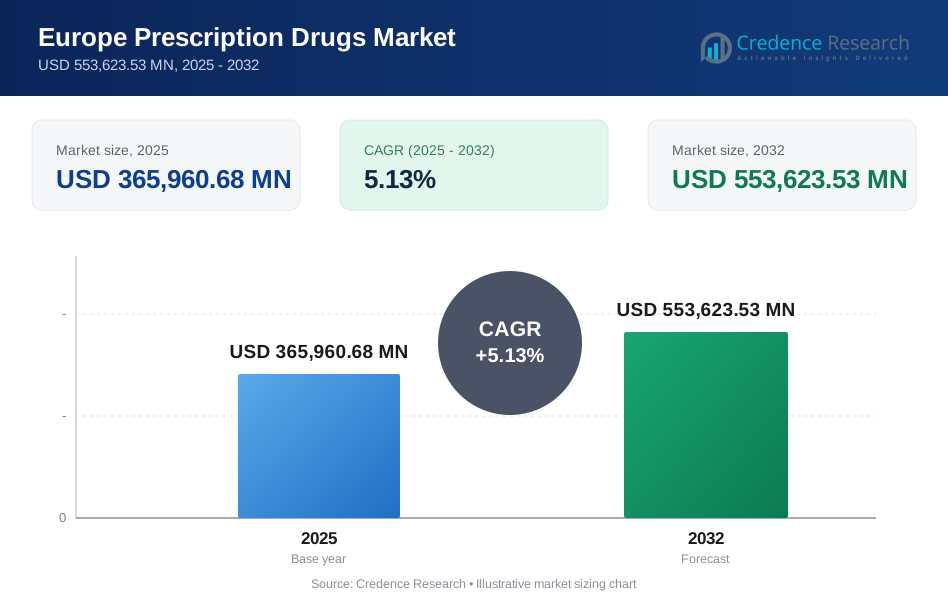
The Europe Prescription Drugs Market size was valued at USD 294,866.12 MN in 2021 and reached USD 365,960.68 MN in 2025. It is anticipated to reach USD 553,623.53 MN by 2032, growing at a CAGR of 5.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2025-2032 |
| Europe Prescription Drugs Market Size 2025 | USD 365,960.68 million |
| Europe Prescription Drugs Market, CAGR | 5.13% |
| Europe Prescription Drugs Market Size 2032 | USD 553,623.53 million |
Europe Prescription Drugs Market Insights
- Market growth is supported by cancer treatment demand, neurological disorder drug innovation, infectious disease prescribing needs, orphan medicine approvals and continued use of generic prescription drugs across mature European health systems.
- Cancer holds a strong position because Europe has a large oncology treatment base and prescription drug portfolios increasingly include targeted therapies, immunotherapies, radioligand therapies and advanced oral oncology products.
- Generic drugs remain important because European payers use generics to control prescription spending, manage patent expiries and support broad access across chronic and infectious disease indications.
- Hospital Pharmacies remain the leading distribution channel because oncology, orphan drugs, advanced infectious disease therapies and complex neurological treatments often require specialist prescribing, monitoring and reimbursement control.
Europe Prescription Drugs Market Segment Insights
By ailment
By ailment, Cancer held the strongest position in 2025 because oncology care in Europe increasingly relies on targeted prescription drugs, immunotherapies, oral anticancer medicines, radiopharmaceuticals and supportive therapies. Alzheimer’s is gaining importance as the European Commission authorized new early-stage Alzheimer’s medicines in 2025, expanding the treatment landscape for neurologic prescription drugs. Migraine supports demand for CGRP-targeted therapies and acute migraine drugs, while Parkinson’s remains a steady chronic prescription category. Chronic Pain supports demand for analgesics, anti-inflammatory drugs, anticonvulsants and non-opioid treatment innovation. Infectious Disease remains important due to antimicrobial resistance, antivirals, HIV medicines and hospital-managed infection treatment. Others include cardiovascular, respiratory, endocrine, immunology and gastrointestinal prescription drugs.
By product type
By product type, Generic held a strong position in 2025 because Europe’s mature reimbursement systems depend on lower-cost medicines to manage public drug spending and expand prescription access. Generic competition is especially important in chronic diseases, infectious disease, pain management and off-patent specialty categories. Orphan drugs are gaining value because rare disease, oncology, neurology and metabolic disorder therapies continue to receive regulatory attention and market exclusivity incentives. Others include branded originator drugs, specialty prescription medicines, biologics, biosimilars, targeted therapies and hospital-only medicines. Product mix growth will depend on patent expiries, payer policy, national formularies, orphan approvals and pricing negotiations.
By distribution channel
By distribution channel, Hospital Pharmacies held the strongest position in 2025 because many high-value prescription drugs require specialist initiation, infusion capacity, hospital formularies, inpatient use or strict monitoring. Oncology drugs, orphan medicines, severe infectious disease treatments and advanced neurological therapies are concentrated in hospital systems. Retail Pharmacies & Drug Stores remain essential for chronic care, generic prescriptions, migraine drugs, pain medicines, antibiotics and refill-based outpatient therapy. Online Pharmacies are gaining relevance through e-prescriptions, home delivery, refill coordination and digital access, but prescription verification and national regulation shape adoption. Growth will favor channels with strong payer integration, product traceability and patient adherence support.
Key Market Drivers
Cancer burden and oncology prescription drug demand
Cancer burden and oncology prescription drug demand represent major growth drivers for the Europe Prescription Drugs Market. Oncology medicines account for a significant share of high-value prescription drug spending because cancer treatment increasingly uses targeted drugs, immuno-oncology, oral anticancer products and hospital-managed therapies.
The European Commission reported that 2.7 million people in the EU were diagnosed with cancer in 2024 and 1.3 million people died from the disease, while cancer cases are projected to increase by 24% by 2035 without decisive action. AstraZeneca reported that oncology medicines accounted for 41% of its Europe product sales in 2025, with oncology sales rising 20% to USD 4,880 million, driven by Tagrisso, Imfinzi, Calquence and Lynparza. This driver supports Cancer, Orphan, Others and Hospital Pharmacies.
Neurological disease innovation and prescription access
Neurological disease innovation and prescription access are strengthening demand across Alzheimer’s, Migraine, Parkinson’s and Chronic Pain categories. Alzheimer’s disease treatment is changing as Europe authorizes therapies for early-stage disease under defined patient selection and monitoring criteria.
EMA reported that Leqembi received EU marketing authorization on April 15, 2025 for adults with mild cognitive impairment or mild dementia due to Alzheimer’s disease who meet specified ApoE4 and amyloid pathology criteria. The European Commission also granted EU marketing authorization for Kisunla in September 2025 to treat mild cognitive impairment, including mild dementia, in early-stage Alzheimer’s disease. This driver supports Alzheimer’s, Hospital Pharmacies and specialist-led prescription access.
Migraine and chronic pain treatment expansion
Migraine and chronic pain treatment expansion supports prescription volume across outpatient and specialist settings. EMA states that Vydura is authorized in the EU for acute treatment of migraine with or without aura in adults, while Aimovig is authorized to prevent migraine in adults who have migraines at least four days a month. Pain therapy innovation also remains active globally; FDA approved Vertex’s Journavx in 2025 as a first-in-class non-opioid analgesic for moderate to severe acute pain in adults, although European market uptake would depend on regional authorization and reimbursement. This driver supports Migraine, Chronic Pain, Retail Pharmacies & Drug Stores and specialist neurology channels.
Infectious disease and antimicrobial resistance pressure
Infectious disease and antimicrobial resistance pressure sustain demand for prescription antibiotics, antivirals, HIV therapies and hospital-managed anti-infectives. The European Commission reports that antimicrobial resistance is responsible for more than 35,000 deaths every year in the EU/EEA and that ECDC data show significantly increasing trends in infections and attributable deaths for almost all bacterium–antibiotic resistance combinations, especially in health care settings. EMA’s 2025 human medicines highlights included Yeytuo, lenacapavir, for pre-exposure prophylaxis to reduce the risk of sexually acquired HIV-1 infection in adults and adolescents at high risk. This driver supports Infectious Disease, Hospital Pharmacies, Generic drugs and newer branded prescription products.
Orphan medicine and new drug authorization momentum
Orphan medicine and new drug authorization momentum supports market value because rare disease and high-unmet-need indications command premium prescription drug pricing and specialist distribution. EMA reported that 104 medicines were recommended for marketing authorization in 2025 and 16 had their orphan designation confirmed by the end of the year. Novartis reported Europe sales of USD 16.7 billion in 2025, up 8%, mainly driven by Kesimpta, Entresto, Kisqali and Pluvicto, while Aimovig sales grew due to increased demand for migraine prevention. This driver supports Orphan, Others, Cancer, Alzheimer’s, Migraine and Hospital Pharmacies.
Key Trends and Opportunities
Alzheimer’s prescription market enters a new phase
Alzheimer’s prescription treatment is entering a new phase in Europe as authorized disease-modifying therapies create new clinical pathways for early diagnosis, biomarker testing, MRI monitoring and specialist prescribing. Leqembi and Kisunla approvals show how neurology prescriptions are shifting toward patient selection, amyloid confirmation and hospital-led treatment infrastructure. This trend creates opportunities for Hospital Pharmacies, specialist memory clinics, diagnostic partners and companies with neurology portfolios. Adoption will depend on national reimbursement, infusion capacity, monitoring requirements, physician confidence and health technology assessment outcomes.
Oncology portfolios drive high-value prescription sales
Oncology portfolios are driving high-value prescription sales as European treatment pathways expand across lung cancer, breast cancer, hematologic malignancies, prostate cancer and gastrointestinal tumors. Roche reported that sales in Europe grew 5% in 2025, supported by strong demand for Ocrevus and Vabysmo and uptake of Polivy, Hemlibra and Phesgo. AstraZeneca also reported strong oncology growth in Europe, showing continued demand for branded oncology prescription drugs. This trend supports Cancer, Orphan drugs, Others and Hospital Pharmacies. Companies with strong oncology launches, combination regimens and biomarker-led indications will gain share.
Generic competition reshapes mature prescription categories
Generic competition is reshaping mature prescription categories across Europe as payers manage drug budgets and patent expiries. Bayer reported that Xarelto sales declined markedly in 2025 because of generic competition, especially in Europe and Japan. This trend creates opportunities for generics manufacturers, retail pharmacy channels and health systems seeking lower-cost access. It also challenges originator companies to defend revenue through lifecycle management, new indications, differentiated formulations and specialty product launches. Generic pressure will remain strongest in mature chronic care, cardiovascular, pain and infectious disease prescriptions.
Online pharmacy and digital prescription channels gain relevance
Online pharmacy and digital prescription channels are gaining relevance as patients seek convenience, repeat refills and faster access to chronic prescription medicines. Retail Pharmacies & Drug Stores remain central, but online platforms can support adherence, refill reminders, delivery and prescription management. Adoption differs by country because pharmacy law, e-prescription systems, reimbursement rules and controlled medicine requirements vary across Europe. Online Pharmacies will gain faster traction in chronic prescription categories, generics, migraine therapy, pain management and stable maintenance medicines. Hospital-only oncology and orphan drugs will remain less exposed to online dispensing due to monitoring and reimbursement complexity.
Key Market Challenges
Pricing pressure and reimbursement controls
Pricing pressure and reimbursement controls remain major challenges for the Europe Prescription Drugs Market. European health systems use reference pricing, health technology assessment, national formularies, tendering and rebate negotiations to control public drug spending. These tools improve access but can reduce revenue growth for branded drugs. Oncology, orphan medicines, Alzheimer’s therapies and specialty drugs face especially close payer scrutiny because they carry high budget impact. Companies must demonstrate clinical benefit, patient selection value, real-world outcomes and cost-effectiveness to secure reimbursement.
Generic erosion and patent expiry risk
Generic erosion and patent expiry risk challenge originator drug sales across mature prescription categories. As major brands lose exclusivity, retail and hospital channels often shift toward generics or lower-cost alternatives. This improves affordability but pressures branded product revenue. Bayer’s 2025 report highlighted marked Xarelto sales decline due to generic competition, especially in Europe and Japan, showing the impact of patent expiry in major prescription categories. Companies must offset erosion through innovation, specialty launches, biologics, orphan medicines, combination therapies and regional lifecycle strategies.
Access variation across European countries
Access variation across European countries can slow market growth because approval at the EU level does not guarantee fast national reimbursement. Countries differ in health technology assessment timelines, pricing rules, hospital budgets, patient co-payment structures and prescription channel regulations. Advanced Alzheimer’s therapies, oncology drugs and orphan medicines may face delayed uptake in some markets due to cost and monitoring requirements. Online Pharmacies also face country-specific restrictions. Companies need tailored access strategies, local evidence and payer engagement to improve launch performance.
Safety monitoring and pharmacovigilance burden
Safety monitoring and pharmacovigilance burden remains high for prescription medicines used in older adults, oncology patients, immunocompromised populations and complex chronic disease groups. Alzheimer’s therapies require MRI monitoring, oncology drugs require adverse event management and anti-infectives require antimicrobial stewardship. EMA’s annual report emphasizes its role in scientific evaluation, safety monitoring, pharmacovigilance standards and EudraVigilance operation for centrally authorized products. Compliance requirements increase operating complexity for manufacturers, hospitals and pharmacies but strengthen trust in prescription drug use.
Regional Analysis
Western Europe
Western Europe leads the Europe Prescription Drugs Market due to strong reimbursement systems, advanced hospitals, high oncology treatment access, established retail pharmacy networks and broad adoption of innovative medicines. Germany, France, the U.K., Switzerland, the Netherlands, Belgium and Austria support strong demand across Cancer, Alzheimer’s, Migraine, Infectious Disease and rare disease prescriptions. Hospital Pharmacies dominate high-value oncology and orphan drugs, while Retail Pharmacies & Drug Stores support generics and chronic therapy refills. Online Pharmacies are gaining relevance where regulations support e-prescription fulfillment. Growth will depend on health technology assessment outcomes, payer negotiations and generic competition.
Northern Europe
Northern Europe represents a high-value market supported by universal health care systems, strong digital health infrastructure, high medicine adherence and early adoption of e-prescription models. Sweden, Denmark, Norway, Finland and Ireland support strong access to branded prescriptions, generics and specialty therapies. Cancer, Alzheimer’s, Migraine and Infectious Disease remain important treatment categories. Hospital Pharmacies are central for oncology and orphan medicines, while retail and online pharmacy systems support chronic prescriptions. Growth will be supported by digital prescribing, public reimbursement and structured patient pathways, although price negotiation and national formularies will continue to shape uptake.
Southern Europe
Southern Europe offers steady growth supported by large patient populations, strong retail pharmacy networks and rising demand for oncology, neurology, infectious disease and chronic pain prescriptions. Italy, Spain, Portugal and Greece use national reimbursement systems to manage access to generics, branded products and specialty medicines. Cancer treatment remains a major hospital pharmacy category, while generics support outpatient affordability. Migraine, Chronic Pain and Infectious Disease prescriptions are strongly linked to Retail Pharmacies & Drug Stores. Growth will depend on public budget capacity, tendering, reimbursement decisions and hospital drug access.
Central and Eastern Europe
Central and Eastern Europe represents an expanding market with increasing access to innovative medicines, growing use of generics and gradual improvement in hospital specialty care. Poland, Czech Republic, Hungary, Romania, Bulgaria, Slovakia and Baltic countries support prescription growth across Cancer, Infectious Disease, Migraine, Chronic Pain and rare disease categories. Generic drugs remain important due to affordability and reimbursement constraints. Hospital Pharmacies are gaining relevance as oncology and orphan drug access improves, while Retail Pharmacies & Drug Stores remain central for outpatient prescriptions. Growth will depend on reimbursement expansion, EU-level access initiatives and national health spending.
Rest of Europe
Rest of Europe includes smaller and non-EU markets with varied prescription drug access, regulatory alignment and reimbursement structures. Switzerland and Norway remain high-value prescription markets, while Balkan and Eastern European countries offer gradual growth as health systems strengthen. Oncology, Infectious Disease, Migraine and chronic disease prescriptions drive demand, but access to orphan and Alzheimer’s therapies may vary due to pricing and reimbursement. Retail Pharmacies & Drug Stores remain the main outpatient channel, while Hospital Pharmacies manage high-cost products. Growth will depend on local policy, procurement capacity, affordability and distributor networks.
Report Attribute Details
| Report Attribute | Details |
| Historical Period | 2021–2024 |
| Base Year | 2025 |
| Forecast Period | 2025–2032 |
| Market Size in 2021 | USD 294,866.12 MN |
| Market Size in 2025 | USD 365,960.68 MN |
| Market Size in 2032 | USD 553,623.53 MN |
| CAGR | 5.13% |
| Segments Covered | Ailment, Product Type, Distribution Channel and Geography |
| Key Companies Covered | GlaxoSmithKline Plc, AstraZeneca Plc, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Teva Pharmaceutical Industries Ltd., Sanofi, Pfizer Inc., AbbVie Inc., Vertex Pharmaceuticals Incorporated and Cipla Ltd |
Europe Prescription Drugs Market Segmentations
By Ailment
- Alzheimer’s
- Parkinson’s
- Migraine
- Chronic Pain
- Cancer
- Infectious Disease
- Others
By Product Type
- Generic
- Orphan
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies & Drug Stores
- Online Pharmacies
Key Players
- GlaxoSmithKline Plc
- AstraZeneca Plc
- Boehringer Ingelheim International GmbH
- Merck & Co., Inc.
- Novartis AG
- F. Hoffmann-La Roche Ltd.
- Teva Pharmaceutical Industries Ltd.
- Sanofi
- Pfizer Inc.
- AbbVie Inc.
- Vertex Pharmaceuticals Incorporated
- Cipla Ltd
Recent Developments
- In April 2025, EMA reported that Leqembi received EU marketing authorization for defined adult patients with early Alzheimer’s disease, creating a new prescription treatment pathway in Europe.
- In September 2025, the European Commission granted EU marketing authorization for Kisunla to treat mild cognitive impairment, including mild dementia, in early-stage Alzheimer’s disease.
- In 2025, EMA recommended 104 medicines for marketing authorization and confirmed orphan designation for 16 medicines by year-end, supporting continued prescription drug innovation in Europe.
- In 2025, Novartis reported Europe sales of USD 16.7 billion, up 8%, driven mainly by Kesimpta, Entresto, Kisqali and Pluvicto, while Aimovig demand supported migraine prevention sales growth.
- In 2025, AstraZeneca reported that Europe oncology product sales increased 20% to USD 4,880 million, driven by Tagrisso, Imfinzi, Calquence and Lynparza.
Report Coverage
The research report offers an in-depth analysis based on ailment, product type, distribution channel and geography. It details leading market players, providing an overview of their business positioning, prescription drug portfolios, oncology exposure, neurology products, infectious disease therapies, generic strategies, orphan medicine portfolios, pharmacy channel reach and strategic relevance in the Europe Prescription Drugs Market. The report includes insights into the competitive environment, market trends, growth drivers, restraints and opportunities. It also examines cancer burden, Alzheimer’s treatment innovation, migraine drug access, chronic pain therapy, infectious disease demand, orphan medicine approvals, generic competition and online pharmacy growth as major factors shaping market development. The report assesses the impact of pricing pressure, reimbursement controls, patent expiry, generic erosion, access variation and safety monitoring requirements on market growth. It provides strategic recommendations for pharmaceutical companies, hospital systems, retail pharmacy networks, online pharmacies, payers, distributors, investors and new entrants seeking to navigate Europe’s prescription drugs ecosystem.
Future Outlook
- Demand for prescription drugs will continue to rise as Europe’s aging population, cancer burden and chronic disease treatment needs expand.
- Cancer will remain a leading ailment category due to strong demand for oncology prescriptions, targeted therapies and hospital-managed medicines.
- Alzheimer’s will gain momentum as authorized early-stage therapies create new specialist prescribing and monitoring pathways.
- Migraine will remain an important outpatient prescription category due to CGRP-targeted therapies and acute treatment options.
- Chronic Pain will support demand for analgesics, non-opioid innovation and chronic symptom management prescriptions.
- Infectious Disease will remain important due to antimicrobial resistance, HIV prevention, antivirals and hospital infection management.
- Generic drugs will remain central to payer strategies, affordability and retail pharmacy dispensing.
- Orphan drugs will gain value as EMA approvals and rare disease treatment pipelines expand.
- Hospital Pharmacies will remain the leading channel for oncology, orphan, Alzheimer’s and severe infectious disease medicines.
- Competition will increase as companies compete on clinical differentiation, reimbursement evidence, generic defense, orphan drug access, pharmacy partnerships and launch speed.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Europe Prescription Drugs Market and what is its projected size in 2032?
At what CAGR is the Europe Prescription Drugs Market projected to grow?
Which ailment segment is expected to lead the market?
Which product type holds strong demand?
Which distribution channel leads the market?
Who are the leading companies in the market?
Which region leads the Europe market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Prescription Drugs Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Prescription Drugs Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 365,960.68 MN → 2032: USD 553,623.53 MN)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Prescription Drugs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Prescription Drugs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Prescription Drugs Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Prescription Drugs Market Drivers
- 3.3 Europe Prescription Drugs Market Restraints & Challenges
- 3.4 Europe Prescription Drugs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Prescription Drugs Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Prescription Drugs Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Prescription Drugs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Prescription Drugs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Prescription Drugs Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Prescription Drugs market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Prescription Drugs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Prescription Drugs Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Prescription Drugs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Prescription Drugs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Prescription Drugs Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Prescription Drugs Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Prescription Drugs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Prescription Drugs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Prescription Drugs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Prescription Drugs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Prescription Drugs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Prescription Drugs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Prescription Drugs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
