
Market Overview:
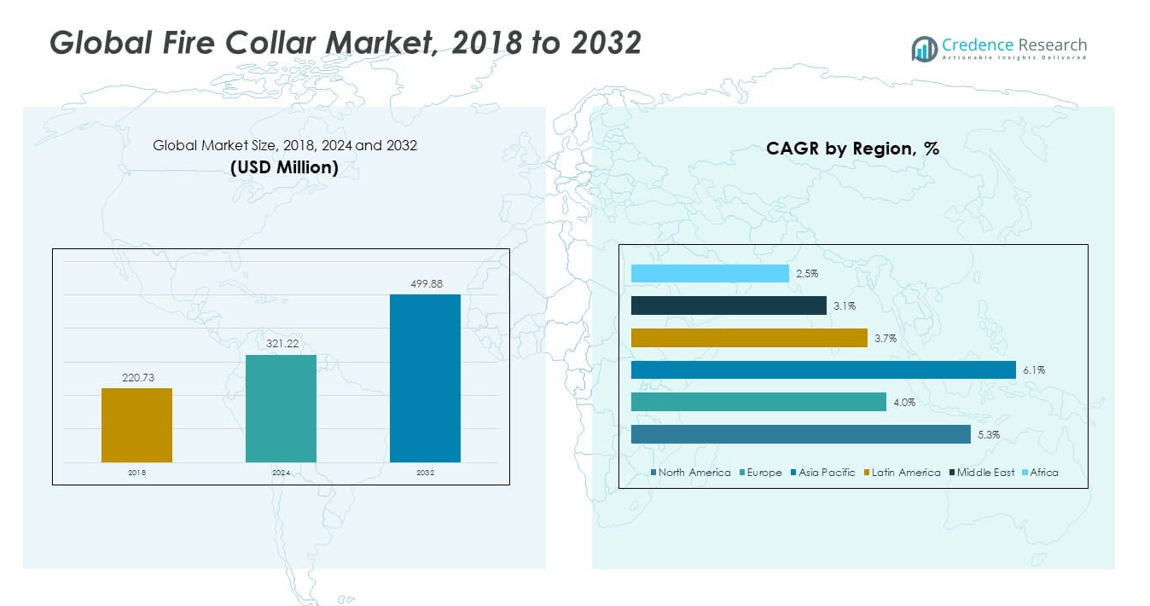
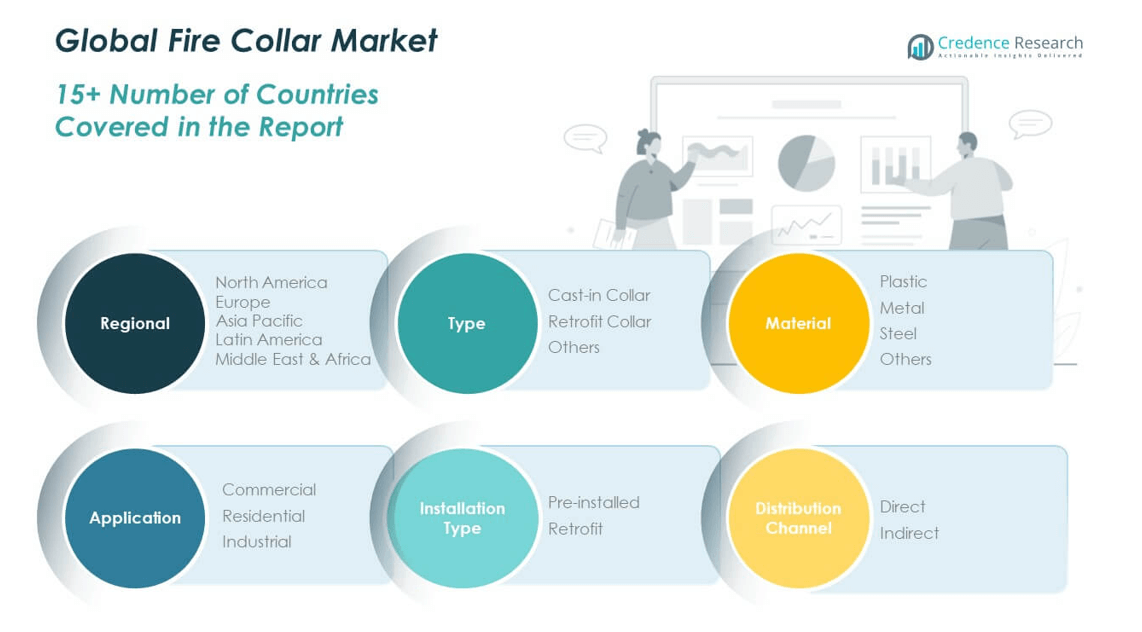
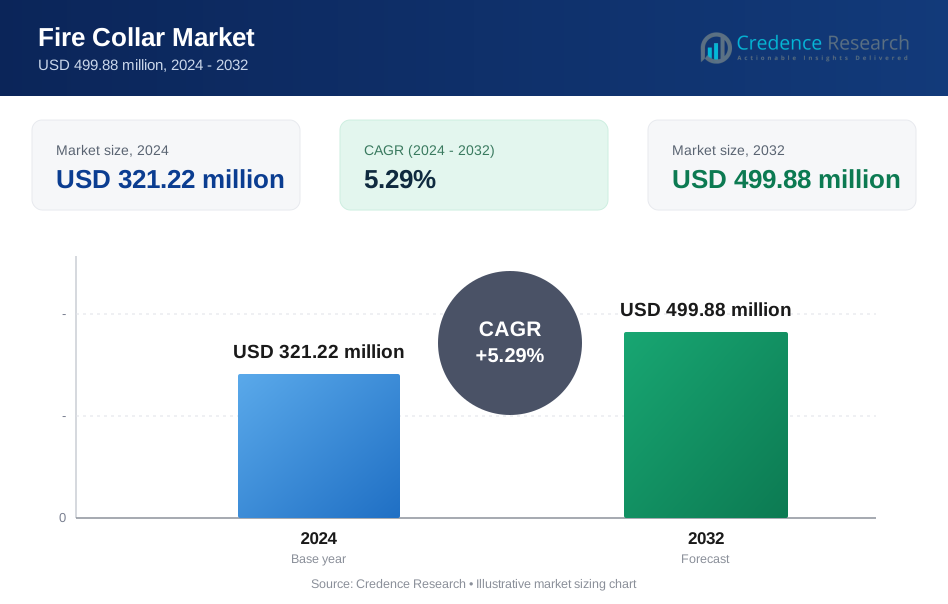
The Global Fire Collar Market size was valued at USD 220.73 million in 2018 to USD 321.22 million in 2024 and is anticipated to reach USD 499.88 million by 2032, at a CAGR of 5.29% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fire Collar Market Size 2024 | USD 321.22 million |
| Fire Collar Market, CAGR | 5.29% |
| Fire Collar Market Size 2032 | USD 499.88 million |
The Global Fire Collar Market is expanding due to rising fire safety regulations in residential, commercial, and industrial infrastructure. Growing construction projects, urbanization, and increasing awareness of passive fire protection systems are major drivers. The demand for fire collars is rising across developed and developing economies, supported by strict building codes and safety standards that require effective fire containment solutions in plumbing and electrical penetrations.
North America and Europe lead the market due to mature construction sectors and stringent fire safety norms. Asia-Pacific is emerging rapidly, driven by large-scale infrastructure development and industrial expansion in countries such as China, India, and Japan. The Middle East also shows strong potential, supported by urban growth and adoption of advanced fire protection technologies in modern buildings. Africa and Latin America are gradually adopting fire safety practices through regulatory reforms.
Market Insights:
- The Global Fire Collar Market was valued at USD 220.73 million in 2018, reached USD 321.22 million in 2024, and is projected to attain USD 499.88 million by 2032, growing at a CAGR of 5.29%.
- North America held the largest share at 34%, driven by strict building codes, widespread fire safety awareness, and the dominance of certified manufacturers. Europe followed with 21%, supported by stringent EN standards and retrofitting activities in older structures. Asia Pacific captured 16%, propelled by large-scale urban construction and infrastructure development.
- Asia Pacific remains the fastest-growing region due to strong industrial expansion, smart city investments, and rising fire safety regulations across emerging economies like China and India.
- By type, cast-in collars accounted for approximately 55% of the total market share in 2024, benefiting from widespread use in new commercial and residential projects.
- Retrofit collars represented nearly 35% of the market, favored in infrastructure renovation, while other collar types captured the remaining 10%, catering to specialized industrial applications.
Market Drivers:
Rising Demand for Fire Protection Systems Across Commercial and Residential Construction
The Global Fire Collar Market is driven by increasing construction of high-rise buildings, commercial complexes, and residential projects. Rapid urbanization and industrialization across developed and emerging nations are boosting the installation of advanced fire safety systems. Governments are enforcing strict building codes that mandate the use of certified fire collars to prevent fire spread. Infrastructure modernization programs in Europe and Asia are further supporting demand. The need for passive fire protection is increasing across plumbing and electrical conduits. Builders are focusing on compliance and safety assurance in large-scale projects. Manufacturers are responding by offering products that meet global fire resistance standards. This trend is creating steady demand across multiple end-user industries.
- For instance, Hilti’s CFS-CID Cast-in Firestop Collar features modular connections for close placement of multiple penetrations, achieves up to 4 hours of fire resistance (as per EN 13501-2:2007+A1:2009, EN 1366-3:2009), and is designed for quick, one-step installation in concrete slabs, eliminating additional coring and reducing labor costs.
Stringent Regulatory Framework and Emphasis on Building Safety Compliance
Tightened safety standards are a major growth driver in the Global Fire Collar Market. Authorities worldwide are revising fire safety codes to reduce risks in industrial and commercial buildings. These regulations require certified firestop materials, including collars, for penetration sealing in walls and floors. Insurance providers are increasingly linking premiums to compliance with such standards. It is encouraging property owners to invest in reliable fire protection solutions. Certification programs like UL and FM approvals enhance credibility and adoption rates. Manufacturers are focusing on testing and documentation to meet regional compliance needs. This regulatory push ensures sustainable long-term market growth.
- For instance, Promat fire collars have been tested for over 30 years to multiple international standards and are designed using intumescent technology that expands to form an insulating barrier during fire events, ensuring compliance with building code requirements in lightweight and concrete floor assemblies.
Growth in Industrial and Infrastructure Development Projects Globally
Industrial growth across energy, manufacturing, and logistics sectors is propelling the Global Fire Collar Market. Large factories, warehouses, and processing plants require robust fire containment systems. Expanding oil and gas, power generation, and transport infrastructure projects are contributing to market expansion. Countries are investing heavily in industrial corridors, smart cities, and special economic zones. It is creating massive demand for certified fire protection materials. Fire collars are increasingly used to seal cable and pipe penetrations in critical installations. Manufacturers are developing advanced designs suitable for industrial-grade applications. This trend ensures continuous adoption across developing and developed economies.
Increasing Focus on Retrofitting and Maintenance of Aging Infrastructure
Upgrading old buildings with modern fire safety features is strengthening the Global Fire Collar Market. Governments and private owners are prioritizing retrofitting to meet new safety codes. Existing structures in Europe, North America, and Asia are being upgraded with certified collars and fire barriers. Facility management companies are investing in inspection and replacement programs. It is driving demand for easy-to-install, cost-effective collar solutions. The rise of green renovation projects also supports integration of sustainable fire protection products. Technological advancements are allowing retrofitting with minimal structural disruption. This ongoing maintenance cycle provides consistent market revenue potential.
Market Trends:
Shift Toward Innovative and Lightweight Fire Collar Designs
The Global Fire Collar Market is witnessing a move toward lightweight, flexible, and easier-to-install designs. Manufacturers are adopting advanced materials such as intumescent polymers for improved performance. Compact and modular collars are gaining preference in commercial and industrial projects. The use of recyclable and non-toxic compounds is aligning with green construction goals. It is improving product sustainability and compliance with environmental regulations. Innovation in design is helping contractors reduce installation time and cost. Smart manufacturing processes are allowing better consistency and quality assurance. This shift reflects a strong focus on safety and ease of application.
- For instance, Walraven’s Pacifyre® MK II Fire Sleeve can be installed easily without special tools, provides fire resistance up to EI 240 for metal pipes and EI 120 for plastic pipes, and has been awarded a European Technical Assessment (ETA-20/0732), validating its performance and simplifying installation for both walls and floors.
Integration of Digital Tools and Smart Inspection Systems
Digital transformation is becoming a key trend in the Global Fire Collar Market. Companies are integrating IoT-enabled sensors for monitoring collar conditions in critical installations. Digital inspection tools ensure better tracking and maintenance of installed products. Software-based compliance management platforms are supporting real-time audits and certification tracking. It is improving operational efficiency and reducing manual errors in inspections. Data-driven insights are helping optimize fire safety strategies in large facilities. The trend supports proactive safety management in smart buildings. Manufacturers are also exploring partnerships with tech firms to expand digital integration.
- For instance, while fire collar manufacturers such as Hilti have developed digital libraries and technical support tools, the integration of inspection-friendly features like Hilti’s “red footprint” in the CFS-CID device simplifies post-installation inspection processes, enhancing compliance and quality assurance at the jobsite.
Rising Adoption of Sustainable and Eco-Certified Fire Protection Materials
Sustainability is a growing trend influencing the Global Fire Collar Market. The demand for halogen-free, low-VOC, and recyclable materials is increasing. Governments and developers are promoting green building certifications like LEED and BREEAM. It is encouraging the use of eco-friendly collars with proven fire resistance. Manufacturers are reformulating materials to minimize environmental impact without reducing performance. Consumers are becoming more conscious of product sourcing and safety credentials. The adoption of cleaner production technologies is improving brand reputation. The move toward sustainability is reshaping product development priorities across regions.
Expansion of Product Portfolios Through Strategic Collaborations and Mergers
Collaborations are shaping competition in the Global Fire Collar Market. Leading players are acquiring or partnering with regional manufacturers to expand their portfolios. These alliances allow quicker market entry and product localization. It is helping companies serve construction standards unique to each region. Mergers are also driving technological exchange and cost optimization. Companies are focusing on expanding distribution networks through global partnerships. Joint ventures with insulation and construction solution providers are becoming common. This trend strengthens brand visibility and broadens product reach across end-user sectors.
Market Challenges Analysis:
High Installation Costs and Limited Awareness in Developing Regions
The Global Fire Collar Market faces challenges from high installation and maintenance costs. Price-sensitive regions often delay or neglect fire protection integration in small projects. Lack of awareness about the benefits of passive fire safety further limits adoption. Contractors sometimes prefer cheaper, uncertified alternatives that compromise safety. It reduces overall product penetration in low-income markets. Training gaps among construction workers also lead to improper installation and inefficiency. It affects the overall effectiveness of fire safety systems. Bridging this knowledge gap and offering affordable solutions are essential for market expansion.
Complex Certification Standards and Supply Chain Disruptions
Compliance complexity is a major challenge in the Global Fire Collar Market. Manufacturers must meet multiple regional testing and certification standards, increasing cost and time-to-market. Variations between EU, UL, and local codes create product approval barriers. Supply chain disruptions for raw materials and logistics have further delayed delivery timelines. It affects project schedules and customer confidence. Dependence on specialized components increases production vulnerability during global crises. Quality assurance requirements demand continuous investment in testing infrastructure. These factors together restrain the overall pace of market growth.
Market Opportunities:
Expansion of Fire Safety Regulations and Modern Infrastructure Projects
New infrastructure development and stricter safety codes are creating opportunities in the Global Fire Collar Market. Government-led urbanization initiatives in Asia-Pacific and the Middle East drive large-scale adoption. Public infrastructure, transport hubs, and healthcare facilities increasingly demand certified fire protection. It encourages long-term contracts and bulk installations. Companies with localized production units can leverage cost advantages. Emerging economies are expected to contribute significantly through regulatory alignment. These opportunities enhance overall industry resilience and profitability.
Product Innovation and Green Material Adoption for Competitive Advantage
Innovation in fire collar design and materials offers major growth prospects for the Global Fire Collar Market. Development of sustainable, halogen-free, and smart collars is attracting new customers. It allows manufacturers to meet both environmental and safety expectations. Partnerships with construction technology firms enhance R&D and customization. The rise in modular and prefabricated construction creates additional application areas. Expanding into niche segments like marine and data center safety provides new revenue streams. Continuous product evolution ensures long-term industry competitiveness.
Market Segmentation Analysis:
By Type
The Global Fire Collar Market is segmented into cast-in collar, retrofit collar, and others. Cast-in collars hold the dominant share due to their suitability in new construction projects and compliance with international fire safety codes. Retrofit collars are gaining traction in renovation and refurbishment applications, especially across developed regions focused on upgrading older structures. Other collar types, including customized and modular variants, cater to specialized industrial needs and flexible installations. Continuous design improvements are enhancing ease of fitting and long-term fire resistance performance.
- For instance, Promat’s family of retrofit fire collars (such as the PROMASEAL FC Retrofit Collar) are split open for easier retrofitting as needed, and are tested for up to 240 minutes fire resistance in accordance with AS 1530: Part 4 and AS 4072: Part 1 with various types and sizes of plastic pipe.
By Material
Plastic, metal, steel, and other materials define the material segmentation. Steel fire collars lead the market because of their high durability, heat resistance, and superior performance under extreme fire conditions. Metal variants follow closely, favored for their cost-efficiency and ease of manufacturing. Plastic collars are popular in residential and low-risk applications for their lightweight and affordable properties. Innovation in composite materials is expanding product diversity and compliance scope.
- For instance, Walraven’s Pacifyre® MK II Fire Sleeve employs a stainless-steel casing combined with a reactive intumescent inlay, and is designed to maintain fire compartment integrity for at least 25 years as indicated in European conformity assessments.
By Application
Commercial, residential, and industrial segments drive the demand landscape. The commercial segment dominates, driven by strict building codes in offices, malls, and institutional facilities. The residential sector benefits from growing awareness of fire protection in multi-story buildings. Industrial applications continue to expand in energy, manufacturing, and logistics due to critical safety requirements.
By Installation Type and Distribution Channel
Pre-installed and retrofit categories define installation scope, with pre-installed collars leading in new infrastructure projects. Retrofit types are widely used in renovation and compliance upgrades. Direct distribution channels dominate due to partnerships with contractors and developers, while indirect sales grow through distributors and e-commerce networks.
Segmentation:
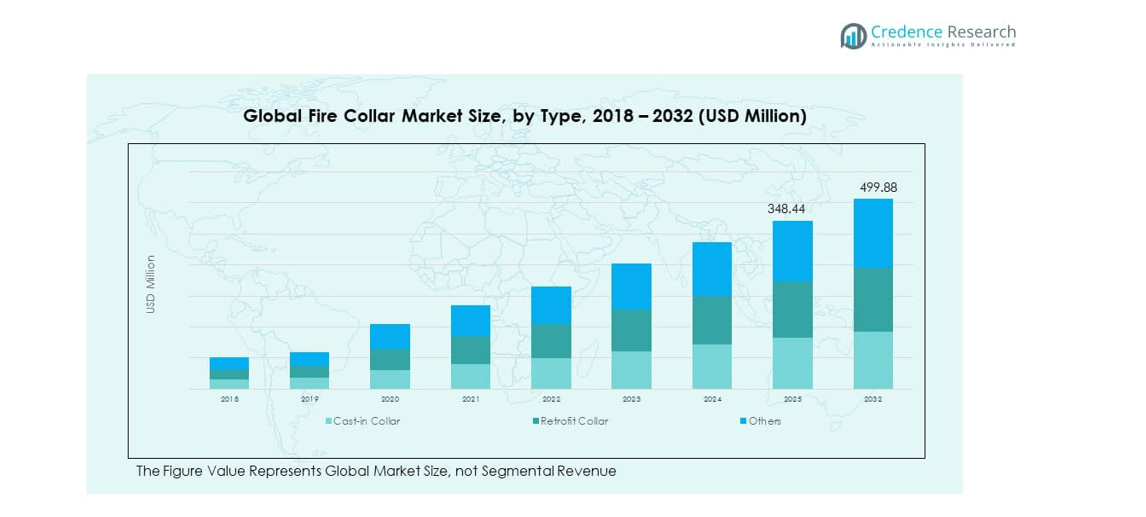
- By Type
- Cast-in Collar
- Retrofit Collar
- Others
- By Material
- Plastic
- Metal
- Steel
- Others
- By Application
- Commercial
- Residential
- Industrial
- By Installation Type
- Pre-installed
- Retrofit
- By Distribution Channel
- Direct
- Indirect
- By Country (Regional Breakdown)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
The North America Global Fire Collar Market size was valued at USD 97.39 million in 2018 to USD 140.28 million in 2024 and is anticipated to reach USD 218.90 million by 2032, at a CAGR of 5.3% during the forecast period. North America accounted for 34% of the global market share in 2024. The region leads due to strict enforcement of building safety codes and widespread use of advanced fire protection systems. High-rise commercial buildings, industrial plants, and residential complexes increasingly adopt fire collars to meet NFPA and UL standards. The U.S. drives the regional market with a mature construction industry and ongoing modernization of infrastructure. Canada supports growth with its focus on sustainable building designs and energy-efficient construction. It benefits from strong presence of leading manufacturers offering certified and eco-friendly solutions. Continuous R&D and technological upgrades maintain regional dominance in global trade.
Europe
The Europe Global Fire Collar Market size was valued at USD 60.75 million in 2018 to USD 85.13 million in 2024 and is anticipated to reach USD 124.47 million by 2032, at a CAGR of 4.5% during the forecast period. Europe captured 21% of the global market share in 2024. Strong regulatory compliance under EN fire standards drives product adoption across residential and industrial sectors. Countries such as Germany, the UK, and France lead installations through advanced safety frameworks and building modernization programs. Retrofitting projects in aging infrastructure are boosting demand for certified firestop materials. Manufacturers focus on product innovation using recyclable and low-emission materials. It benefits from government-backed safety campaigns and fire prevention awareness initiatives. The region remains an early adopter of sustainable construction technologies. Growth is steady, supported by continuous renovation activity and infrastructure resilience policies.
Asia Pacific
The Asia Pacific Global Fire Collar Market size was valued at USD 42.48 million in 2018 to USD 67.00 million in 2024 and is anticipated to reach USD 118.09 million by 2032, at a CAGR of 6.9% during the forecast period. Asia Pacific held a 16% market share in 2024. Rapid urbanization, rising industrial projects, and government-led infrastructure investments are fueling market expansion. China, India, Japan, and South Korea contribute strongly through large-scale construction and smart city programs. Growing awareness of passive fire protection in developing economies supports product adoption. It benefits from increasing private investment in commercial and industrial complexes. Domestic manufacturers are enhancing production capacity to meet safety standards. Local regulatory reforms are aligning with international fire norms, strengthening regional competitiveness. This region is expected to remain the fastest-growing market globally.
Latin America
The Latin America Global Fire Collar Market size was valued at USD 10.43 million in 2018 to USD 14.98 million in 2024 and is anticipated to reach USD 20.64 million by 2032, at a CAGR of 3.7% during the forecast period. Latin America represented 4% of the global market share in 2024. The region experiences growing demand from commercial and institutional construction, particularly in Brazil and Mexico. Development of new business complexes and public infrastructure is stimulating product usage. It faces challenges from limited awareness and inconsistent enforcement of fire safety codes. Local governments are introducing stricter regulations to improve compliance in new projects. Affordable retrofitting solutions are attracting adoption in residential buildings. Manufacturers are focusing on cost-effective fire collars tailored to regional needs. The construction sector recovery is expected to drive gradual market improvement.
Middle East
The Middle East Global Fire Collar Market size was valued at USD 6.23 million in 2018 to USD 8.30 million in 2024 and is anticipated to reach USD 10.91 million by 2032, at a CAGR of 3.1% during the forecast period. The Middle East accounted for 3% of the global market share in 2024. Demand is supported by large-scale infrastructure, hospitality, and oil & gas projects. Countries like the UAE, Saudi Arabia, and Qatar are integrating advanced fire safety systems in smart cities and mega projects. Rapid urban expansion is driving installations across commercial towers and industrial zones. It benefits from strict government mandates in high-occupancy buildings. Adoption is rising due to focus on international safety certification and improved fire resilience. Imports dominate supply chains, though local production is increasing gradually. Long-term construction growth sustains steady demand across the region.
Africa
The Africa Global Fire Collar Market size was valued at USD 3.45 million in 2018 to USD 5.53 million in 2024 and is anticipated to reach USD 6.87 million by 2032, at a CAGR of 2.3% during the forecast period. Africa held a 2% share of the global market in 2024. The market is developing gradually, driven by expanding commercial construction in South Africa, Egypt, and Nigeria. Urban growth and government housing initiatives are supporting modest adoption. It faces limitations in infrastructure funding and fire safety enforcement. International organizations are helping promote compliance and safety awareness. The entry of foreign construction firms brings advanced building standards to major cities. Local distributors are forming alliances with global brands to widen access. Although small in scale, Africa presents long-term potential through infrastructure modernization.
Key Player Analysis:
- Hilti Corporation
- 3M Company
- Specified Technologies Inc.
- STI Firestop
- Tenmat Ltd.
- Promat International
- Trafalgar Fire
Competitive Analysis:
The Global Fire Collar Market is characterized by strong competition among established global and regional players. Leading companies focus on product innovation, regulatory compliance, and expanding distribution networks. Key participants such as Hilti Corporation, 3M Company, Promat International, and Trafalgar Fire emphasize developing lightweight, easy-to-install, and eco-friendly fire protection solutions. It benefits from rising construction safety standards and retrofit demand across developed markets. Strategic mergers and collaborations strengthen supply capabilities and enhance product reach. Continuous investment in R&D supports material advancement and fire resistance testing. The market shows balanced competition, with regional manufacturers focusing on cost efficiency and tailored product portfolios.
Recent Developments:
- In September 2025, Hilti Corporation earned six Pro Tool Innovation Awards for its wide range of construction solutions, including advancements in fire protection and safety accessories. Though not explicitly tied to a new fire collar launch, this recognition highlights Hilti’s leadership in developing innovative safety products for commercial buildings, and its commitment to enhancing passive fire protection systems is a driving force in the sector.
- In 2025, 3M continues to play a significant role in the fire collar market by advancing its fire barrier technologies, including products that function as intumescent wraps and plastic pipe devices—key solutions for passive fire prevention. The company regularly introduces enhancements within its fire barrier portfolio to address evolving building codes and increased demand for high-performance fire safety components in global construction projects.
- On April 7, 2025, Specified Technologies Inc.—also known as STI Firestop—launched the SpecSeal® 8 Inch Cast-In Device, expanding its offerings for firestop pipe penetrations in new constructions. This product aims to simplify installation while delivering robust fire protection, serving the growing need for reliable and efficient passive fire safety measures across diverse building types.
- In June 2025, Promat International became the first UK manufacturer to formally accept design responsibility for passive fire protection systems installed according to its standard details and testing protocols. This move aligns the company’s fire collars and passive protection solutions with the latest Building Safety Act requirements—enhancing accountability and raising safety standards within the industry.
Report Coverage:
The research report offers an in-depth analysis based on type, material, application, installation type, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of certified fire protection systems across high-rise and industrial buildings.
- Rising government enforcement of building codes promoting passive fire safety solutions.
- Growing demand for eco-friendly, recyclable, and halogen-free fire collar materials.
- Expanding infrastructure and smart city projects in emerging economies.
- Greater focus on digital inspection and IoT-enabled fire safety monitoring systems.
- Regional players enhancing capacity to meet international safety certifications.
- Rising retrofitting demand for older structures in developed markets.
- Advancements in intumescent materials improving fire resistance and durability.
- Expanding partnerships between global brands and local distributors.
- Increasing R&D investment focused on cost-effective and lightweight designs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Fire Collar Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fire Collar Market projected to grow between 2024 and 2032?
Which Fire Collar Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Fire Collar Market?
Who are the leading companies in the Fire Collar Market?
Which region commanded the largest share of the Fire Collar Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fire Collar Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fire Collar Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 321.22 million → 2032: USD 499.88 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fire Collar Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fire Collar Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fire Collar Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fire Collar Market Drivers
- 3.3 Fire Collar Market Restraints & Challenges
- 3.4 Fire Collar Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fire Collar Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fire Collar Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fire Collar category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fire Collar Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Fire Collar Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Fire Collar market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fire Collar Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fire Collar Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Fire Collar Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fire Collar (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Fire Collar Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fire Collar Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Fire Collar Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fire Collar Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fire Collar Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fire Collar Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fire Collar Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fire Collar Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fire Collar Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
