
3D Printed Nanocellulose Market Overview:
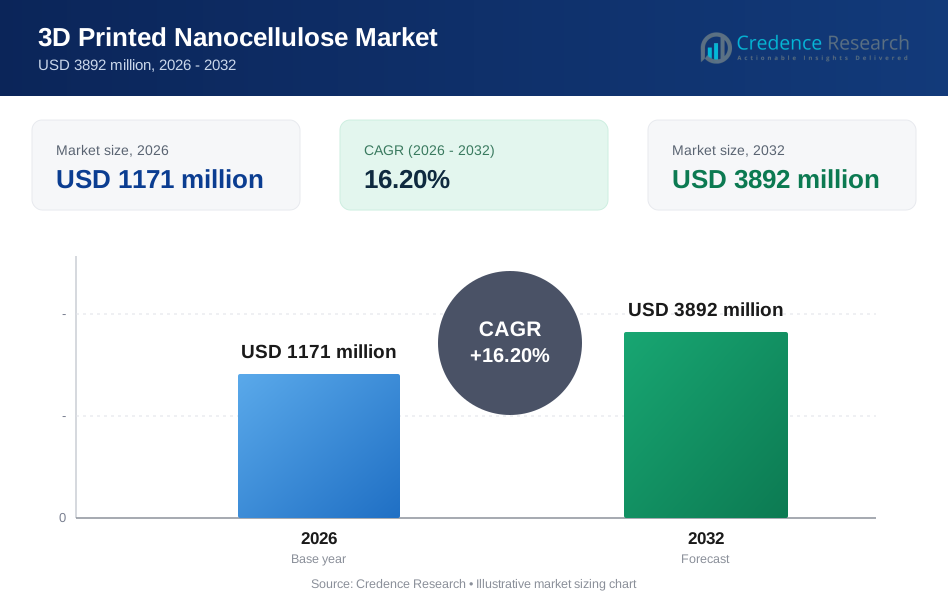
3D Printed Nanocellulose Market was valued at USD 1171 million in 2026 and is anticipated to reach USD 3892 million by 2032, growing at a CAGR of 16.20% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| 3D Printed Nanocellulose Market Size 2026 | USD 1171 million |
| 3D Printed Nanocellulose Market, CAGR | 16.20% |
| 3D Printed Nanocellulose Market Size 2032 | USD 3892 million |
The 3D Printed Nanocellulose Market is shaped by leading companies such as Nanografi, Sappi, CelluForce, UPM Biomedicals, Oji Holdings Corporation, CELLINK (BICO Group AB), Novum, and Axcelon Biopolymers Corporation. These players strengthen the sector through advanced bioink development, high-purity nanocellulose production, and expanding applications in biomedical scaffolds, flexible electronics, and sustainable packaging. Strategic partnerships with research institutes help accelerate innovation and improve printability and material performance. North America emerges as the leading region, holding about 38% market share in 2026 due to strong investment in regenerative medicine, material science research, and early adoption of biofabrication technologies.
3D Printed Nanocellulose Market Insights
- The 3D Printed Nanocellulose Market reached USD 1171 million in 2026 and is projected to hit USD 3892 million by 2032, growing at a CAGR of 16.20%.
- Strong drivers include rising demand for biocompatible materials and wider use of nanocellulose scaffolds, with the biomedical segment holding about 48% share in 2026.
- Key trends center on growth in flexible electronics, sustainable packaging films, and organ-on-chip research as nanocellulose inks and composites gain traction.
- Leading players such as Nanografi, Sappi, CelluForce, UPM Biomedicals, and CELLINK (BICO Group AB) compete through material innovation and research partnerships, while high production costs remain a restraint.
- North America leads with nearly 38% regional share in 2026, followed by Europe at 31% and Asia Pacific at 24%, supported by expanding R&D ecosystems and strong adoption across biomedical and electronics applications.
3D Printed Nanocellulose Market Segmentation Analysis:
By Product
Nanocellulose filament leads the product segment with about 46% share in 2026. Strong demand comes from its strength, print stability, and wide use in biomedical and structural prototypes. Research labs and additive manufacturing firms prefer filament due to easy processing and high mechanical performance. Nanocellulose ink follows as material jetting gains traction in flexible sensors and soft tissue models. Pre-printed scaffolds grow steadily with rising interest in ready-to-use bio-structures for regenerative studies. Growth across the product segment links to rising adoption of sustainable biomaterials and expanding R&D in medical engineering.
- For instance, Stora Enso is a known producer of nanocellulose and is involved in developing various nanocellulose applications, including packaging and potential biomedical uses.
By Type
Cellulose nanofibers (CNF) dominate the type segment with nearly 52% share in 2026. CNF holds strong due to high tensile strength, biocompatibility, and stable rheology for extrusion-based 3D printing. Researchers use CNF for tissue scaffolds, eco-composites, and conductive films. Cellulose nanocrystals (CNC) see rising demand in electronics and packaging due to higher crystallinity and barrier strength. Bacterial nanocellulose (BNC) grows in biomedical fields because of purity and strong moisture retention. Growth across this segment is driven by wider material customization and improved processing methods.
- For instance, CelluForce Inc. manufactures cellulose nanocrystals with an average crystal length of 100–300 nanometers and elastic modulus close to 150 GPa, supporting high-strength CNF- and CNC-based printable formulations.
By Application
Biomedical applications dominate the market with about 48% share in 2026. Hospitals and research groups adopt nanocellulose for tissue regeneration, wound dressings, and drug delivery due to strong biocompatibility and mechanical support. Environmental uses grow as nanocellulose supports adsorption media for water treatment and pollutant capture. Food and packaging applications expand with interest in biodegradable films and oxygen-barrier coatings. Electronics show rising use in flexible substrates and printed circuits. Growth across the application segment is driven by sustainability goals and rapid innovation in bio-derived engineered materials.
Key Growth Drivers
Rising Demand for Sustainable and Biocompatible Materials
The market grows strongly as industries shift toward sustainable, biodegradable, and biocompatible materials. Nanocellulose supports this push with its renewable origin, low environmental impact, and strong mechanical behavior. Research groups adopt 3D-printed nanocellulose for biomedical scaffolds, wound dressings, and implants due to excellent tissue integration. Packaging and electronics manufacturers also explore nanocellulose as a substitute for petroleum-based materials. This wide appeal accelerates product development and commercial interest. Government policies that support bio-based innovation add further momentum, creating a solid foundation for long-term growth across healthcare, packaging, and environmental engineering.
- For instance, UPM Biomedicals produces GrowDex nanocellulose hydrogel derived from wood pulp with fiber diameters in the range of 20–100 nanometers, supporting high cell viability in 3D cultures. The material is manufactured from renewable Nordic wood using a closed-loop process that consumes no fossil-based raw materials. GrowDex has been validated for long-term cell culture exceeding 21 days, demonstrating structural stability and biocompatibility for research and product development.
Expanding Applications in Biomedical Engineering and Regenerative Medicine
Advances in tissue engineering stimulate rapid market expansion, as nanocellulose proves highly suitable for cell growth, nutrient flow, and structural support. Researchers use 3D-printed nanocellulose scaffolds to repair cartilage, skin, and soft tissues, driven by rising demand for personalized medical solutions. Hospitals and biotechnology firms invest in nanocellulose-based hydrogels and scaffolds to meet growing needs for safer, customizable implants. Strong clinical interest encourages deeper collaboration between material scientists and medical practitioners. These advancements position nanocellulose as a key material for next-generation regenerative treatments, strengthening the market outlook.
- For instance, Borregaard develops Exilva cellulose nanofibers with lengths above 1 micrometer and high water-binding capacity exceeding 10 grams of water per gram of fiber, making them suitable for printable biomedical hydrogels.
Growing Use in Advanced Electronics and Flexible Devices
Electronics manufacturers adopt nanocellulose for lightweight, flexible, and biodegradable components. Its strong barrier properties and tunable conductivity support use in flexible circuits, printed sensors, energy storage films, and wearable devices. Rising development of nanocellulose-based substrates aligns with global demand for sustainable electronics. Partnerships between research institutes and electronics companies drive new printable inks and composite formulations. As industries seek alternatives to synthetic polymers, nanocellulose’s mechanical stability and low thermal expansion make it attractive for high-precision printing. This expanding electronics ecosystem becomes a major growth driver for the market.
Key Trends & Opportunities
Advancement of Customized Biofabrication and Organ-on-Chip Models
A major trend involves the development of nanocellulose-based structures for organ-on-chip systems and customized biofabrication. These models support disease research and drug testing with more accuracy than conventional in vitro setups. Nanocellulose’s ability to mimic extracellular matrix behavior creates strong opportunities in pharmaceutical development. Biofabrication labs explore multi-material 3D printing, combining nanocellulose with living cells and bioinks. This trend opens pathways for commercialized ready-to-use biomedical constructs and accelerates the shift toward personalized medicine platforms, creating sustained growth opportunities for advanced material suppliers.
- For instance, CELLINK (BICO Group) develops nanocellulose-based bioinks with fibril diameters around 20 nanometers and printable strand widths as low as 200 micrometers, enabling high-resolution organ-on-chip architectures. These bioinks maintain structural integrity for continuous perfusion experiments lasting 28 days, supporting long-term drug response studies.
Rising Use in Sustainable Packaging and Circular Economy Models
The push for circular economy practices drives interest in nanocellulose for eco-friendly packaging films, coatings, and barrier layers. Food brands and consumer-goods companies explore nanocellulose as an alternative to plastics, targeting reduced waste and improved biodegradability. Advances in printable nanocellulose inks allow packaging producers to adopt lightweight, compostable, yet durable designs. Regulatory pressure on single-use plastics increases demand for materials that meet safety and environmental standards. These developments position nanocellulose as a key material in sustainable packaging innovation, offering long-term opportunities for market players.
- For instance, Stora Enso has engineered nanocellulose-coated packaging boards achieving oxygen transmission rates below 1 cubic centimeter per square meter per day, suitable for food-packaging barrier layers. Its pilot coating lines operate at web speeds above 200 meters per minute, demonstrating scalability for commercial packaging production. The nanocellulose coatings add barrier performance at coating weights under 5 grams per square meter, supporting lightweight, recyclable, and compostable packaging formats aligned with circular economy goals.
Innovation in Nanocellulose Composites for High-Strength Industrial Uses
A growing opportunity emerges from industrial interest in nanocellulose-reinforced composites. Manufacturers use these composites to enhance strength, reduce weight, and improve durability in automotive, aerospace, and construction components. New 3D printing formulations optimize dispersion and layer bonding, enabling wider adoption. The shift toward lightweight engineering materials strengthens nanocellulose’s role in performance-driven applications. As firms seek replacements for carbon-intensive materials, nanocellulose composites provide both environmental benefits and structural performance, creating a strong pathway for expanded industrial uptake.
Key Challenges
High Production Costs and Limited Large-Scale Commercialization
Despite strong interest, high production costs remain a major barrier. Nanocellulose extraction and refining require advanced equipment, energy input, and specialized processes. Many suppliers operate at small or pilot scales, which raises cost per unit and limits availability. This challenge slows adoption in mass-market applications such as packaging and consumer goods. Without cost-effective scaling, companies find it difficult to compete with cheaper synthetic materials. Broader commercialization depends on improved manufacturing efficiency, optimized supply chains, and new technologies that reduce processing expenses while maintaining quality.
Technical Barriers in Printability, Material Stability, and Standardization
3D printing with nanocellulose faces challenges related to print consistency, moisture sensitivity, and material stability. The rheology of nanocellulose varies between CNF, CNC, and BNC, creating difficulties in maintaining predictable printing outcomes. Lack of standard formulations and print protocols limits widespread industrial use. Engineers must address issues such as drying shrinkage, layer adhesion, and long-term mechanical reliability. These challenges slow advancement in high-precision fields like electronics and biomedical engineering. Market expansion depends on improved material standardization, compatible printing systems, and stronger quality control procedures.
Regional Analysis
North America
North America holds the largest share of about 38% in the 3D Printed Nanocellulose Market in 2026. Strong adoption comes from advanced biomedical research, early use of biofabrication tools, and well-funded university labs. The region invests in tissue engineering, wound care materials, and sustainable packaging. Technology firms also explore nanocellulose substrates for printed electronics. Supportive research grants and collaborations between medical institutes and material developers help accelerate commercialization. Growing focus on biodegradable materials and precision healthcare strengthens demand across the United States and Canada, positioning the region as a leading hub for nanocellulose innovation.
Europe
Europe accounts for nearly 31% market share in 2026, supported by strong regulatory focus on sustainability and advanced material development. Research centers in Germany, Sweden, Finland, and the Netherlands drive innovation in nanocellulose composites, bioinks, and packaging films. The region leads in environmental engineering projects that use nanocellulose for pollution control and water treatment. Medical institutions increasingly adopt bio-scaffolds and regenerative structures. Funding programs under the EU Green Deal and Horizon Europe accelerate research and pilot commercialization. Rising interest in circular economy practices, especially in food packaging and electronics, boosts long-term growth across Europe.
Asia Pacific
Asia Pacific holds around 24% market share in 2026 and grows quickly due to expanding biomedical manufacturing, strong electronics production, and rising investment in sustainable materials. Japan, China, and South Korea lead research in flexible electronics, nanocellulose printing inks, and bio-scaffolds. Universities and state-funded labs drive large-scale projects in biodegradable packaging and environmental remediation. Growing healthcare spending and rapid industrial innovation help increase adoption. The region also benefits from strong pulp and paper industries, which support raw material availability. Rising focus on green technologies and scalable manufacturing strengthens Asia Pacific’s future market position.
Latin America
Latin America captures close to 4% market share in 2026, with growth driven by early adoption in environmental engineering, water treatment, and biodegradable packaging. Research institutions in Brazil, Chile, and Mexico explore nanocellulose composites for sustainability-focused applications. Rising interest in affordable biomedical materials creates new opportunities for bio-inks and scaffold development. Limited industrial-scale production remains a challenge, yet government-backed innovation programs support small pilot projects. Increasing collaboration with global research groups helps expand technical knowledge. As awareness of eco-friendly materials grows, the region slowly develops its role in the 3D printed nanocellulose landscape.
Middle East & Africa
The Middle East & Africa region holds about 3% market share in 2026, supported by early-stage exploration of nanocellulose in construction additives, water purification, and sustainable packaging. Universities in South Africa and the UAE lead research, while partnerships with international laboratories strengthen material testing. Adoption in biomedical fields remains limited but shows gradual progress as healthcare modernization expands. High investment in environmental remediation and desalination technologies increases interest in nanocellulose filters. Although industrial capacity remains low, rising sustainability mandates and research funding create long-term potential for the regional market.
3D Printed Nanocellulose Market Segmentations:
By Product
- Nanocellulose Filament
- Nanocellulose Ink
- Pre-printed Nanocellulose Scaffolds
By Type
- Cellulose Nanofibers (CNF)
- Cellulose Nanocrystals (CNC)
- Bacterial Nanocellulose (BNC)
By Application
- Biomedical
- Environmental
- Food and Packaging
- Electronics
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the 3D Printed Nanocellulose Market features key players such as Nanografi, Sappi, CelluForce, UPM Biomedicals, Oji Holdings Corporation, CELLINK (BICO Group AB), Novum, and Axcelon Biopolymers Corporation. These companies focus on advancing nanocellulose production, developing high-performance bioinks, and expanding material applications across biomedical engineering, electronics, and sustainable packaging. Many players invest in R&D partnerships with universities and medical institutes to improve scaffold design, printability, and biocompatibility. Firms also explore scalable extraction methods to reduce material costs and support broader commercialization. Strategic collaborations, product launches, and pilot projects help strengthen market presence. As industries shift toward renewable and biodegradable materials, competition increases around differentiated formulations, customized biofabrication tools, and regulatory compliance.
Key Player Analysis
- Nanografi
- Sappi
- CelluForce
- UPM Biomedicals
- Oji Holdings Corporation
- CELLINK (BICO Group AB)
- Novum
- Axcelon Biopolymers Corporation
Recent Developments
- In 2025, Oji Holdings Corporation Oji Holdings continues R&D on cellulose nanofibers (CNF) as a high-performance sustainable material. The company reports ongoing CNF work for diverse applications.
- In November 2025, Oji Holdings R&D milestone Oji announced wood-derived material (sulfated hemicellulose) approval as a veterinary pharmaceutical API in Australia. This shows broader biobased material use, though not 3D nanocellulose specific.
- In October 2026, UPM Biomedicals UPM Biomedicals launched FibGel™, a birch-wood derived injectable nanocellulose hydrogel for medical devices. This product offers a sustainable, biocompatible option for implants.
Report Coverage
The research report offers an in-depth analysis based on Product, Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as biomedical firms adopt nanocellulose for advanced tissue scaffolds.
- Bioinks will improve with better printability, stability, and cell compatibility.
- Organ-on-chip and drug-testing platforms will drive strong research demand.
- Electronics makers will use nanocellulose for flexible circuits and sensor substrates.
- Sustainable packaging companies will adopt nanocellulose films to replace plastics.
- Production scaling will improve as manufacturers invest in efficient extraction processes.
- Composite development will grow for lightweight automotive and aerospace components.
- Regulatory clarity will support medical-grade nanocellulose commercialization.
- Academic–industry partnerships will accelerate material innovation and new applications.
- Regional expansion will occur as Asia Pacific and Europe increase R&D and pilot manufacturing.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for 3D Printed Nanocellulose Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is 3D Printed Nanocellulose Market projected to grow between 2026 and 2032?
Which 3D Printed Nanocellulose Market segment held the largest share in 2026?
What are the primary factors fueling the growth of 3D Printed Nanocellulose Market?
Who are the leading companies in 3D Printed Nanocellulose Market?
Which region commanded the largest share of 3D Printed Nanocellulose Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 3D Printed Nanocellulose Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2026; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global 3D Printed Nanocellulose Market Snapshot
- 2.1.1 Market Size – Historical (2026) & Forecast (2026-2032) (2026: USD 1171 million → 2032: USD 3892 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 3D Printed Nanocellulose Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2026 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2026
- 2.3.2 Top 10 Players by Volume Share – 2026
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. 3D Printed Nanocellulose Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 3D Printed Nanocellulose Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 3D Printed Nanocellulose Market Drivers
- 3.3 3D Printed Nanocellulose Market Restraints & Challenges
- 3.4 3D Printed Nanocellulose Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 3D Printed Nanocellulose Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 3D Printed Nanocellulose Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, 3D Printed Nanocellulose category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 3D Printed Nanocellulose Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. 3D Printed Nanocellulose Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2026)
- 5.1.2 Global Export Volume by Country (2026)
- 5.1.3 Global Import Value by Country (2026)
- 5.1.4 Global Import Volume by Country (2026)
- 5.1.5 Net Trade Balance by Country (2026)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2026)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the 3D Printed Nanocellulose market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 3D Printed Nanocellulose Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2026
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 3D Printed Nanocellulose Market Share Analysis – 2026
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2026)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 3D Printed Nanocellulose Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in 3D Printed Nanocellulose (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New 3D Printed Nanocellulose Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global 3D Printed Nanocellulose Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2026 & 2032)
- 7.1.2 Channel Mix Evolution (2026-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America 3D Printed Nanocellulose Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe 3D Printed Nanocellulose Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific 3D Printed Nanocellulose Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America 3D Printed Nanocellulose Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East 3D Printed Nanocellulose Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa 3D Printed Nanocellulose Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. 3D Printed Nanocellulose Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
