
Geocomposites Market Overview:
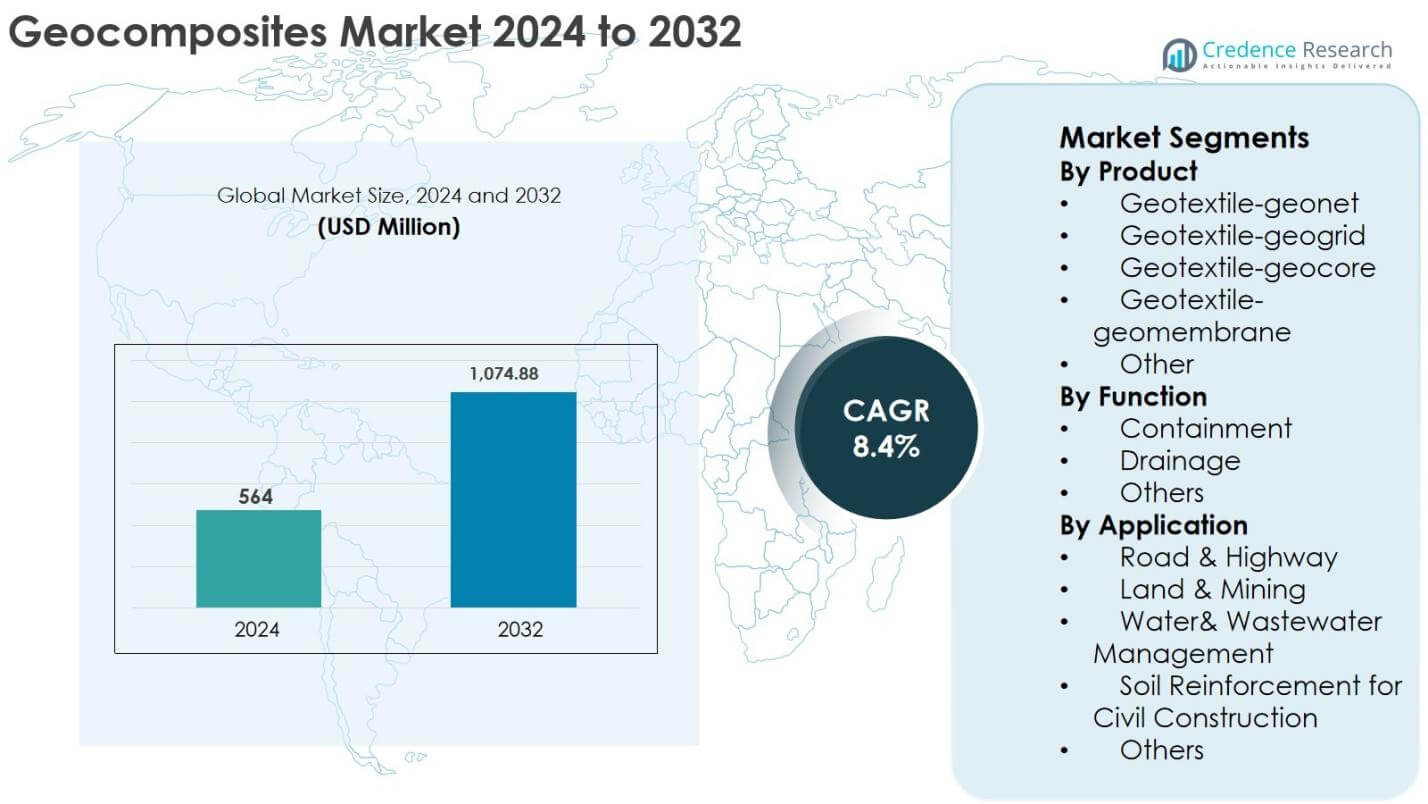
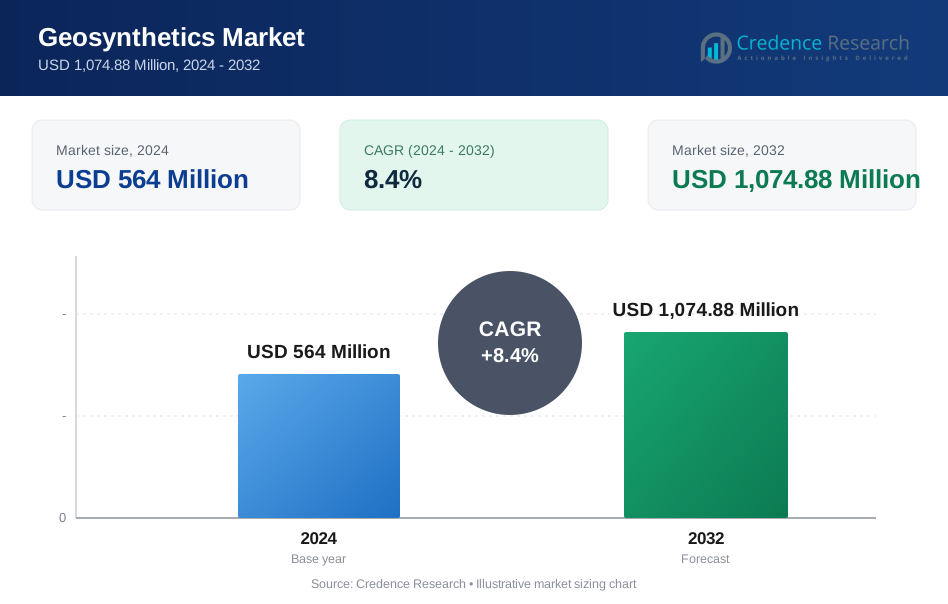
Geocomposites market size was valued USD 564 Million in 2024 and is anticipated to reach USD 1,074.88 Million by 2032, at a CAGR of 8.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Geocomposites Market Size 2024 | USD 564 million |
| Geocomposites Market, CAGR | 8.4% |
| Geocomposites Market Size 2032 | USD 1,074.88 million |
Geocomposites Market Insights
- Market growth is driven by rising demand for soil reinforcement, drainage, and erosion-control solutions in highways, landfills, mining areas, and large-scale civil construction projects, supported by stricter environmental regulations and infrastructure modernization programs worldwide.
- Key market trends include increasing adoption of geotextile-geogrid products, which hold a leading 34.6% segment share in 2024, along with growing usage of sustainable, polymer-efficient geocomposites and technically advanced multi-layer systems across containment and drainage applications.
- The competitive landscape features active participation from major players focusing on product innovation, performance optimization, and regional expansion, with companies strengthening distribution networks and partnering with engineering and construction firms to enhance market reach.
- Asia-Pacific leads the market with a 33.8% regional share in 2024, followed by North America at 29.4% and Europe at 26.7%, while Latin America and the Middle East & Africa collectively represent emerging growth regions supported by infrastructure and mining-related investments.
Geocomposites Market Segmentation Analysis:
By Product
The Geocomposites market by product demonstrates strong adoption across engineered combinations, with geotextile-geogrid emerging as the dominant sub-segment with a 34.6% market share in 2024. This configuration gains preference due to its superior tensile strength, slope stabilization capability, and effectiveness in load-bearing reinforcement for transportation and industrial infrastructure. Geotextile-geonet follows closely in drainage and landfill lining projects, while geotextile-geomembrane sees rising demand in containment systems. Growth across products is driven by rapid urbanization, increasing roadway rehabilitation projects, and stringent environmental protection regulations that accelerate the use of high-performance, durable geocomposite solutions.
- For instance, TenCate Geosynthetics’ Mirafi® geotextile–geogrid systems are used in reinforced soil structures for highways and railways to improve bearing capacity and reduce differential settlement.
By Function
In terms of function, the Geocomposites market is led by the drainage segment, which accounted for 41.2% of the market share in 2024. This dominance stems from its critical role in preventing soil erosion, relieving pore-water pressure, and enhancing sub-surface stability in highways, railways, and landfill engineering. Containment functions continue to expand with greater emphasis on waste management and groundwater protection, while other functional uses support soil separation and reinforcement. Key growth drivers include infrastructure modernization programs, stricter geotechnical safety standards, and wider acceptance of engineered drainage composites over conventional granular materials.
- For instance, AGRU produces needle-punched geocomposite clay liners (e.g., Bentonite-based liners) and geotextile-backed HDPE geomembranes for landfills, mining, and industrial ponds to improve leak prevention and regulatory compliance
By Application
Across applications, road and highway construction represents the leading segment with a 38.5% market share in 2024, supported by extensive usage of geocomposites for pavement reinforcement, base stabilization, embankment support, and drainage enhancement. Land and mining applications record steady adoption for heap-leach pads and erosion-control structures, while water and wastewater management benefits from lining, filtration, and containment solutions. Demand continues to rise in soil reinforcement for civil construction. Market growth is driven by large-scale transportation investments, sustainability-focused engineering practices, and increasing reliance on lightweight, high-strength materials that extend infrastructure service life.
Key Growth Drivers
Infrastructure Expansion and Transportation Modernization
Rapid global investment in transportation and civil infrastructure projects is a primary growth driver for the Geocomposites market. Governments are prioritizing the construction and rehabilitation of highways, railways, bridges, and airport runways to improve mobility and support economic development. Geocomposites play a critical role in these projects by enhancing soil stabilization, improving pavement durability, and enabling efficient drainage, which collectively extend infrastructure service life and reduce maintenance costs. The increasing adoption of lightweight reinforcement materials over traditional aggregates also supports faster installation and lower project costs. Additionally, urbanization in emerging economies has accelerated demand for erosion control and embankment reinforcement solutions. Public–private infrastructure partnerships, expansion of smart mobility corridors, and large-scale road development initiatives in Asia-Pacific, the Middle East, and Latin America further stimulate market growth, reinforcing the importance of geocomposites as essential engineered materials in modern geotechnical and transportation engineering applications.
- For instance, Solmax (including the former TenCate Geosynthetics portfolio) supplies Mirafi® and other geocomposite systems for roadway subgrade stabilization and edge drainage to improve bearing capacity and mitigate water-induced pavement failures
Environmental Sustainability and Regulatory Compliance
Strengthening environmental regulations and sustainability commitments significantly drive the adoption of geocomposites across containment, landfill engineering, and water management applications. Regulatory bodies increasingly mandate engineered solutions for groundwater protection, waste containment, slope stabilization, and erosion control, positioning geocomposites as preferred alternatives to conventional materials. Their reduced carbon footprint, lower material consumption, and enhanced performance in filtration and drainage align with circular economy objectives and climate-resilient infrastructure development. The ability of geocomposites to replace bulk natural aggregates also minimizes quarrying and onsite environmental disruption. In industrial and mining operations, stricter leachate control and soil retention standards accelerate the use of geotextile-geomembrane and geotextile-geonet combinations. Growing emphasis on sustainable construction certifications, eco-friendly land development, and resilient flood-management systems further strengthens market penetration. As governments and industries continue prioritizing green engineering practices, the demand for durable, recyclable, and performance-optimized geocomposite systems is expected to increase steadily.
- For instance, Maccaferri’s MacMat® and MacDrain® geocomposites support erosion control and surface drainage on environmentally sensitive slopes, minimizing soil loss and construction impacts compared with conventional granular solutions.
Cost Efficiency and Performance Advantages Over Traditional Materials
Geocomposites deliver significant economic and operational advantages compared with conventional construction and soil reinforcement materials, driving widespread market adoption. Their multifunctional design enables simultaneous reinforcement, filtration, and drainage, reducing the need for multiple material layers and minimizing installation labor. Lightweight structure lowers transportation and handling costs, while faster deployment speeds construction schedules in road, mining, and land development projects. The long-term performance benefits-such as improved load distribution, enhanced stability, and superior durability under harsh environmental conditions-reduce lifecycle maintenance expenses and extend infrastructure longevity. Engineers increasingly prefer geocomposites due to their consistent material quality, design flexibility, and suitability for complex terrain and geotechnical conditions. The shift toward mechanized and modular construction methods also aligns with geocomposite compatibility, reinforcing their role in modern construction practices. These combined performance and cost efficiencies position geocomposites as value-driven solutions across large-scale infrastructure and environmental engineering projects.
Key Trends & Opportunities
Rising Adoption in Renewable Energy and Environmental Engineering Projects
A major emerging trend in the Geocomposites market is the expanding use of geocomposite materials in renewable energy infrastructure and large-scale environmental engineering projects. Solar farms, wind energy foundations, and energy storage sites increasingly require ground stabilization, erosion control, and drainage reinforcement, creating new application opportunities. In environmental remediation, geocomposites support landfill capping, leachate drainage, wastewater containment, and brownfield rehabilitation, aligning with global sustainability and resource-recovery initiatives. Climate-resilient infrastructure programs emphasize flood-protection embankments, shoreline stabilization, and slope reinforcement, further boosting demand. Growth in eco-industrial parks, green urban landscapes, and sustainable land development strengthens the role of geocomposites in environmental compliance. As climate-adaptation funding expands, engineers and policymakers increasingly recognize geocomposites as reliable and efficient materials for long-term environmental resilience, positioning the sector for sustained adoption across green and restoration-focused infrastructure segments.
- For instance, HUESKER’s Fortrac® geogrid-based reinforcement geocomposites are used in onshore wind farm access roads and crane platforms to improve bearing capacity on soft ground and reduce aggregate consumption.
Technological Advancements and Product Innovation in Smart and High-Performance Geocomposites
Ongoing material innovation presents significant opportunities in the Geocomposites market, particularly through the development of high-strength, polymer-enhanced, and sensor-integrated composite solutions. Manufacturers are advancing geocomposites with improved tensile strength, chemical resistance, and UV stability to support heavy-load infrastructure and harsh environmental applications. The integration of smart monitoring technologies, including fiber-optic sensing for strain and moisture detection, enables predictive maintenance and structural health monitoring in roadways and embankments. Bio-based and recycled polymer geocomposites are gaining prominence as sustainable alternatives, addressing carbon-reduction targets and material circularity requirements. Customized multi-layer configurations designed for specialized applications such as mining pads, tunnel linings, and marine protection create new market niches. Digital design tools and advanced geotechnical modelling also improve engineering accuracy and performance optimization. These innovation-driven advancements enhance reliability, expand functional capabilities, and create strong growth opportunities across next-generation infrastructure programs.
- For instance, several infrastructure projects have combined conventional geosynthetics with distributed fiber-optic sensors embedded in soil or structures for real-time deformation and moisture tracking, supporting data-driven asset management.
Key Challenges
Fluctuating Raw Material Prices and Supply Chain Dependence
The Geocomposites market faces a major challenge from volatility in polymer-based raw material prices and supply chain dependencies, particularly for polypropylene, polyester, and polyethylene resins. Price fluctuations driven by crude oil dynamics, geopolitical disruptions, and logistics constraints directly affect manufacturing costs and profit margins. Small and mid-scale producers remain especially vulnerable to supply interruptions and extended lead times. Additionally, reliance on imported raw materials in several regions creates cost inefficiencies and procurement uncertainty. Competitive pricing pressure in infrastructure projects further limits manufacturers’ ability to pass cost increases to end users. The lack of standardized global pricing structures and limited recycling integration add to the challenge. To mitigate risks, industry participants increasingly explore local sourcing, backward integration, recycled polymer alternatives, and strategic supplier partnerships, yet supply chain resilience remains a critical concern impacting long-term market stability and scalability.
Limited Awareness, Technical Skill Gaps, and Performance Misconceptions in Emerging Markets
Despite growing adoption, the Geocomposites market confronts challenges associated with limited technical awareness and skill gaps among contractors, project authorities, and regulatory bodies, especially in developing economies. In some regions, traditional construction practices continue to dominate due to misconceptions about geocomposite performance, cost benefits, and long-term durability. Inadequate design expertise, insufficient training in geotechnical installation techniques, and lack of standardized engineering guidelines can result in suboptimal deployment or reluctance to adopt advanced composite systems. Variations in regulatory approval processes and slow incorporation of geosynthetic standards into public infrastructure specifications further delay market penetration. Addressing this challenge requires stronger collaboration among manufacturers, engineering institutions, and government agencies through demonstration projects, technical certification programs, and evidence-based performance benchmarking to accelerate knowledge transfer and improve confidence in geocomposite-based infrastructure solutions.
Geocomposites Market Analysis
North America
North America holds a strong position in the Geocomposites market, accounting for 29.4% of the global share in 2024, driven by extensive investments in highway rehabilitation, landfill engineering, and stormwater management infrastructure. The United States leads adoption due to stringent environmental compliance standards, mature geotechnical engineering practices, and widespread use of geotextile-geogrid and drainage composites in road base reinforcement and erosion control. Canada contributes notably through mining and oil-sand containment projects. Ongoing federal and state infrastructure funding, resilience upgrades for climate-vulnerable assets, and increasing landfill capacity expansion continue to support stable regional demand for high-performance geocomposite solutions.
Europe
Europe represents 26.7% of the Geocomposites market share in 2024, supported by strong regulatory emphasis on sustainability, soil erosion prevention, and groundwater protection across transportation, waste management, and industrial land development projects. Western Europe, led by Germany, France, and the UK, demonstrates advanced adoption of geotextile-geomembrane and drainage composites in railway embankments, tunnel lining, and coastal reinforcement. Eastern Europe records rising usage in road modernization and cross-border logistics corridors. Circular-economy policies, green-infrastructure initiatives, and widespread landfill upgrade programs further stimulate market growth, while engineering standardization and geosynthetic design integration strengthen long-term demand across the region.
Asia-Pacific
Asia-Pacific dominates the Geocomposites market with the largest regional share of 33.8% in 2024, fueled by rapid urbanization, large-scale transportation development, and expanding mining and water-management projects. China and India lead consumption through expressway expansion, railway corridors, smart-city construction, and erosion-control applications in rapidly developing urban regions. Southeast Asia and Australia contribute through mining pads, landfill capping, and coastal protection initiatives. Government-backed infrastructure stimulus, industrial land-development programs, and growing awareness of engineering efficiency accelerate adoption of geotextile-geogrid and drainage composites, positioning Asia-Pacific as the fastest-growing regional market throughout the forecast period.
Latin America
Latin America accounts for 5.6% of the Geocomposites market share in 2024, with demand primarily concentrated in mining, road stabilization, and landfill engineering applications across Brazil, Mexico, Chile, and Peru. Infrastructure expansion in freight corridors, port facilities, and energy-related civil works supports the increasing use of geocomposites for slope stabilization, leachate control, and pavement reinforcement. The region benefits from growing adoption of engineered drainage systems in urban development and flood-mitigation projects. Although budget constraints and project execution delays affect deployment pace, rising private-sector participation and modernization of geotechnical construction practices continue to create progressive market opportunities.
Middle East & Africa
The Middle East & Africa region holds 4.5% of the Geocomposites market share in 2024, driven by applications in desert road stabilization, landfill containment, water-retention systems, and large-scale civil infrastructure projects. Gulf countries invest significantly in geocomposite-based drainage and soil reinforcement for transportation corridors, smart-city expansions, and coastal protection. Africa records increasing adoption in mining tailing ponds, dam reinforcement, and erosion-control initiatives, particularly in South Africa and Morocco. Harsh climatic conditions, sand-drift challenges, and water-management requirements strengthen the case for durable geocomposite materials, while ongoing infrastructure diversification and sustainability programs support steady long-term regional growth.
Geocomposites Market Segmentations:
By Product
- Geotextile-geonet
- Geotextile-geogrid
- Geotextile-geocore
- Geotextile-geomembrane
- Other
By Function
- Containment
- Drainage
- Others
By Application
- Road & Highway
- Land & Mining
- Water& Wastewater Management
- Soil Reinforcement for Civil Construction
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Geocomposites market features a moderately consolidated structure, with leading players focusing on product innovation, performance enhancement, and application‐specific engineering to strengthen their market presence. Companies such as HUESKER, TenCate Geosynthetics Americas, GSE Environmental, Terram, Thrace Group, ABG Ltd., Officine Maccaferri, Ocean Global, Leggett & Platt, Incorporated, and CLIMAX SYNTHETICS PVT. LTD. actively compete through advancements in geotextile-geogrid, drainage, and containment composite systems tailored for transportation, mining, landfill, and water-management projects. Strategic priorities include expanding manufacturing capacities, strengthening distribution networks, and developing sustainable, polymer-efficient solutions aligned with environmental regulations and infrastructure modernization trends. Partnerships with civil engineering firms, government agencies, and construction contractors support wider adoption, while investments in R&D drive improved durability, load resistance, and installation efficiency. Regional expansion into high-growth markets in Asia-Pacific, the Middle East, and Latin America further intensifies competition, as players target large-scale infrastructure programs and long-term geotechnical engineering initiatives to secure market leadership.
Key Player Analysis
- Terram
- HUESKER
- Ocean Global
- Thrace Group
- ABG Ltd.
- Officine Maccaferri Spa
- Leggett & Platt, Incorporated
- TenCate Geosynthetics Americas
- CLIMAX SYNTHETICS PVT. LTD.
- GSE Environmental
Recent Developments
- In October 2025, HUESKER Inc. launched the active geocomposite product “Tektoseal Active PFAS”, an advanced geocomposite designed to absorb and immobilize PFAS contaminants in soil and leachate applications, catering to environmental protection and landfill containment projects.
- In July 2024, Wrekin Products (UK) launched its new geosynthetics brand “Geoworks,” consolidating and marketing its portfolio of geotextiles, geogrids, geomembranes, geomats, geocells, and geocellular paving solutions within the geocomposites and broader geosynthetics marke
Report Coverage
The research report offers an in-depth analysis based on Product, Function, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Geocomposites market will witness sustained growth as governments and private developers continue to invest in transportation, landfill management, and large-scale civil engineering projects.
- Adoption will increase as engineers prefer lightweight, durable, and multifunctional materials that enhance structural stability and reduce long-term maintenance requirements.
- Demand will rise in road and highway reinforcement, rail infrastructure, and embankment stabilization projects as countries focus on infrastructure modernization.
- The market will benefit from stricter environmental regulations that promote engineered drainage, erosion control, and groundwater protection solutions.
- Technological innovation will expand, with manufacturers developing high-performance geocomposites featuring improved tensile strength, filtration efficiency, and resistance to harsh conditions.
- Sustainability initiatives will encourage greater use of recycled and polymer-efficient materials, supporting circular-economy construction practices.
- Growth opportunities will emerge in renewable energy, mining, waste-to-energy facilities, and climate-resilient infrastructure projects.
- Market players will strengthen R&D collaboration with engineering firms to design application-specific composite systems.
- Asia-Pacific will remain the fastest-growing region due to rapid urban development and expanding industrial and mining activities.
- Increased awareness, training programs, and incorporation of geosynthetics into engineering standards will support broader global adoption of geocomposites.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Infrastructure Expansion and Transportation Modernization
Global investments in highways, railways, and civil infrastructure are fueling demand for geocomposites, which provide essential soil stabilization, drainage, and reinforcement. Their use extends infrastructure service life and reduces maintenance costs, making them integral to modernization programs.
Stricter Environmental Regulations and Sustainability Initiatives
Tighter regulations on waste containment, groundwater protection, and erosion control are driving adoption of geocomposites as engineered solutions. Their lower carbon footprint and ability to replace bulk aggregates align with sustainability and circular economy goals.
Cost Efficiency and Performance Advantages
Geocomposites offer multifunctional benefits - reinforcement, filtration, and drainage - in a single product, reducing material layers and installation labor. Their lightweight nature lowers transportation costs and speeds up project timelines, providing significant economic and operational advantages over traditional materials.
Technological Advancements and Product Innovation
Ongoing R&D is leading to high-performance, polymer-efficient, and sensor-integrated geocomposites with improved strength, durability, and monitoring capabilities. These innovations expand application possibilities and support adoption in demanding infrastructure and environmental projects.
Growth in Renewable Energy and Environmental Engineering Applications
The rise of renewable energy infrastructure and large-scale environmental remediation projects is creating new opportunities for geocomposites in ground stabilization, drainage, and containment, further expanding the market beyond traditional civil engineering sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Geocomposites Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Geocomposites Market projected to grow between 2024 and 2032?
Which Geocomposites Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Geocomposites Market?
Who are the leading companies in the Geocomposites Market?
Which region commanded the largest share of the Geocomposites Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Geotextile-geonet
- 1.2.2 Geotextile-geogrid
- 1.2.3 Geotextile-geocore
- 1.2.4 Geotextile-geomembrane
- 1.2.5 Other
- 1.3 By Function
- 1.3.1 Containment
- 1.3.2 Drainage
- 1.3.3 Others
- 1.4 By Application
- 1.4.1 Road & Highway
- 1.4.2 Land & Mining
- 1.4.3 Water & Wastewater Management
- 1.4.4 Soil Reinforcement for Civil Construction
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 564 Million → 2032: USD 1,074.88 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Geosynthetics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Geosynthetics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Geosynthetics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Geosynthetics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Geosynthetics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Geosynthetics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Geosynthetics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Geosynthetics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 564 Million → 2032: USD 1,074.88 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Geosynthetics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Geotextile-geonet
- 12.3.7.2 Geotextile-geogrid
- 12.3.7.3 Geotextile-geocore
- 12.3.7.4 Geotextile-geomembrane
- 12.3.7.5 Other
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Function - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Containment
- 12.4.7.2 Drainage
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Road & Highway
- 12.5.7.2 Land & Mining
- 12.5.7.3 Water & Wastewater Management
- 12.5.7.4 Soil Reinforcement for Civil Construction
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Geosynthetics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Geosynthetics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Geosynthetics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Geosynthetics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 HUESKER
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 TenCate Geosynthetics Americas
- 18.4 GSE Environmental
- 18.5 Terram
- 18.6 Thrace Group
- 18.7 ABG Ltd.
- 18.8 Officine Maccaferri
- 18.9 Ocean Global
- 18.10 Leggett & Platt, Incorporated
- 18.11 CLIMAX SYNTHETICS PVT. LTD.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

