
Market Overview:
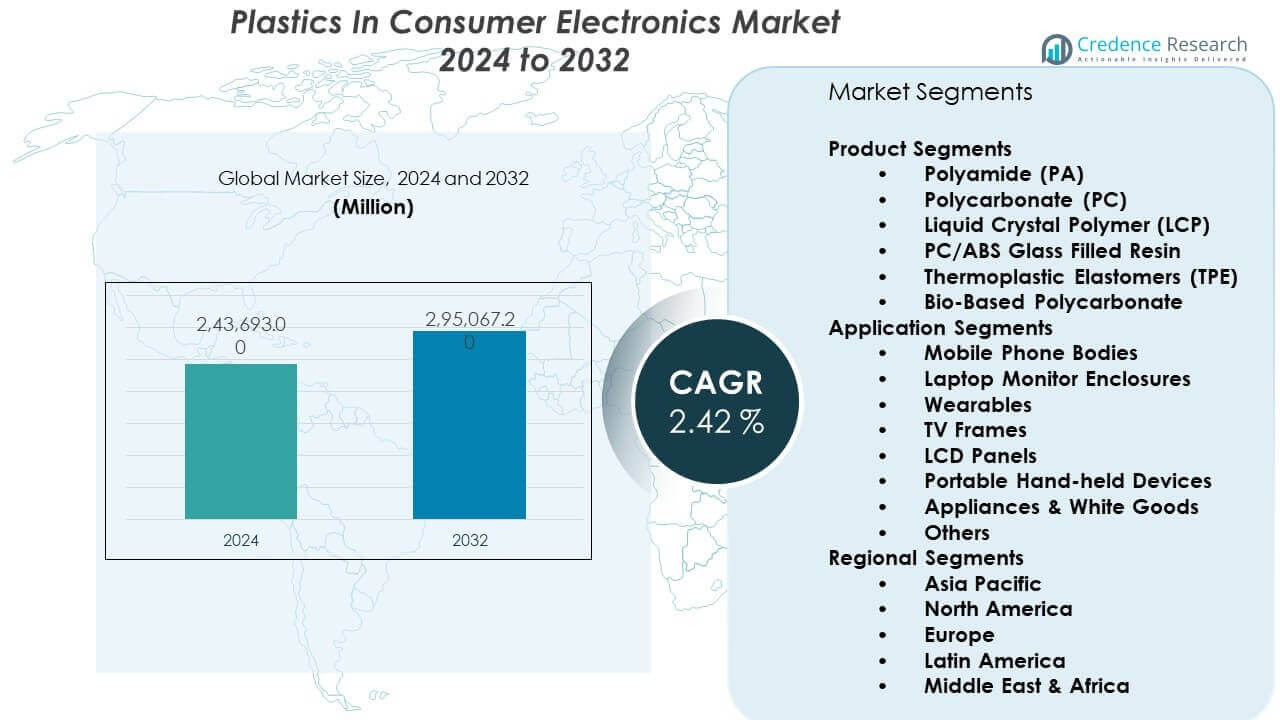
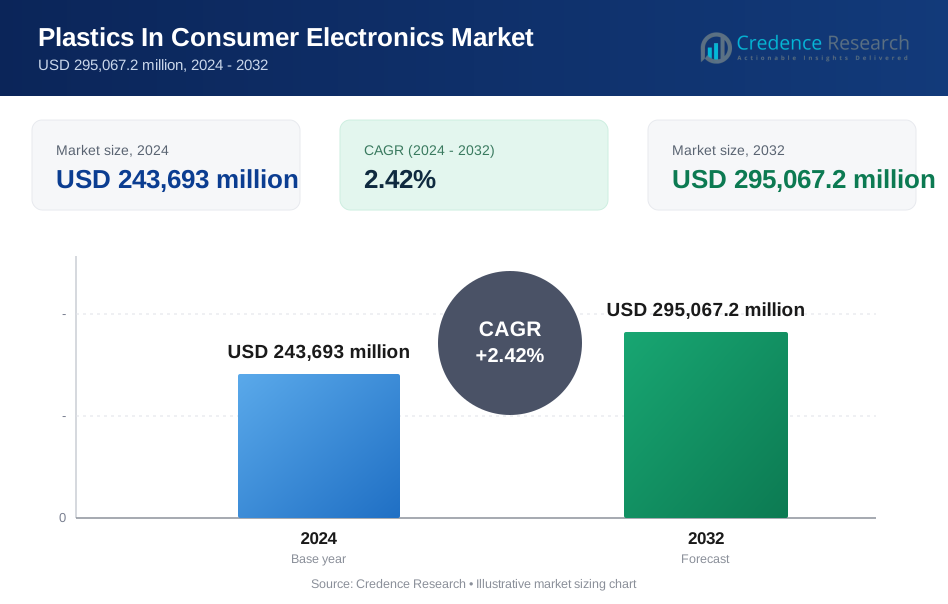
The Plastics in Consumer Electronics Market is projected to grow from USD 243,693 million in 2024 to USD 295,067.2 million by 2032. The market is expected to expand at a compound annual growth rate of 2.42% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Plastics In Consumer Electronics Market Size 2024 | USD 243,693 million |
| Plastics In Consumer Electronics Market, CAGR | 2.42% |
| Plastics In Consumer Electronics Market Size 2032 | USD 295,067.2 million |
Market growth is driven by rising production of smartphones, laptops, and wearables. Manufacturers prefer plastics for insulation, impact resistance, and design freedom. Thin-wall molding supports compact device layouts. Heat-resistant polymers protect internal components. Lightweight casings improve portability and user comfort. Mass production favors plastics for faster processing cycles. Recycling-focused polymer grades gain attention from brands. Consumer preference for sleek designs supports advanced plastic use. Electronics makers rely on plastics to balance performance and cost.
Asia Pacific leads the market due to large electronics manufacturing hubs. China, South Korea, and Taiwan dominate component production. Strong supply chains support high polymer consumption. Japan focuses on precision and high-performance plastic materials. North America remains a key innovation center for electronics design. The United States drives demand for premium devices. Europe shows steady growth with sustainability-driven material choices. Emerging markets in Southeast Asia gain momentum from assembly expansion.
Market Insights:
- The market reached USD 243,693 million in 2024 and is projected to reach USD 295,067.2 million by 2032, growing at a CAGR of 2.42%, supported by steady consumer electronics production.
- Asia Pacific leads with 68.07% share, driven by large-scale manufacturing in China, South Korea, and India, while Europe holds 15% due to recycling mandates, and North America accounts for ~12% with strong device innovation.
- North America is the fastest-growing region with ~12% share, supported by premium electronics demand, material innovation, and higher adoption of recycled and bio-based plastics.
- By product type, polycarbonate holds 33.1% share, reflecting high use in smartphone casings, display housings, and impact-resistant components.
- By application, laptop monitor enclosures account for 22% share, supported by lightweight design requirements and consistent replacement demand.
Market Drivers:
Rising Demand For Lightweight And Compact Consumer Electronic Devices
The Plastics in consumer electronics market gains momentum from compact device demand. Manufacturers focus on reducing product weight to improve comfort. Plastics support thin and lightweight housing structures. Smartphones and tablets rely on slim casing designs. Lightweight materials lower logistics and handling costs. Plastics allow complex shapes for modern aesthetics. Design teams value flexibility during product development. It supports mass production with consistent quality output.
- For instance, Samsung confirmed that Galaxy S23 devices use recycled plastics from discarded fishing nets and PET bottles, cutting component weight while maintaining drop-test durability standards exceeding 1.2 meters.
Cost Efficiency And High-Volume Manufacturing Compatibility Across Electronics
The Plastics in consumer electronics market benefits from strong cost control needs. Electronics brands operate in price-sensitive segments. Plastics reduce raw material and processing expenses. Injection molding supports large-scale manufacturing cycles. Short production times improve factory efficiency. Manufacturers gain predictable performance across batches. Stable supply chains support planning accuracy. It improves margins in competitive markets.
- For instance, Apple suppliers use multi-cavity injection molds for polycarbonate components, producing millions of identical parts per month with dimensional tolerances under ±0.05 mm.
Electrical Insulation And Component Protection Requirements In Devices
The Plastics in consumer electronics market depends on insulation performance. Electronic components require reliable electrical isolation. Plastics protect users from electrical exposure. Device housings reduce short-circuit risks. Materials withstand moderate internal heat levels. Plastics absorb vibration and minor impacts. Product reliability improves through protective casings. It supports compliance with safety standards.
Design Flexibility Supporting Product Differentiation And Brand Identity
The Plastics in consumer electronics market enables strong design variation. Brands focus on distinct product appearances. Plastics allow smooth curves and color options. Surface finishes enhance visual appeal. Rapid design changes support frequent model updates. Custom shapes strengthen brand identity. Plastics support faster tooling adjustments. It shortens design-to-market timelines.
Market Trends:
Shift Toward High-Performance Engineering Plastics In Premium Devices
The Plastics in consumer electronics market shows a shift toward advanced materials. Manufacturers adopt engineering-grade plastics. Premium devices demand higher heat resistance. Stronger polymers extend product lifespan. High-end electronics require durable enclosures. Material innovation improves mechanical strength. Suppliers invest in polymer development. It supports premium product positioning.
- For instance, BASF’s Ultramid® polyamide grades used in electronic connectors withstand continuous operating temperatures up to 160 °C and short-term exposure beyond 200 °C in certified device applications.
Growing Use Of Recycled And Bio-Based Plastic Materials
The Plastics in consumer electronics market reflects sustainability priorities. Electronics brands adopt recycled plastic content. Environmental targets influence material selection. Bio-based plastics receive growing attention. Regulatory pressure supports sustainable sourcing. Consumers favor eco-conscious product claims. Manufacturers adjust procurement strategies. It strengthens sustainability credentials.
- For instance, Murata Manufacturing uses LCP connectors in 5G modules due to dielectric stability at frequencies above 28 GHz with minimal signal loss.
Rising Adoption Of Matte, Textured, And Soft-Touch Finishes
The Plastics in consumer electronics market follows surface design trends. Consumers value improved tactile experience. Matte finishes reduce visible fingerprints. Textured surfaces enhance grip quality. Soft-touch coatings improve handling comfort. Brands invest in surface treatment technology. Finish quality influences buying decisions. It improves perceived product value.
Integration Of Plastics With Multi-Material Device Structures
The Plastics in consumer electronics market supports hybrid product designs. Devices combine plastics with metal or glass. Plastics reduce overall structural weight. Hybrid designs balance strength and flexibility. Assembly methods evolve for mixed materials. Plastics ease bonding and fastening needs. Structural optimization becomes a design priority. It supports advanced device architectures.
Market Challenges Analysis:
Environmental Concerns And Regulatory Pressure On Plastic Usage
The Plastics in consumer electronics market faces regulatory challenges. Governments enforce stricter plastic usage rules. Brands face pressure to cut virgin plastic use. Recycling infrastructure varies by region. Compliance increases operational complexity. Material traceability becomes mandatory. Public perception affects brand trust. It forces shifts in material strategy.
Performance Limitations Under High Thermal And Mechanical Stress
The Plastics in consumer electronics market encounters performance limits. High-power devices generate more internal heat. Some polymers degrade under thermal stress. Mechanical wear affects long-term durability. Material failure risks quality issues. Manufacturers increase testing standards. Design tolerances narrow across products. It raises validation costs.
Market Opportunities:
Expansion Of Wearables And Smart Devices With Lightweight Designs
The Plastics in consumer electronics market gains from wearable growth. Smart devices need lightweight materials. Plastics support ergonomic and compact designs. Comfort drives user adoption rates. Wearable demand rises across age groups. Product cycles remain short. Plastics enable rapid prototyping. It supports faster launches.
Innovation In Sustainable Plastics And Advanced Polymer Blends
The Plastics in consumer electronics market offers strong innovation potential. Material suppliers develop sustainable polymers. Advanced blends improve strength and recyclability. Electronics brands seek compliant materials. New polymers meet safety standards. Sustainable sourcing attracts investors. Research spending rises steadily. It opens long-term growth paths.
Market Segmentation Analysis:
Product Segments
The Plastics in consumer electronics market shows clear differentiation across polymer types. Polyamide supports connectors and internal housings due to strength and heat resistance. Polycarbonate holds wide use in casings and display-related parts due to impact resistance. Liquid Crystal Polymer serves high-frequency and miniaturized components in advanced electronics. PC/ABS glass filled resin balances rigidity and durability in structural frames. Thermoplastic elastomers support flexible and touch-friendly parts in modern devices. Bio-based polycarbonate gains attention for sustainability-focused electronics. It benefits from regulatory and brand-level environmental goals.
- For instance, Murata Manufacturing uses LCP connectors in 5G modules due to dielectric stability at frequencies above 28 GHz with minimal signal loss.
Application Segments
The Plastics in consumer electronics market reflects strong demand across diverse device categories. Mobile phone bodies lead usage due to large production volumes. Laptop monitor enclosures rely on lightweight plastics for portability. Wearables drive demand for flexible and skin-friendly materials. TV frames use rigid plastics to balance size and cost efficiency. LCD panels depend on precision plastics for insulation and alignment. Portable hand-held devices favor impact-resistant polymers. Appliances and white goods sustain steady demand for durable plastics. It maintains relevance through wide application coverage and stable replacement cycles.
- For instance, LG Electronics uses reinforced polycarbonate blends in TV frames exceeding 55-inch sizes to maintain structural rigidity while reducing overall chassis weight.
Segmentation:
Product Segments
- Polyamide (PA)
- Polycarbonate (PC)
- Liquid Crystal Polymer (LCP)
- PC/ABS Glass Filled Resin
- Thermoplastic Elastomers (TPE)
- Bio-Based Polycarbonate
Application Segments
- Mobile Phone Bodies
- Laptop Monitor Enclosures
- Wearables
- TV Frames
- LCD Panels
- Portable Hand-held Devices
- Appliances & White Goods
- Others
Regional Segments
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific Leads Through Large-Scale Electronics Manufacturing Base
The Plastics in consumer electronics market is led by Asia Pacific with a 68.07% share. China anchors large-scale smartphone and electronics production. South Korea and Japan support premium devices and advanced polymer use. India and Vietnam expand assembly capacity for global brands. Strong supplier networks reduce material costs and lead times. Local tooling and molding ecosystems support fast product cycles. This scale keeps the region dominant in global plastics demand.
Europe And North America Balance Compliance, Innovation, And Material Upgrades
Europe accounts for 15% share, driven by strict sustainability and recycling regulations. Germany, France, and the UK promote recycled plastic use in electronics. Circular economy policies influence material selection across devices. North America holds nearly 12% share with strong innovation focus. The United States leads in premium electronics design and materials testing. Brands emphasize bio-based and recycled plastics. This approach sustains stable demand across both regions.
Latin America And Middle East & Africa Show Gradual Scale-Up In Electronics Output
Latin America represents about 5% share with growth in regional electronics assembly. Brazil and Mexico benefit from near-shoring and rising consumer demand. Expanding middle-class populations support device sales. Middle East & Africa hold nearly 3% share with fast device adoption. Gulf countries invest in manufacturing and industrial diversification. South Africa and Nigeria see rising smartphone penetration. It supports gradual market expansion from a smaller base.
Key Player Analysis:
- BASF SE
- Covestro AG
- SABIC
- DuPont de Nemours Inc.
- Mitsubishi Chemical Corporation
- LG Chem Ltd.
- Solvay S.A.
- Celanese Corporation
- Eastman Chemical Company
- Evonik Industries AG
- LANXESS AG
- DSM‑firmenich
- Sinopec
- Formosa Plastics Corporation
- Teijin Limited
- Sumitomo Chemical Co., Ltd.
Competitive Analysis:
The Plastics in consumer electronics market shows strong competition among global material suppliers and component manufacturers. Leading companies focus on engineering plastics, high-performance polymers, and sustainable materials. Product differentiation depends on heat resistance, durability, and surface quality. Firms invest in material innovation to support miniaturized electronics. Strategic partnerships with OEMs strengthen long-term supply contracts. Regional players compete on cost efficiency and localized production. It remains moderately consolidated with clear tier-one leaders. Competitive strength depends on material portfolio breadth and application expertise.
Recent Developments:
- In May 2025, BASF signed an agreement to acquire DOMO Chemicals' 49% stake in the Alsachimie joint venture, strengthening its polyamide 6.6 precursors supply critical for electronics components like connectors and housings. This move ensures reliable European supply for high-performance plastics used in consumer electronics.
- In August 2025, Covestro completed the acquisition of Pontacol, a Swiss maker of multilayer adhesive films, expanding its portfolio for functional films in electronics assemblies and flexible circuits. On December 14, 2025, Covestro closed its strategic partnership with XRG P.J.S.C., enabling innovation in sustainable plastics for consumer devices through enhanced R&D and circular economy initiatives.
- In July 2024, DuPont completed the acquisition of Donatelle Plastics Incorporated for $313 million, adding advanced injection molding and precision machining for medical-grade plastics adaptable to electronics enclosures and components. This bolsters DuPont's capabilities in high-growth areas overlapping with consumer electronics manufacturing.
Report Coverage:
The research report offers an in-depth analysis based on Product Segments and Application Segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will increase due to ongoing miniaturization of consumer electronic devices.
- Engineering plastics will see wider adoption to meet durability and heat resistance needs.
- Sustainable and recycled polymers will gain stronger acceptance among global OEMs.
- Wearable electronics will drive higher use of flexible and soft-touch plastic materials.
- Hybrid material designs will expand to balance strength, weight, and cost efficiency.
- Regulatory pressure will push manufacturers toward compliant and traceable plastic sourcing.
- Asia Pacific will continue to lead global production and material consumption volumes.
- Premium consumer electronics will support demand for high-performance polymer grades.
- Material innovation will enable faster product development and shorter launch cycles.
- Strategic partnerships between polymer suppliers and device makers will strengthen market stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Plastics in consumer electronics market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Plastics in consumer electronics market projected to grow between 2025 and 2032?
Which Plastics in consumer electronics market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Plastics in consumer electronics market?
Who are the leading companies in the Plastics in consumer electronics market?
Which region commanded the largest share of the Plastics in consumer electronics market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Plastics In Consumer Electronics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Plastics In Consumer Electronics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 243,693 million → 2032: USD 295,067.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Plastics In Consumer Electronics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Plastics In Consumer Electronics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Plastics In Consumer Electronics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Plastics In Consumer Electronics Market Drivers
- 3.3 Plastics In Consumer Electronics Market Restraints & Challenges
- 3.4 Plastics In Consumer Electronics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Plastics In Consumer Electronics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Plastics In Consumer Electronics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Plastics In Consumer Electronics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Plastics In Consumer Electronics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Plastics In Consumer Electronics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Plastics In Consumer Electronics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Plastics In Consumer Electronics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Plastics In Consumer Electronics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Plastics In Consumer Electronics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Plastics In Consumer Electronics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Plastics In Consumer Electronics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Plastics In Consumer Electronics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Plastics In Consumer Electronics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Plastics In Consumer Electronics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Plastics In Consumer Electronics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Plastics In Consumer Electronics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Plastics In Consumer Electronics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Plastics In Consumer Electronics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Plastics In Consumer Electronics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
