
Market Overview:
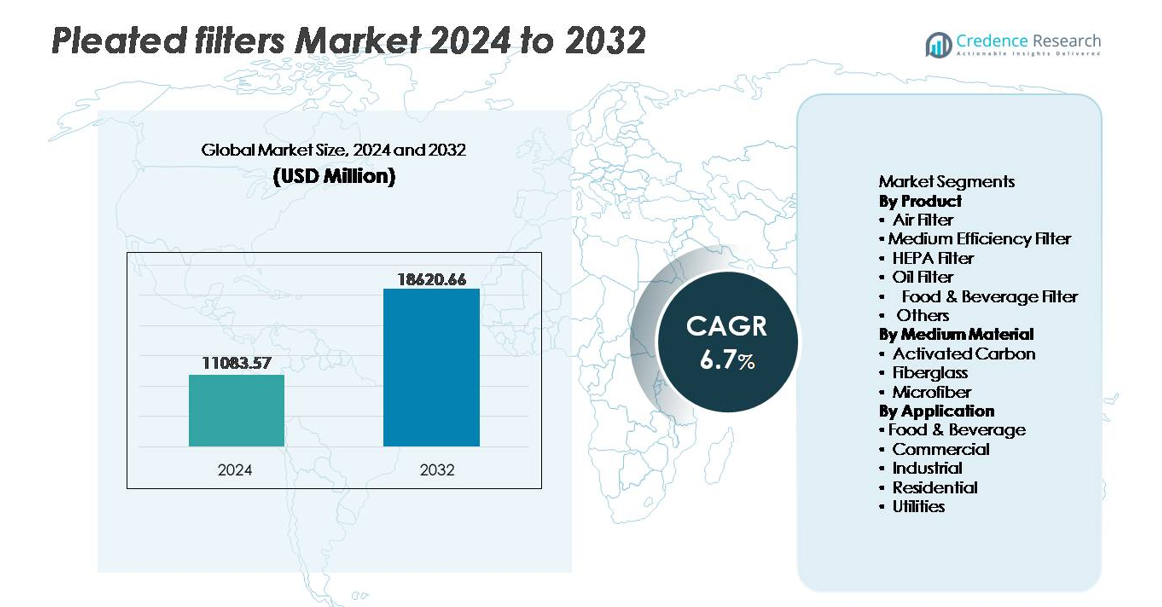
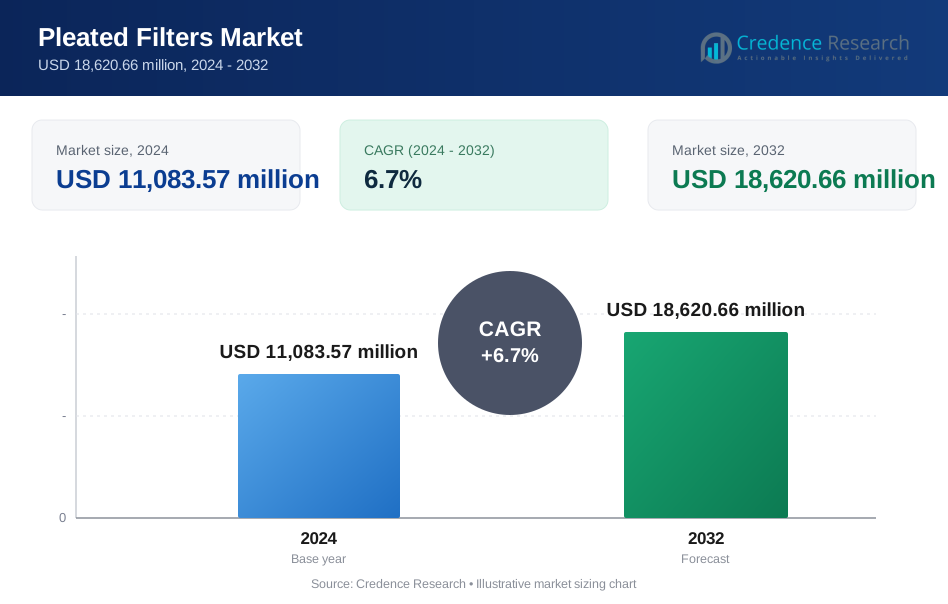
The global pleated filters market was valued at USD 11,083.57 million in 2024 and is projected to reach USD 18,620.66 million by 2032, growing at a CAGR of 6.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pleated Filters Market Size 2024 | USD 11,083.57 million |
| Pleated Filters Market, CAGR | 6.7% |
| Pleated Filters MarketSize 2032 | USD 18,620.66 million |
The pleated filters market features strong participation from global and regional manufacturers, with Delta Filtration, Camfil AB, Honeywell International Inc., Freudenberg and Company, Absolent Group, General Motors Company, Donaldson Company, Inc., Atlas Copco, Clarcor Air Filtration, and 3M Company positioned as key players. These companies compete through advanced filter media innovations, energy-efficient designs, and customized solutions for industrial, commercial, and residential applications. North America remains the leading regional market, holding approximately 32% of global share, driven by stringent indoor air quality standards, mature HVAC adoption, and large-scale industrial operations requiring high-performance filtration systems.
Market Insights:
- The global pleated filters market was valued at USD 11,083.57 million in 2024 and is expected to reach USD 18,620.66 million by 2032, expanding at a CAGR of 6.7% during the forecast period.
- Market growth is propelled by rising air pollution concerns, regulatory standards for indoor air quality, and increased adoption of HVAC systems across commercial, industrial, and residential sectors.
- Advancements in nanofiber-coated media, antimicrobial filtration, and smart filter monitoring systems represent key trends supporting premium product adoption.
- The market remains moderately competitive, with players focusing on product durability, energy efficiency, and recyclable filter components to differentiate in price-sensitive segments.
- North America leads with 32% share, followed by Asia-Pacific at 29% and Europe at 27%, while air filters represent the dominant product segment, driven by high installation and replacement rates across buildings and manufacturing facilities.
Market Segmentation Analysis:
By Product
Air filters represent the dominant product segment, holding the largest share due to their widespread adoption in HVAC systems and their ability to capture particulate matter in indoor environments. The demand is driven by regulatory emphasis on indoor air quality, increasing urban pollution, and the construction of commercial complexes and cleanrooms. HEPA filters are expanding rapidly, particularly in healthcare, microelectronics, and aerospace, where ultra-fine particulate removal is critical. Oil and food & beverage filters demonstrate steady growth, supported by rising industrial processing and hygiene compliance standards.
- For instance, Camfil’s Megalam EnerGuard filter incorporates a proprietary polymeric media capable of achieving ultra-low penetration on the Most Penetrating Particle Size (MPPS). This filter is available in various efficiencies, including U15 (an ULPA classification), which enables installations designed for cleanroom classifications up to and including ISO Class 3 environments. The general MPPS for HEPA/ULPA filters is typically around 0.12–0.15 microns (within the 0.1 to 0.2 micron range).
By Medium Material
Fiberglass stands as the leading medium material, driven by its durability, flame resistance, and suitability for high-temperature industrial environments including chemical processing and power generation. Activated carbon pleated filters are gaining momentum due to their capacity to adsorb odors, gases, and volatile organic compounds, making them ideal for commercial kitchens, laboratories, and waste management facilities. Microfiber-based filters continue to expand in high-precision applications, particularly pharmaceutical and electronics manufacturing, where fine particulate removal and low-pressure drop performance support operational efficiency.
- For instance, AAF Flanders manufactures high-temperature fiberglass filter media used in environments reaching up to 260°C, enabling deployment in gas-turbine inlet systems and chemical furnaces where thermal cycling stability and dimensional retention are critical.
By Application
The industrial sector dominates the application landscape, supported by filtration requirements across manufacturing, oil & gas, metalworking, cement, and automotive production. Stringent worker safety regulations and emission control policies drive higher-grade filtration installations. The commercial segment follows, propelled by retail, corporate buildings, hospitals, and hospitality infrastructure prioritizing clean indoor air quality. Residential use is increasing gradually due to consumer awareness of health risks associated with airborne pollutants. Utilities integrate pleated filters in power generation and water treatment, focusing on equipment protection and process reliability.
Key Growth Drivers:
Rising Air Quality Concerns and Regulatory Compliance
Growing public health concerns associated with airborne particulate matter, allergens, and industrial emissions serve as a primary driver for pleated filter adoption. Governments across North America, Europe, and Asia-Pacific are tightening regulatory frameworks related to indoor and outdoor air quality, including filtration standards for commercial buildings, manufacturing facilities, and clean air zones. The rise of respiratory disorders linked to pollution and occupational exposure is prompting organizations to invest in higher-grade filtration systems. Urbanization and increased vehicle density add to particulate concentration, placing filtration infrastructure among priority installations. The expansion of healthcare infrastructure, biotechnology labs, and semiconductor cleanrooms where even micro-particle contamination can inhibit operational processes further accelerates demand. Pleated filters benefit from low maintenance, better airflow, and extended service life compared to traditional panel filters, which aligns with end-user requirements for energy efficiency and cost optimization.
- For instance, 3M High Airflow (HAF) pleated filter media offers up to 25 Pascals lower initial pressure drop than comparable mechanical filters at similar efficiency ratings, reducing HVAC energy consumption and extending operational runtime between filter replacements in hospitals and life science facilities.
Industrial Growth and Expansion of Process Manufacturing
The growth of process-heavy industries such as pharmaceuticals, food and beverage, cement, metals, and chemical manufacturing drives the adoption of pleated filters for air, liquid, and oil filtration. As companies scale operations and expand globally, filtration systems become mission-critical to safeguard equipment, maintain sterile production environments, and comply with HACCP, GMP, and emission-monitoring standards. Preventive maintenance strategies are also catalyzing integration of advanced pleated filters to reduce downtime and extend asset lifecycle. Increasing automation and robotics in factories require cleaner air and controlled particulate levels to protect sensitive assemblies. The expansion of the global supply chain has brought strict quality inspection and cross-border compliance, motivating enterprises to deploy filtration that delivers higher capture rates and lower pressure drops. Rising investments in renewable energy, including battery manufacturing and hydrogen infrastructure, further broaden industrial filtration needs.
- For instance, Eaton’s industrial filtration solutions include DCF self-cleaning pleated filters capable of handling flow rates up to 1,500 liters per minute in continuous chemical production, supporting uninterrupted operation while reducing filter changeout labor requirements.
Growth in Residential and Commercial Construction Activities
Rapid development of residential and commercial infrastructure, including hospitality properties, hospitals, educational institutions, and retail complexes, significantly supports pleated filter demand. Modern building designs integrate centralized HVAC systems that require efficient filters to maintain indoor air quality and improve energy conservation. Smart building initiatives and green certification programs are driving the installation of advanced filtration systems that reduce operational energy expenditure and support sustainability goals. The surge in co-working spaces, shopping malls, and mixed-use facilities increases the need for standardized air filtration across shared environments. In parallel, consumer awareness about airborne contaminants including viruses, mold spores, VOCs, and dust mites is rising, prompting homeowners to use upgraded pleated filters compatible with ducted air conditioning systems. Post-pandemic risk mitigation has shifted filtration from optional cost to operational necessity, influencing both private and institutional purchases.
Key Trends & Opportunities:
Integration of Nanofiber and Multifunctional Filter Media
A notable trend shaping market innovation is the adoption of nanofiber-coated pleated filters that offer superior filtration efficiency without significantly restricting airflow. Manufacturers are exploring hybrid media incorporating antimicrobial coatings, electrostatic fiber layers, and moisture-resistant surfaces to cater to healthcare, food handling, and laboratory applications. Multifunctional filter media capable of capturing microplastics, odors, gaseous compounds, and chemical aerosols present further commercial opportunities. As industries pursue carbon-neutral operations, demand grows for recyclable filter components and biodegradable frames, enabling circular-economy filtration models. In addition, the opportunity to customize media properties fire resistance, oil repellence, or electrostatic charge retention creates differentiated market offerings and premium pricing potential.
- For instance, Donaldson’s Ultra-Web® nanofiber technology applies fibers with diameters as small as 0.2 microns onto pleated media, enhancing surface loading and improving particulate capture of submicron dust while maintaining lower pressure drop, making it suitable for industrial dust collectors handling high particulate concentrations.
Adoption of Smart Filtration and Predictive Maintenance Systems
Digital transformation is creating new opportunities through sensor-embedded pleated filters and IoT-connected HVAC units capable of monitoring airflow resistance, particulate loading, and pressure drops in real time. As organizations shift toward predictive maintenance, data-driven filtration management supports cost reduction by extending replacement intervals and improving energy efficiency. Commercial buildings, large industrial campuses, and healthcare systems are adopting cloud-monitoring dashboards to optimize filter usage remotely. Smart filtration aligns with growing ESG and energy-efficiency requirements, enabling organizations to reduce carbon footprints associated with HVAC energy consumption. The integration of automated filter alerts and compliance reporting tools further drives adoption among regulated sectors.
- For instance, Camfil’s Air Image Sensor platform measures PM1, PM2.5, PM10, temperature, humidity, VOC levels, and CO₂ concentration with real-time monitoring at a data refresh rate of 60 seconds, enabling precise air quality adjustments for commercial and pharmaceutical environments.
Key Challenges:
Environmental Impact of Waste Disposal and Recycling Limitations
A major challenge confronted by the pleated filter market relates to waste management and disposal. Many filters combine synthetic fibers, adhesives, plastics, and metal components that complicate recycling and increase landfill accumulation. Incineration may reduce bulk but releases toxic gases if media contain treated fibers or chemical coatings. Industries with high-frequency replacement cycles, such as food processing and pharmaceuticals, generate substantial filtration waste, raising environmental and regulatory burdens. As sustainability goals intensify, manufacturers face pressure to develop compostable housings, mono-material filters, or return-and-recycle programs-yet these require higher production costs and redesigned supply chains.
Price Pressure and Availability of Low-Cost Alternatives
The market faces competitive pressure from low-cost manufacturers offering non-branded pleated filters, particularly in regions where price outweighs performance. Fluctuations in raw material prices-especially fiberglass, polymers, and activated carbon-also influence production margins. While high-efficiency filters deliver superior performance, many end-users still prioritize upfront cost over lifecycle benefits, slowing premium segment expansion. Industrial customers may delay replacement cycles to reduce expenses, resulting in decreased recurring sales. The presence of alternative filtration technologies such as electrostatic precipitators or washable filters can influence procurement decisions, especially where operating conditions are moderate and regulatory oversight is limited.
Regional Analysis:
North America
North America holds the largest share of the pleated filters market, accounting for approximately 32%, driven by stringent indoor air quality regulations imposed by OSHA, EPA, and ASHRAE standards. The region benefits from extensive HVAC penetration in residential and commercial buildings, alongside strong adoption across pharmaceutical production, food processing, and semiconductor manufacturing. Rising replacement frequency, the expansion of cleanroom-capable facilities, and heightened consumer focus on allergy and pollutant control further support demand. The United States leads growth, supported by infrastructure modernization and investments in energy-efficient filtration for public buildings and healthcare institutions.
Europe
Europe represents around 27% of the global market, supported by robust regulatory frameworks related to emission controls, workplace safety, and green building certifications. The EU’s carbon-reduction commitments and air pollution mitigation programs are accelerating upgrades across industrial filtration systems. Germany, France, and the United Kingdom remain major demand centers due to advanced manufacturing, automotive production, and healthcare infrastructure. Aging buildings transitioning to modern HVAC systems also drive retrofitted filtration solutions. Strict food hygiene compliances and pharmaceutical production standards create sustained demand for high-efficiency pleated filters designed for sterile and contamination-controlled environments.
Asia-Pacific
Asia-Pacific accounts for approximately 29% market share and is the fastest-growing regional segment due to rapid industrialization, urban population expansion, and increasing air pollution indices in major cities. China and India dominate demand, propelled by manufacturing growth in electronics, chemicals, and heavy industries. Rising middle-class purchasing power and adoption of centralized air conditioning in commercial and residential spaces elevate filtration requirements. Government investments in hospital construction and industrial safety compliance further boost consumption. Multinational companies expanding production capacity across Southeast Asia support accelerated filtration adoption aligned with global quality standards.
Latin America
Latin America captures around 6% of the market, with Brazil and Mexico leading due to expanding industrial and food processing operations. Demand is driven by increased commercial building development, particularly in urban centers focused on modern infrastructure. The region’s improving healthcare investments, adoption of cleaner industrial practices, and awareness of airborne contaminants are gradually strengthening the market presence. However, budget sensitivity and dependency on imported filtration materials limit rapid penetration of advanced filters. Opportunities lie in mining, cement, and oil processing sectors where equipment protection and emission compliance requirements continue rising.
Middle East & Africa
The Middle East & Africa region represents approximately 6% of global market share, supported by air filtration needs in power plants, oil refineries, and desalination facilities. The Gulf region, led by Saudi Arabia and the UAE, shows increasing installation of high-performance filters in commercial complexes, airports, and healthcare networks. Harsh climatic conditions characterized by dust and sandstorms emphasize durable and frequent air filtration cycles. Industrial diversification programs, such as Saudi Vision 2030 and UAE manufacturing expansion, support long-term filtration investments. Adoption remains slower in parts of Africa due to cost barriers and limited HVAC infrastructure.
Market Segmentations:
By Product
- Air Filter
- Medium Efficiency Filter
- HEPA Filter
- Oil Filter
- Food & Beverage Filter
- Others
By Medium Material
- Activated Carbon
- Fiberglass
- Microfiber
By Application
- Food & Beverage
- Commercial
- Industrial
- Residential
- Utilities
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape:
The competitive landscape of the pleated filters market is moderately fragmented, characterized by a mix of global manufacturers and specialized regional suppliers competing on performance reliability, product customization, and pricing. Leading companies focus on expanding their portfolios with advanced filter media, including nanofiber composites and antimicrobial coatings designed for industrial, healthcare, and cleanroom environments. Strategic initiatives involve geographic expansion, OEM partnerships with HVAC system manufacturers, and solutions aligned with energy-efficiency and sustainability requirements. The market is witnessing increased investment in digital filtration monitoring and predictive maintenance tools, enabling manufacturers to differentiate through value-added services. Supply chain optimization and backward integration in media production remain key profitability levers, particularly as raw material cost fluctuations continue. Companies that offer reusable, recyclable, or bio-based filter components are gaining competitive momentum as end-users prioritize environmentally responsible filtration solutions across commercial and industrial applications.
Key Player Analysis:
- Delta Filtration
- Camfil AB
- Honeywell International Inc.
- Freudenberg and Company
- Absolent Group
- General Motors Company
- Donaldson Company, Inc.
- Atlas Copco
- Clarcor Air Filtration
- 3M Company
Recent Developments:
- In April 2025, 3M introduced a new product under its Filtrete brand: the “Filtrete Refillable Air Filter Kit”. The kit uses a reusable frame (rated to last up to 20 years) and a replaceable filter insert that lasts up to 12 months.
- In March 2025, Absolent described its new “True Downflow” dust/fume-extraction configuration, where filter elements use vertical alignment and top-to-bottom airflow so that dust released during pulse-jet cleaning is pulled downward by gravity, reducing upflow or crossflow. This design reduces required filter media surface area and enables a more compact filtration unit compared to traditional designs.
Report Coverage:
The research report offers an in-depth analysis based on Product, Medium material Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for pleated filters will continue increasing as indoor air quality and workplace safety regulations intensify across global industries.
- Nanofiber and multifunctional media will gain traction for higher filtration efficiency with low pressure drop.
- Smart, sensor-enabled filters will support predictive maintenance and reduce operational energy consumption.
- Sustainable and recyclable filter materials will emerge as a competitive differentiator among manufacturers.
- Growth in process manufacturing and cleanroom environments will boost adoption of high-performance filtration solutions.
- Construction expansion and smart building deployments will drive installation in HVAC systems.
- Customized filter designs will become more common in oil, gas, and chemical applications.
- E-commerce channels will accelerate aftermarket replacement filter sales.
- Integration with digital building management systems will influence commercial and industrial adoption.
- Asia-Pacific will surface as the fastest-growing market due to rapid industrialization and infrastructure development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Pleated Filters, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Pleated Filters market projected to grow between 2024 and 2032?
Which Pleated Filters segment held the largest share in 2024?
What are the primary factors fueling the growth of the Pleated Filters market?
Who are the leading companies in the Pleated Filters market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,083.57 million → 2032: USD 18,620.66 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pleated Filters Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pleated Filters Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pleated Filters Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pleated Filters Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pleated Filters Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pleated Filters Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pleated Filters Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pleated Filters Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,083.57 million → 2032: USD 18,620.66 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pleated Filters Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pleated Filters Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Pleated Filters Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Pleated Filters Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

