
Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Overview:
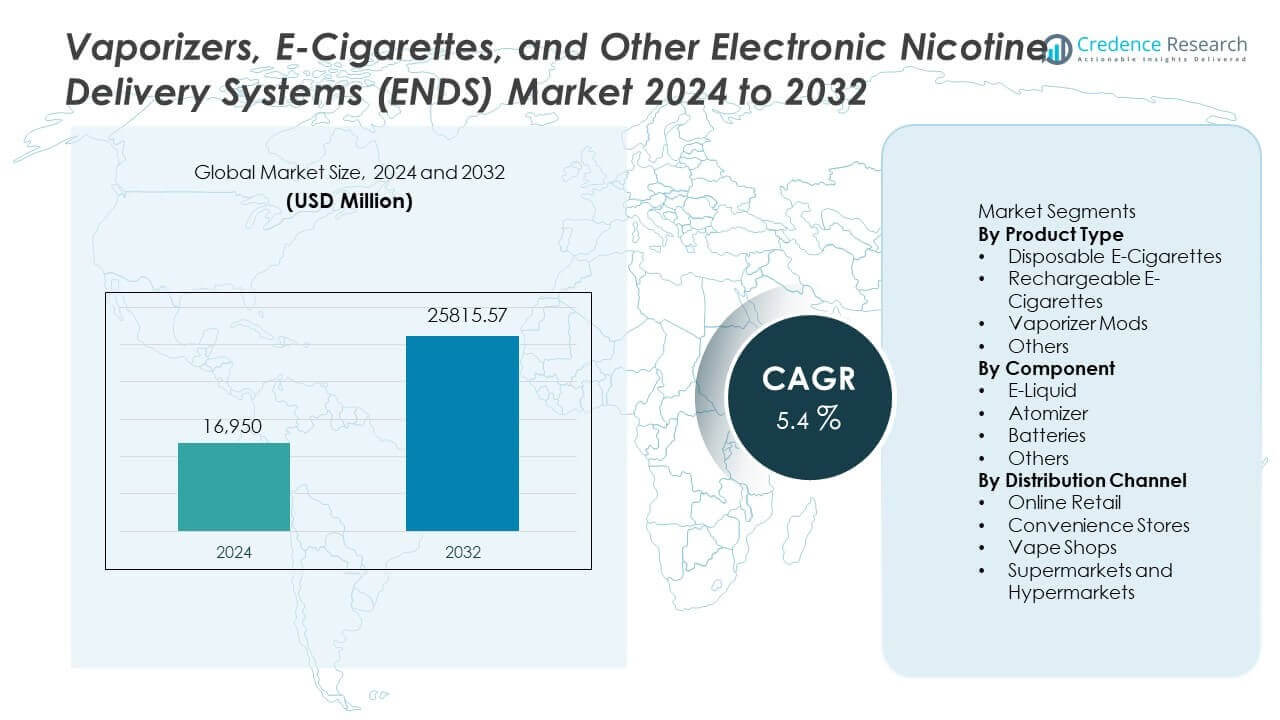
The Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) market reached USD 16,950 million in 2024. The market is projected to grow to USD 25,815.57 million by 2032, driven by a CAGR of 5.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Size 2024 | USD 16,950 million |
| Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market, CAGR | 5.4% |
| Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Size 2032 | USD 25,815.57 million |
Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Insights
- Demand rises as smokers shift toward smoke-free nicotine delivery, supported by flavour variety and compact device design. Disposable e-cigarettes lead the product segment with a 38% share.
- Key trends include wider adoption of rechargeable systems, refillable tank formats, and premium vapour output features that enhance user experience and increase long-term spending.
- Leading companies such as JUUL Labs, British American Tobacco, Philip Morris International, and RELX Technology invest in heating efficiency, flavour innovation, and online retail strategies, while regulatory constraints and safety perception challenges restrict market expansion.
- North America leads regional performance with a 37% share, followed by Europe at 32% and Asia Pacific at 22%, reflecting strong consumer awareness and expanding retail access across established and emerging markets.
Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Segmentation Analysis:
By Product Type
Disposable e-cigarettes lead the product segment with a market share of 38%, supported by strong uptake among new users seeking convenience and no-maintenance usage. This category benefits from wide flavour availability and competitive pricing, driving higher repeat purchases. Rechargeable e-cigarettes follow due to demand for customisation and longer device lifespan. Vaporizer mods serve experienced users who prefer stronger vapour output and adjustable power control. Growth across all product types reflects rising consumer interest in smoke-free alternatives, supported by expanding retail visibility and product innovation. Manufacturers continue to introduce compact designs and improved heating systems to enhance user experience.
- For instance, SMOK released the RPM 5 system with a variable wattage range of 5–80 W, enabling advanced airflow control and stronger vapour density for long-term users.
By Component
E-liquid dominates the component segment with a market share of 46%, driven by ongoing replacement demand and flavour diversity. This sub-segment remains central to consumer spending as users regularly purchase refills to maintain usage levels. Atomizers and batteries support device performance and reliability, creating recurring replacement cycles. Growth in refillable formats increases interest in nicotine salt formulations and premium e-liquid blends. Continuous flavour innovation strengthens customer loyalty and retail turnover. Producers also focus on cleaner formulations and vaping smoothness to address consumer safety expectations. Component development continues to enhance vapour output efficiency and temperature control accuracy.
- For instance, Vaporesso’s GTX coil series features mesh coil technology with a resistance range from 0.2 to 1.2 ohms, raising heating precision and atomizer durability to more than 20 refill cycles.
By Distribution Channel
Online retail holds the largest channel share at 41%, supported by strong demand for product variety, discreet delivery, and competitive pricing. Digital platforms provide broad brand access and detailed product information, improving conversion rates among both new and experienced users. Convenience stores remain an important channel for impulse purchases, while vape shops drive specialist sales and personalised guidance. Supermarkets and hypermarkets expand visibility through curated device and refill assortments. Online growth continues to accelerate, supported by fast delivery and promotional bundling. Platforms also benefit from subscription models and recurring refill orders, strengthening long-term customer retention across the ENDS category.
Key Growth Drivers
Rising Shift Toward Smoke-Free Alternatives
Consumers show growing interest in smoke-free nicotine options due to increasing awareness of the health risks linked to traditional cigarettes. ENDS products offer a cleaner inhalation experience, reduced odour, and lower perceived harm, supporting strong category adoption. Younger adults and transitioning smokers drive steady demand, while flavour options and device portability further strengthen appeal. Broader retail availability and digital purchasing platforms enhance accessibility and product visibility. Manufacturers expand device efficiency and heating performance to create more satisfying user experiences, reinforcing long-term usage. These factors continue to lift market momentum and support sustained product diversification.
- For instance, Philip Morris International reported that more than 28 million adults worldwide had switched to its smoke-free portfolio, reflecting rapid consumer migration from cigarettes to ENDS formats.
Technological Advancements in Device Design and Performance
Continuous innovation in heating mechanisms, battery life, and temperature control enhances vapour consistency and product reliability. Manufacturers invest in compact formats, improved airflow systems, and smart power regulation to raise consumer satisfaction. Refillable tanks and adjustable coils appeal to experienced users seeking customization and reduced operating costs. New-generation devices focus on safety enhancements, including automatic shut-off features and regulated wattage control. Product upgrades also strengthen user engagement and support premium line expansion. As technology evolves, consumers gain access to smoother inhalation, longer runtimes, and improved nicotine delivery efficiency, helping drive stronger category penetration.
- For instance, British American Tobacco upgraded its Vuse Go platform with a redesigned ceramic heating technology and a streamlined airflow chamber that increased vapour consistency and improved flavour density across its expanded range of blends.
Expanding Online Retail and Digital Purchase Behaviour
Digital platforms play a critical role in informing purchase decisions and improving access to device and refill options. Wide product listings, consumer reviews, and targeted promotional offers encourage strong conversion rates across demographics. Online channels also attract buyers who prefer discreet purchases and home delivery. Subscription services for e-liquids and accessories increase repeat sales and support long-term usage. Retailers leverage data-driven recommendations to personalize offerings, improving customer retention and basket size. Rising e-commerce penetration across major regions helps reduce geographic limitations, making digital retail a major revenue engine for the ENDS market.
Key Trends & Opportunities
Growth in Customizable and Premium Product Lines
Consumers increasingly choose devices with adjustable airflow, power settings, and refillable tank systems to improve flavour control and vapour volume. This trend encourages brands to expand premium product ranges targeting experienced users. Demand for higher-grade materials, compact metal housings, and enhanced battery performance creates significant revenue potential. The premium shift opens opportunities for product differentiation and stronger brand loyalty. In addition, rising interest in nicotine salt formulations and gourmet flavours supports higher spending patterns. Companies that focus on advanced engineering and design precision stand to benefit most from expanding customisation demand.
- For instance, Geekvape introduced a corrosion-resistant zinc alloy housing and a 3,000 mAh lithium-ion battery unit, increasing continuous vaping time by more than 400 puffs per full charge cycle.
Rising Focus on Regulatory-Aligned and Safety-Centric Innovation
Manufacturers explore compliance-driven product development to meet evolving regulatory standards and strengthen consumer trust. The opportunity lies in improving product traceability, ingredient transparency, and emissions control. Brands focus on child-resistant packaging, leak-proof tank structures, and safer heating elements to minimise risk. These safety-led enhancements support acceptance among health-conscious users and regulatory bodies. As markets mature, companies that align closely with compliance and testing requirements gain competitive advantage. Long-term opportunities emerge for refined product certifications, responsible nicotine delivery, and structured product labelling.
- For instance, Altria’s device platform achieved emissions testing performance that reduced carbonyl levels by up to 97 mg per 100 puffs compared with conventional smoking emissions.
Key Challenges
Stringent and Evolving Regulatory Restrictions
Frequent policy changes introduce uncertainty for product approvals, marketing activity, and distribution frameworks. Restrictions on flavours, nicotine levels, and sales channels limit product variety and affect demand among adult users. Companies face rising compliance costs due to mandatory testing, emissions evaluation, and documentation requirements. Advertising and promotional limitations reduce brand visibility and slow customer acquisition efforts. Varying rules across global regions further complicate product expansion strategies. As regulatory standards continue to tighten, manufacturers must navigate complex compliance pathways to preserve market presence.
Ongoing Concerns Over Health Risks and Safety Perception
Negative public sentiment tied to vaping-related incidents and health concerns influences purchasing decisions. Misconceptions around long-term effects discourage new adoption and limit category trust. Reports of device malfunctions and counterfeit products raise additional safety concerns. These factors create caution among retailers, healthcare professionals, and end users. Brands must address these challenges through transparent communication, quality control, and product validation. Strong focus on safety assurance and consumer education is essential to counter reputational risk and strengthen market stability.
Regional Analysis
North America
North America leads the Vaporizers, E-Cigarettes, and ENDS market with a market share of 37%, supported by strong consumer awareness, widespread retail access, and rapid adoption among adult smokers transitioning from conventional cigarettes. The United States drives regional performance through active product innovation and competitive brand presence. Expanding e-commerce platforms improve device availability and refill accessibility. Regulatory developments remain influential, shaping product standards and distribution controls. Canada contributes to market growth with rising demand for premium and reusable systems. Strong investment in research, flavour development, and advanced heating technology continues to strengthen North America’s leadership position.
Europe
Europe holds a market share of 32%, driven by growing preference for smoke-free nicotine delivery and regulations that support controlled product quality. The United Kingdom, France, and Germany form key markets with strong retail penetration, varied flavour offerings, and demand for rechargeable devices. Public health messaging supports category acceptance among smokers seeking reduced-risk alternatives. Regulatory clarity improves consumer confidence and encourages product innovation. Growth in refillable systems and advanced mod formats increases revenue potential. Strong manufacturing presence, distribution structure, and cross-border trading further reinforce Europe’s competitive standing in the ENDS market.
Asia Pacific
Asia Pacific accounts for a market share of 22%, supported by increasing awareness, urban lifestyle influence, and growing interest in vapour-based nicotine consumption. China leads device manufacturing and exports, driving technological progress and product affordability. Japan and South Korea show strong uptake of compact and high-performance devices. Expanding online sales channels and modern retail formats strengthen category visibility. Younger demographics and shifting lifestyle preferences enhance market momentum. Ongoing product development, improved safety features, and flavour innovation tailored to regional taste profiles continue to boost ENDS demand across Asia Pacific.
Latin America and Middle East & Africa
Latin America and Middle East & Africa collectively hold a market share of 9%, driven by rising consumer awareness, expanding retail networks, and growing acceptance of reduced-risk nicotine formats. Key growth markets include Brazil, Mexico, the UAE, and South Africa, where younger users drive online purchasing and flavour adoption. Regulatory diversity affects product flow and availability across both regions. Device imports, specialist vape stores, and digital retailing improve product access. Although adoption levels remain lower than major regions, rising affordability, urban growth, and increasing brand entry support long-term expansion prospects for the ENDS category.
Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Segmentations:
By Product Type
- Disposable E-Cigarettes
- Rechargeable E-Cigarettes
- Vaporizer Mods
- Others
By Component
- E-Liquid
- Atomizer
- Batteries
- Others
By Distribution Channel
- Online Retail
- Convenience Stores
- Vape Shops
- Supermarkets and Hypermarkets
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the Vaporizers, E-Cigarettes, and ENDS market features leading players such as JUUL Labs, British American Tobacco, Philip Morris International, Japan Tobacco, Imperial Brands, and RELX Technology. These companies focus on product innovation, expanded flavour portfolios, and advanced heating systems to strengthen brand positioning. Strong emphasis on rechargeable and compact device formats supports higher adoption among adult users, while growing investment in nicotine salt formulations enhances product performance and satisfaction. Companies also leverage online sales networks and subscription-based refill services to drive recurring revenue. Regulatory compliance remains central, prompting manufacturers to improve product traceability, emissions control, and packaging safety. New entrants from Asia, including SMOK, Innokin, and KangerTech, intensify competition through cost-effective, feature-rich devices targeting value-driven consumers. Strategic partnerships, distribution expansion, and premium product development continue to shape long-term competitiveness in the global ENDS market.
Key Player Analysis
- JUUL Labs Inc.
- British American Tobacco plc
- Philip Morris International Inc.
- Japan Tobacco Inc.
- Imperial Brands plc
- RELX Technology
- Altria Group Inc.
- Shenzhen IVPS Technology Co. Ltd. (SMOK)
- Shenzhen Kanger Technology Co. Ltd.
- Shenzhen Innokin Technology Co. Ltd.
Recent Developments
- In September 2025, RELX Technology secured a UK distribution deal for its MaxGo pod system devices, with first shipments arriving that month.
- In July 2025, JUUL Labs Inc. received U.S. FDA authorization to continue selling tobacco and menthol flavored e-cigarettes for adult smokers, easing earlier restrictions.
- In March 2025, Philip Morris International Inc. expanded U.S. sales of its IQOS heated tobacco device in Austin, Texas as part of smoke-free product growth.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Component, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as more adult smokers shift to smoke-free nicotine options.
- Product innovation will focus on improved heating systems, airflow control, and longer battery life.
- Rechargeable and refillable devices will gain traction due to lower long-term cost and better performance.
- Online retail channels will expand, supported by subscription refills and personalised buying journeys.
- Regulatory clarity will encourage safer product designs and strengthen consumer confidence.
- Premium flavour development and nicotine salt adoption will enhance user satisfaction and retention.
- Emerging markets will show stronger adoption as awareness and affordability improve.
- Sustainability in materials and packaging will shape future device and component development.
- Competitive activity will increase as low-cost manufacturers enter advanced device categories.
- Advances in device testing, emissions analysis, and safety validation will support long-term market stability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Smoke-Free Alternatives
Increasing awareness of the health risks associated with traditional cigarettes is driving consumers to adopt ENDS products, which offer a cleaner inhalation experience, reduced odor, and lower perceived harm. This shift is particularly strong among younger adults and transitioning smokers, fueling steady market growth.
Technological Advancements in Device Design
Continuous innovation in heating mechanisms, battery life, and temperature control is enhancing product reliability and user satisfaction. Features such as adjustable airflow, refillable tanks, and smart power regulation are attracting both new and experienced users, supporting higher adoption rates.
Expanding Online Retail and Digital Purchase Behavior
The growth of digital platforms is making ENDS products more accessible, offering wide product variety, discreet delivery, and competitive pricing. Online channels also enable subscription models for e-liquids and accessories, increasing repeat sales and customer retention.
Flavour Diversity and Premiumization
A broad range of flavours and the introduction of premium product lines with customizable features are appealing to consumers seeking personalized experiences. This trend is driving higher spending patterns and encouraging brand loyalty, especially among experienced users.
Regulatory Clarity and Safety Innovations
As regulatory frameworks mature, manufacturers are focusing on compliance-driven product development, including safer heating elements, child-resistant packaging, and emissions control. These efforts are improving consumer trust and supporting long-term market stability.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) market projected to grow between 2024 and 2032?
Which Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) market?
Who are the leading companies in the Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) market?
Which region commanded the largest share of the Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 E-Liquid
- 1.2.2 Atomizer
- 1.2.3 Batteries
- 1.2.4 Others
- 1.3 By Product Type
- 1.3.1 Disposable E-Cigarettes
- 1.3.2 Rechargeable E-Cigarettes
- 1.3.3 Vaporizer Mods
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 16,950 million → 2032: USD 25,815.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 16,950 million → 2032: USD 25,815.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 E-Liquid
- 12.3.7.2 Atomizer
- 12.3.7.3 Batteries
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Disposable E-Cigarettes
- 12.4.7.2 Rechargeable E-Cigarettes
- 12.4.7.3 Vaporizer Mods
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Vaporizers, E-Cigarettes, and Other Electronic Nicotine Delivery Systems (ENDS) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 JUUL Labs Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 British American Tobacco plc
- 17.4 Philip Morris International Inc.
- 17.5 Japan Tobacco Inc.
- 17.6 Imperial Brands plc
- 17.7 RELX Technology
- 17.8 Altria Group Inc.
- 17.9 Shenzhen IVPS Technology Co. Ltd. (SMOK)
- 17.10 Shenzhen Kanger Technology Co. Ltd.
- 17.11 Shenzhen Innokin Technology Co. Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

