
Market Overview:
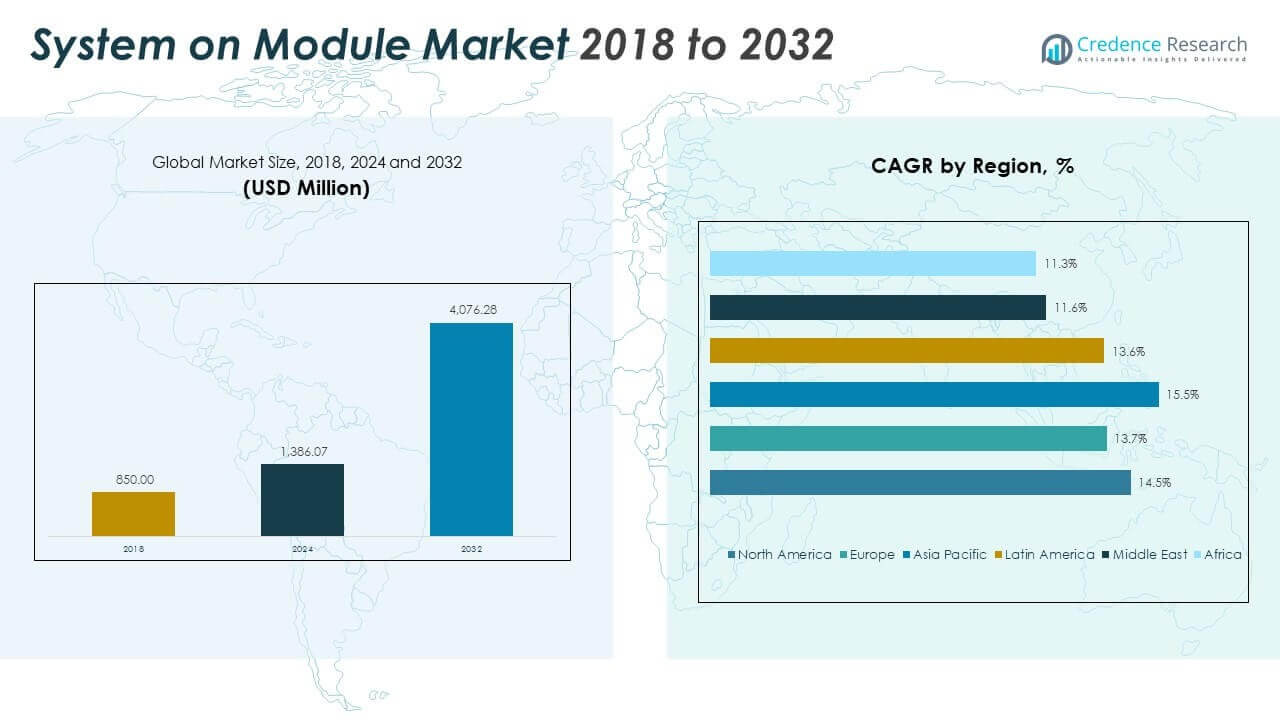
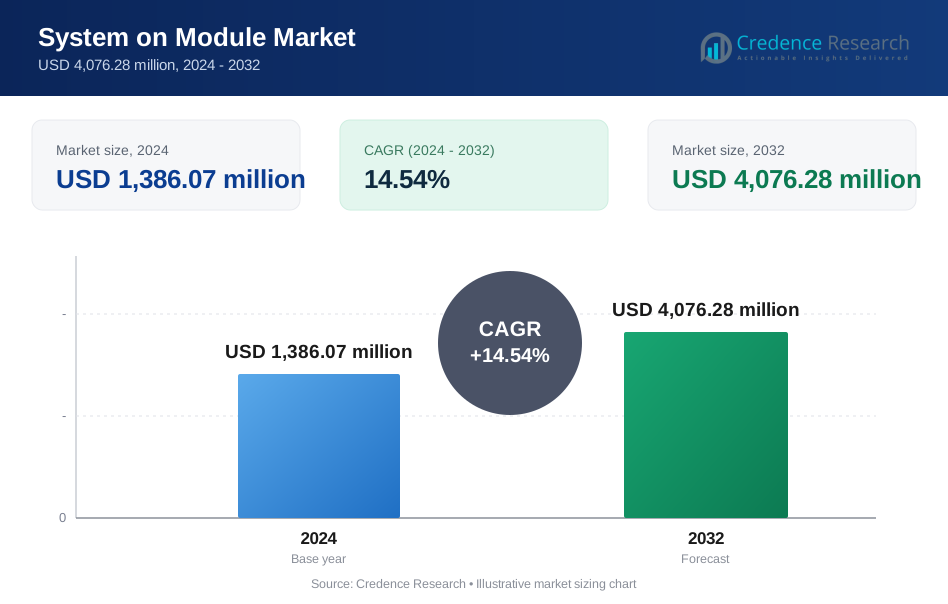
The System on Module Market size was valued at USD 850.00 million in 2018 to USD 1,386.07 million in 2024 and is anticipated to reach USD 4,076.28 million by 2032, at a CAGR of 14.54% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| System on Module (SoM) Market Size 2024 | USD 1,386.07 Million |
| System on Module (SoM) Market , CAGR | 14.54% |
| System on Module (SoM) Market Size 2032 | USD 4,076.28 Million |
Rising demand for compact, power-efficient computing solutions across various embedded applications is fueling market growth. SoMs enable faster time-to-market, lower R&D costs, and ease of integration, making them ideal for industrial automation, robotics, healthcare devices, and automotive systems. The growing adoption of edge computing and AI-based systems further boosts demand. SoMs offer scalability and reliability, meeting the design needs of modern embedded solutions. These modules help OEMs manage complexity, shorten development cycles, and enhance flexibility. Use cases continue expanding in sectors requiring long-term deployment and rugged operation. Innovation in processor technologies also contributes to the market's momentum.
Asia Pacific leads the System on Module Market due to its dominant electronics manufacturing base and rapid industrial digitization. Countries like China, Japan, South Korea, and Taiwan drive high-volume adoption in embedded applications. North America holds strong due to early technology integration in medical, defense, and industrial sectors. Europe follows with robust automotive and automation adoption. Emerging markets such as India and Southeast Asia are gaining traction due to smart city initiatives and IoT deployment. The regional spread reflects both mature and evolving use cases across industries, supporting global growth.
Market Insights:
- The System on Module Market was valued at USD 850.00 million in 2018, reached USD 1,386.07 million in 2024, and is projected to grow to USD 4,076.28 million by 2032 at a CAGR of 14.54%.
- Asia Pacific held the largest market share in 2024, accounting for 1%, driven by robust electronics manufacturing in China, Japan, South Korea, and Taiwan. North America followed with 27.3%, and Europe with 24.3%, both benefiting from industrial automation and automotive innovation.
- Asia Pacific is the fastest-growing region with a 5% CAGR, supported by expanding semiconductor hubs, digital transformation initiatives, and rising demand for edge AI and IoT applications.
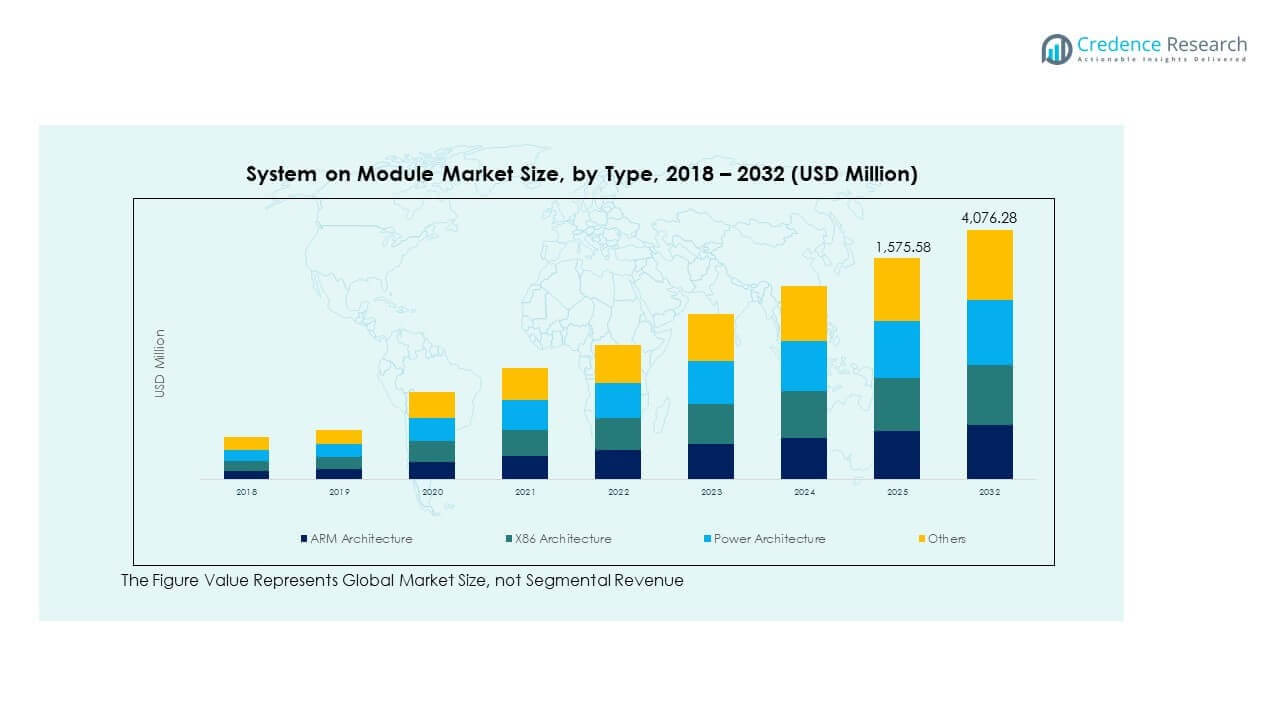
- By type, ARM Architecture led the System on Module Market in 2024 with approximately 32–34% share, favored for its power efficiency and wide adoption across mobile and embedded applications.
- X86 Architecture held around 25–27% share, driven by industrial control and legacy systems, while Power Architecture captured 18–20%, serving specialized needs in defense and networking systems.
Market Drivers
Surging Demand for Compact, Power-Efficient Embedded Computing in Industrial Automation
Growing demand for embedded systems in industrial automation strengthens the System on Module Market. Companies adopt SoMs to reduce product development time and cost while improving system performance. Factories deploy SoMs in robotics, motion control, and predictive maintenance systems. These modules support multi-core processing and real-time operations. Their compact footprint fits well in space-constrained devices. Power efficiency is a major advantage in harsh industrial environments. OEMs value SoMs for seamless integration with sensors and actuators. It creates scalable solutions for future factory expansions.
- For compact, power-efficient SoMs in industrial automation, Compulab's UCM-iMX95 based on NXP i.MX 95 offers 6x ARM Cortex-A55 cores at up to 2.0 GHz with real-time Cortex-M7/M33 support for robotics and motion control.
Rising Use of SoMs in Healthcare Devices and Portable Medical Equipment
Portable diagnostic tools and patient monitoring systems increasingly adopt System on Module platforms. These modules enable low-latency processing, compact design, and remote connectivity. Hospitals use SoM-based solutions in imaging, infusion pumps, and ECG systems. Medical device OEMs seek faster regulatory approvals with proven SoM platforms. It reduces design risks and enhances product reliability. Healthcare providers demand secure, power-efficient computing for continuous operation. Growing telehealth and homecare services boost adoption further. The market gains momentum through digitization of clinical operations.
Increasing Integration of SoMs in Automotive Applications and ADAS Platforms
Automotive companies deploy SoMs in infotainment, telematics, and ADAS. These platforms support high-speed computing, real-time data fusion, and sensor integration. It allows automakers to shorten design cycles and introduce advanced features quickly. SoMs meet the stringent power and thermal needs of vehicle systems. OEMs rely on rugged modules certified for automotive-grade performance. The rise of EVs and autonomous driving accelerates demand for embedded solutions. SoMs provide the flexibility needed for future vehicle architectures. Compliance with functional safety standards boosts their adoption.
- For automotive SoMs in ADAS and EVs, NXP i.MX 952 provides 4x Cortex-A55 cores, eIQ Neutron NPU, and ASIL-B compliance under ISO 26262 for real-time sensor fusion in driver monitoring systems.
Growing Adoption of AI and Machine Vision Accelerates SoM Integration Across Sectors
AI workloads and machine vision are penetrating multiple industries, supporting new use cases for SoMs. These modules integrate GPUs or NPUs to process image, video, and sensor data in real time. Use cases span from quality inspection in factories to facial recognition in smart cities. It enhances the performance of edge AI applications. SoMs with pre-validated AI frameworks speed up deployment. Developers leverage them to reduce AI inferencing latency at the edge. Smart retail, security, and logistics adopt SoMs for next-gen analytics. Demand grows for customizable SoMs with AI-ready toolkits.
Market Trends
Increased Focus on Edge AI Computing and Decentralized Processing Architectures
The shift from centralized cloud computing to edge processing shapes the System on Module Market. SoMs are used in smart cameras, factory floor controllers, and drones. These modules support AI inferencing directly at the edge. It enables real-time decision-making and reduces cloud dependency. Developers integrate SoMs in vision-guided robotics, smart kiosks, and autonomous systems. Market players bundle AI toolchains for seamless development. This trend strengthens SoM utility in latency-sensitive environments. Security and bandwidth efficiency drive further growth in edge deployments.
- For example, Digi International's ConnectCore MP25 SoM is fully verified for edge AI, featuring an STM32MP25 processor with a 1.35 TOPS NPU for real-time inferencing in computer vision applications.
Emergence of Custom SoMs for Application-Specific Demands in Niche Industries
Vendors are offering tailored SoMs for specific industry needs like aerospace, defense, and railways. These customized platforms offer specialized interfaces, rugged form factors, and extended lifecycle support. It helps OEMs meet stringent compliance and reliability requirements. Custom SoMs also address constraints in temperature, vibration, or power. This trend improves customer retention through dedicated engineering support. Long-term supply agreements become common in critical sectors. It pushes manufacturers to invest in modular designs. System on Module Market players expand design libraries to meet niche specifications.
Rapid Development of 5G-Enabled SoMs for High-Bandwidth, Low-Latency Use Cases
The rollout of 5G networks creates demand for SoMs that support high-speed communication. These modules are used in mobile base stations, edge gateways, and connected vehicles. 5G-enabled SoMs handle faster data exchange and remote device coordination. It supports growth in smart cities, autonomous drones, and AR/VR. Developers benefit from higher throughput and network slicing support. SoMs built for 5G integrate RF, antenna, and protocol stack components. This trend promotes innovation across smart mobility and public safety infrastructure. It reinforces SoM relevance in connected ecosystems.
- For example, Quectel's RM510Q-GL 5G SoM achieves verified peak downlink speeds of 4.5 Gbps and uplink of 2.9 Gbps in sub-6 GHz and mmWave modes for high-bandwidth edge gateways and vehicles.
Shift Toward Open Standards and Interoperable SoMs Across Hardware Platforms
Standardization improves design portability and shortens time-to-market. Vendors promote open standards such as SMARC, Qseven, and COM Express. These standards allow faster evaluation and deployment of SoMs across hardware generations. It reduces risk for OEMs during upgrades or platform transitions. Open-source tools support faster software development cycles. Interoperability between SoMs and carrier boards improves flexibility. This trend aligns with growing demand for modular, future-ready electronics. It encourages vendor-neutral ecosystems, increasing SoM market competition.
Market Challenges Analysis
Design Complexity, Interface Compatibility, and Integration Risks Slow SoM Adoption in Traditional Systems
The System on Module Market faces technical challenges in legacy system integration. Many traditional OEMs operate proprietary architectures and closed-loop designs. Integrating SoMs requires skilled engineering to manage interface mismatches. Compatibility issues between carrier boards and modules delay development. Limited documentation from vendors affects project timelines. It raises total cost of ownership when debugging or testing fails. High reliance on software customization further complicates the integration. Smaller OEMs lack in-house capabilities to manage these risks. This barrier slows SoM penetration in conservative markets.
Concerns Over Long-Term Support, Supply Chain Reliability, and Vendor Lock-In Restrict Broader Adoption
Companies fear obsolescence and platform discontinuity in long-lifecycle applications. Shorter product cycles from SoM vendors raise concerns over long-term support. It impacts critical sectors like industrial automation and medical devices. Geopolitical disruptions and component shortages increase supply chain risks. Enterprises seek vendor-agnostic solutions to avoid lock-in. Multi-sourcing becomes difficult due to custom firmware or drivers. Certification and compliance needs increase cost and delay. These factors pressure manufacturers to offer transparent roadmaps and extended support guarantees.
Market Opportunities
Expansion of AIoT and Smart Infrastructure Projects Creates Strong Growth Potential for SoM Vendors
Government and enterprise investment in smart infrastructure supports market expansion. SoMs offer compact, high-performance computing for edge applications. Projects in smart energy, surveillance, and public transportation use SoMs for control and data processing. It positions SoM providers as key enablers of next-gen urban systems. AIoT-driven infrastructure requires real-time decision-making at the edge. SoMs meet this demand through efficient integration of processing and connectivity in a single module. Vendors focus on offering rugged, low-power modules for harsh environments. Public-private partnerships in digital infrastructure enhance deployment speed and scale.
Growing Demand from Startups and Makers Accelerates Low-Cost SoM Segment Growth
Startups use off-the-shelf SoMs to accelerate prototyping and reduce product launch costs. It encourages innovation in wearables, robotics, and consumer IoT. Community support and development kits improve accessibility, driving broader market entry. Makers benefit from access to modular tools and low-code environments. This trend fosters rapid experimentation and faster MVP development. Open-source ecosystems built around SoMs further fuel innovation. Educational institutions and research labs also adopt entry-level SoMs for project-based learning. It drives a steady wave of future engineers and developers into the ecosystem.
Market Segmentation Analysis:
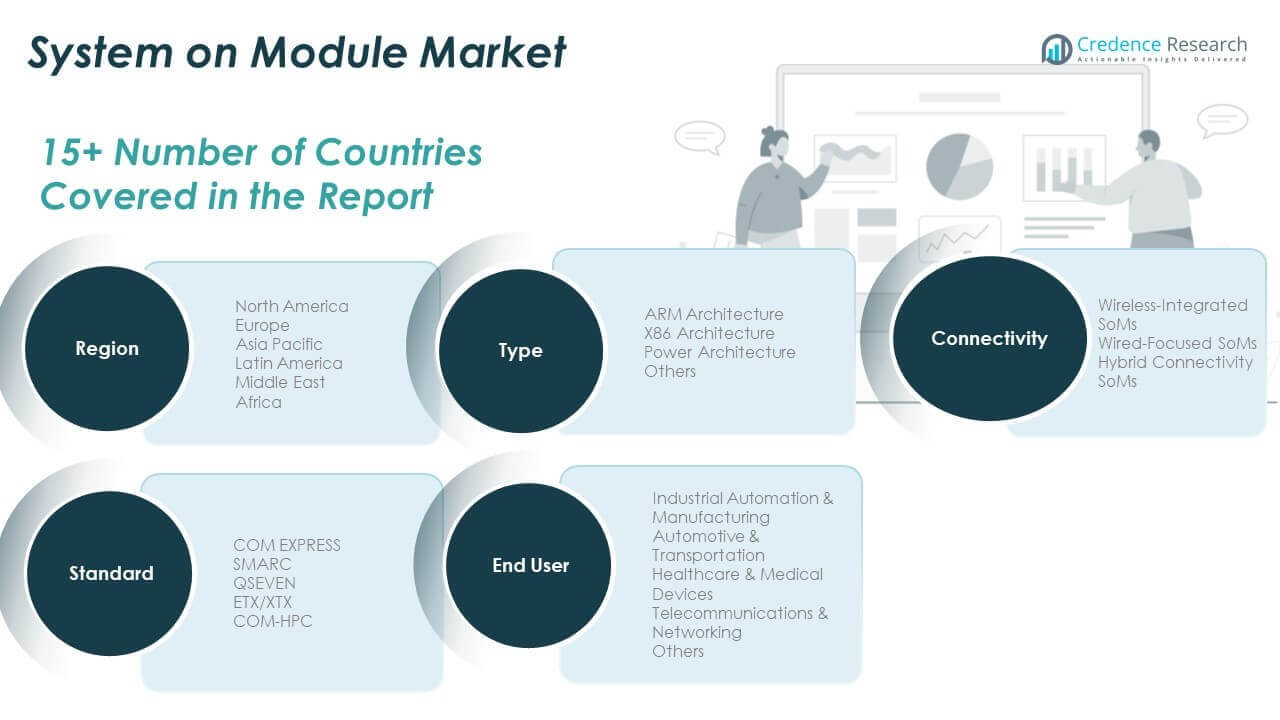
The System on Module Market is segmented by type, connectivity, standard, and end user, each shaping demand dynamics.
By type, ARM architecture leads due to its power efficiency and widespread use in mobile and embedded systems. X86 architecture holds relevance in industrial PCs and legacy systems, while Power architecture serves specialized applications in aerospace and defense.
- For example, NXP Semiconductors' i.MX 8M Plus ARM-based SoM delivers 2.3 TOPS NPU performance for edge AI at under 3W power draw, confirmed across multiple datasheets and module implementations.
By connectivity, wireless-integrated SoMs dominate due to the growing need for mobile, remote, and IoT applications. Wired-focused SoMs support applications requiring stable high-bandwidth connections in fixed environments. Hybrid connectivity SoMs are gaining traction where flexible integration is essential across multiple communication layers.
- For instance, Toradex's Verdin iMX8M Plus SoM integrates dual-band 802.11ac Wi-Fi with 2x2 MU-MIMO support, delivering reliable wireless performance for industrial embedded applications. It features a compact 70×50 mm footprint and supports Bluetooth 5 alongside Wi-Fi connectivity.
By standard, COM Express holds a leading position with widespread industry acceptance in embedded computing. SMARC and Qseven offer compact, low-power options suited for space-constrained devices. ETX/XTX and Standard 5 continue to serve legacy applications with proven stability and compatibility.
By end user, industrial automation and manufacturing remain the largest segment, adopting SoMs in robotics, PLCs, and motion control systems. Automotive and transportation sectors leverage SoMs for infotainment, telematics, and ADAS. Healthcare and medical devices deploy them in diagnostics and portable monitoring. End User 4 captures niche or emerging use cases under early-stage commercialization.
Segmentation:
By Type
- ARM Architecture
- X86 Architecture
- Power Architecture
By Connectivity
- Wireless-Integrated SoMs
- Wired-Focused SoMs
- Hybrid Connectivity SoMs
By Standard
- COM Express
- SMARC
- Qseven
- ETX / XTX
- Standard 5
By End User
- Industrial Automation & Manufacturing
- Automotive & Transportation
- Healthcare & Medical Devices
- End User 4
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America System on Module Market size was valued at USD 236.30 million in 2018 to USD 379.22 million in 2024 and is anticipated to reach USD 1,113.24 million by 2032, at a CAGR of 14.5% during the forecast period. North America held approximately 27.3% of the global market share in 2024. The region benefits from advanced adoption in industrial automation, medical electronics, and defense systems. Companies leverage SoMs in robotics, aerospace control units, and diagnostic devices. High R&D spending and a strong embedded systems ecosystem support long-term growth. The U.S. leads in deploying rugged and high-performance SoMs across industrial sectors. Healthcare firms adopt modules in portable devices and real-time monitoring tools. Semiconductor companies based in the region actively develop custom SoM platforms. It continues to gain momentum due to demand for modular computing in edge AI and secure connectivity applications.
Europe
The Europe System on Module Market size was valued at USD 215.22 million in 2018 to USD 336.78 million in 2024 and is anticipated to reach USD 933.27 million by 2032, at a CAGR of 13.7% during the forecast period. Europe accounted for nearly 24.3% of the market share in 2024. The region shows strong growth due to demand from automotive, industrial control, and transportation sectors. Germany, France, and the UK lead in smart factory initiatives using embedded computing modules. SoMs are widely adopted in railway safety systems, automotive infotainment, and process automation. Manufacturers prioritize energy efficiency and scalable architecture in compliance-heavy industries. European vendors also drive innovation in open-standard SoMs. The region benefits from active collaboration between OEMs and embedded computing firms. It remains a key market for customized SoMs used in mission-critical industrial applications.
Asia Pacific
The Asia Pacific System on Module Market size was valued at USD 305.83 million in 2018 to USD 513.74 million in 2024 and is anticipated to reach USD 1,618.69 million by 2032, at a CAGR of 15.5% during the forecast period. Asia Pacific captured the largest market share at 37.1% in 2024. The region leads in electronics manufacturing and rapid deployment of embedded systems across consumer and industrial sectors. China, Japan, South Korea, and Taiwan dominate due to their strong semiconductor base. SoMs are used in robotics, EVs, IoT devices, and surveillance systems. India and Southeast Asia show fast adoption driven by smart city projects and digital transformation. Local startups and OEMs increasingly use off-the-shelf SoMs for product acceleration. Regional governments support technology exports and electronics R&D. It stands out as the most dynamic region for volume growth and product diversification.
Latin America
The Latin America System on Module Market size was valued at USD 61.20 million in 2018 to USD 98.95 million in 2024 and is anticipated to reach USD 272.58 million by 2032, at a CAGR of 13.6% during the forecast period. Latin America held a market share of 7.2% in 2024. The region sees growing use of SoMs in industrial automation, mining, and oil and gas control systems. Brazil and Mexico lead adoption due to rising local manufacturing and integration of IIoT technologies. Demand grows for wireless and hybrid SoMs to support remote infrastructure monitoring. Healthcare and smart agriculture applications also drive interest. Budget-conscious OEMs opt for flexible SoMs with ready development tools. Regional challenges such as logistics and import dependency slow down growth slightly. It offers steady opportunities in mid-tier embedded systems and rugged deployments.
Middle East
The Middle East System on Module Market size was valued at USD 17.85 million in 2018 to USD 25.77 million in 2024 and is anticipated to reach USD 61.57 million by 2032, at a CAGR of 11.6% during the forecast period. The region represented around 1.9% of the market share in 2024. Market expansion is supported by investments in defense, oilfield automation, and smart infrastructure. UAE and Saudi Arabia lead demand for AI-powered embedded modules in surveillance, mobility, and energy systems. Government programs in digital transformation encourage adoption of modular embedded platforms. Industrial sectors integrate SoMs for predictive maintenance and equipment control. Demand for wireless SoMs grows with deployment of 5G and edge analytics. Regional players increasingly collaborate with global module vendors. It remains a niche yet strategic growth zone for high-performance SoMs.
Africa
The Africa System on Module Market size was valued at USD 13.60 million in 2018 to USD 31.61 million in 2024 and is anticipated to reach USD 76.92 million by 2032, at a CAGR of 11.3% during the forecast period. Africa held about 2.3% of the global market share in 2024. The region is in early adoption stages, with growth led by South Africa, Nigeria, and Egypt. SoMs are used in telecom, power management, and public health systems. Local integrators use entry-level modules for low-cost, scalable IoT deployments. Agricultural monitoring and off-grid automation applications are expanding. Educational institutions contribute by training engineers in embedded platforms. Import reliance and limited design infrastructure remain key challenges. It presents future potential as digital infrastructure and smart solutions grow.
Key Player Analysis:
- Avalue Technology
- Renesas Electronics
- iWave Systems
- Tessolve
Competitive Analysis:
The System on Module Market features a mix of global and regional players competing through product innovation, scalability, and design flexibility. Leading companies focus on offering customizable, power-efficient SoMs with long lifecycle support and strong development ecosystems. Key players such as Avalue Technology, Renesas Electronics, iWave Systems, and Tessolve maintain strong engineering capabilities and diverse product portfolios. It remains highly competitive with constant upgrades in connectivity, processing speed, and thermal efficiency. Vendors invest in partnerships with OEMs to support application-specific needs across industrial, medical, and automotive sectors. Emerging companies target the low-cost segment with off-the-shelf modules and open-source support. Established firms maintain leadership through compliance-ready modules and extended supply chain networks. It continues to evolve with growing demand for AI-ready, compact modules that meet global standards. Competitive differentiation depends on performance benchmarks, customer service, and integration flexibility across various hardware platforms.
Recent Developments:
- In December 2025, iWave Systems introduced the iG-RainboW-G69M, an OSM Size-S System on Module based on TI AM62L for low-power IoT and HMI, paired with a Raspberry Pi-sized carrier board in the System on Module market.
- In September 2025, Avalue Technology rolled out three new Open Standard Modules (OSMs) OSM-IMX93, OSM-RK3568, and OSM-RK3566 for smarter, greener IoT devices in the System on Module market, emphasizing compact sizing, energy efficiency, and rugged reliability for industrial automation and robotics.
Report Coverage:
The research report offers an in-depth analysis based on type, connectivity, standard, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market advances through wider adoption of modular computing in industrial automation, robotics, and factory digitalization programs.
- Edge AI use cases expand, driving demand for compact modules with integrated accelerators and real-time processing capability.
- Automotive electronics adopt scalable SoMs to support infotainment, telematics, and driver assistance platforms.
- Healthcare device makers rely on certified SoMs to shorten development cycles and reduce regulatory complexity.
- Open standards strengthen interoperability and lower switching barriers across hardware generations.
- Wireless and hybrid connectivity gain traction with smart infrastructure and distributed IoT deployments.
- Asia Pacific manufacturing scale improves availability and shortens global supply timelines.
- Startups and system integrators accelerate innovation using ready-to-deploy module platforms.
- Vendor focus shifts toward long lifecycle support and application-specific customization.
- Sustainability goals encourage power-efficient designs and compact system footprints across deployments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for System on Module Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the System on Module Market projected to grow between 2024 and 2032?
Which System on Module Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the System on Module Market?
Who are the leading companies in the System on Module Market?
Which region commanded the largest share of the System on Module Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 System on Module Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global System on Module Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,386.07 million → 2032: USD 4,076.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 System on Module Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. System on Module Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 System on Module Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 System on Module Market Drivers
- 3.3 System on Module Market Restraints & Challenges
- 3.4 System on Module Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 System on Module Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 System on Module Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, System on Module category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 System on Module Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. System on Module Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the System on Module market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 System on Module Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 System on Module Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 System on Module Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in System on Module (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New System on Module Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global System on Module Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America System on Module Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe System on Module Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific System on Module Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America System on Module Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East System on Module Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa System on Module Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. System on Module Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
