
Market Overview:
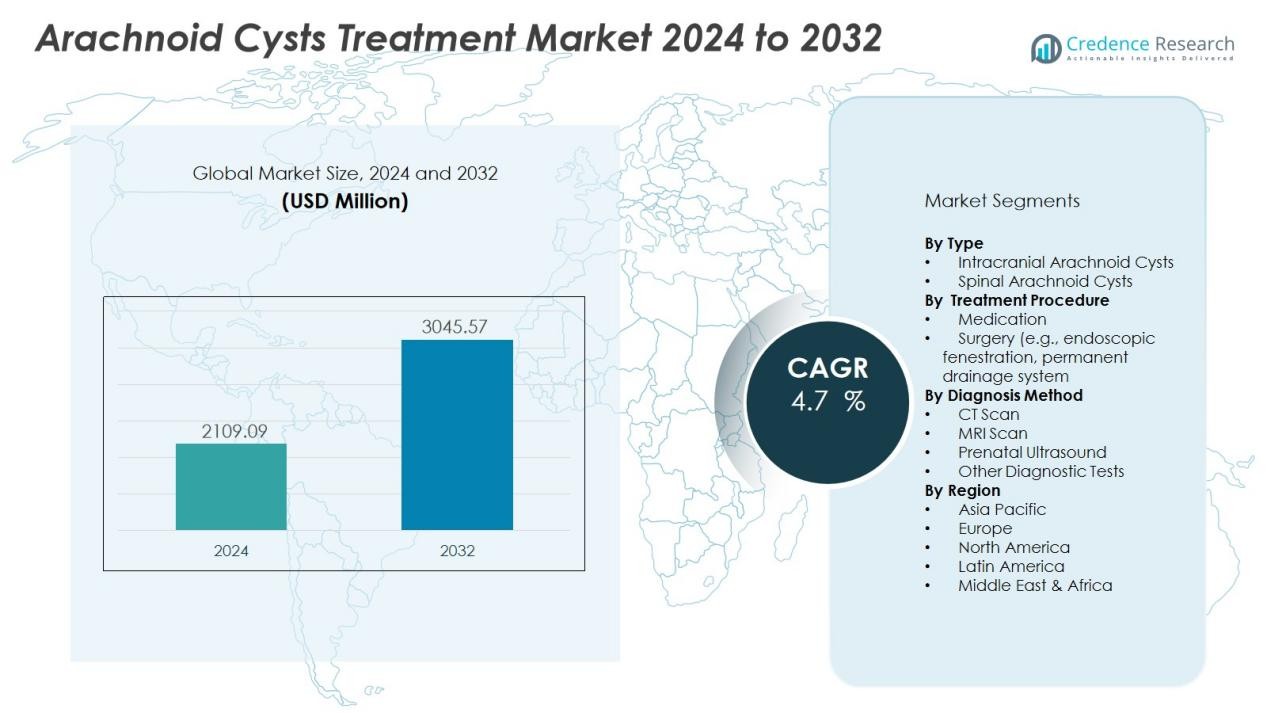
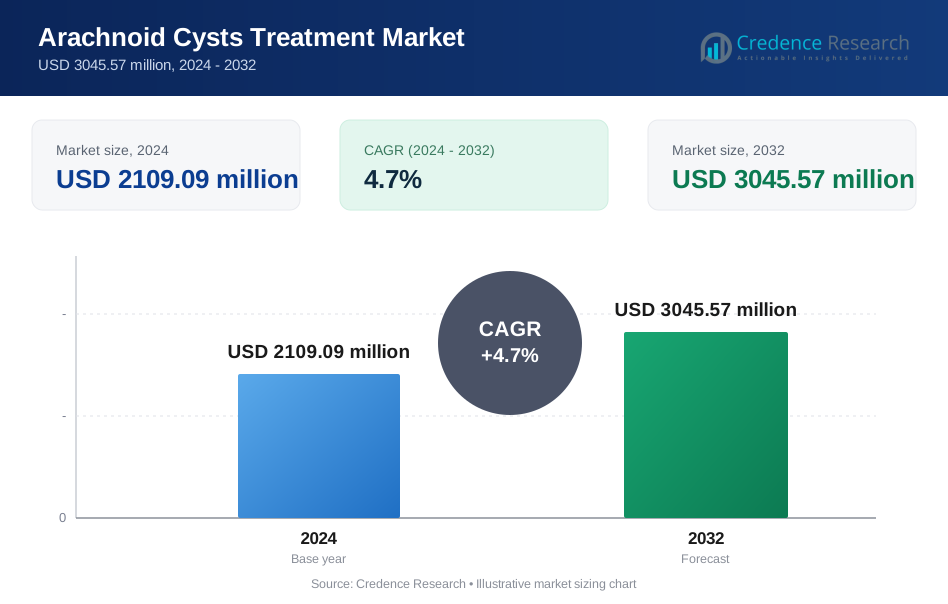
The Arachnoid Cysts Treatment Market size was valued at USD 2109.09 million in 2024 and is anticipated to reach USD 3045.57 million by 2032, at a CAGR of 4.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Arachnoid Cysts Treatment Market Size 2024 | USD 2109.09 Million |
| Arachnoid Cysts Treatment Market, CAGR | 4.7% |
| Arachnoid Cysts Treatment Market Size 2032 | USD 3045.57 Million |
Growth in this market is primarily driven by the increasing prevalence of diagnosed arachnoid cysts, greater awareness among clinicians and patients, and improvements in neuro‑imaging diagnostics such as MRI and CT scanning. In addition, the shift toward minimally invasive neurosurgical procedures and advanced device technologies is boosting uptake of treatment options globally.
Regionally, North America maintains a dominant share — approximately 43% of market revenues in 2024 — supported by advanced healthcare infrastructure and high medical spending. Meanwhile, the Asia‑Pacific region is expected to record the fastest growth, driven by rising healthcare investment, expanding neuro‑imaging capacity, and increasing access in emerging markets such as China and India.
Market Insights:
- The Arachnoid Cysts Treatment Market was valued at USD 2109.09 million in 2024 and is projected to reach USD 3045.57 million by 2032, growing at a CAGR of 4.7%.
- North America holds the largest market share at 43%, driven by advanced healthcare infrastructure, high medical spending, and widespread neuroimaging capabilities.
- Europe follows with a market share of around 25–30%, benefiting from strong regulatory systems, access to neurosurgical care, and high density of specialist facilities.
- Asia-Pacific, with a market share of approximately 20%, is the fastest-growing region due to rising healthcare investment, expanding diagnostic capacity, and increasing patient awareness.
- Intracranial arachnoid cysts dominate the market, followed by spinal arachnoid cysts, with intracranial cysts commanding a larger share due to higher diagnosis rates and the need for surgical intervention.
Market Drivers:
Increasing Incidence and Early Diagnosis of Arachnoid Cysts
The rising prevalence of arachnoid cysts is a primary driver for the growth of the Arachnoid Cysts Treatment Market. Improved diagnostic technologies, such as MRI and CT scans, allow for early detection of these cysts, even in asymptomatic individuals. Early diagnosis leads to increased treatment initiation and monitoring, contributing to a growing demand for effective management options. With more patients being diagnosed, the need for innovative and minimally invasive treatments continues to rise.
- For instance, GE Healthcare's MAGiC (Magnetic Resonance Image Compilation) technology enables the generation of quantitative T1 and T2 maps, as well as multiple diagnostic contrasts, from a single acquisition lasting approximately 5 minutes.
Advancements in Surgical Techniques and Treatment Technologies
Innovations in surgical methods and treatment technologies significantly influence the Arachnoid Cysts Treatment Market. Minimally invasive procedures, such as endoscopic cyst fenestration and neuroendoscopic techniques, have enhanced the effectiveness and reduced recovery times for patients. These advancements allow for more accurate and less traumatic interventions, contributing to their growing adoption. As these techniques evolve, they offer higher success rates and fewer complications, pushing the demand for surgical treatments in the market.
- For instance, Karl Storz's LOTTA neuroendoscopic system, a pioneer in neuroendoscopy since the 1990s, enables treatment of obstructive hydrocephalus, intraventricular tumors and arachnoid cysts with both 6° and 30° viewing angles for enhanced visualization during bimanual dissection procedures.
Expanding Awareness and Patient Education
The increasing awareness among clinicians and patients about arachnoid cysts and their potential health implications is driving the growth of the Arachnoid Cysts Treatment Market. With more individuals being educated on the symptoms and risks associated with the condition, treatment demand has surged. Patients are more likely to seek medical attention once they understand the potential impact of untreated cysts on brain function and overall health. This growing awareness is further fueled by health campaigns and the dissemination of information in medical communities.
Rising Investment in Healthcare Infrastructure Globally
Increased healthcare investment worldwide, particularly in emerging regions, is accelerating the growth of the Arachnoid Cysts Treatment Market. Governments and private entities are improving healthcare infrastructure, leading to better access to advanced diagnostic and treatment facilities. This trend is especially visible in Asia-Pacific, where healthcare investments are growing rapidly, facilitating quicker access to high-quality medical services for patients with arachnoid cysts. Enhanced access to care directly boosts the adoption of available treatment options.
Market Trends:
Rising Adoption of Minimally Invasive and Image‑Guided Surgical Interventions
The Arachnoid Cysts Treatment Market has witnessed strong uptake of minimally invasive surgery for cyst management. Surgeons favour endoscopic fenestration and targeted drainage systems because they lower patient discomfort and shorten hospital stays. It has become a key trend that neurosurgical centres invest in high‑definition neuroendoscopy and intraoperative imaging to enhance precision and safety. Hospitals with robust imaging platforms outperform peers in outcome metrics and patient preference. These developments drive demand for specialised instruments and services in cyst treatment pathways.
- For instance, Gazi University Faculty of Medicine’s neurosurgery team achieved safe and successful neuroendoscopic management for rare suprasellar arachnoid cysts, with most patients experiencing symptom improvement.
Integration of Advanced Neuroimaging, Artificial Intelligence and Personalized Care Models
Neuroimaging enhancements—such as real‑time MRI, CT fusion, and AI‑assisted diagnostics—are shaping the Arachnoid Cysts Treatment Market significantly. It enables earlier detection of arachnoid cysts and provides data that supports tailored intervention strategies for individual patients. AI tools refine image quality, automate measurement of cyst size and growth, and flag symptomatic cases that require intervention. Healthcare providers adopt these tools to streamline workflows, reduce operative risk, and improve outcomes. Concurrently, care models incorporate genetic, anatomical and clinical data to guide decision‑making and follow‑up protocols.
- For instance, Philips launched SmartSpeed Precise technology powered by dual-AI engines that delivers an 80% improvement in image sharpness and enables MRI scans to be completed up to 3 times faster.
Market Challenges Analysis:
High Treatment Cost and Reimbursement Constraints
The Arachnoid Cysts Treatment Market encounters significant pressure from elevated procedure and device costs. Many diagnostic tools, surgical implants, and imaging services carry high price‐tags that limit accessibility in low‐ and mid‐income regions. It restricts patient uptake and constrains provider adoption of advanced techniques. Payers may hesitate to reimburse novel treatments when evidence remains limited. These economic factors dampen market momentum and widen the access gap across geographies.
Clinical Complexity and Limited Consensus on Care Pathways
Patient management in this market often involves complex surgical intervention and variable outcomes, which raise adoption hurdles. It remains challenging to standardize treatment protocols for certain cyst locations or patient sub‐groups, because data on long‐term outcomes are scarce. Surgical risks, complications and recurrence potential weigh on clinicians’ decisions and patient willingness. The segment of cases requiring intervention remains relatively small because many cysts stay asymptomatic and observation may suffice. These clinical uncertainties limit broader market growth and heighten the burden on providers to justify intervention pathways.
Market Opportunities:
Expansion of Minimally‑Invasive Treatment Adoption
The Arachnoid Cysts Treatment Market presents significant opportunity through stronger uptake of minimally‑invasive and outpatient surgical solutions. Providers increasingly favour endoscopic cyst fenestration and permanent drainage systems that reduce hospital stay and recovery time. It opens paths for device manufacturers to introduce specialised instruments and technology that support these procedures. Hospitals and ambulatory surgical centres can expand service lines to meet rising demand for less invasive care. This shift also enables payers and providers to develop value‑based care models centred on improved clinical outcomes and cost efficiency.
Growth Potential in Emerging Markets and Digital Health Integration
Emerging regions such as Asia‑Pacific and Latin America offer robust growth potential in the market due to rising healthcare investment and improved diagnostic access. It gives stakeholders room to establish infrastructure and capture unmet treatment demand for arachnoid cysts. Telemedicine‑enabled follow‑ups and remote monitoring technologies further enhance care access in underserved zones and support longitudinal patient management. Medical device companies can partner with local distributors and hospitals to tailor treatment packages that address regional needs. This approach fosters penetration of advanced treatment options in markets that previously faced access constraints.
Market Segmentation Analysis:
By Type (Intracranial vs Spinal)
The segment by type divides the market into intracranial arachnoid cysts and spinal arachnoid cysts. Intracranial cysts hold the larger share because they are diagnosed more frequently and require surgical intervention more often. Spinal cysts remain less common but will grow faster thanks to improved spinal imaging and surgical techniques. It gives device makers and service providers a clear target for differentiation in product development and service offerings.
- For instance, Clearmind Biomedical received FDA 510(k) clearance in August 2024 for its Neuroblade System, a multifunctional neuroendoscopy platform integrating visualization, illumination, irrigation, suction, coagulation, and powered debridement in a single device.
By Treatment Procedure (Medication vs Surgery)
Treatment‑procedure segmentation covers medication and surgical options for arachnoid cyst management. Surgery dominates the market since it offers definitive relief in symptomatic cases, including fenestration and drainage systems. Medication plays a complementary role by managing symptoms such as headaches or seizures and offers a less invasive alternative for some patients. It opens opportunities for value‑based care models that combine therapeutic and supportive interventions.
- For instance, BC Children's Hospital successfully treated 3 out of 4 pediatric patients with ruptured arachnoid cysts using acetazolamide at dosages between 9.0-18.0 mg/kg per day, achieving complete reabsorption of subdural collections within 6 months without requiring surgery.
By Diagnosis Method (CT Scan, MRI Scan, Prenatal Ultrasound, Other Tests)
The diagnosis method segment includes CT scans, MRI scans, prenatal ultrasound, and other diagnostic tests. MRI scans lead because they provide high‐resolution imaging without radiation and support precise cyst characterization. CT scans remain popular in settings needing fast, cost‑effective diagnostics. Prenatal ultrasound expands recognition of cysts before birth, creating early intervention pathways. It invites suppliers and providers to tailor imaging solutions by region and capability.
Segmentations:
By Type
- Intracranial Arachnoid Cysts
- Spinal Arachnoid Cysts
By Treatment Procedure
- Medication
- Surgery (e.g., endoscopic fenestration, permanent drainage system)
By Diagnosis Method
- CT Scan
- MRI Scan
- Prenatal Ultrasound
- Other Diagnostic Tests
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Region Analysis
North America holds a market share of 43.2 % in 2024 for the Arachnoid Cysts Treatment Market. The region benefits from established healthcare infrastructure, high levels of neuroimaging deployment, and strong neurosurgical expertise. Hospitals and clinics invest heavily in MRI and CT systems, which support early diagnosis and intervention of arachnoid cysts. It also enjoys favourable reimbursement frameworks that encourage use of advanced treatment procedures. The presence of major device manufacturers supports rapid innovation in minimally invasive cyst treatment. Patient awareness ranks high, which drives treatment demand and sustains growth.
Europe Region Analysis
Europe captures a market share of around 25‑30 % for the arachnoid cysts treatment market during the current period. The region enjoys robust regulatory systems, widespread access to neurosurgical care, and high density of specialist facilities. It drives adoption of new techniques such as endoscopic fenestration and drainage systems. It faces moderate growth compared to emerging regions because many markets are mature with steady baseline demand. Healthcare systems in Germany, the UK and France push for improved neuro‑care, which supports uptake of treatment solutions. Patient advocacy groups and clinician networks raise awareness and promote early referral.
Asia‑Pacific and Other Regions Analysis
Asia‑Pacific anticipates the fastest growth and holds a market share of approximately 20 % at present in the arachnoid cysts treatment market. The region sees increasing healthcare investment, rising diagnostic capacity and growing patient awareness in countries like China and India. It has room to expand treatment access through telemedicine, training programmes and lower‑cost device solutions. Latin America, Middle East and Africa share smaller portions but present untapped opportunities due to improving infrastructure and increasing neurological care focus. It remains critical for stakeholders to tailor market strategies to local regulatory landscapes and cost structures in these regions.
Key Player Analysis:
- DePuy Synthes
- Hitachi Medical Corporation
- GE Healthcare
- Siemens Healthineers
- Canon Medical Systems
- Elekta
- Stryker Corporation
- Medtronic
- Braun Melsungen AG
- Brainlab
- Varian Medical Systems
- Johnson & Johnson
- Philips Healthcare
- NeuroWave Systems
- NuVasive
Competitive Analysis:
The competitive landscape of the Arachnoid Cysts Treatment Market features prominent medical‑device and imaging companies. Companies such as DePuy Synthes, Hitachi Medical Corporation, GE Healthcare, Siemens Healthineers, Canon Medical Systems, Elekta, Stryker Corporation and Medtronic compete on technology innovation, global reach and clinical partnerships. The market demands advanced imaging systems, minimally invasive surgical tools and neuro‑management devices, and it rewards companies that invest in R&D trends and form strategic alliances. Lead players extend their product portfolios through acquisitions or development of drainage systems and endoscopic instruments. They secure distribution channels in key regions and expand presence in emerging markets to capture growth opportunities. Some firms emphasise cost‑effective solutions to win in regions with constrained healthcare budgets. It becomes essential for companies to demonstrate clinical outcomes and regulatory compliance to maintain leadership.
Recent Developments:
- In September 2025, Hitachi agreed to acquire the German data and AI services firm synvert to boost its global AI-driven business initiatives.
- In September 2025, GE Healthcare announced an agreement to acquire icometrix, expanding its neurological AI imaging capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Type, Treatment Procedure, Diagnosis Method and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The increasing adoption of minimally invasive surgical techniques will drive demand for advanced treatment devices.
- Growing use of AI‑enhanced neuroimaging will enable earlier diagnosis and improve patient outcomes.
- Emerging markets in Asia‑Pacific and Latin America will offer expansion opportunities for device manufacturers and service providers.
- Integration of telemedicine and remote monitoring will support post‑operative care and follow‑up protocols.
- Device companies will pursue strategic partnerships with neurosurgical centres to accelerate innovation and market penetration.
- Health systems will focus on value‑based care models that emphasize cost‑effectiveness and treatment efficacy.
- New implantable drainage systems will enter the market, offering less invasive options for cyst management.
- Greater patient awareness and education campaigns will increase case identification and demand for treatment.
- Regulatory bodies will streamline approvals for imaging and surgical devices to support faster market entry.
- Research into genomic and biomarker‑based diagnostics will open the pathway for more personalised treatment approaches.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Arachnoid Cysts Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate (CAGR) is the Arachnoid Cysts Treatment Market projected to grow between 2024 and 2032?
Which segment of the Arachnoid Cysts Treatment Market held the largest share in 2024?
What are the primary factors fueling the growth of the Arachnoid Cysts Treatment Market?
Who are the leading companies in the Arachnoid Cysts Treatment Market?
Which region commanded the largest share of the Arachnoid Cysts Treatment Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Arachnoid Cysts Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Arachnoid Cysts Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2109.09 million → 2032: USD 3045.57 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Arachnoid Cysts Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Arachnoid Cysts Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Arachnoid Cysts Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Arachnoid Cysts Treatment Market Drivers
- 3.3 Arachnoid Cysts Treatment Market Restraints & Challenges
- 3.4 Arachnoid Cysts Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Arachnoid Cysts Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Arachnoid Cysts Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Arachnoid Cysts Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Arachnoid Cysts Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Arachnoid Cysts Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Arachnoid Cysts Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Arachnoid Cysts Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Arachnoid Cysts Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Arachnoid Cysts Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Arachnoid Cysts Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Arachnoid Cysts Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Arachnoid Cysts Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Arachnoid Cysts Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Arachnoid Cysts Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Arachnoid Cysts Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Arachnoid Cysts Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Arachnoid Cysts Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Arachnoid Cysts Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Arachnoid Cysts Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
