
Automotive Paints And Coatings Market Overview:
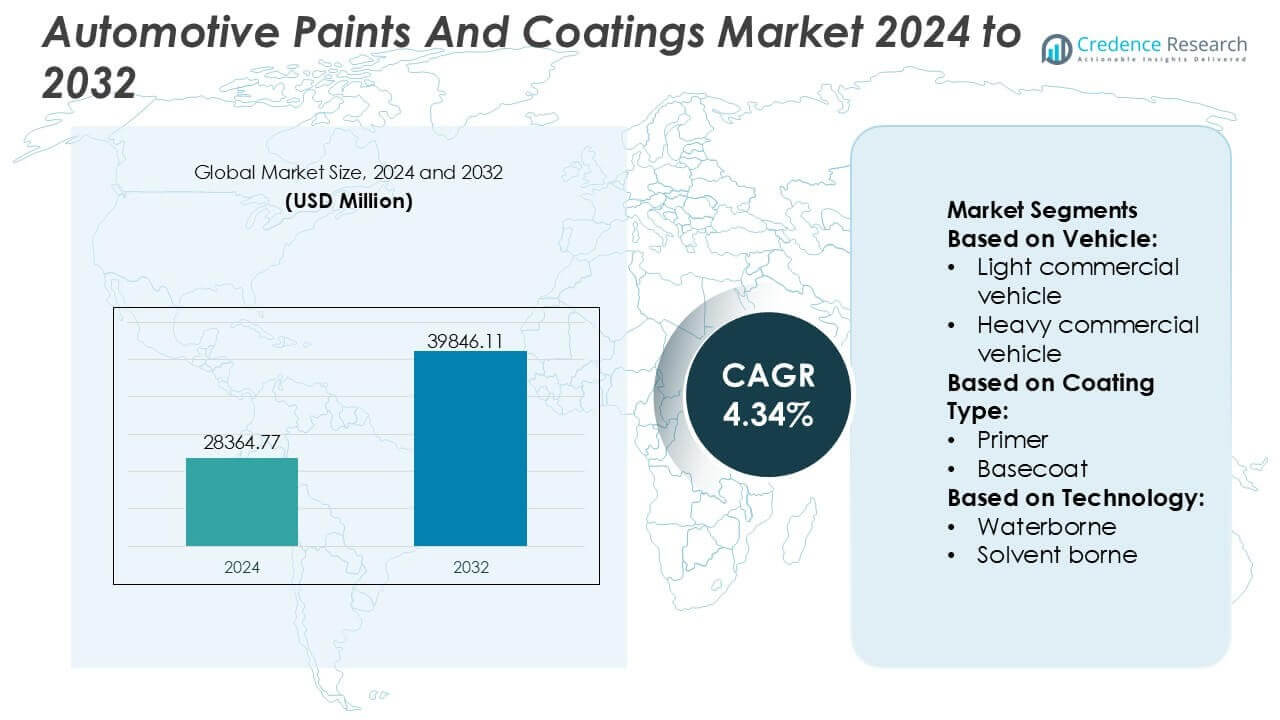
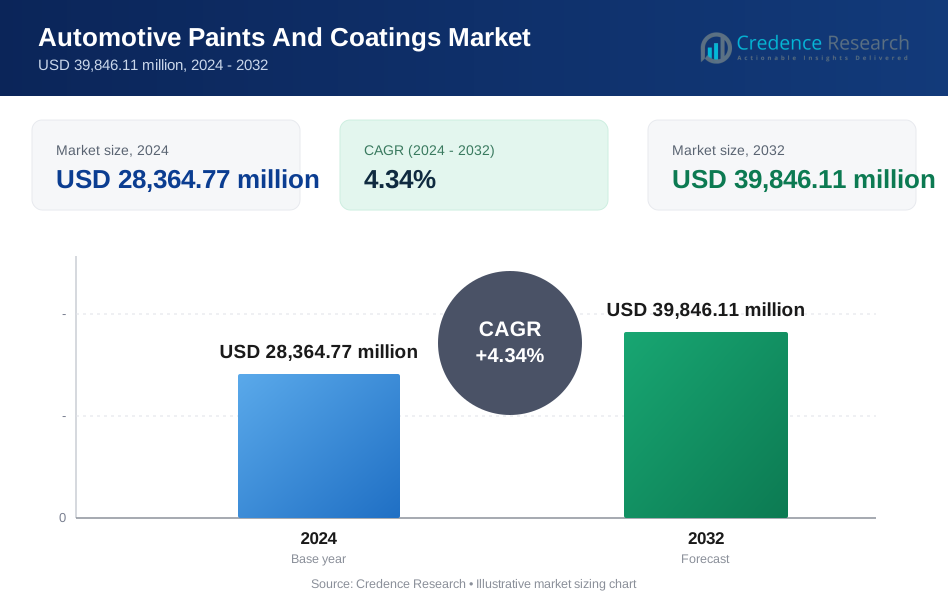
Automotive Paints And Coatings Market size was valued USD 28364.77 million in 2024 and is anticipated to reach USD 39846.11 million by 2032, at a CAGR of 4.34% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Paints And Coatings Market Size 2024 | USD 28364.77 million |
| Automotive Paints And Coatings Market, CAGR | 4.34% |
| Automotive Paints And Coatings Market Size 2032 | USD 39846.11 million |
Automotive Paints And Coatings Market Insights
- Market growth is primarily driven by rising global vehicle production, increasing adoption of electric vehicles, and stringent environmental regulations that accelerate the shift toward waterborne and powder coating technologies.
- Key market trends include strong demand for low-VOC coatings, high-solids clearcoats, and color-customization solutions, with waterborne coatings dominating the technology segment at around 46% share due to regulatory compliance and OEM preference.
- The competitive landscape is characterized by globally integrated players focusing on R&D-led innovation, localized manufacturing, and long-term OEM supply contracts to strengthen market penetration and operational efficiency.
- From a regional perspective, Asia-Pacific leads with an exact 38% market share, supported by high automotive production in China, India, and Japan, while Europe and North America follow, driven by sustainability mandates and premium vehicle demand.
Automotive Paints And Coatings Market Segmentation Analysis:
By Vehicle
By vehicle type, Passenger Cars represent the dominant sub-segment in the automotive paints and coatings market, accounting for an estimated 68% market share. This dominance is driven by high global passenger vehicle production volumes, frequent model refresh cycles, and strong demand for aesthetic differentiation through color, gloss, and surface finish. Passenger cars also require multiple coating layers electrocoat, primer, basecoat, and clearcoat per unit, increasing overall coating consumption. Growth is further supported by rising adoption of advanced coatings for scratch resistance, UV protection, and corrosion control. Light commercial vehicles follow, while heavy commercial vehicles maintain steady demand linked to durability requirements.
- For instance, Axalta Coating Systems, LLC has deployed its next-generation Fast Cure Low Energy (FCLE) System for automotive refinishers and collision centers, which enables curing at bake temperatures as low as 60 °C (or ambient air dry) to reduce energy consumption by up to 45%.
By Coating Type
By coating type, Clearcoat emerges as the leading sub-segment, holding approximately 36% market share, driven by its critical role in enhancing surface gloss, color depth, and long-term durability. Clearcoats protect vehicles against UV radiation, chemical exposure, weathering, and minor abrasions, making them essential for both aesthetic appeal and lifecycle performance. Increasing consumer preference for premium finishes, metallic effects, and high-gloss appearances continues to boost clearcoat demand. Primer and electrocoat coatings remain essential for corrosion resistance and adhesion, while basecoats support color customization and brand differentiation across passenger and commercial vehicle platforms.
- For instance, Berger Paints India has commercialized high-performance automotive clearcoats engineered to deliver gloss levels above 90 GU at a 60° measurement angle, with cured film thicknesses controlled within 40–50 microns. Company technical datasheets also indicate accelerated weathering resistance exceeding 1,500 hours in QUV testing and scratch resistance performance validated at loads above 5 N in standardized mar resistance tests, demonstrating clear, measurable enhancements in surface durability and finish retention.
By Technology
By technology, Waterborne coatings dominate the market with an estimated 52% share, supported by stringent environmental regulations and OEM commitments to reduce volatile organic compound emissions. Waterborne systems deliver comparable color quality, durability, and process efficiency while significantly lowering solvent content. Their compatibility with high-speed automotive production lines and advanced spray technologies further accelerates adoption. Solvent-borne coatings retain relevance in specific applications requiring fast curing, while powder coatings gain traction for underbody and component protection. UV-cured coatings remain niche but are increasingly explored for rapid curing and energy-efficient finishing in select automotive applications.
Key Growth Drivers
Rising Global Vehicle Production and Model Proliferation
Growth in global automotive production remains a primary driver for paints and coatings demand, supported by expanding passenger car output and increasing light commercial vehicle fleets. Automakers continue to introduce frequent facelifts, special editions, and region-specific models, all of which increase coating volumes per vehicle through diversified color palettes and finish requirements. The shift toward multi-layer coating systems combining electrocoat, primer, basecoat, and clearcoat further amplifies consumption. Emerging markets contribute additional momentum as rising vehicle ownership expands the installed base requiring OEM and refinishing coatings.
- For instance, PPG Industries, Inc. has introduced its Envirobase® High Performance waterborne basecoat system supporting more than 90,000 color formulas globally, with OEM-validated film builds of 12–18 microns per basecoat layer and curing compatibility with bake temperatures below 140 °C.
Increasing Focus on Vehicle Aesthetics and Surface Performance
Consumer preference for visually appealing vehicles with long-lasting finishes significantly drives adoption of advanced automotive coatings. High-gloss, metallic, pearlescent, and matte finishes are increasingly used to enhance brand identity and vehicle differentiation. Beyond aesthetics, coatings now deliver functional benefits such as scratch resistance, UV stability, corrosion protection, and chemical resistance. Automakers rely on premium coatings to maintain exterior quality over extended ownership cycles, especially in harsh climatic conditions, making performance-enhanced clearcoats and basecoats a critical growth driver.
- For instance, NIPSEA Group has advanced its automotive clearcoat and basecoat platforms to deliver gloss retention exceeding 85 gloss units after 1,000 hours of accelerated weathering, with controlled clearcoat film thickness ranges of 35–45 microns.
Regulatory Push Toward Low-Emission and Sustainable Coatings
Stringent environmental regulations governing volatile organic compound emissions strongly influence coating technology adoption. OEMs increasingly transition toward waterborne, powder, and low-solvent systems to comply with emission norms while maintaining production efficiency. Sustainability commitments across automotive supply chains further accelerate the replacement of conventional solvent-borne coatings. Coating suppliers benefit from rising investments in eco-friendly formulations that balance environmental compliance with durability, color consistency, and high-throughput manufacturing compatibility, reinforcing long-term market growth.
Key Trends & Opportunities
Rapid Shift Toward Waterborne and Powder Coating Technologies
A major trend shaping the market is the accelerated shift toward waterborne and powder coatings across OEM paint shops. These technologies significantly reduce solvent emissions while delivering high-quality finishes compatible with automated painting lines. Powder coatings are gaining traction in underbody and component applications due to superior material utilization and corrosion resistance. This transition creates strong opportunities for coating manufacturers that offer advanced formulations with faster curing, improved flow characteristics, and consistent color performance.
- For instance, BASF SE has expanded its CathoGuard® waterborne electrocoat portfolio to deliver corrosion protection exceeding 2,000 hours in neutral salt spray testing with uniform film builds of 18–22 microns.
Growing Adoption of Functional and Smart Coatings
Automotive coatings are evolving beyond decorative functions toward performance-enhancing and smart solutions. Self-healing clearcoats, anti-microbial interior coatings, heat-reflective surfaces, and anti-fingerprint finishes are gaining OEM interest. These innovations support vehicle durability, cabin hygiene, and thermal management, particularly in electric and connected vehicles. Suppliers capable of integrating functional additives without disrupting production cycles are well positioned to capture emerging opportunities in premium and next-generation vehicle segments.
- For instance, Asian Paints has developed advanced automotive clearcoat formulations incorporating elastic polymer networks capable of recovering surface micro-scratches with widths below 20 microns when exposed to temperatures above 50 °C.
Expansion of Automotive Refinishing and Aftermarket Demand
Rising vehicle parc and longer ownership cycles are expanding demand for automotive refinishing coatings. Repair, repainting, and customization activities increase steadily as consumers prioritize vehicle appearance and resale value. This trend creates opportunities for coatings tailored to faster drying, color-matching accuracy, and application flexibility across diverse repair environments. Growth in insurance-backed repairs and organized aftermarket networks further supports this opportunity.
Key Challenges
High Capital and Operational Costs of Advanced Coating Systems
Automotive paint shops require significant capital investment in spray booths, curing ovens, emission control systems, and automation infrastructure. Transitioning to new coating technologies often involves process revalidation, equipment upgrades, and workforce training. These high upfront and operational costs can limit rapid adoption, particularly for smaller OEMs and suppliers in cost-sensitive markets. Maintaining consistent quality while managing energy consumption and waste treatment remains a persistent operational challenge.
Volatility in Raw Material Prices and Supply Chain Constraints
Automotive coatings rely on resins, pigments, solvents, and additives that are vulnerable to price volatility and supply disruptions. Fluctuations in petrochemical feedstock costs directly impact formulation economics and supplier margins. Additionally, supply chain constraints can affect pigment availability and lead times, complicating OEM production planning. Coating manufacturers must continuously balance cost control with performance requirements, making raw material volatility a critical challenge for sustained profitability.
Regional Analysis
North America
North America holds an estimated 34% market share in the automotive paints and coatings market, driven by strong vehicle production volumes, high penetration of electric vehicles, and strict environmental regulations. OEMs and refinishers across the U.S. and Canada increasingly adopt waterborne and low-VOC coating technologies to comply with emission standards while maintaining durability and finish quality. The region benefits from advanced manufacturing infrastructure, high R&D spending, and close collaboration between automakers and coating suppliers. Demand for premium clearcoats, scratch-resistant finishes, and lightweight coating systems remains strong, particularly in passenger cars and light commercial vehicles.
Europe
Europe accounts for approximately 29% market share, supported by a well-established automotive manufacturing base and some of the world’s most stringent environmental and sustainability regulations. Automakers in Germany, France, Italy, and the UK emphasize waterborne, powder, and UV-cured coatings to reduce solvent emissions and energy consumption. The region shows strong demand for high-performance primers and clearcoats that enhance corrosion resistance and aesthetic differentiation. Growth is further supported by the premium and luxury vehicle segment, where advanced color effects, matte finishes, and customized coatings play a critical role in brand positioning and vehicle design.
Asia-Pacific
Asia-Pacific dominates the automotive paints and coatings market with an estimated 37% market share, led by high vehicle production in China, India, Japan, and South Korea. Rapid urbanization, rising disposable incomes, and expanding middle-class populations continue to drive passenger car demand. Cost-effective solvent-borne coatings remain widely used, while waterborne and powder coatings gain momentum due to tightening environmental regulations. The region benefits from large-scale manufacturing capacity, localized supply chains, and strong OEM presence. Growth in electric vehicles and two-wheelers further accelerates demand for durable, lightweight, and fast-curing coating solutions.
Latin America
Latin America represents around 6% market share, supported by steady automotive production in Brazil, Mexico, and Argentina. The region’s market is driven by demand for cost-efficient coating solutions for passenger cars and commercial vehicles. Solvent-borne coatings continue to dominate due to lower costs and established application infrastructure, although waterborne technologies are gradually gaining acceptance. Automotive refinish coatings play a significant role, supported by an aging vehicle fleet and strong aftermarket demand. Economic recovery trends, regional trade agreements, and increasing localization of vehicle manufacturing are expected to support moderate growth across the region.
Middle East & Africa
The Middle East & Africa holds roughly 4% market share, with demand primarily driven by vehicle imports, commercial fleets, and aftermarket refinishing activities. Harsh climatic conditions increase the need for coatings with enhanced heat, UV, and corrosion resistance. Solvent-borne coatings remain prevalent, though regulatory initiatives in select countries are encouraging adoption of low-VOC alternatives. Growth is supported by infrastructure development, expanding logistics fleets, and rising vehicle ownership in urban centers. While OEM production remains limited compared to other regions, refinish and protective automotive coatings continue to provide stable market opportunities.
Automotive Paints And Coatings Market Segmentations:
By Vehicle:
- Light commercial vehicle
- Heavy commercial vehicle
By Coating Type:
- Primer
- Basecoat
By Technology:
- Waterborne
- Solvent borne
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The automotive paints and coatings market players such as Axalta Coating Systems, LLC, Berger Paints India, PPG Industries, Inc., NIPSEA Group, BASF SE, Asian Paints, RPM International Inc., Kansai Paint Co., Ltd., The Sherwin-Williams Company. The automotive paints and coatings market is characterized by moderate consolidation and intense competition driven by technological differentiation, regulatory compliance, and strong integration with automotive OEMs. Participants compete primarily on coating performance, durability, color consistency, and application efficiency across passenger and commercial vehicle segments. Increasing regulatory pressure on emissions and solvent usage continues to accelerate the shift toward waterborne, powder, and low-VOC coating systems, making sustainability a key competitive factor. Innovation in electrocoat corrosion protection, scratch-resistant clearcoats, and lightweight-compatible formulations supports demand from electric and premium vehicle platforms. Competitive strategies emphasize continuous R&D investment, expansion of regional manufacturing capacity particularly in Asia-Pacific and digital optimization of coating processes to improve throughput and reduce waste. Long-term supply contracts with automakers, localized production to reduce logistics risk, and ongoing process automation collectively shape the competitive dynamics of the market.
Key Player Analysis
- Axalta Coating Systems, LLC
- Berger Paints India
- PPG Industries, Inc.
- NIPSEA Group
- BASF SE
- Asian Paints
- RPM International Inc.
- Kansai Paint Co., Ltd.
- The Sherwin-Williams Company
- Akzo Nobel N.V.
Recent Developments
- In August 2024, GoMechanic announced proving 25 stores in 8 cities with car detailing services, including ceramic coating and paint protection film (PPF). The service of the company is aimed at satisfying growing demand for the advanced vehicle protection solutions, with improved vehicle appearance and durability.
- In April 2024, Nippon Paint launched its consumer-focused automotive body and paint repair brand, Mastercraft, in India starting with its first store in Gurugram, offering services like quick repairs (Velocity Repair), detailing, ceramic coating, and paint protection, using Japanese tech for eco-friendly, high-quality finishes, with plans to expand across India and internationally.
- In February 2024, Sherwin-Williams General Industrial launched Duraspar Industrial Performance (IP), a new coating system for demanding industries like work trucks, blending automotive level finishes with tough industrial durability to streamline paint processes, reduce rework, and boost profitability for manufacturers.
Report Coverage
The research report offers an in-depth analysis based on Vehicle, Coating Type, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of waterborne and powder coatings will accelerate as automakers prioritize low-VOC and environmentally compliant solutions.
- Demand for advanced coatings compatible with electric vehicle platforms will increase, driven by thermal management and lightweighting needs.
- Smart and automated paint application systems will expand to improve coating uniformity, reduce material waste, and enhance production efficiency.
- Development of high-durability and self-healing clearcoats will gain traction to improve vehicle lifespan and reduce maintenance requirements.
- Growth in vehicle production across Asia-Pacific will continue to support capacity expansions and localized coating manufacturing.
- Customization of colors, textures, and finishes will rise as OEMs focus on brand differentiation and premium vehicle aesthetics.
- Increased use of digital color matching and simulation tools will improve consistency across global production plants.
- Regulatory pressure will drive continued innovation in bio-based resins and sustainable raw materials for coatings.
- Aftermarket demand for refinish coatings will strengthen due to rising vehicle parc and longer vehicle ownership cycles.
- Strategic collaborations between coating suppliers and automotive OEMs will deepen to co-develop next-generation coating technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Automotive Paints and Coatings Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Automotive Paints and Coatings Market projected to grow between 2024 and 2032?
Which Automotive Paints and Coatings Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Automotive Paints and Coatings Market?
Who are the leading companies in the Automotive Paints and Coatings Market?
Which region commanded the largest share of the Automotive Paints and Coatings Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Paints And Coatings Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Paints And Coatings Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 28,364.77 million → 2032: USD 39,846.11 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Paints And Coatings Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Paints And Coatings Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Paints And Coatings Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Paints And Coatings Market Drivers
- 3.3 Automotive Paints And Coatings Market Restraints & Challenges
- 3.4 Automotive Paints And Coatings Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Paints And Coatings Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Paints And Coatings Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Paints And Coatings category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Paints And Coatings Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Paints And Coatings Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Paints And Coatings market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Paints And Coatings Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Paints And Coatings Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Paints And Coatings Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Paints And Coatings (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Paints And Coatings Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Paints And Coatings Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Paints And Coatings Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Paints And Coatings Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Paints And Coatings Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Paints And Coatings Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Paints And Coatings Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Paints And Coatings Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Paints And Coatings Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
