
Railway Management System Market Overview:
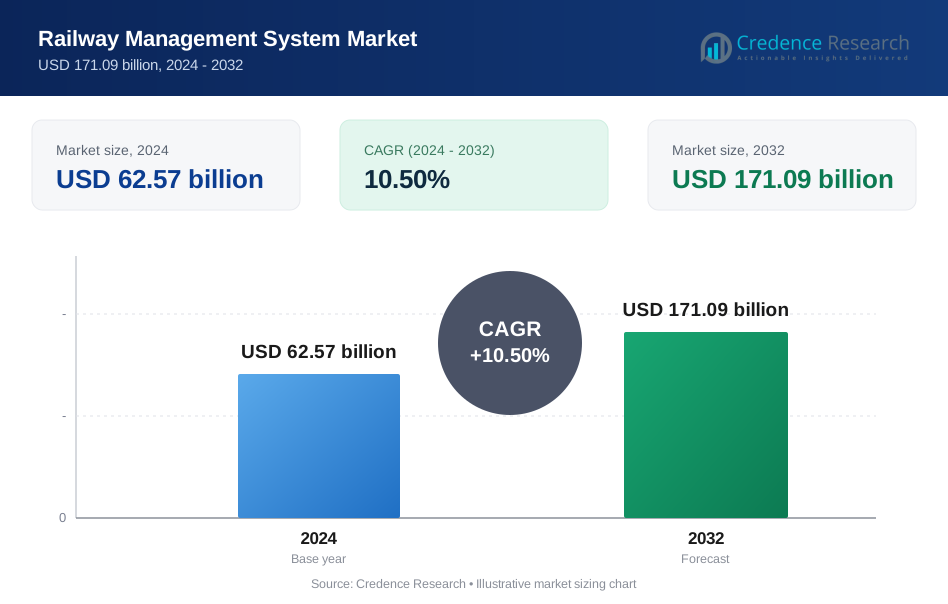
Railway Management System market size stood at USD 60,989.5 million in 2024 and is projected to reach USD 121,614.62 million by 2032, registering a CAGR of 9.01% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Railway Management System Market Size 2024 | USD 60,989.5 million |
| Railway Management System Market, CAGR | 9.01% |
| Railway Management System Market Size 2032 | USD 121,614.62 million |
Railway Management System Market Insights
- Solutions lead the offering segment with 39 percent share, driven by deployment of integrated scheduling, traffic control, and passenger information platforms that support digital operations across national and regional rail networks.
- Cloud deployment and AI-based analytics remain key trends as operators adopt predictive asset management, real-time scheduling tools, and smart communication platforms that improve network efficiency and passenger services.
- Competitive strategies involve Siemens Mobility, Alstom, Hitachi Rail, and Thales investing in digital control systems, centralized traffic platforms, and advanced communication technologies, while regional vendors offer localized solutions and cost-effective integration support.
- Asia Pacific holds 36 % share, followed by Europe at 30 % and North America at 22 %, supported by smart rail investments, high-speed development, and modernization of operational control systems across expanding metro and freight networks.

Railway Management System Market Segmentation Analysis:
By Offering
Solutions lead this segment with 39% share, driven by increasing adoption of integrated management platforms that support passenger information, freight scheduling, and traffic control functions across national and regional rail networks. Services represent 26% share as operators depend on training, system integration, and maintenance support to manage modern rail operations. Software holds 21% share, supported by demand for digital analytics and operational dashboards. Hardware accounts for 14% share, driven by automated signaling equipment and communication devices. Growth reflects rising digital integration and demand for real-time fleet monitoring across expanding networks.
- For instance, Siemens Mobility delivered major traffic-management systems for operators in Spain and Norway supporting automated routing and real-time conflict detection across over 2,000 km of mainline track.
By System Type
Operations management dominates with 37% share, supported by large-scale deployments of scheduling, routing, and traffic control tools that improve operational efficiency. Control management holds 28% share, focused on centralized monitoring and signaling systems that ensure safe rail movement across high-speed and freight corridors. Asset management represents 20% share, driven by predictive maintenance and digital lifecycle tools that reduce downtime. Communication and networking hold 15% share, as operators adopt secure communication platforms, radio networks, and signaling protocols for real-time operations.
- For instance, signing and centralized monitoring by Alstom covers over 1,200 km of mixed-speed track in European countries under ERTMS standards.
By Deployment
On-premises deployment leads with 40% share, driven by high data security requirements and legacy infrastructure across national rail systems. Cloud deployment accounts for 30% share, supported by growing adoption of scalable and flexible platforms that enable digital services and real-time data analytics. Hybrid deployment holds 23% share, integrating on-premises control systems with cloud-based analytics for large-scale operations. Edge deployment represents 7% share, supported by localized data processing and real-time operational decision-making at stations and rolling stock.
Key Growth Drivers
Rising Focus on Network Modernization and Digitalization
Rail operators upgrade legacy systems to improve operational efficiency, safety, and service reliability across national networks. Digital control systems, data-driven scheduling, and smart traffic management platforms reduce congestion and shorten turnaround times. Modernization initiatives expand demand for integrated systems capable of supporting real-time operation, predictive analytics, and communication control. These upgrades help operators manage high passenger volume and freight loading while improving infrastructure utilization.
- For instance, Deutsche Bahn uses a digital-twin framework to monitor track and infrastructure health in real time; its use of digital twin models spans thousands of kilometers of track, enabling early fault detection long before failures occur.
Expansion of Smart Rail and Passenger Services
Smart rail development encourages integration of next-generation passenger information systems, ticketing automation, and real-time service alerts. Increasing ridership drives demand for integrated communication platforms that improve passenger experience and service responsiveness. Data analytics improve scheduling accuracy and station flow management. These improvements support safer, more reliable, and user-friendly rail operations.
- For instance, Japan Railways deploys the system ATOS across fourteen lines, offering electronic displays and voice alerts in two languages, helping thousands of daily commuters stay informed of arrivals, departures, and delays.
Growing Need for Efficient Freight Operations
Global trade growth increases freight rail activity across industrial and logistics corridors. Operators adopt digital scheduling, route optimization, and asset tracking platforms to manage increased load and optimize delivery time. Predictive analytics support fleet availability and reduce operational delays.
Key Trends & Opportunities
Adoption of Cloud and AI-Based Management Tools
Operators use cloud platforms for real-time analytics, system control, and fleet scheduling. AI-based forecasting improves route planning and service reliability. Cloud solutions support scalable deployments across freight and passenger networks. These tools reduce manual tasks and improve decision-making.
- For instance, Trenitalia uses data analytics and AI for predictive maintenance to help avoid unplanned downtime and improve operational efficiency. This system helps the Italian operator monitor its trains for maintenance and safety issues.
Integration of IoT and Predictive Maintenance
IoT sensors support real-time monitoring of rolling stock and infrastructure, enabling predictive maintenance that lowers downtime. Operators use data analytics to track asset health and plan maintenance cycles. These systems extend asset life and improve network reliability.
- For instance, Hitachi Rail deployed condition-monitoring sensors on over 280 Class 800 fleet units in the United Kingdom, enabling predictive checks of traction motors and doors through continuous data streams processed at operating depots.
Key Challenges
High Cost of Modernization and System Integration
Upgrading legacy networks requires capital investment in digital platforms, communication infrastructure, and control systems. Budget limitations slow modernization across developing regions. Integration complexity increases when combining legacy control systems with modern software.
Cybersecurity Risks Across Connected Networks
Digital systems create vulnerability to cyberattacks targeting control centers and communication platforms. Operators must deploy secure communication, threat detection, and authentication tools. Skill limitations slow secure adoption across regional networks.
Regional Analysis
Asia Pacific
Asia Pacific leads the Railway Management System market with 36% share, supported by growing investments in digital rail technologies across China, Japan, and India. Smart rail initiatives focus on real-time scheduling, passenger information, and communication control across metro and intercity lines. Large freight corridors require advanced traffic management and predictive analytics to improve operational efficiency. Urban transit expansion increases deployment of operation control and automated passenger service platforms. Regional governments adopt integrated management solutions for network upgrade and service modernization.
Europe
Europe holds 30% share, driven by strong digital transformation strategies across the United Kingdom, Germany, and France. High-speed rail networks rely on advanced control systems, communication infrastructure, and centralized traffic management to maintain operational reliability. Passenger experience improvements drive demand for integrated passenger information and ticketing platforms. Regulatory frameworks encourage adoption of intelligent rail systems and lifecycle planning tools. Cross-border networks depend on unified digital control standards and data sharing capabilities.
North America
North America accounts for 22% share, driven by modernization of passenger and freight operations across the United States and Canada. Operators invest in digital control systems, asset management platforms, and predictive analytics to improve network performance and reduce service disruption. Freight expansion increases deployment of scheduling, routing, and load planning systems. Cloud-based control platforms and AI-based forecasting support real-time decision-making across national networks.
Middle East and Africa
Middle East and Africa represent 7% share, supported by new rail development projects across the Gulf region and emerging digital modernization initiatives in Africa. Urban mobility projects introduce smart passenger information systems and integrated ticketing solutions. Freight corridors expand rail transport across industrial zones, increasing demand for traffic control and asset planning platforms. National development strategies create opportunities for digital rail platforms and centralized operation management.
Latin America
Latin America holds 5% share, driven by modernization programs across metro and passenger networks in Brazil, Mexico, and Chile. Operators invest in passenger information, route scheduling, and asset management platforms to improve service availability. Freight development promotes adoption of planning and control platforms across industrial corridors. Limited investment budgets slow large-scale modernization, but gradual upgrades continue improving operational efficiency across urban and regional rail networks.
Railway Management System Market Segmentations:
By Offering
- Solutions
- Services
- Software
- Hardware
By System Type
- Operations Management
- Control Management
- Asset Management
- Communication and Networking
By Deployment
- On-Premises
- Cloud
- Hybrid
- Edge
By Application
- Freight Management
- Passenger Information
- Traffic Control
- Rail Asset Planning
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis in the Railway Management System market includes major players such as Siemens Mobility, Alstom, Hitachi Rail, Thales Group, Bombardier Transportation, Wabtec Corporation, Toshiba Infrastructure Systems, Huawei Technologies, IBM, and Cisco Systems, offering integrated platforms that support traffic management, passenger information, scheduling, and predictive asset planning. These players focus on digitalization, cloud deployment, and AI-based analytics that improve service reliability and support smart rail operations. Many companies expand partnerships with national rail authorities to deploy centralized operation centers and automated control platforms for high-capacity metro, intercity, and freight networks. Vendors also invest in advanced communication systems and secure data networks to support interoperability across large infrastructures. Continuous innovation in predictive analytics, IoT integration, and hybrid deployment strengthens competitive positioning as operators modernize existing infrastructure and expand digital rail systems.
Key Player Analysis
- Siemens Mobility
- Alstom
- Hitachi Rail
- Thales Group
- Bombardier Transportation
- Wabtec Corporation
- Toshiba Infrastructure Systems
- Huawei Technologies
- IBM
- Cisco Systems
Recent Developments
- In May 2025, Alstom deployed the first phase of its Iconis Traffic Management System (TMS) for KiwiRail in New Zealand, centralizing network control for the Wairarapa Line from the Wellington control centre.
- In October 2024, Hitachi Rail was selected to implement a Mobility-as-a-Service (MaaS) solution for Etihad Rail, which is responsible for developing and operating the UAE’s National Railway Network.
- In September 2024, Indra and Lithuanian Railways (LTG Infra) signed a letter of intent to explore the joint development of a pioneering digital signalling interlocking system.
Report Coverage
The research report offers an in-depth analysis based on Offering, System Type, Deployment, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Digital rail transformation will drive wider deployment of integrated management platforms.
- Predictive analytics will strengthen asset planning and real-time scheduling.
- Cloud-based control systems will gain adoption across major networks.
- Smart rail projects will increase demand for communication and passenger information tools.
- High-speed development will support advanced traffic control technologies.
- Cybersecurity integration will become a key priority in system deployments.
- IoT-enabled inspection and diagnostics will improve operational reliability.
- Hybrid deployment models will combine legacy systems with modern analytics.
- Regional operators will adopt automation to manage rising passenger capacity.
- Unified network control standards will grow across multi-country rail corridors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Railway Management System market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Railway Management System market projected to grow between 2024 and 2032?
Which Railway Management System market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Railway Management System market?
Who are the leading companies in the Railway Management System market?
Which region commanded the largest share of the Railway Management System market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Railway Management System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Railway Management System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 62.57 billion → 2032: USD 171.09 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Railway Management System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Railway Management System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Railway Management System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Railway Management System Market Drivers
- 3.3 Railway Management System Market Restraints & Challenges
- 3.4 Railway Management System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Railway Management System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Railway Management System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Railway Management System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Railway Management System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Railway Management System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Railway Management System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Railway Management System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Railway Management System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Railway Management System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Railway Management System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Railway Management System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Railway Management System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Railway Management System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Railway Management System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Railway Management System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Railway Management System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Railway Management System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Railway Management System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Railway Management System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
