
Market Overview
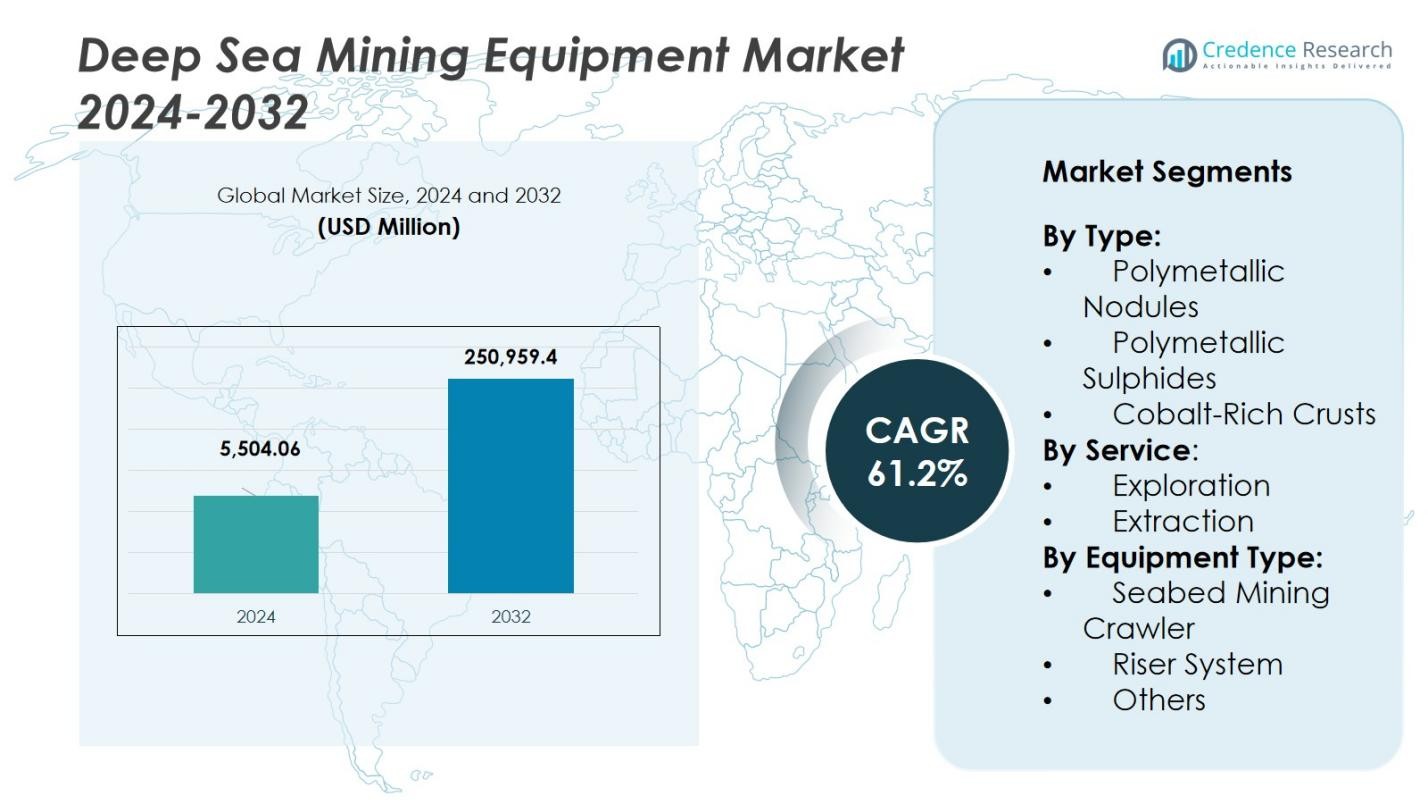
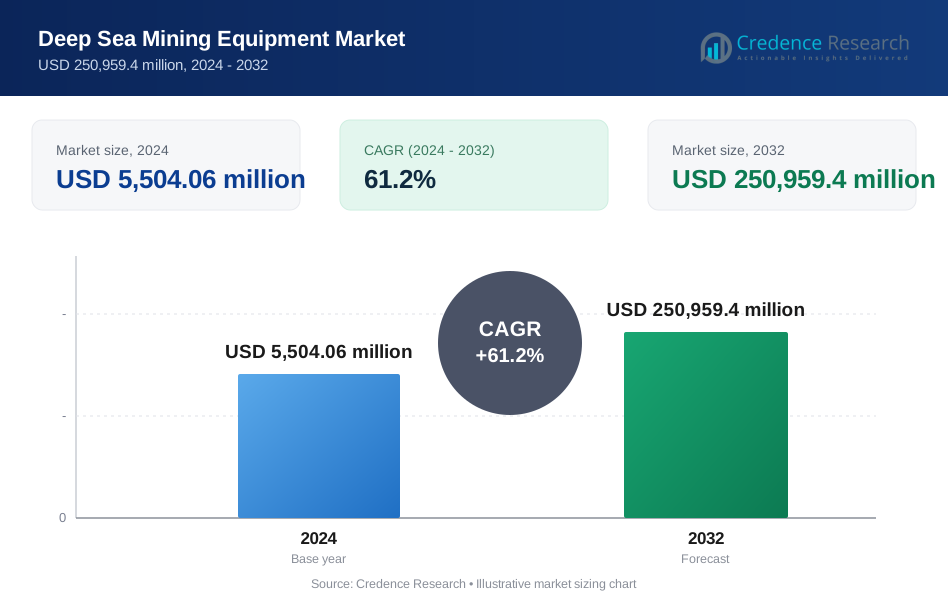
The Deep Sea Mining Equipment Market size was valued at USD 5,504.06 million in 2024 and is anticipated to reach USD 250,959.4 million by 2032, at a CAGR of 61.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Deep Sea Mining Equipment Market Size 2024 | USD 5,504.06 Million |
| Deep Sea Mining Equipment Market, CAGR | 61.2% |
| Deep Sea Mining Equipment Market Size 2032 | USD 250,959.4 Million |
The Deep Sea Mining Equipment Market is dominated by key players such as Subsea 7, Nautilus Minerals, DEME Group, SMD (Soil Machine Dynamics), and Royal IHC. These companies are at the forefront of developing advanced deep-sea mining technologies, including seabed mining crawlers, riser systems, and other specialized equipment. Their leadership stems from extensive experience in offshore operations, strong R&D capabilities, and strategic partnerships with research institutions. The Asia-Pacific region leads the market with a substantial share of 36.23% in 2024, driven by robust investments from China, India, and Japan in deep-sea exploration projects. North America follows with 25.14%, driven by the United States and Canada’s push for resource independence and technological innovation. Europe and the LAMEA region account for 19.61% and 18.02% shares, respectively, with ongoing investments and emerging opportunities in seabed mining.
Market Insights
- The Deep Sea Mining Equipment Market was valued at USD 5,504.06 million in 2024 and is projected to reach USD 250,959.4 million by 2032, growing at a CAGR of 61.2% during the forecast period.
- The primary driver of growth is the increasing demand for rare earth metals, such as nickel, cobalt, and copper, essential for electric vehicles and renewable energy technologies.
- Technological advancements in seabed mining crawlers, riser systems, and automation are contributing to improved operational efficiency, making deep-sea mining more viable.
- The market faces challenges such as high operational costs and environmental concerns, with strict regulations pushing for sustainable mining technologies.
- The Asia-Pacific region holds the largest market share of 36.23%, followed by North America at 25.14%. The Extraction service segment leads with 72.5% share, while the Polymetallic Nodules type holds 58.3% of the market share in 2024.
Market Segmentation Analysis:
By Type:
The Polymetallic Nodules segment is the dominant sub-segment in the Deep Sea Mining Equipment Market, holding a substantial market share of 58.3% in 2024. This segment is driven by the increasing demand for critical metals like nickel, cobalt, and copper, which are essential for electric vehicle (EV) batteries and renewable energy technologies. The high concentration of these metals in polymetallic nodules, coupled with the advancements in deep-sea mining technologies, makes this segment a key player in the market's growth trajectory.
- For instance, India’s National Institute of Ocean Technology conducted deep-sea mining trials in the Andaman Sea, targeting polymetallic nodules rich in metallic elements vital for clean energy technologies.
By Service:
The Extraction service segment leads the Deep Sea Mining Equipment Market, commanding 72.5% of the total market share in 2024. This segment's dominance is attributed to the technological advancements in extraction equipment and its crucial role in obtaining valuable minerals from the seabed. As demand for rare metals and minerals continues to rise in industries such as electronics, automotive, and renewable energy, extraction services are expected to experience consistent growth driven by increased exploration activities and investments in extraction technologies.
- For instance, Shanghai Jiao Tong University's independently developed prototype, Kaituo II, which reached depths over 4,100 meters, showcasing advanced capability in deep-sea extraction technology.
By Equipment Type:
The Seabed Mining Crawler segment is the dominant sub-segment in the Deep Sea Mining Equipment Market, holding 64.7% of the market share in 2024. This equipment is essential for deep-sea mining, as it enables the collection of valuable minerals from the ocean floor. The segment is driven by the growing demand for rare earth metals and the technological innovations that have enhanced the efficiency and depth at which these crawlers can operate. Additionally, seabed mining crawlers are critical to reducing the environmental impact of deep-sea mining operations, further boosting their adoption.
Key Growth Drivers
Rising Demand for Rare Earth Metals
The increasing demand for rare earth metals, especially in electric vehicles (EVs), renewable energy technologies, and electronics, is a significant driver of the Deep Sea Mining Equipment Market. Polymetallic nodules, which contain essential metals like nickel, cobalt, and copper, are a primary target for deep-sea mining operations. As the world shifts toward sustainable energy solutions and greener technologies, the need for these metals continues to rise, fueling the demand for advanced mining equipment capable of reaching the ocean’s depths.
- For instance, Nautilus Minerals' Solwara 1 project in Papua New Guinea's Bismarck Sea was among the first to target high-grade copper and gold-rich seafloor massive sulphides at a depth of around 1600 meters, though the project was ultimately abandoned in 2019 due to bankruptcy.
Advancements in Technology
Technological advancements in deep-sea mining equipment, such as seabed mining crawlers and riser systems, have dramatically improved the efficiency and safety of operations. These innovations allow for more effective exploration and extraction of valuable minerals from the seabed, even at greater depths. As mining companies increasingly invest in R&D to overcome technical challenges and improve automation, the Deep Sea Mining Equipment Market is set to witness rapid growth, ensuring operations can meet the rising demand for rare earth metals.
- For instance, De Beers' next-generation crawler weighs 370 tonnes and uses advanced navigation and hydraulic track tensioning to improve recovery rates by 20%, ensuring precise and reliable seabed traversal at depths of 100-135 meters.
Government Support and Policy Incentives
Government support and favorable policies related to deep-sea exploration and mining are further fueling market growth. Many countries are actively exploring the potential of deep-sea mining to ensure a steady supply of critical minerals for their growing industries. Policy incentives, such as subsidies, tax benefits, and funding for research, help reduce the financial barriers to entry and support the development of innovative mining technologies. As governments recognize the economic potential of deep-sea resources, the market for mining equipment is poised for continued expansion.
Key Trends & Opportunities
Sustainability and Environmental Regulations
As environmental concerns surrounding deep-sea mining rise, there is an increasing focus on sustainable practices and technologies in the industry. Stricter environmental regulations are pushing mining companies to adopt eco-friendly solutions that minimize the impact on marine ecosystems. This trend presents an opportunity for equipment manufacturers to develop sustainable mining technologies that address these challenges while improving operational efficiency. There is growing demand for solutions that balance resource extraction with environmental protection, creating a niche market for green mining technologies.
- For instance, Global Sea Mineral Resources NV (GSR) a subsidiary of DEME Group is developing ocean‑mineral retrieval systems with baseline environment‑data collection programmes for polymetallic nodules as part of its “sustainable ocean mineral resources” initiative.
Collaboration with Research Institutions
Collaborating with research institutions and universities is emerging as a key trend in the Deep Sea Mining Equipment Market. These partnerships are vital for driving technological innovation and advancing the capabilities of mining equipment. Research institutions contribute to the development of new materials, robotics, and automation systems that can improve the efficiency of deep-sea mining operations. As the market continues to grow, these collaborations will play a critical role in refining mining technologies, ensuring they are capable of meeting the increasing demand for seabed minerals.
- For instance, The Metals Company (TMC) has formalised partnerships with leading scientific research institutions and internationally‑renowned universities to support its exploration of polymetallic nodules in the Clarion‑Clipperton Zone, including dozens of discrete studies into bathymetry, pelagic and benthic biology as part of its environmental and social impact assessment.
Key Challenges
High Operational Costs
One of the major challenges faced by companies in the Deep Sea Mining Equipment Market is the high operational costs associated with deep-sea mining. The need for advanced, specialized equipment and the complexity of operations at extreme depths require significant investment. Additionally, the cost of ensuring environmental protection and compliance with regulatory standards further raises operational expenses. As a result, companies must find ways to optimize their operations and reduce costs without compromising safety or environmental sustainability, which remains a significant hurdle.
Environmental Concerns and Regulatory Pressure
Environmental concerns and regulatory pressure present significant challenges to the growth of the Deep Sea Mining Equipment Market. Mining operations at the ocean floor can disrupt delicate marine ecosystems and biodiversity, raising concerns about long-term ecological impacts. As a result, governments and environmental organizations are imposing stricter regulations to limit the environmental damage caused by deep-sea mining. These regulations can delay project timelines, increase compliance costs, and require additional investment in environmentally friendly technologies, which may slow market growth.
Regional Analysis
Asia‑Pacific
In the Asia‑Pacific region, the Deep Sea Mining Equipment Market secured the largest regional share of 36.23% in 2024. This dominance stems from intensive investments by nations such as China, India, and Japan in seabed exploration and mining projects to support rising demand for critical minerals like nickel, cobalt, and copper. The region’s strong manufacturing base, expanding electronics sector, and government‑backed resource‑security initiatives further drive equipment deployment. Continued industrialization and offshore mining contract awards position Asia‑Pacific as the focal growth hub for deep‑sea mining equipment.
North America
North America holds a substantial market share of 25.14% in the Deep Sea Mining Equipment Market in 2024. The growing momentum in the United States and Canada is driven by strategic pushes for mineral independence and advanced underwater mining technologies. The region’s extensive R&D capabilities, stringent environmental regulation frameworks, and strong private investment combine to stimulate procurement of cutting‑edge seabed mining crawlers, riser systems, and supporting services. As the region increasingly focuses on resource security, North America is set to be one of the fastest-growing regions during the forecast period.
Europe
Europe accounts for 19.61% of the global deep-sea mining equipment market in 2024. While the region does not lead in volume, it is steadily increasing its share as companies and governments engage in international seabed mining initiatives and collaborate with research institutions to enhance equipment capabilities. Europe’s strong ship‑building heritage, regulatory expertise, and technology-innovative firms provide a solid foundation. Its focus on environmentally‑compliant equipment solutions allows the region to hold a strong position in niche segments of the market.
LAMEA Region (Latin America, Middle East & Africa)
The LAMEA region holds a smaller market share of 18.02% in the Deep Sea Mining Equipment Market in 2024. However, it presents emerging opportunities, especially in countries like Brazil and Chile in Latin America and South Africa in Africa, which are beginning to explore seabed mineral deposits. Despite regulatory complexity, infrastructural constraints, and geopolitical factors, gradual policy reforms and resource-rich offshore zones position this region as a promising frontier for deep-sea mining equipment, with significant potential for future market growth.
Market Segmentations:
By Type:
- Polymetallic Nodules
- Polymetallic Sulphides
- Cobalt-Rich Crusts
By Service:
- Exploration
- Extraction
By Equipment Type:
- Seabed Mining Crawler
- Riser System
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Deep Sea Mining Equipment Market is highly competitive, with key players such as Subsea 7, Nautilus Minerals, DEME Group, SMD (Soil Machine Dynamics), and Royal IHC leading the industry. These companies dominate the market through their advanced technological capabilities, extensive experience in underwater operations, and strong R&D initiatives. Market players are focused on developing innovative equipment and solutions to enhance the efficiency, safety, and environmental sustainability of deep-sea mining operations. As demand for seabed minerals rises, these companies are investing heavily in automation and robotics to improve operational performance at greater depths. Strategic partnerships and collaborations with research institutions are also common, enabling the development of cutting-edge technologies. Moreover, regulatory compliance, particularly in terms of environmental protection, remains a key focus for these players as governments impose stricter environmental standards. As a result, the competitive landscape is shaped by technological advancements, regulatory adherence, and efforts to minimize environmental impact.
Key Player Analysis
- Plot Projects
- ProcessOne
- AlertFind
- Beeem
- PushAssist
- NotifyVisitors
- Pulsate
- Prowl
- Regroup Mass Notification
Recent Developments
- In February 2025, Cook Islands and People’s Republic of China signed a Memorandum of Understanding for a “Blue Partnership in the Field of Seabed Minerals Affairs” covering cooperation on seabed‑mineral exploration and technology transfer.
- In October 2025, Nauticus Robotics, Inc. secured a US $250 million equity line of credit and launched a strategic initiative to enter the deep‑sea rare‑earth/critical‑minerals exploration market, leveraging its subsea robotics platform.
- In April 2025, Impossible Metals applied for a deep‑sea mining lease in U.S. federal waters and announced development of autonomous underwater vehicles (AUVs) for harvesting critical seabed metals while aiming to protect environment.
Report Coverage
The research report offers an in-depth analysis based on Type, Service, Equipment Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Deep Sea Mining Equipment Market is expected to grow significantly due to increasing demand for rare earth metals essential for electric vehicles and renewable energy technologies.
- Technological advancements in deep-sea mining equipment, including robotics, automation, and AI, will drive operational efficiency and reduce costs.
- The market will see increased investments from both government and private sectors as countries look to secure access to seabed resources.
- Environmental concerns will push companies to develop and adopt more sustainable mining technologies with minimal ecological impact.
- Stricter regulatory frameworks will drive the need for equipment that meets higher environmental and operational standards.
- As exploration in deeper waters becomes more viable, the market will expand into previously unexplored seabed regions.
- The Asia-Pacific region will continue to dominate the market due to its large manufacturing base and resource demand.
- Strategic collaborations between equipment manufacturers and research institutions will spur innovation in deep-sea mining technologies.
- Increased demand for critical minerals will lead to the expansion of deep-sea mining projects in both developed and emerging markets.
- Competition in the market will intensify as more players enter the industry, focusing on cutting-edge technology and sustainability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Deep Sea Mining Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Deep Sea Mining Equipment Market projected to grow between 2025 and 2032?
Which Deep Sea Mining Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Deep Sea Mining Equipment Market?
Who are the leading companies in the Deep Sea Mining Equipment Market?
Which region commanded the largest share of the Deep Sea Mining Equipment Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Deep Sea Mining Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Deep Sea Mining Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,504.06 million → 2032: USD 250,959.4 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Deep Sea Mining Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Deep Sea Mining Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Deep Sea Mining Equipment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Deep Sea Mining Equipment Market Drivers
- 3.3 Deep Sea Mining Equipment Market Restraints & Challenges
- 3.4 Deep Sea Mining Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Deep Sea Mining Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Deep Sea Mining Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Deep Sea Mining Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Deep Sea Mining Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Deep Sea Mining Equipment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Deep Sea Mining Equipment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Deep Sea Mining Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Deep Sea Mining Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Deep Sea Mining Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Deep Sea Mining Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Deep Sea Mining Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Deep Sea Mining Equipment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Deep Sea Mining Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Deep Sea Mining Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Deep Sea Mining Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Deep Sea Mining Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Deep Sea Mining Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Deep Sea Mining Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Deep Sea Mining Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
