
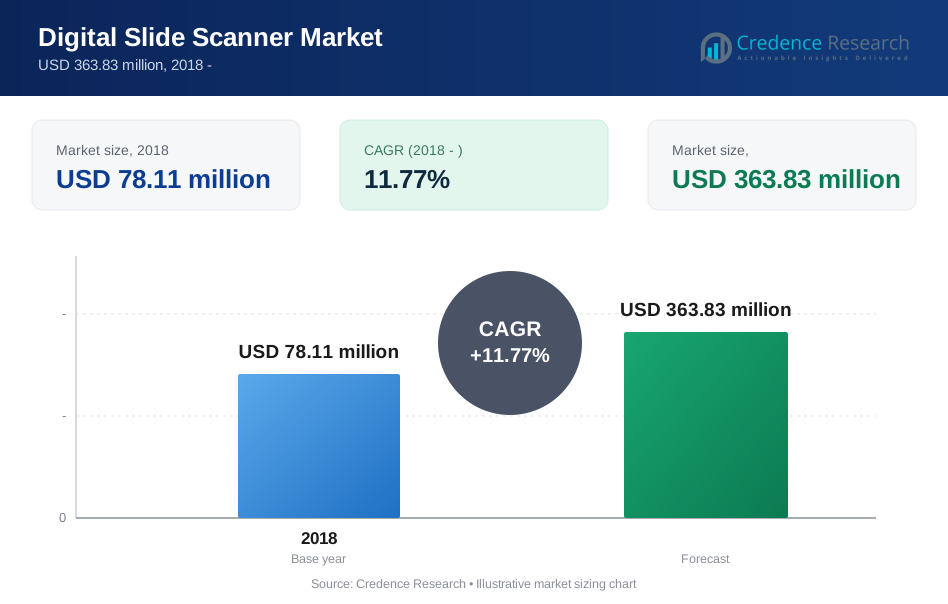
The Global Digital Slide Scanners Market size was valued at USD 78.11 million in 2018 to USD 140.43 million in 2024 and is anticipated to reach USD 363.83 million by 2032, at a CAGR of 11.77% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Slide Scanners Market Size 2024 | USD 140.43 million |
| Digital Slide Scanners Market, CAGR | 11.71% |
| Digital Slide Scanners Market Size 2032 | USD 363.83 million |
The market is expanding as pathology labs and hospitals adopt digital imaging solutions to improve workflow efficiency and diagnostic accuracy. Rising demand for telepathology and remote consultations fuels investments in advanced scanners. Technological progress in image resolution, automation, and AI integration enhances usability for medical research and clinical applications. Furthermore, increasing cancer cases and the global push for digital healthcare transformation drive adoption of these systems across both developed and emerging healthcare ecosystems.
Geographically, North America leads the market, supported by well-established healthcare infrastructure, high diagnostic volumes, and strong adoption of digital pathology. Europe follows with strong regulatory backing and growing digitization initiatives in clinical laboratories. Asia-Pacific is emerging as the fastest-growing region, driven by expanding healthcare investments, rising cancer prevalence, and adoption of digital pathology in China, India, and Southeast Asia. Latin America and the Middle East & Africa show gradual growth through government healthcare modernization initiatives.

Market Insights:
- The Global Digital Slide Scanners Market size was valued at USD 78.11 million in 2018, reached USD 140.43 million in 2024, and is projected to attain USD 363.83 million by 2032, growing at a CAGR of 11.77%.
- North America led with 38.4% share in 2024, driven by advanced healthcare infrastructure and high diagnostic volumes, followed by Asia Pacific at 30.7% due to large patient pools, and Europe at 21.6% supported by strong regulatory frameworks.
- Asia Pacific is the fastest-growing region with 30.7% share in 2024, supported by healthcare modernization, rising cancer prevalence, and growing telepathology adoption in China and India.
- Automated digital slide scanners accounted for the largest share of around 45% in 2024, reflecting demand for high-throughput and workflow efficiency in hospitals and labs.
- Desktop digital slide scanners held about 25% share in 2024, while portable and manual scanners filled niche needs in smaller labs, teaching environments, and regional facilities.
Market Drivers:
Rising Demand for Digital Pathology in Clinical Diagnostics:
The Global Digital Slide Scanners Market is driven by the rising shift from traditional microscopy toward digital pathology for accurate and rapid diagnoses. Hospitals and laboratories seek faster workflows to handle increasing case volumes, especially in cancer diagnostics. Digital scanners offer high-resolution imaging, allowing pathologists to analyze slides remotely and collaborate across locations. The adoption of telepathology strengthens this demand by enabling access to expert reviews in underserved regions. Medical institutions prioritize these tools to reduce diagnostic delays and improve treatment outcomes. Growing patient awareness around timely cancer detection further drives usage. Governments encourage digitization in pathology to improve healthcare efficiency. The adoption of advanced scanners in diagnostics strengthens the market outlook.
- For instance, Leica Biosystems’ Aperio GT 180 scanner delivers brightfield scanning speeds of up to 180 slides per hour while maintaining image resolution at 0.25µm/pixel, facilitating rapid diagnoses in high-volume clinical settings. Digital scanners offer high-resolution imaging, allowing pathologists to analyze slides remotely and collaborate across locations.
Growing Integration of Artificial Intelligence and Automation Features:
Artificial intelligence integration in digital slide scanners enhances diagnostic accuracy and efficiency. Automated scanning and image analysis reduce manual workload, ensuring consistency in pathology results. The Global Digital Slide Scanners Market benefits from this trend as laboratories adopt systems with AI-powered diagnostic support. Automated tools allow pathologists to focus on complex cases instead of repetitive tasks. Healthcare institutions adopt AI-enabled platforms to accelerate disease detection and reduce turnaround time. Continuous innovation in machine learning algorithms strengthens clinical confidence in digital pathology. Automated workflows streamline pathology services and minimize human error. The rising reliance on AI-backed automation fuels consistent demand across healthcare networks.
- For example, PathAI’s AISight platform integrates AI-assisted image analysis that processes thousands of slides weekly with reported diagnostic concordance rates exceeding 95%, significantly reducing pathologist review time. The Global Digital Slide Scanners Market benefits from this trend as laboratories adopt systems with AI-powered diagnostic support. Automated tools allow pathologists to focus on complex cases instead of repetitive tasks.
Increasing Prevalence of Cancer and Chronic Diseases:
The rising incidence of cancer globally significantly influences the adoption of digital slide scanners. Growing patient populations in oncology create a strong need for accurate diagnostic tools. The Global Digital Slide Scanners Market benefits from the demand for reliable, high-quality imaging in disease detection. Digital scanners play a crucial role in monitoring treatment responses and guiding therapeutic decisions. Chronic diseases such as cardiovascular disorders also support wider adoption. Healthcare systems invest in pathology digitization to reduce diagnostic gaps. Patient-centric initiatives highlight the importance of early detection through advanced technologies. It strengthens the role of digital scanners in meeting long-term healthcare needs.
Expansion of Telemedicine and Remote Consultation Services:
The adoption of telemedicine accelerates the demand for digital slide scanners in pathology workflows. Pathologists can review digital slides remotely, enhancing collaboration across countries and regions. The Global Digital Slide Scanners Market benefits from this trend by enabling wider access to specialized expertise. Remote diagnosis reduces the need for physical sample transfers, saving time and resources. Healthcare institutions integrate scanners with cloud-based platforms for secure image sharing. Rising adoption of virtual tumor boards relies heavily on digital slide imaging. Remote consultations help smaller hospitals gain access to advanced diagnostics. It positions digital slide scanners as essential tools in expanding telehealth ecosystems.
Market Trends:
Adoption of Hybrid Cloud Solutions for Digital Pathology Workflows:
The Global Digital Slide Scanners Market witnesses a strong trend toward hybrid cloud adoption for managing large volumes of imaging data. Hospitals and laboratories store sensitive patient data securely while leveraging cloud platforms for collaboration. Hybrid systems balance local storage needs with scalable cloud-based solutions. They enable faster image retrieval and remote access for pathologists working across multiple facilities. Cloud integration supports real-time collaboration for global clinical trials and research projects. Vendors design scanners compatible with secure platforms to meet regulatory standards. This trend enhances operational efficiency and data security in healthcare networks. It underscores the move toward integrated, cloud-enabled pathology solutions.
- For instance, Leica Biosystems’ Aperio HALO AP platform offers hybrid cloud compatibility that enables remote access to clinical cases with image retrieval latencies under 3 seconds in multi-center deployments. Hybrid systems balance local storage needs with scalable cloud-based solutions. They enable faster image retrieval and remote access for pathologists working across multiple facilities.
Increased Focus on Multi-Modal Imaging Capabilities in Scanners:
Manufacturers increasingly develop scanners capable of handling multi-modal imaging in pathology applications. The Global Digital Slide Scanners Market benefits from this innovation, supporting applications in histology, immunohistochemistry, and molecular studies. Multi-modal imaging improves diagnostic depth by combining diverse techniques in one workflow. Pathologists gain comprehensive insights into disease progression and cellular-level changes. Advanced scanners offer flexibility to adapt to specialized research and clinical needs. Research institutions adopt multi-modal platforms to expand translational research. This trend enhances the versatility of digital scanners across healthcare and academic fields. It elevates their role as all-in-one diagnostic solutions for complex medical environments.
- For example, 3DHISTECH’s P480 2nd Generation scanner integrates polarization imaging with multi-fluorescence modes, scanning slides at resolutions down to 0.22µm/pixel, enabling detailed cellular and molecular analyses. Multi-modal imaging improves diagnostic depth by combining diverse techniques in one workflow. Pathologists gain comprehensive insights into disease progression and cellular-level changes.
Growing Adoption of Digital Slide Scanners in Academic Research:
Universities and medical schools increasingly adopt digital slide scanners to train the next generation of pathologists. The Global Digital Slide Scanners Market benefits from this trend by expanding beyond clinical diagnostics into education. Students access digital libraries of scanned slides for flexible learning. These systems support collaborative study across international institutions. Faculty members use digital platforms to integrate case-based teaching into curricula. Research programs in oncology and genetics utilize scanners for large-scale imaging projects. This trend fosters skill development in handling digital pathology tools early in careers. It strengthens the academic foundation for future healthcare professionals.
Rising Collaborations Between Scanner Providers and Pharma Companies:
Pharmaceutical companies collaborate with digital slide scanner providers to support drug discovery and clinical trials. The Global Digital Slide Scanners Market benefits from this trend as imaging solutions accelerate biomarker research. Pharma firms require digitized slides for analyzing treatment outcomes in oncology trials. Collaborations drive scanner adoption in research-focused laboratories. These partnerships enhance capabilities in molecular diagnostics and personalized medicine. Vendors customize scanners for pharma needs, including large-scale, high-throughput imaging. This trend ensures greater integration of scanners into drug development pipelines. It positions scanners as vital tools for accelerating innovation in therapeutic development.

Market Challenges Analysis:
High Cost of Systems and Infrastructure Limitations in Emerging Markets:
The Global Digital Slide Scanners Market faces barriers due to high equipment and maintenance costs. Smaller hospitals and laboratories in emerging economies find it difficult to adopt these systems. Infrastructure limitations, including weak internet connectivity, further restrict deployment. Advanced scanners require substantial investments in data storage and network capabilities. Healthcare institutions in low-resource regions struggle to justify such expenditures. Vendors must address affordability through flexible pricing and leasing models. Limited financial support slows penetration in rural and underserved healthcare settings. It creates a gap between advanced economies and developing nations in digital pathology adoption.
Concerns About Data Security and Standardization of Digital Pathology:
Another major challenge lies in data security and interoperability issues in digital pathology workflows. The Global Digital Slide Scanners Market must address risks related to patient confidentiality when using cloud-based platforms. Cybersecurity threats raise concerns among healthcare providers handling sensitive imaging data. Standardization of file formats and compatibility across systems also remains an issue. Institutions face delays in integration due to lack of universal frameworks. Regulatory approvals differ across regions, creating compliance complexities for vendors. Resistance among pathologists accustomed to traditional microscopy further slows adoption. It highlights the need for stronger guidelines and reliable security solutions in digital pathology.
Market Opportunities:
Growing Investments in AI-Powered Pathology and Clinical Research:
The Global Digital Slide Scanners Market holds opportunities with rising adoption of AI-powered platforms for diagnostics and research. Healthcare systems invest in AI to improve accuracy and reduce diagnostic errors. Clinical research organizations utilize scanners for high-volume studies in oncology and genetics. The demand for automation drives development of faster, AI-integrated scanners. Pharma companies expand usage in biomarker discovery and personalized medicine projects. Educational institutions integrate AI-enabled systems into medical training. It strengthens adoption across multiple healthcare and research environments. The focus on AI-driven pathology ensures sustained growth opportunities for vendors.
Expansion of Digital Pathology Across Emerging Healthcare Systems Globally:
The Global Digital Slide Scanners Market finds growth prospects in expanding digital pathology adoption across developing healthcare systems. Emerging countries invest in upgrading diagnostic infrastructure and pathology workflows. Government initiatives to modernize healthcare services accelerate adoption. Remote diagnostic needs in rural areas enhance demand for scanners. Vendors explore partnerships with local providers to expand accessibility. Training programs support broader acceptance among healthcare professionals. It opens doors for deeper market penetration in Asia, Latin America, and Africa. Vendors capitalizing on this momentum strengthen long-term growth potential in underserved regions.
Market Segmentation Analysis:
By Product Segment
The Global Digital Slide Scanners Market is segmented into automated, manual, portable, and desktop scanners. Automated scanners dominate demand due to their efficiency in handling large sample volumes and minimizing manual intervention. Manual scanners remain relevant in smaller laboratories and teaching facilities where cost control is vital. Portable scanners address the need for mobility and on-site diagnostics, especially in research and regional hospitals. Desktop scanners continue to gain traction among mid-sized labs seeking reliable yet compact solutions. It reflects diverse adoption patterns across healthcare and academic settings.
- For instance, ZEISS’ Axioscan 7 automated slide scanner handles up to 400 slides per batch with automatic focus adjustment and throughput of 100 slides per hour at 40x magnification. Manual scanners remain relevant in smaller laboratories and teaching facilities where cost control is vital. Portable scanners address the need for mobility and on-site diagnostics, especially in research and regional hospitals.
By Technology Segment
The market is divided into brightfield and fluorescence scanners, each serving distinct diagnostic needs. Brightfield scanners hold the largest share, driven by their role in routine pathology and wide adoption in clinical labs. Fluorescence scanners grow steadily with applications in oncology, genetics, and molecular diagnostics. Their advanced imaging capabilities support research on cellular and molecular processes. It highlights the trend of integrating high-resolution technology for precise analysis in both clinical and research applications.
- For example, Hamamatsu Photonics’ NanoZoomer S60 scanner offers fluorescence imaging with up to six fluorescence channels and a spatial resolution at 0.46µm/pixel, supporting multiplexed biomarker analysis for cancer research. Their advanced imaging capabilities support research on cellular and molecular processes.
By End User Segment
Hospitals and clinical pathology labs represent the leading end-user group, driven by rising diagnostic volumes and digital transformation initiatives. Biopharmaceutical and biotech companies increasingly adopt scanners to support drug discovery and biomarker research. Academic and research institutes use scanners for training, collaboration, and translational research projects. Other users include specialty labs and independent diagnostic centers extending adoption to varied healthcare environments. It reinforces the widespread role of digital scanners across healthcare, research, and life sciences industries.

Segmentation:
By Product Segment
- Automated Digital Slide Scanners
- Manual Digital Slide Scanners
- Portable Digital Slide Scanners
- Desktop Digital Slide Scanners
By Technology Segment
- Brightfield Scanners
- Fluorescence Scanners
By End User Segment
- Hospitals & Clinical Pathology Labs
- Biopharmaceutical & Biotech Companies
- Academic & Research Institutes
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Digital Slide Scanners Market size was valued at USD 30.34 million in 2018 to USD 53.92 million in 2024 and is anticipated to reach USD 140.12 million by 2032, at a CAGR of 11.8% during the forecast period. North America accounts for around 38.4% share of the Global Digital Slide Scanners Market in 2024. The region leads adoption due to advanced healthcare infrastructure and widespread digitization initiatives. Hospitals and pathology labs invest heavily in automated systems to improve diagnostic workflows. High prevalence of cancer and chronic diseases drives demand for precision diagnostics. Research collaborations between universities, pharmaceutical companies, and healthcare providers accelerate technology adoption. Regulatory support for digital pathology strengthens confidence in advanced imaging solutions. It benefits from strong funding in both clinical and research environments. The dominance of leading manufacturers headquartered in the region further consolidates its leadership.
Europe
The Europe Digital Slide Scanners Market size was valued at USD 17.68 million in 2018 to USD 30.35 million in 2024 and is anticipated to reach USD 72.81 million by 2032, at a CAGR of 10.7% during the forecast period. Europe holds around 21.6% share of the Global Digital Slide Scanners Market in 2024. The region shows steady growth, supported by stringent regulatory frameworks for pathology digitization. Countries such as Germany, the UK, and France drive adoption through national healthcare modernization initiatives. Aging populations contribute to rising diagnostic needs across oncology and chronic diseases. Academic and research institutes play a significant role in advancing adoption. Pharmaceutical companies use scanners to enhance biomarker studies and drug trials. Strong demand for interoperability and standardized platforms encourages innovation. It strengthens market penetration across healthcare systems seeking efficiency and cost savings.
Asia Pacific
The Asia Pacific Digital Slide Scanners Market size was valued at USD 22.76 million in 2018 to USD 43.18 million in 2024 and is anticipated to reach USD 121.93 million by 2032, at a CAGR of 13.0% during the forecast period. Asia Pacific captures around 30.7% share of the Global Digital Slide Scanners Market in 2024. The region emerges as the fastest-growing due to large patient pools and rising healthcare investments. Countries such as China, Japan, and India adopt scanners to strengthen oncology diagnostics. Government initiatives to upgrade healthcare infrastructure fuel adoption. Research institutes expand usage for translational research and academic training. Growing awareness of telepathology enhances adoption in underserved areas. Pharmaceutical outsourcing in countries like India supports scanner demand for drug trials. It reflects the region’s transformation into a critical growth hub.
Latin America
The Latin America Digital Slide Scanners Market size was valued at USD 3.78 million in 2018 to USD 6.71 million in 2024 and is anticipated to reach USD 15.43 million by 2032, at a CAGR of 10.1% during the forecast period. Latin America represents about 4.8% share of the Global Digital Slide Scanners Market in 2024. Growth is supported by expanding diagnostic infrastructure in Brazil, Argentina, and Mexico. Governments focus on modernizing healthcare delivery systems to address rising disease burdens. Adoption remains concentrated in large urban hospitals and research institutions. Limited financial resources in smaller labs hinder widespread penetration. International partnerships with global scanner providers help expand access. Academic institutions adopt scanners for training and research initiatives. It shows gradual yet consistent progress toward digital pathology adoption.
Middle East
The Middle East Digital Slide Scanners Market size was valued at USD 2.21 million in 2018 to USD 3.63 million in 2024 and is anticipated to reach USD 7.94 million by 2032, at a CAGR of 9.4% during the forecast period. The Middle East accounts for about 2.6% share of the Global Digital Slide Scanners Market in 2024. Growth is concentrated in GCC countries where healthcare modernization projects remain strong. Hospitals adopt digital pathology systems to enhance cancer diagnostics and improve turnaround times. Investment in research facilities supports advanced imaging adoption. Countries such as Saudi Arabia and the UAE drive regional demand. Barriers include uneven adoption across smaller economies and limited technical expertise. Government-led healthcare expansion initiatives help offset these challenges. It positions the region as an emerging but uneven growth market.
Africa
The Africa Digital Slide Scanners Market size was valued at USD 1.35 million in 2018 to USD 2.65 million in 2024 and is anticipated to reach USD 5.61 million by 2032, at a CAGR of 8.9% during the forecast period. Africa represents around 1.9% share of the Global Digital Slide Scanners Market in 2024. Growth is gradual due to infrastructure limitations and restricted funding in healthcare systems. Adoption is mostly concentrated in South Africa and Egypt, where research institutions lead demand. Rural regions continue to face challenges in integrating digital pathology. International collaborations with donor agencies and universities support early-stage adoption. Rising cancer prevalence highlights the need for advanced diagnostics. Local governments explore telepathology solutions to address physician shortages. It reflects a market in early development, with long-term potential as healthcare systems strengthen.
Key Player Analysis:
- Leica Biosystems
- Hamamatsu Photonics
- ZEISS
- 3DHISTECH
- Olympus Corporation
- Digital Pathology Solutions
- Roche Diagnostics
- Ventana Medical Systems
- Invetech
- Fimmic
- Labcyte Inc.
Competitive Analysis:
The Global Digital Slide Scanners Market is highly competitive, with leading players focusing on product innovation, automation, and integration of artificial intelligence to strengthen their portfolios. Companies compete by offering advanced imaging solutions that meet the demands of hospitals, research institutions, and pharmaceutical firms. It is shaped by established firms with strong distribution networks and rising participation from regional players targeting niche applications. Vendors expand presence through partnerships, acquisitions, and global collaborations to enhance product reach. Competition intensifies as emerging players introduce cost-effective scanners for developing markets, while established leaders maintain dominance with premium offerings.
Recent Developments:
- In June 2025, Leica Biosystems unveiled its next-generation digital pathology portfolio at the European Congress on Digital Pathology, featuring high-performance scanners and intelligent software for diverse pathology needs, including the Aperio GT 180 scanner for high-speed brightfield scanning and the Aperio FL scanning system for multi-modal whole slide imaging. More recently, in September 2025, Leica Biosystems launched the Aperio HALO AP, a new clinical image management software expanding its digital pathology solutions, facilitating on-screen diagnosis, multi-disciplinary meetings, and consultations with an integrated Aperio AI Store featuring partner-developed applications. Earlier, in January 2025, Leica Biosystems introduced the HistoCore CHROMAX Workstation to automate and modernize staining and coverslipping processes, improving lab efficiency with touchscreen interfaces.
- In March 2025, ZEISS and imec extended their strategic partnership through 2029 to support advanced semiconductor research infrastructure and innovation in Europe, aligned with the European Chips Act. In August 2025, ZEISS renewed and expanded a global imaging partnership with vivo, aiming to broaden imaging technologies beyond smartphones and enhance a comprehensive imaging ecosystem. Additionally, in May 2025, ZEISS signed a strategic partnership agreement with tesa to industrialize holographically functionalized films.
- Roche Diagnostics showcased AI and digital health innovations in July 2025 at the Association for Diagnostics & Laboratory Medicine conference, emphasizing integrated solutions like navify® digital tools and advanced assays for diseases including Alzheimer's. Roche also renewed its Global Fund partnership in 2025, committing technical assistance to improve diagnostic networks globally. The acquisition of Ventana Medical Systems by Roche was completed earlier, adding key cancer diagnostic instruments to Roche’s portfolio.
- PathAI launched the Precision Pathology Network in July 2025, a network of digital pathology labs utilizing its AI-powered AISight platform to facilitate early access to AI pathology solutions and collaborative research with biopharma.
Report Coverage:
The research report offers an in-depth analysis based on product, technology, and end-user segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-powered pathology platforms will increase adoption in diagnostics and research.
- Telepathology expansion will strengthen cross-border collaboration in healthcare.
- Automated scanners will dominate demand in hospitals and clinical labs.
- Multi-modal imaging capabilities will gain traction in academic research.
- Pharma partnerships will drive growth in biomarker discovery and clinical trials.
- Portable scanners will see rising demand in remote and regional facilities.
- Emerging economies will accelerate adoption through healthcare modernization.
- Cloud-based integration will become critical for data storage and collaboration.
- Cost-competitive models will gain traction in small labs and teaching institutes.
- Global vendors will expand through mergers, acquisitions, and regional partnerships.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Digital Slide Scanner Market?
What factors are driving the growth of the Digital Slide Scanner Market?
What are some challenges faced by the Digital Slide Scanner Market?
Who are the major players in the Digital Slide Scanner Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Digital Slide Scanner Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Digital Slide Scanner Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (the forecast period) (2018: USD 78.11 million → forecast year: USD 363.83 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Digital Slide Scanner Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Digital Slide Scanner Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Digital Slide Scanner Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Digital Slide Scanner Market Drivers
- 3.3 Digital Slide Scanner Market Restraints & Challenges
- 3.4 Digital Slide Scanner Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Digital Slide Scanner Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Digital Slide Scanner Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Digital Slide Scanner category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Digital Slide Scanner Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Digital Slide Scanner Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Digital Slide Scanner market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Digital Slide Scanner Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Digital Slide Scanner Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Digital Slide Scanner Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Digital Slide Scanner (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Digital Slide Scanner Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Digital Slide Scanner Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Digital Slide Scanner Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Digital Slide Scanner Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Digital Slide Scanner Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Digital Slide Scanner Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Digital Slide Scanner Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Digital Slide Scanner Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Digital Slide Scanner Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
