
Market Overview
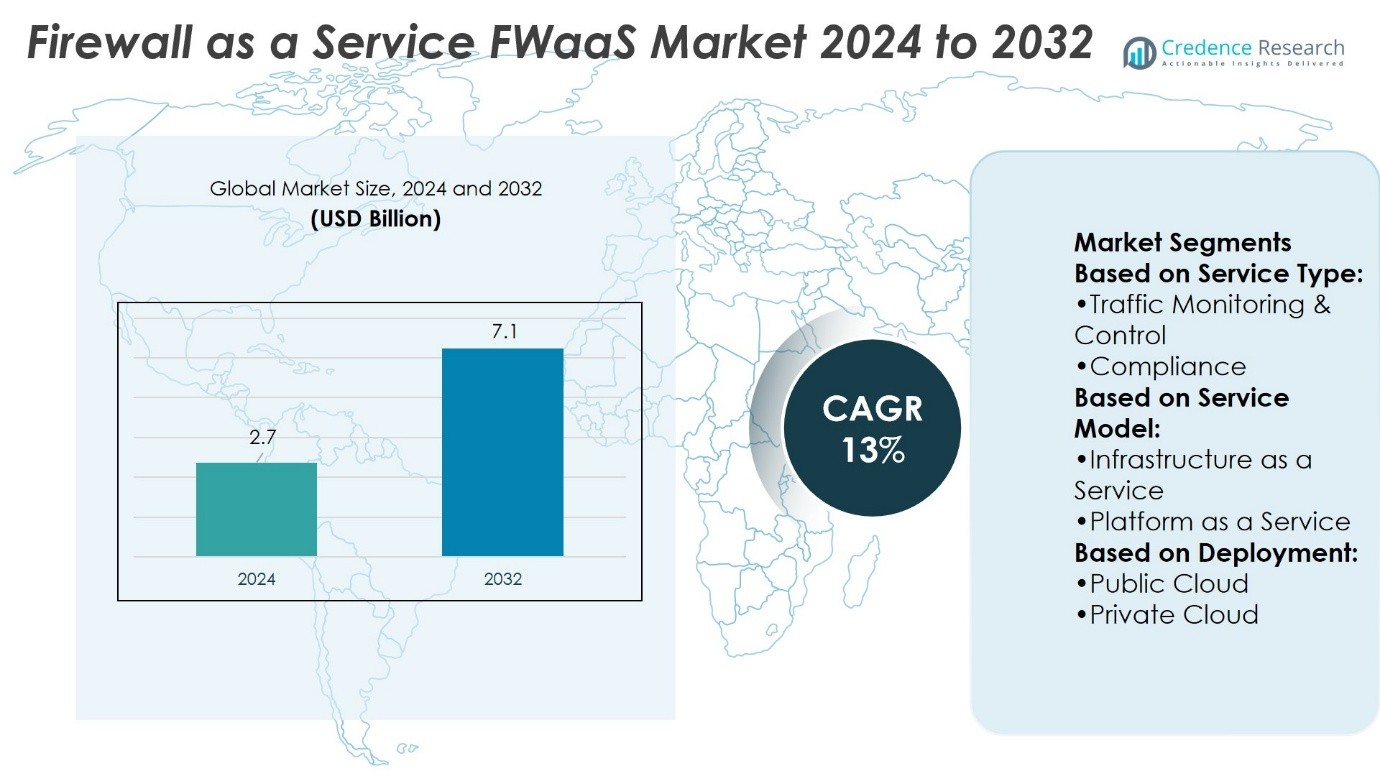
Firewall as a Service (FWaaS) Market size was valued at USD 2.7 billion in 2024 and is anticipated to reach USD 7.1 billion by 2032, at a CAGR of 13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Firewall as a Service Market Size 2024 | USD 2.7 Billion |
| Firewall as a Service Market, CAGR | 13% |
| Firewall as a Service Market Size 2032 | USD 7.1 Billion |
The Firewall as a Service (FWaaS) Market grows with rising cloud adoption, increasing cyber threats, and the demand for secure remote access. Enterprises rely on FWaaS to deliver scalable protection, centralized visibility, and compliance with strict data regulations. It enables organizations to secure hybrid and multi-cloud environments without heavy infrastructure costs. Key trends include the integration of artificial intelligence for real-time threat detection, the expansion of zero-trust security models, and the adoption of secure access service edge frameworks. These factors position FWaaS as a critical component in modern cybersecurity strategies, supporting digital transformation across industries.
North America leads the Firewall as a Service FWaaS Market with the largest share, driven by advanced cloud adoption and strong cybersecurity regulations, followed by Europe with strict data privacy frameworks and rising zero-trust deployments. Asia-Pacific shows the fastest growth due to digital transformation and increasing cyber risks across China, India, and Japan. Latin America and the Middle East & Africa steadily expand with growing investments in security modernization. Key players include Cisco, Fortinet, Palo Alto Networks, Zscaler, and Sophos.
Market Insights
- Firewall as a Service FWaaS Market size was valued at USD 2.7 billion in 2024 and is expected to reach USD 7.1 billion by 2032, at a CAGR of 13%.
- Market growth is driven by rising cloud adoption, increasing cyber threats, and demand for secure remote access.
- Key trends include AI-powered threat detection, expansion of zero-trust frameworks, and adoption of secure access service edge models.
- Competition remains strong as vendors focus on scalable, cloud-native solutions with managed service offerings.
- Market restraints include integration challenges with legacy systems and concerns over vendor reliability.
- North America leads the market with the largest share, followed by Europe with strong compliance-driven adoption.
- Asia-Pacific records the fastest growth, while Latin America and Middle East & Africa expand steadily with digital security investments.
Market Drivers
Rising Cybersecurity Threats Driving the Demand for Advanced Cloud-Based Solutions
The Firewall as a Service (FWaaS) Market gains momentum from escalating cyber threats that target businesses across industries. Organizations seek cloud-based defenses that scale quickly and adapt to evolving risks. FWaaS enables firms to consolidate security functions under a unified platform, reducing reliance on on-premises hardware. It enhances protection against malware, phishing, and distributed denial-of-service attacks. Growing digital transformation pushes firms to secure networks for remote and mobile users. It positions FWaaS as a reliable solution to safeguard business continuity and sensitive information.
- For instance, Fortinet’s EDR solution blocked all 51 advanced persistent threat scenarios in the latest SE Labs Advanced Security Test-achieving a perfect 100% in protection accuracy (816 of 816 points), legitimate accuracy (742 of 742 points), and total accuracy (1,558 of 1,558 points).
Increasing Cloud Adoption and Remote Workforce Expansion Fueling Growth
The Firewall as a Service FWaaS Market benefits from rapid cloud adoption and rising demand for secure remote connectivity. Enterprises migrate applications, data, and infrastructure to public and hybrid cloud environments, requiring flexible security frameworks. FWaaS delivers centralized visibility, policy enforcement, and threat detection for distributed systems. Organizations prioritize solutions that secure endpoints across multiple locations without heavy infrastructure investments. It empowers businesses to manage hybrid workforces while maintaining compliance standards. Cloud-native architectures strengthen the market’s role in digital transformation strategies.
- For instance, Zscaler processes more than 500 trillion security signals daily through its Zero Trust Exchange platform data fabric, bolstering AI-powered threat detection and automated defenses.
Regulatory Compliance and Data Privacy Requirements Creating Strong Demand
The Firewall as a Service FWaaS Market is reinforced by strict data protection rules and industry regulations. Businesses must comply with standards like GDPR, HIPAA, and PCI DSS while securing global operations. FWaaS platforms offer continuous monitoring and automated reporting that simplify compliance management. It ensures data handling practices meet legal expectations while reducing audit complexity. Companies adopt FWaaS to align security strategies with regulatory frameworks. Growing awareness of privacy risks supports adoption in finance, healthcare, and government sectors.
Cost Efficiency and Scalability Encouraging Widespread Adoption
The Firewall as a Service FWaaS Market expands with demand for cost-efficient and scalable cybersecurity models. Traditional firewall systems require expensive hardware, frequent updates, and specialized staff. FWaaS reduces capital expenditure by shifting protection to subscription-based models. It allows organizations to scale resources up or down depending on network requirements. Predictable pricing structures support budgeting while minimizing operational complexity. Businesses recognize FWaaS as a flexible investment that delivers enterprise-grade protection without infrastructure burdens. This balance of security and efficiency accelerates long-term adoption.
Market Trends
Integration of Artificial Intelligence and Machine Learning into Threat Detection
The Firewall as a Service FWaaS Market demonstrates a clear trend toward AI and machine learning integration. Vendors embed intelligent algorithms to identify and block threats with greater speed and accuracy. It supports automated anomaly detection and reduces reliance on manual monitoring. Machine learning models adapt to evolving attack vectors, strengthening proactive defense. Enterprises adopt these tools to limit downtime and reduce false positives. The focus on predictive security capabilities ensures continuous protection across diverse environments.
- For instance, Barracuda Managed XDR logged 11 trillion IT events identifying just over 1 million potential risks. Of those, 16,812 high-severity threats were identified as confirmed malicious instances requiring immediate action via automated defense. The 11 trillion logged events equate to an average of about 350,000 events per second.
Expansion of Zero-Trust Network Security Architecture Across Industries
The Firewall as a Service FWaaS Market aligns with the growing adoption of zero-trust frameworks. Organizations prioritize identity-based authentication and micro-segmentation to secure critical assets. It emphasizes verifying every access request, regardless of location or user. FWaaS platforms support zero-trust policies with centralized visibility and flexible controls. Enterprises adopt these practices to address hybrid work environments and remote operations. The trend strengthens the role of FWaaS in modern network security strategies.
- For instance, Cisco's Secure Firewall 3105 achieved a real-world TLS throughput of 4.17 Gbps in NetSecOPEN testing, exceeding its 3.2 Gbps datasheet value by 30%. The firewall also delivered 100% detection of evasive threats while maintaining performance under heavy load conditions.
Growing Demand for Multi-Cloud and Hybrid Cloud Security Integration
The Firewall as a Service FWaaS Market evolves with rising adoption of multi-cloud and hybrid architectures. Companies require unified security policies across different cloud providers and on-premises systems. It enables consistent monitoring, policy enforcement, and data protection across fragmented infrastructures. FWaaS supports seamless integration with leading platforms like AWS, Azure, and Google Cloud. Businesses value these capabilities to avoid security gaps during migration or workload distribution. This trend positions FWaaS as a central tool for cloud security orchestration.
Rising Focus on Managed Security Services and Subscription Models
The Firewall as a Service FWaaS Market shows a steady shift toward managed services and flexible pricing. Enterprises prefer subscription-based models that reduce upfront costs and streamline upgrades. It provides continuous support from specialized providers, addressing skill shortages in cybersecurity. Managed offerings deliver real-time monitoring, compliance reporting, and faster incident response. Organizations value predictable costs while gaining access to advanced threat intelligence. This trend reinforces FWaaS as a scalable and service-driven security solution.
Market Challenges Analysis
Complexity of Integration with Legacy Infrastructure and Diverse IT Environments
The Firewall as a Service FWaaS Market faces significant challenges in integrating with existing legacy infrastructure. Many enterprises operate on hybrid networks that combine outdated systems with modern cloud environments. It creates compatibility issues that delay adoption and require extensive customization. FWaaS solutions must adapt to varying architectures while maintaining seamless security controls. Organizations often struggle to align centralized policies across different endpoints and platforms. This complexity increases deployment costs and slows large-scale implementation, limiting the pace of adoption.
Rising Concerns Over Data Privacy, Vendor Dependence, and Service Reliability
The Firewall as a Service FWaaS Market encounters growing concerns around data privacy and vendor reliability. Companies depend heavily on external providers for managing critical security functions. It raises questions about control, transparency, and long-term service continuity. Outages or service disruptions may compromise protection and expose sensitive data. Enterprises also face risks from varying regional compliance requirements that FWaaS providers must address. Balancing reliance on third-party services with the need for regulatory compliance and operational resilience remains a persistent challenge.
Market Opportunities
Expanding Role in Securing Remote Workforces and Cloud-Centric Enterprises
The Firewall as a Service FWaaS Market presents opportunities through the rapid expansion of remote workforces and cloud-driven businesses. Organizations seek scalable and cloud-native solutions that secure users across multiple devices and geographies. It supports centralized policy enforcement while reducing infrastructure costs, making it attractive for mid-sized and large enterprises. The shift toward hybrid and multi-cloud adoption further strengthens demand for FWaaS platforms. Companies value its ability to deliver consistent protection across public and private environments. This creates a strong pathway for providers to expand market presence and service portfolios.
Rising Demand in Emerging Economies and Regulated Industries
The Firewall as a Service FWaaS Market gains opportunities in emerging economies where digital transformation is accelerating. Enterprises in Asia-Pacific, Latin America, and the Middle East invest heavily in advanced cybersecurity to protect growing digital ecosystems. It enables businesses in finance, healthcare, and government sectors to meet strict compliance and privacy regulations. Service providers that tailor FWaaS offerings to regional needs stand to capture significant growth. Organizations in regulated industries prioritize advanced monitoring and reporting tools offered by FWaaS. This creates long-term opportunities for expanding adoption across industries and geographies.
Market Segmentation Analysis:
By Service Type
The Firewall as a Service FWaaS Market segments into traffic monitoring & control, compliance & audit management, reporting & log management, automation & orchestration, security management, managed services, professional services, and others. Traffic monitoring & control holds strong relevance due to its role in detecting anomalies and preventing network breaches. Compliance & audit management gains importance in industries bound by strict regulatory frameworks. Reporting & log management provides visibility into threats and user activity, strengthening real-time response. Automation & orchestration streamline workflows and improve operational efficiency. Managed services and professional services attract enterprises that lack in-house expertise, offering end-to-end security support. It ensures businesses of varying sizes access specialized protection aligned with their operational needs.
- For instance, WatchGuard’s Threat Lab reported a 323% increase in AI-powered IntelligentAV detections in Q1 2025, alongside a 712% surge in new malware threats on endpoints, reinforcing the need for real-time AI-based defense against evasive threats.
By Service Model
The Firewall as a Service FWaaS Market divides by service model into infrastructure as a service, platform as a service, and software as a service. Software as a service dominates due to its scalability, ease of deployment, and centralized control. It allows enterprises to secure networks without maintaining hardware or complex infrastructure. Infrastructure as a service supports organizations that prefer flexible, cloud-hosted resources with strong customization. Platform as a service integrates security functions within application development frameworks, enabling built-in defense mechanisms. Businesses choose models depending on their cloud strategy and cost structure. The availability of multiple models ensures FWaaS aligns with varied enterprise requirements.
- For instance, Forcepoint’s Cloud Network Firewall independently blocked 977 exploits and 35 evasion techniques, maintaining a throughput of 943 Mbps during tests-demonstrating consistent performance under realistic loads.
By Deployment
The Firewall as a Service FWaaS Market further classifies deployment into public cloud, private cloud, and hybrid cloud. Public cloud deployment gains traction among small and medium enterprises due to affordability and ease of access. Private cloud appeals to organizations that prioritize data sovereignty and strict control over sensitive assets. Hybrid cloud emerges as a preferred model for large enterprises managing workloads across diverse environments. It combines flexibility with advanced security features, ensuring continuity of operations. Growing reliance on multi-cloud strategies strengthens the hybrid approach, making it a long-term growth driver. This diversity in deployment models ensures FWaaS meets security needs across industries and geographies.
Segments:
Based on Service Type:
- Traffic Monitoring & Control
- Compliance
Based on Service Model:
- Infrastructure as a Service
- Platform as a Service
Based on Deployment:
- Public Cloud
- Private Cloud
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America accounts for the largest share of the Firewall as a Service FWaaS Market, with around 35 % in 2024. The region benefits from a well-established digital economy, advanced cloud adoption, and strong awareness of cybersecurity risks. Enterprises across industries such as banking, healthcare, retail, and manufacturing continue to prioritize FWaaS solutions for securing their expanding digital footprints. It provides centralized visibility, compliance management, and advanced threat detection, which remain critical for organizations handling sensitive data. The United States leads the regional market, supported by investments from both private enterprises and government agencies that aim to strengthen cybersecurity readiness. Canada contributes steadily with its focus on data privacy and compliance, particularly in financial and public sectors. The overall dominance of North America is expected to continue as enterprises expand hybrid work models and increase spending on managed security services.
Europe
Europe holds a significant share of the Firewall as a Service FWaaS Market, estimated at 28 % in 2024. The region’s strength is linked closely to its strict regulatory environment, including GDPR and sector-specific data protection laws. Companies in Europe adopt FWaaS not only to secure their cloud-based operations but also to ensure compliance with legal frameworks that require continuous monitoring and detailed reporting. It plays an essential role in financial services, government institutions, and healthcare providers, where data sensitivity is high. Leading economies such as Germany, the United Kingdom, and France drive adoption by integrating FWaaS into broader digital transformation strategies. The market also benefits from the growing demand for zero-trust security frameworks that emphasize identity and access control. With cloud expansion continuing across Europe, FWaaS adoption is likely to accelerate, reinforcing the region’s role as one of the largest contributors to global market growth.
Asia-Pacific
Asia-Pacific captures about 25 % of the Firewall as a Service FWaaS Market in 2024 and demonstrates the fastest growth rate globally. The region is experiencing rapid digitalization, large-scale cloud adoption, and rising awareness of cybersecurity risks. Countries like China, India, Japan, and Singapore are at the forefront of investment in FWaaS platforms. It enables organizations to secure remote users, manage hybrid environments, and comply with evolving regional data protection rules. Small and medium enterprises, alongside large corporations, are increasingly shifting to subscription-based security models to reduce capital costs. Governments across Asia-Pacific are also investing in cybersecurity frameworks to counter rising cyberattacks that target public and private sectors. The increasing establishment of new data centers and the expansion of multi-cloud deployments create additional demand for FWaaS solutions. With strong growth momentum, Asia-Pacific is expected to steadily increase its market share over the coming years.
Latin America
Latin America holds about 7 % of the Firewall as a Service FWaaS Market in 2024, with adoption driven by enterprises in Brazil, Mexico, and Argentina. Organizations in these countries are becoming more aware of the importance of cloud-based security solutions to safeguard digital infrastructure. It offers affordable and scalable protection, making FWaaS appealing for enterprises with limited resources for traditional hardware-based systems. The financial sector in particular seeks FWaaS to meet compliance standards while securing sensitive customer information. Governments are also showing interest in strengthening public sector cybersecurity, which opens opportunities for service providers. While the pace of adoption is slower compared to North America, Europe, and Asia-Pacific, the market potential in Latin America remains strong. Rising internet penetration, growth in e-commerce, and digital transformation initiatives are expected to increase demand over the next decade.
Middle East & Africa
The Middle East & Africa region contributes around 5 % of the Firewall as a Service FWaaS Market in 2024. Although smaller compared to other regions, MEA is seeing steady growth driven by industries such as energy, telecom, and government services. Many organizations in the region face high exposure to cyber risks due to expanding digital ecosystems. It provides them with cost-effective, flexible, and scalable security solutions. Countries like the United Arab Emirates and Saudi Arabia lead adoption in the Middle East, focusing on compliance and modernization. In Africa, South Africa remains a growing market due to its strong banking and telecom sectors. Challenges such as limited digital infrastructure and lower awareness of advanced cybersecurity solutions restrict current adoption levels. However, with ongoing infrastructure development and growing cloud penetration, the region holds strong long-term potential for FWaaS expansion.
Key Player Analysis
- Sophos Ltd. (U.K.)
- Fortinet, Inc. (U.S.)
- Check Point Solution Technologies Ltd. (Israel)
- Forcepoint LLC (U.S.)
- Zscaler, Inc. (U.S.)
- Cato Networks Ltd. (Israel)
- Barracuda Networks, Inc. (U.S.)
- Juniper Networks, Inc. (U.S.)
- Cisco Systems Inc. (U.S.)
- Palo Alto Networks (U.S.)
Competitive Analysis
The Firewall as a Service FWaaS Market players such as Sophos Ltd. (U.K.), Fortinet, Inc. (U.S.), Check Point Solution Technologies Ltd. (Israel), Forcepoint LLC (U.S.), Zscaler, Inc. (U.S.), Cato Networks Ltd. (Israel), Barracuda Networks, Inc. (U.S.), Juniper Networks, Inc. (U.S.), Cisco Systems Inc. (U.S.), and Palo Alto Networks (U.S.). The Firewall as a Service FWaaS Market is becoming increasingly competitive as enterprises demand advanced, flexible, and cost-effective security solutions. Vendors are focusing on developing platforms that combine cloud-native design with features such as AI-driven threat detection, automated policy enforcement, and real-time analytics. The adoption of zero-trust security models and secure access service edge frameworks highlights the market’s shift toward identity-centric and application-aware approaches. Companies operating in diverse industries, from banking to healthcare, prioritize FWaaS to maintain compliance with strict data protection regulations while supporting remote and mobile workforces. The market’s competitiveness is reinforced by constant technological upgrades, integration with hybrid cloud strategies, and increasing awareness of data privacy risks across global regions.
Recent Developments
- In May 2024, Palo Alto Networks launched Prisma SASE 3.0, which provides both managed and unmanaged devices with enhanced Zero Trust security. The release features the first natively integrated enterprise browser in the industry, AI-driven data security, and enhanced application performance, all designed to future-proof and revolutionize workforce security.
- In April 2024, Sonrai Security, a leader in cloud security solutions, unveiled the launch of the industry’s first Cloud Permissions Firewall for AWS, Azure, and Google Cloud. This groundbreaking technology revolutionizes cloud access and permissions security, offering a seamless one-click least privilege solution with zero disruption for cloud operations and development teams.
- In April 2024, Zscaler revealed it agreed to buy Airgap Networks with the goal of advancing Zero Trust Segmentation for IoT/OT devices and sensitive infrastructure. The acquisition will revolutionize enterprise security across campuses, branches, factories, and data centers by doing away with the requirement for traditional firewall-based segmentation.
- In December 2023, Thales acquired Imperva, a U.S. cybersecurity firm focused on application and data security. The acquisition enhances the cybersecurity capability of Thales by the integration of FWaaS capabilities from Imperva.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Service Model, Deployment and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Firewall as a Service FWaaS Market will expand with rising cloud adoption across industries.
- Demand will grow as enterprises strengthen zero-trust and identity-driven security models.
- It will gain importance in securing remote and hybrid workforces.
- Vendors will integrate AI and automation to improve real-time threat detection.
- Multi-cloud and hybrid cloud environments will drive adoption of flexible FWaaS solutions.
- Regulatory compliance and data privacy requirements will remain strong growth drivers.
- Managed services and subscription-based models will increase customer reliance on providers.
- Emerging economies will contribute significantly as digital transformation accelerates.
- Integration with secure access service edge platforms will shape the market’s evolution.
- Investments in scalable, service-driven architectures will reinforce long-term market leadership.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Cybersecurity Threats
The increasing frequency and sophistication of cyberattacks are pushing organizations to adopt advanced, cloud-based firewall solutions that can scale and adapt to evolving risks, making FWaaS a critical component for business continuity and data protection.
Accelerated Cloud Adoption and Remote Workforce Expansion
As enterprises migrate applications and infrastructure to the cloud and support distributed workforces, the need for centralized, flexible, and scalable security frameworks like FWaaS grows, enabling secure access and policy enforcement across diverse environments.
Stringent Regulatory Compliance and Data Privacy Requirements
Strict data protection regulations such as GDPR, HIPAA, and PCI DSS are compelling organizations to implement FWaaS platforms that offer continuous monitoring, automated compliance reporting, and robust data privacy controls.
Cost Efficiency and Scalability of Cloud-Native Security
FWaaS reduces capital expenditure and operational complexity by shifting security to a subscription-based, scalable model, allowing organizations to efficiently manage resources and adapt protection levels as their network needs change.
Integration of AI and Zero-Trust Security Models
The adoption of AI-powered threat detection and zero-trust frameworks within FWaaS platforms enhances real-time protection and identity-based access control, supporting enterprises in proactively defending against advanced threats and securing hybrid environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Firewall as a Service FWaaS Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Firewall as a Service FWaaS Market projected to grow between 2025 and 2032?
Which Firewall as a Service FWaaS Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Firewall as a Service FWaaS Market?
Who are the leading companies in the Firewall as a Service FWaaS Market?
Which region commanded the largest share of the Firewall as a Service FWaaS Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Deployment
- 1.2.1 Public Cloud
- 1.2.2 Private Cloud
- 1.2.3 Hybrid Cloud
- 1.3 By Service Type
- 1.3.1 Traffic Monitoring & Control
- 1.3.2 Compliance & Audit Management
- 1.3.3 Reporting & Log Management
- 1.3.4 Automation & Orchestration
- 1.3.5 Security Management
- 1.3.6 Managed Services
- 1.3.7 Professional Services
- 1.4 By Service Model
- 1.4.1 Infrastructure as a Service
- 1.4.2 Platform as a Service
- 1.4.3 Software as a Service
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.7 billion → 2032: USD 7.1 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Firewall as a Service Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Firewall as a Service Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Firewall as a Service Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Firewall as a Service Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Firewall as a Service Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Firewall as a Service Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Firewall as a Service Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Firewall as a Service Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.7 billion → 2032: USD 7.1 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Firewall as a Service Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Deployment - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Public Cloud
- 12.3.6.2 Private Cloud
- 12.3.6.3 Hybrid Cloud
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Traffic Monitoring & Control
- 12.4.6.2 Compliance & Audit Management
- 12.4.6.3 Reporting & Log Management
- 12.4.6.4 Automation & Orchestration
- 12.4.6.5 Security Management
- 12.4.6.6 Managed Services
- 12.4.6.7 Professional Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Service Model - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Infrastructure as a Service
- 12.5.6.2 Platform as a Service
- 12.5.6.3 Software as a Service
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Firewall as a Service Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Firewall as a Service Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Firewall as a Service Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Cisco Systems Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Fortinet, Inc.
- 17.4 Palo Alto Networks
- 17.5 Zscaler, Inc.
- 17.6 Sophos Ltd.
- 17.7 Check Point Solution Technologies Ltd.
- 17.8 Forcepoint LLC
- 17.9 Barracuda Networks, Inc.
- 17.10 Juniper Networks, Inc.
- 17.11 Cato Networks Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

