
Industrial Belt Scale Market Overview:
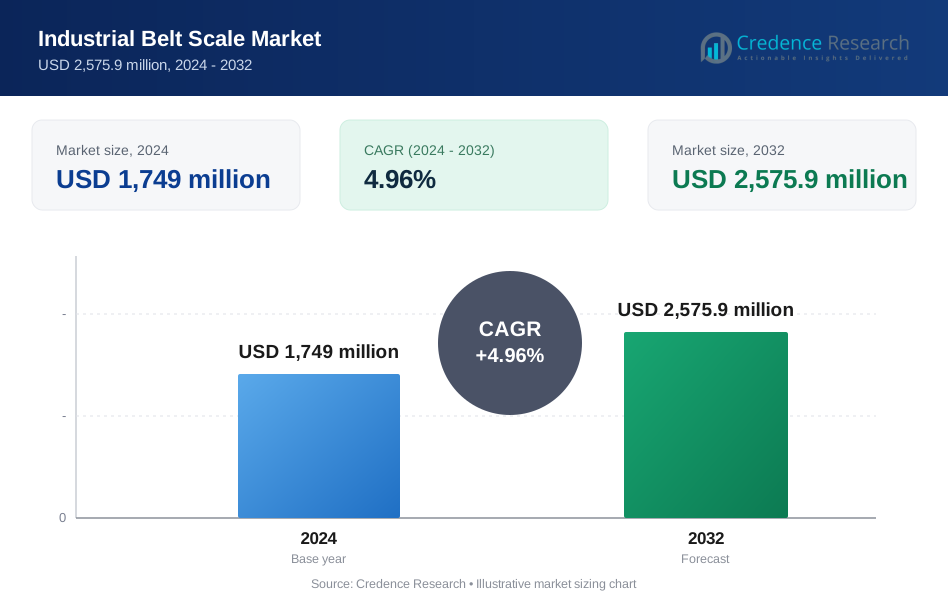
The industrial belt scale market was valued at USD 1,749 million in 2024 and is projected to reach USD 2,575.9 million by 2032, expanding at a CAGR of 4.96% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Belt Scale Market Size 2024 | USD 1,749 million |
| Industrial Belt Scale Market, CAGR | 4.96% |
| Industrial Belt Scale Market Size 2032 | USD 2,575.9 million |
Industrial Belt Scale Market Insights
- Market growth is driven by rising demand for continuous material flow measurement, automation, and process optimization in mining, cement, power generation, and bulk material handling industries, where belt scales enable real-time monitoring, inventory control, and operational efficiency.
- Key trends include increasing adoption of electronic load-cell belt scales, which hold the dominant technology share, and growing uptake of smart and IoT-enabled systems for remote monitoring and predictive maintenance, while multi-idler belt scales lead the idler-type segment due to higher accuracy.
- The competitive landscape is moderately consolidated, with global players focusing on product innovation, modular designs, digital integration, and aftersales services, while regional and mid-sized manufacturers compete through cost-effective and retrofit-friendly solutions.
- Regionally, Asia Pacific leads with ~32% market share, followed by North America (~28%) and Europe (~24%), driven by industrial expansion, infrastructure development, and strong replacement demand, while Latin America and the Middle East & Africa together account for the remaining share.

Industrial Belt Scale Market Segmentation Analysis:
By Idler / Scale Type
By idler and scale type, multi-idler belt scales represent the dominant sub-segment, accounting for the largest market share due to their superior accuracy in measuring bulk materials over long conveyor spans. These systems distribute load across multiple idlers, reducing the impact of belt tension variation and material load fluctuations, which is critical in mining, cement, and power generation applications. Single- and dual-idler scales remain prevalent in cost-sensitive or low-throughput installations, while triple-idler designs gain traction in heavy-duty operations. Fixed-frame belt scales dominate permanent installations, whereas modular belt scales are increasingly adopted for retrofit flexibility and faster deployment.
- For instance, Schenck Process supplies multi-idler belt scale frames configured with three and four idler stations designed for belt widths up to 2,400 mm and continuous material flow rates exceeding 10,000 t/h, enabling reliable measurement on long overland conveyors used in iron ore and coal handling systems.
By Technology
By technology, electronic load-cell belt scales dominate the market, driven by their high measurement accuracy, reliability, and compatibility with automated process control systems. These systems are widely deployed across large-scale industrial operations where real-time data integration with PLC and SCADA platforms is essential. Smart and IoT-enabled belt scales represent the fastest-growing sub-segment, supported by rising demand for predictive maintenance, remote monitoring, and data-driven optimization. Mechanical belt scales maintain relevance in basic applications with minimal power or digital infrastructure, while hybrid digital–mechanical systems serve transitional markets seeking improved accuracy without full system upgrades.
- For instance, Siemens supplies Milltronics electronic belt scale systems such as the heavy-duty MSI and MMI models utilizing stainless-steel load cells which are available in various capacities, ranging from 25 lbs to 2,000 lbs (approximately 11.3 kg to 907.2 kg) per sensing element.
By Conveyor Belt Width
By conveyor belt width, the 500-1200 mm segment holds the dominant market share, reflecting its widespread use across cement plants, mining conveyors, aggregates handling, and industrial material transport systems. This width range balances material throughput, mechanical stability, and cost efficiency, making it suitable for both new installations and retrofits. Belts below 500 mm are mainly used in light-duty and niche industrial processes, while the 1200–2000 mm segment supports high-capacity bulk handling. Conveyors above 2000 mm are limited to large-scale mining and port terminals, where extreme throughput requirements justify higher system complexity and cost.
Key Growth Drivers
Rising Demand for Process Automation and Operational Efficiency
Industrial operations increasingly prioritize automation to improve throughput, reduce human intervention, and enhance measurement accuracy in bulk material handling. Belt scales play a critical role in enabling continuous, real-time mass flow measurement, supporting automated control of production and logistics processes. Industries such as mining, cement, power generation, and ports rely on belt scales to optimize material feeding, blending, and inventory reconciliation. As plants pursue higher utilization rates and tighter process control, belt scales become integral to closed-loop automation systems connected to PLC and SCADA platforms. This demand is further reinforced by the need to minimize material losses, reduce rework, and improve yield consistency, positioning belt scales as essential instrumentation rather than optional equipment.
- For instance, Thermo Fisher Scientific (through its Ramsey brand) supplies belt scale electronics, such as the Ramsey Flex Digitizer, capable of processing continuous load signals at a sampling rate of 100 measurements per second (100 Hz), supporting precise feed control on overland conveyors exceeding 1,500 m (4,000 ft digitizer to integrator distance) in length at iron ore and copper mining sites".
Expansion of Mining, Cement, and Infrastructure Projects
Ongoing expansion in mining, cement, steel, and infrastructure development continues to drive demand for conveyor-based material handling systems, directly supporting belt scale adoption. Large-scale projects require accurate, continuous measurement of ores, clinker, coal, and aggregates across long conveyor networks. Belt scales enable precise production monitoring, regulatory reporting, and cost control in these capital-intensive industries. Emerging economies, in particular, are investing heavily in mining capacity and infrastructure, creating sustained demand for new conveyor installations and associated weighing systems. In mature markets, modernization and capacity upgrades further contribute to steady replacement and retrofit demand for advanced belt scale solutions.
- For instance, FLSmidth integrates electronic belt scale assemblies into its cement plant material handling lines, with systems (such as the Pfister® MULTIBELT) engineered for clinker conveyors operating at typical belt speeds of up to 1.25 m/s and ambient temperatures generally reaching 40 °C, enabling reliable mass flow measurement from preheater discharge to storage silos.
Increasing Focus on Cost Control and Material Accountability
Industrial operators face growing pressure to control operating costs and improve material accountability across complex supply chains. Belt scales support accurate mass balance calculations, production reporting, and billing reconciliation, especially in industries handling high-value or high-volume bulk materials. Accurate weighing helps identify process inefficiencies, detect losses, and prevent overfeeding or underfeeding of materials. As margin pressures intensify, companies increasingly view belt scales as tools for financial control and operational transparency rather than purely measurement devices. This shift in perception strengthens long-term demand across both greenfield projects and brownfield upgrades.
Key Trends & Opportunities
Adoption of Smart and IoT-Enabled Belt Scales
The integration of smart sensors, connectivity, and analytics is transforming traditional belt scales into intelligent monitoring systems. IoT-enabled belt scales provide real-time performance data, remote diagnostics, and predictive maintenance insights, reducing unplanned downtime and maintenance costs. These capabilities align with broader Industry 4.0 initiatives, where data-driven decision-making improves plant efficiency and asset utilization. As digital infrastructure adoption accelerates across industrial facilities, smart belt scales present significant growth opportunities, particularly in large, distributed conveyor networks where manual inspection is inefficient.
- For instance, Yokogawa Electric Corporation integrates various IoT-enabled sensors, such as wireless vibration sensors and fiber optic temperature sensors (DTSX), into its OpreX control architecture. This enables the remote supervision of extensive conveyor lines (extending over 10 km) in port and bulk terminal applications, significantly reducing the need for manual, on-site inspection while providing continuous operational visibility and supporting predictive maintenance."
Growing Retrofit and Modular Installation Demand
A notable trend is the increasing preference for modular and retrofit-friendly belt scale designs. Many operators seek to upgrade existing conveyors without extended shutdowns or structural modifications. Modular belt scales enable faster installation, easier calibration, and scalability, making them attractive for operational plants. This trend opens opportunities for suppliers to target replacement markets, especially in aging industrial facilities where conveyor systems remain mechanically sound but measurement technology requires modernization.
- For instance, Rice Lake Weighing Systems’ Master™ 221DB and 211 belt scale weigh frames are designed for installation on existing conveyor structures with belt widths ranging from 450 mm to 1,800 mm (18 to 72 inches) and operating speeds typically up to 4 m/s.
Key Challenges
Accuracy Limitations Due to Installation and Operating Conditions
Achieving and maintaining measurement accuracy remains a key challenge for belt scale systems. Factors such as belt tension variation, misalignment, material build-up, and inconsistent loading profiles can significantly affect performance. Inadequate installation practices or insufficient calibration further exacerbate accuracy issues. These challenges increase the need for skilled installation, commissioning, and ongoing maintenance, which can raise total ownership costs and limit adoption among smaller operators with limited technical expertise.
High Initial Investment and Maintenance Requirements
The upfront cost of industrial belt scale systems, particularly multi-idler and smart-enabled configurations, can be a barrier for cost-sensitive end users. Beyond equipment costs, expenses related to installation, calibration, and periodic verification add to the overall investment. In harsh operating environments, components are subject to wear, vibration, and contamination, increasing maintenance demands. These factors can delay purchasing decisions or encourage continued use of lower-accuracy alternatives, especially in smaller or less automated facilities.
Regional Analysis
North America
North America accounts for approximately 28% of the global industrial belt scale market, supported by advanced automation adoption across mining, aggregates, power generation, and bulk material logistics. The United States dominates regional demand due to extensive use of conveyor-based handling in coal, metals, and cement industries, along with strong replacement demand from aging infrastructure. High emphasis on process optimization, material accountability, and integration with PLC/SCADA systems sustains steady adoption of multi-idler and electronic load-cell belt scales. Canada contributes through mining operations, while ports and terminals further support demand for high-capacity, high-accuracy belt scale installations.
Europe
Europe holds an estimated 24% market share, driven by strict operational efficiency standards, mature industrial automation, and strong emphasis on precision measurement. Germany, the UK, France, and Italy lead demand due to well-established cement, chemicals, and bulk manufacturing sectors. The region shows high penetration of multi-idler and fixed-frame belt scales in permanent installations. Sustainability initiatives and energy efficiency targets further encourage accurate material tracking and reporting. Retrofit demand is particularly strong, as industrial operators upgrade legacy mechanical systems to electronic and hybrid belt scales without major conveyor modifications.
Asia Pacific
Asia Pacific represents the largest regional market with around 32% share, driven by rapid industrialization, infrastructure expansion, and large-scale mining and cement production. China and India dominate regional demand due to extensive conveyor usage in coal handling, steel manufacturing, and construction materials. Southeast Asia and Australia further contribute through mining and port operations. High-volume material handling requirements favor multi-idler and wide-belt scale systems. While electronic load-cell belt scales dominate new installations, cost-sensitive markets continue adopting modular and hybrid systems, supporting broad-based growth across both greenfield and retrofit projects.
Latin America
Latin America accounts for approximately 9% of the global market, led by mining-intensive economies such as Chile, Brazil, and Peru. Belt scales are widely used in copper, iron ore, and aggregates operations to support production monitoring and export logistics. Infrastructure development and port modernization projects are strengthening demand for conveyor weighing systems. However, budget constraints often drive preference for modular and dual-idler configurations. Replacement and calibration services also represent a notable portion of demand, as operators seek to improve accuracy and compliance without fully replacing existing conveyor systems.
Middle East & Africa
The Middle East & Africa region holds around 7% market share, supported by mining activity, cement production, and bulk material handling in ports and industrial zones. Countries such as South Africa, Saudi Arabia, and the UAE lead regional demand. Large cement plants and mining operations favor fixed-frame and multi-idler belt scales for continuous production monitoring. Infrastructure investment and industrial diversification initiatives are gradually increasing adoption. However, market growth remains moderated by limited automation penetration in parts of Africa, where mechanical and hybrid belt scales continue to see sustained usage.
Industrial Belt Scale Market Segmentations:
By Idler / Scale Type
- Single-Idler
- Multi-Idler
- Dual-Idler
- Triple-Idler
- Fixed-Frame Belt Scale
- Modular Belt Scale
By Technology
- Electronic Load-Cell Belt Scales
- Smart / IoT-Enabled Belt Scales
- Mechanical Belt Scales
- Hybrid Digital-Mechanical Belt Scales
By Conveyor Belt Width
- Below 500 mm
- 500-1200 mm
- 1200-2000 mm
- Above 2000 mm
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The industrial belt scale market features a moderately consolidated competitive landscape characterized by the presence of global weighing technology providers and specialized industrial instrumentation manufacturers. Leading companies compete on measurement accuracy, system reliability, durability in harsh operating environments, and integration capabilities with automation and control systems. Market participants continue to focus on expanding electronic load-cell and multi-idler belt scale portfolios to address high-capacity and high-accuracy applications. Strategic priorities include product innovation, modular designs for retrofit installations, and digital enhancements such as remote diagnostics and data connectivity. Companies also strengthen their market positions through long-term service contracts, calibration support, and regional distribution networks. Emerging players compete by offering cost-effective solutions tailored to mid-scale operations, while established manufacturers leverage brand reputation, technical expertise, and global service presence to secure large industrial and infrastructure projects.
Key Player Analysis
- Minebea Intec
- Merrick Industries
- Thermo Fisher Scientific
- Rice Lake Weighing Systems
- Yamato Scale
- Schenck Process
- Tecweigh / Tecnetics Industries
- Mettler-Toledo
- Thayer Scale
- Siemens
Recent Developments
- In November 2025, Minebea Intec expanded the MiNexx® product family with next-generation weighing indicators and floor scales that improve connectivity and measurement precision, reflecting ongoing enhancements to its industrial weighing portfolio.
- In June 2025, Rice Lake Weighing Systems launched the SCT-4XD belt scale digitizer, a digital processing unit for bulk material weighing that enhances data capture and system responsiveness for in-motion belt scales.
Report Coverage
The research report offers an in-depth analysis based on Idler / Scale Type, Technology, Conveyor Belt Width and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Industrial belt scales will see wider adoption as industries increase automation and rely on continuous, real-time material flow measurement.
- Demand will strengthen for high-accuracy multi-idler belt scales in mining, cement, and bulk material handling operations.
- Smart and IoT-enabled belt scales will gain traction as operators prioritize remote monitoring and predictive maintenance.
- Integration with PLC, SCADA, and plant-wide digital platforms will become a standard requirement.
- Retrofit and modular belt scale solutions will expand as operators upgrade existing conveyor systems with minimal downtime.
- Accuracy improvement technologies, including advanced load cells and signal processing, will drive product differentiation.
- Growth in infrastructure, mining, and port capacity will support sustained installation of conveyor weighing systems.
- Service, calibration, and lifecycle support offerings will play a larger role in vendor competitiveness.
- Adoption will increase in emerging economies as industrial material handling systems expand.
- Manufacturers will focus on rugged designs to ensure reliability in harsh and high-load operating environments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the industrial belt scale market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the industrial belt scale market projected to grow between 2024 and 2032?
Which industrial belt scale segment held the largest share in 2024?
What are the primary factors fueling the growth of the industrial belt scale market?
Who are the leading companies in the industrial belt scale market?
Which region commanded the largest share of the industrial belt scale market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Industrial Belt Scale Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Industrial Belt Scale Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,749 million → 2032: USD 2,575.9 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Industrial Belt Scale Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Industrial Belt Scale Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Industrial Belt Scale Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Industrial Belt Scale Market Drivers
- 3.3 Industrial Belt Scale Market Restraints & Challenges
- 3.4 Industrial Belt Scale Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Industrial Belt Scale Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Industrial Belt Scale Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Industrial Belt Scale category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Industrial Belt Scale Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Industrial Belt Scale Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Industrial Belt Scale market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Industrial Belt Scale Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Industrial Belt Scale Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Industrial Belt Scale Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Industrial Belt Scale (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Industrial Belt Scale Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Industrial Belt Scale Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Industrial Belt Scale Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Industrial Belt Scale Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Industrial Belt Scale Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Industrial Belt Scale Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Industrial Belt Scale Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Industrial Belt Scale Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Industrial Belt Scale Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
