
Market Overview:
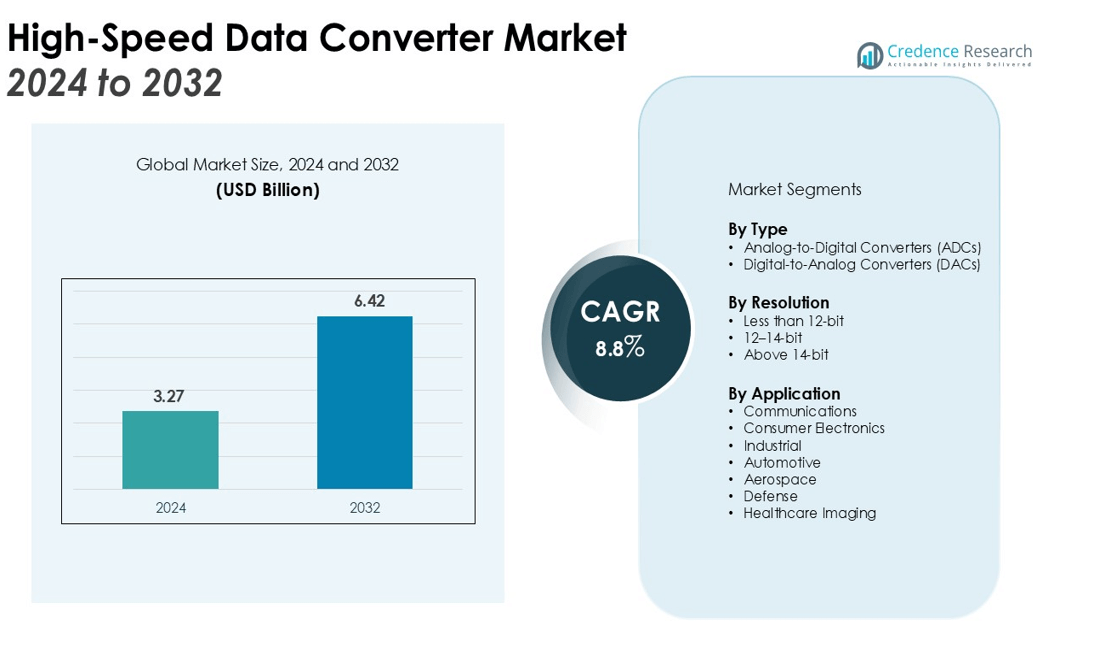
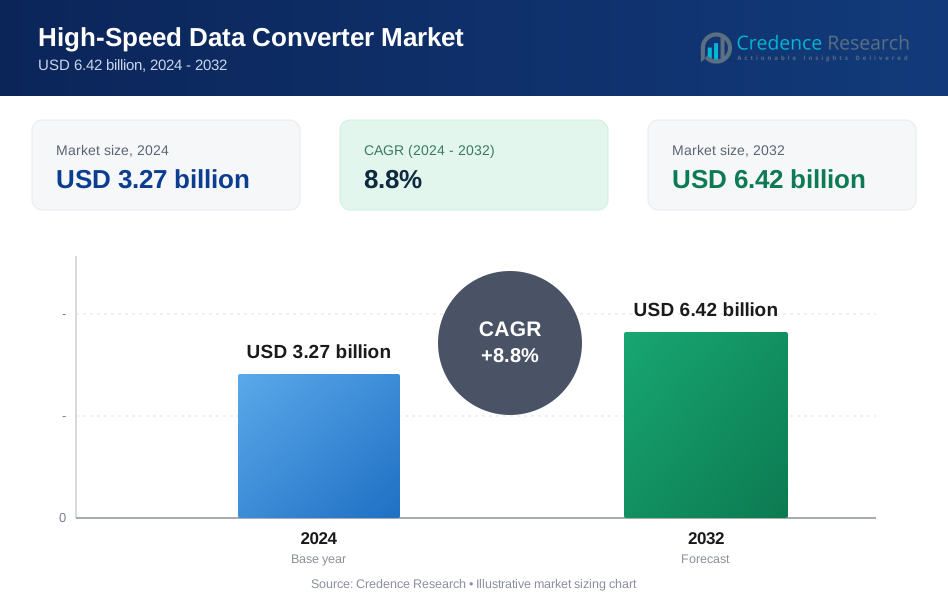
The High-Speed Data Converter Market size was valued at USD 3.27 billion in 2024 and is anticipated to reach USD 6.42 billion by 2032, at a CAGR of 8.8% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| High-Speed Data Converter Market Size 2024 | USD 3.27 billion |
| High-Speed Data Converter Market, CAGR | 8.8% |
| High-Speed Data Converter Market Size 2032 | USD 6.42 billion |
Market growth is fueled by the increasing deployment of 5G infrastructure, rising demand for data centers, and accelerating adoption of IoT devices. High-Speed converters enable efficient digitization in mission-critical applications such as aerospace, defense, and industrial automation. The demand for real-time processing in automotive systems and healthcare imaging is also boosting usage. Moreover, advances in semiconductor technologies are reducing power consumption while increasing performance, making these converters viable for broader commercial applications.
Regionally, North America dominates the High-Speed Data Converter Market due to strong investments in defense electronics, 5G deployment, and advanced semiconductor design. Europe follows, supported by aerospace and industrial automation demand. Asia-Pacific is expected to post the fastest growth, led by China, Japan, and South Korea, driven by rapid network expansion, electronics manufacturing, and growing semiconductor capabilities. Growing collaborations between semiconductor companies and research institutions are further driving technological advancements and strengthening global competitiveness.
Market Insights:
- The High-Speed Data Converter Market was valued at USD 3.27 billion in 2024 and is projected to reach USD 6.42 billion by 2032, growing at a CAGR of 8.8%.
- Rising 5G infrastructure deployment and surging demand from data centers and IoT ecosystems are major growth drivers.
- Aerospace, defense, and automotive sectors are increasing adoption, with converters supporting radar, secure networks, and advanced driver assistance systems.
- Healthcare imaging and industrial automation rely on high-speed converters for real-time processing and precision applications.
- Challenges remain due to high development costs, design complexity, and thermal management in compact systems.
- North America leads the market with 38% share, supported by defense, aerospace, and extensive 5G rollout.
- Asia-Pacific, holding 24% share, is the fastest-growing region, driven by electronics manufacturing, 5G expansion, and government-backed semiconductor investments.
Market Drivers:
Rising Demand from 5G Infrastructure and Communication Networks
The High-Speed Data Converter Market is witnessing strong growth driven by the deployment of 5G infrastructure worldwide. These converters are essential for supporting massive data traffic, low latency, and higher bandwidth needs. Telecom operators rely on them for efficient signal conversion in base stations and advanced communication systems. Growing demand for high-performance wireless connectivity is creating consistent opportunities for adoption.
- For instance, the RF front-end of massive MIMO 5G base stations often incorporates large antenna arrays with 32 or 64 elements to improve capacity.
Expanding Role in Data Centers and Cloud Computing
Data centers are a major driver of the High-Speed Data Converter Market due to rising global data volumes. It enables high-speed digitization and processing required for cloud services and AI workloads. Organizations investing in scalable and energy-efficient infrastructure are boosting demand for advanced converter solutions. The rapid adoption of edge computing further increases reliance on high-performance converters.
- For instance, Texas Instruments is collaborating with NVIDIA to develop 800V high-voltage DC power distribution systems for the next generation of AI data centers.
Increased Application in Aerospace, Defense, and Automotive
Aerospace and defense sectors utilize High-Speed converters for radar, satellite communication, and secure networks. The automotive industry also demands them for advanced driver assistance systems and real-time processing. It supports safety-critical functions, autonomous vehicle technologies, and high-resolution imaging systems. The combination of defense modernization and smart mobility drives steady growth in this segment.
Technological Advancements and Power Efficiency Improvements
Continuous advancements in semiconductor technologies are enhancing the performance of High-Speed converters. It includes improvements in sampling rates, resolution, and power efficiency, making products suitable for broader applications. Manufacturers are focusing on integrating converters into smaller and more efficient designs. These innovations strengthen adoption across healthcare imaging, industrial automation, and consumer electronics.
Market Trends:
Integration with Emerging Technologies and Advanced Applications
The High-Speed Data Converter Market is experiencing significant momentum through integration with emerging technologies such as artificial intelligence, machine learning, and edge computing. These converters are enabling real-time data processing and analytics across critical applications, including autonomous driving, industrial automation, and smart healthcare systems. It supports higher sampling rates and resolution to meet the demand for precision in data-intensive environments. The adoption of 5G and future 6G networks is further pushing the need for high performance in communication infrastructure. The trend toward miniaturization of devices and the growth of IoT ecosystems are also accelerating demand. Vendors are aligning innovation strategies to match these evolving industry requirements.
- For instance, Texas Instruments' THS1206 is a high-speed data converter with 12-bit resolution and a maximum conversion rate of 6 Mega Samples Per Second (MSPS), making it suitable for high-speed data acquisition in applications like radar and communications.
Shift Toward Low-Power and High-Performance Architectures
Another key trend shaping the High-Speed Data Converter Market is the shift toward designs that balance high performance with low power consumption. Semiconductor companies are focusing on developing architectures that deliver energy efficiency without sacrificing processing speed or accuracy. It reflects growing requirements in portable devices, wearables, and mobile communication systems. Healthcare imaging and aerospace applications are also adopting these innovations to reduce system costs and enhance reliability. Continuous research in advanced packaging and integration is expanding design possibilities for next-generation converters. This trend is expected to open new opportunities across diverse end-use sectors over the forecast period.
- For example, NTT developed a high-speed, low-power digital-to-analog converter (DAC) using Indium Phosphide (InP) HBT technology, which operates at a sampling rate of up to 28 Giga-Samples per second (GS/s) while consuming only 0.95W.
Market Challenges Analysis:
High Development Costs and Design Complexity
The High-Speed Data Converter Market faces challenges due to the high cost of development and increasing design complexity. Advanced converters require significant investment in research, testing, and semiconductor fabrication. It demands specialized expertise to achieve high sampling rates and resolution without compromising power efficiency. Smaller manufacturers struggle to compete with established players that have larger R&D budgets. The complexity of integrating converters into compact devices also increases production costs and time-to-market. These factors can limit adoption across price-sensitive sectors.
Thermal Management and Performance Limitations
Thermal management remains a critical challenge for the High-Speed Data Converter Market as converters operate at high speeds. Excessive heat can impact performance, reduce reliability, and shorten device lifespan. It requires advanced cooling solutions and energy-efficient designs to address these concerns. Power consumption also remains a limiting factor in portable and battery-operated applications. Meeting performance expectations while ensuring durability is a constant challenge for manufacturers. Continuous pressure to deliver higher efficiency within smaller form factors further complicates design optimization efforts.
Market Opportunities:
Expansion into Emerging 5G and 6G Infrastructure
The High-Speed Data Converter Market holds strong opportunities in the expansion of global 5G networks and the development of 6G. Telecom operators require advanced converters to support higher bandwidth, faster signal conversion, and lower latency. It enables efficient processing for base stations, small cells, and satellite communication systems. Governments and enterprises investing in digital infrastructure will further boost demand. The growing reliance on seamless connectivity in smart cities and IoT ecosystems strengthens the role of high-speed converters. This creates a sustained growth path for manufacturers targeting telecom and communication sectors.
Growth Potential in Healthcare and Automotive Applications
Healthcare and automotive industries are creating new avenues for the High-Speed Data Converter Market with their increasing reliance on real-time processing. Medical imaging systems demand high-resolution converters to improve diagnostic accuracy. It supports critical applications such as MRI, CT scans, and portable imaging devices. In the automotive sector, converters play a vital role in advanced driver assistance systems, autonomous vehicles, and in-vehicle connectivity. Expanding electric and connected vehicle adoption accelerates this trend. Rising investments in smart mobility and healthcare digitization will generate long-term opportunities for high-speed converter suppliers.
Market Segmentation Analysis:
By Type
The High-Speed Data Converter Market is segmented into analog-to-digital converters (ADCs) and digital-to-analog converters (DACs). ADCs hold a major share due to their vital role in telecommunications, data centers, and defense applications where high-frequency signals must be captured accurately. DACs are also gaining traction in wireless communication, test equipment, and audio-visual systems. It benefits from increasing demand for real-time processing across diverse industries.
By Resolution
Segmentation by resolution includes converters with less than 12-bit, 12–14-bit, and above 14-bit categories. High-resolution converters above 14-bit are expanding rapidly, driven by healthcare imaging, aerospace, and precision industrial automation. Converters in the 12–14-bit range remain widely adopted in automotive and communication infrastructure for balancing speed and efficiency. It continues to witness demand for lower-bit converters in cost-sensitive consumer electronics and portable devices.
- For instance, in medical imaging, ABLIC’s high-voltage linear transmit pulsers for ultrasound equipment demonstrate high-resolution performance, these components can generate a ±90V arbitrary output waveform, which helps create high-quality diagnostic images.
By Application
Key applications span communications, consumer electronics, industrial, automotive, aerospace, and defense. Communication leads the High-Speed Data Converter Market with strong reliance on converters for 5G networks and data-intensive transmission systems. Industrial and automotive applications are growing due to the rise of smart factories and connected vehicles. Aerospace and defense use converters for radar, electronic warfare, and satellite systems. It is also benefiting from rising demand in medical imaging, where high-speed and high-resolution data conversion supports diagnostic accuracy.
- For instance, Texas Instruments’ DAC38RF82 serves the 5G communications sector with high-speed performance, this RF-sampling digital-to-analog converter is capable of operating with an input data rate of up to 9 Giga-samples-per-second (GSPS) to synthesize wideband signals.
Segmentations:
By Type
- Analog-to-Digital Converters (ADCs)
- Digital-to-Analog Converters (DACs)
By Resolution
- Less than 12-bit
- 12–14-bit
- Above 14-bit
By Application
- Communications
- Consumer Electronics
- Industrial
- Automotive
- Aerospace
- Defense
- Healthcare Imaging
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Leading with Strong Technological Adoption
North America accounts for 38% share of the High-Speed Data Converter Market, making it the largest regional contributor. The strong presence of semiconductor leaders and extensive 5G deployment reinforce this dominance. The region benefits from defense and aerospace industries that depend on high-speed digitization for secure communication. It is also supported by continuous growth in data centers and cloud computing services. Research institutions and technology firms drive product innovation and ensure advanced adoption across applications. The reliance on real-time data processing continues to secure North America’s leadership in this market.
Europe Advancing Through Industrial and Aerospace Demand
Europe holds 28% share of the High-Speed Data Converter Market, driven by its strong aerospace and industrial automation base. Leading economies such as Germany, France, and the United Kingdom spearhead adoption through advanced manufacturing and defense modernization programs. It benefits from rising integration in radar technologies, test equipment, and industrial systems that require precision. Regional focus on sustainable designs and energy efficiency further strengthens the use of high-speed converters. Collaborations between technology firms and research institutes continue to improve innovation pipelines. These factors maintain Europe as a key global contributor.
Asia-Pacific Emerging as the Fastest-Growing Market
Asia-Pacific commands 24% share of the High-Speed Data Converter Market and is positioned as the fastest-growing regional hub. Strong manufacturing ecosystems in China, Japan, South Korea, and Taiwan support large-scale adoption. It benefits from accelerated 5G rollout, consumer electronics demand, and healthcare digitization. Expanding applications in smart mobility and IoT devices fuel consistent growth across industries. Government-backed investments in semiconductor capabilities strengthen the region’s competitiveness. These combined factors ensure Asia-Pacific remains the most dynamic growth engine in this market.
Key Player Analysis:
- Analog Devices, Inc.
- Asahi Kasei Microdevices Corporation
- Caelus Technology Limited
- Cirrus Logic, Inc.
- DigiKey
- Faraday Technology Corporation
- GlobalSpec
- Infineon Technologies AG
- Microchip Technology Inc.
- Omni Design Technologies, Inc.
- Renesas Electronics Corporation.
- ROHM Co., Ltd.
Competitive Analysis:
The High-Speed Data Converter Market is characterized by strong competition among global semiconductor leaders focusing on innovation, scalability, and performance optimization. Companies are investing heavily in R&D to enhance converter resolution, sampling rates, and power efficiency. It is witnessing strategic collaborations between semiconductor firms and research institutions to accelerate product development and expand application areas. Leading players are strengthening portfolios with integrated solutions tailored for 5G infrastructure, aerospace, defense, and healthcare imaging. Market competition is further shaped by the push toward miniaturization and low-power architectures to meet demand in automotive and consumer electronics. Regional players are also entering the space with specialized offerings, intensifying rivalry and creating opportunities for partnerships. Pricing strategies, product differentiation, and continuous technology upgrades remain critical factors in defining competitive advantage within this market.
Recent Developments:
- In August 2025, Analog Devices, Inc. announced its support for 800 VDC data center architectures to advance AI infrastructure.
- In May 2025, Asahi Kasei Microdevices Corporation partnered with Dirac to integrate Dirac's AudioIQ software into its automotive audio digital signal processors (DSPs), like the AK7709.
- In June 2025, Cirrus Logic, Inc. launched a new line of professional-grade analog-to-digital converters (ADCs) and digital-to-analog converters (DACs).
Report Coverage:
The research report offers an in-depth analysis based on Type, Resolution, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The High-Speed Data Converter Market will expand with rising demand for 5G and next-generation networks.
- Growing reliance on cloud computing and data centers will continue to drive converter adoption.
- Real-time processing requirements in autonomous vehicles will strengthen demand for advanced converters.
- Healthcare imaging systems will rely on high-resolution converters to enhance diagnostic accuracy.
- Aerospace and defense applications will increasingly use converters for radar, satellite, and secure communications.
- Integration of converters into compact, low-power designs will create opportunities in portable devices.
- The rise of IoT ecosystems will push manufacturers to deliver high-speed and energy-efficient solutions.
- Semiconductor innovation will improve performance, reduce latency, and enable broader industrial applications.
- Collaborations between global firms and regional manufacturers will accelerate product development and supply chain resilience.
- Expansion in Asia-Pacific, supported by strong electronics manufacturing, will shape the next growth phase of this market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for High-Speed Data Converter, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the High-Speed Data Converter Market projected to grow between 2024 and 2032?
Which High-Speed Data Converter Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the High-Speed Data Converter Market?
Who are the leading companies in the High-Speed Data Converter Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 High-Speed Data Converter Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global High-Speed Data Converter Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3.27 billion → 2032: USD 6.42 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 High-Speed Data Converter Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. High-Speed Data Converter Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 High-Speed Data Converter Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 High-Speed Data Converter Market Drivers
- 3.3 High-Speed Data Converter Market Restraints & Challenges
- 3.4 High-Speed Data Converter Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 High-Speed Data Converter Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 High-Speed Data Converter Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, High-Speed Data Converter category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 High-Speed Data Converter Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. High-Speed Data Converter Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the High-Speed Data Converter market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 High-Speed Data Converter Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 High-Speed Data Converter Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 High-Speed Data Converter Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in High-Speed Data Converter (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New High-Speed Data Converter Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global High-Speed Data Converter Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America High-Speed Data Converter Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe High-Speed Data Converter Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific High-Speed Data Converter Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America High-Speed Data Converter Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East High-Speed Data Converter Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa High-Speed Data Converter Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. High-Speed Data Converter Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
