
Market Overview
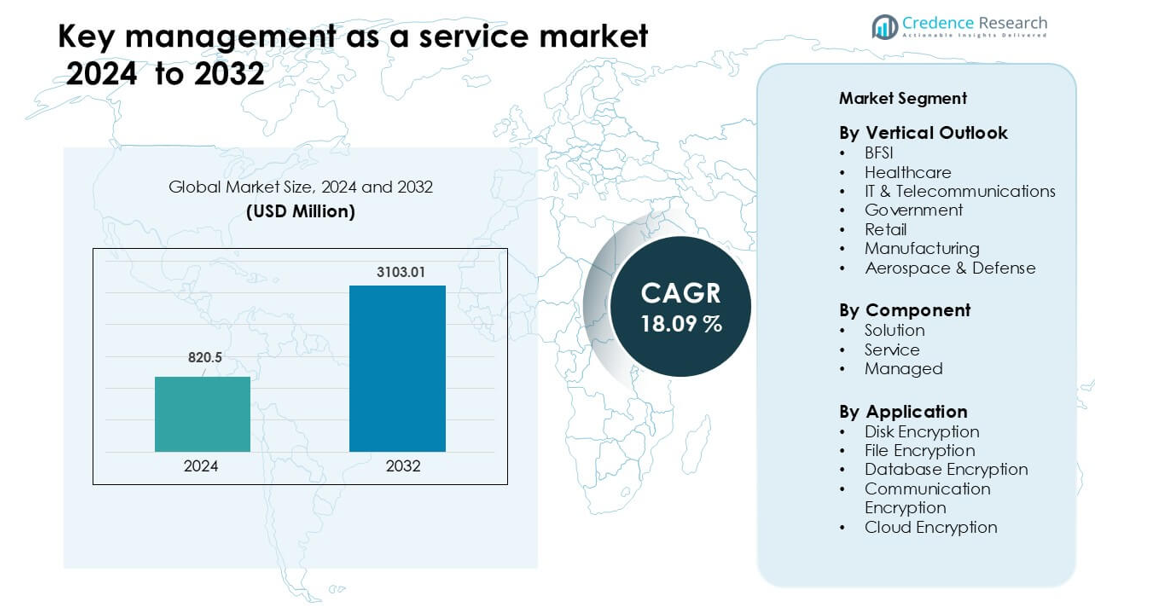
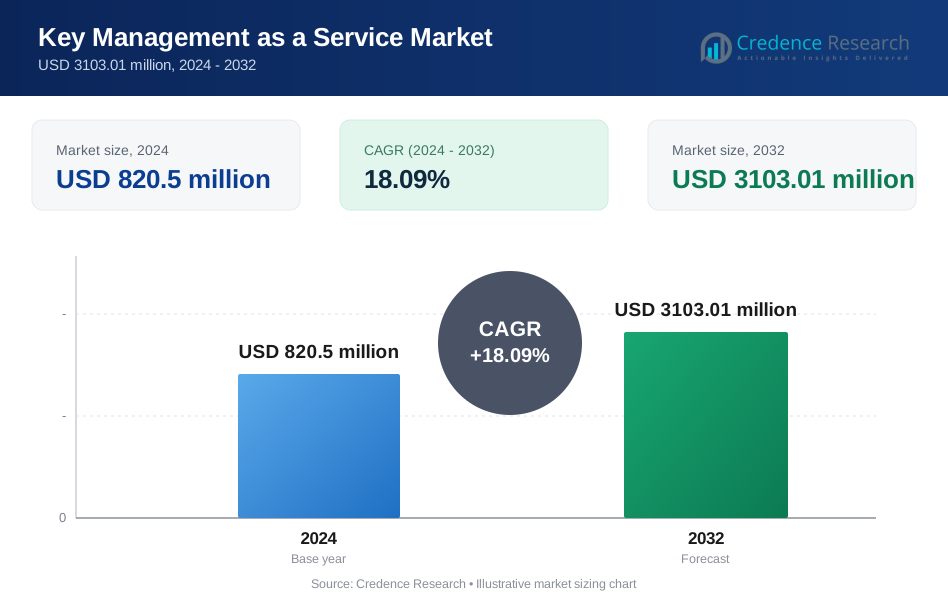
Key management as a service market was valued at USD 820.5 million in 2024 and is anticipated to reach USD 3103.01 million by 2032, growing at a CAGR of 18.09 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Key Management as a Service Market Size 2024 | USD 820.5 million |
| Key Management as a Service Market, CAGR | 18.09% |
| Key Management as a Service Market Size 2032 | USD 3103.01 million |
The key management as a service market is shaped by major players such as IBM Corporation, CipherCloud, Unbound Tech, Google, Thales (Gemalto), Intel Corporation, Sepior ApS, Egnyte, and KeyNexus Inc. These companies lead through advanced cloud integration, stronger encryption controls, and support for multi-cloud security needs. Their focus on automation, compliance readiness, and scalable key orchestration strengthens global adoption. North America remained the leading region in 2024 with 38% share, driven by strict data protection rules, high cloud usage, and strong investments from BFSI, healthcare, and technology sectors.
Market Insights
- The key management as a service market reached USD 820.5 million in 2024 and is anticipated to reach USD 3103.01 million by 2032, growing at a CAGR of 18.09 % during the forecast period.
- Strong demand came from the BFSI segment, which held about 31% share due to strict compliance needs and heavy cloud adoption across financial systems.
- Multi-cloud expansion and zero-trust security frameworks shaped major trends, pushing firms to shift toward centralized and automated key handling platforms.
- Competition intensified as IBM Corporation, CipherCloud, Unbound Tech, Google, Thales (Gemalto), and Intel Corporation advanced cloud-ready encryption tools with faster key rotation and strong compliance support.
- North America led with 38% share, driven by strict data protection laws and high cloud usage, while Asia-Pacific grew fastest as enterprises expanded digital infrastructure and strengthened cybersecurity spending.
Market Segmentation Analysis:
By Vertical Outlook
The BFSI segment led the key management as a service market in 2024 with about 31% share. Banks and insurers drove demand due to rising cloud migration, higher digital transaction volumes, and strict data protection mandates. Healthcare and IT & telecommunications recorded steady gains as providers secured patient data, electronic records, and large communication networks. Government and defense agencies expanded adoption to safeguard classified data and support national cybersecurity programs. Retail and manufacturing followed as these sectors increased reliance on connected systems and required stronger protection for customer and operational data.
- For instance, one of India’s largest private banks—with over 43 million customers and 5,430 branches uses Thales’ CipherTrust Cloud Key Manager to manage encryption keys across AWS and Azure, gaining full visibility into when and how their keys are generated, used, and retired.
By Component
The solution segment dominated the key management as a service market in 2024 with nearly 54% share. Firms selected scalable key lifecycle tools to support encryption-heavy workloads and meet compliance goals. Services grew as organizations sought expert deployment support and rapid integration with cloud platforms. Managed key management advanced due to rising preferences for outsourced security operations that reduce internal workloads. Demand across all components increased as companies handled more sensitive data and adopted multi-cloud environments that required centralized cryptographic control.
- For instance, Thales’ CipherTrust Cloud Key Manager supports automated key rotation jobs: organizations can schedule rotation of hundreds of master keys per cloud subscription, helping reduce compliance burden.
By Application
Cloud encryption held the largest share in 2024 with about 37% share, driven by rapid enterprise cloud adoption and strict regulations on data protection. Disk and file encryption grew as businesses secured stored information, remote devices, and shared content. Database encryption gained traction due to rising cyberattacks targeting structured records across finance, healthcare, and retail. Communication encryption expanded with higher use of unified communication tools and remote work models. Each application advanced as companies adopted stronger encryption policies to limit breach risks and protect data across expanding digital ecosystems.
Key Growth Drivers
Growing Regulatory Pressure and Data Protection Needs
New privacy laws required stronger control over encrypted data and increased the use of key management tools. Firms faced strict audits and heavy penalties for poor data handling, so they adopted safer systems. Key management as a service offered clear logs, controlled access, and better monitoring to meet these laws. Companies used these services to secure personal, financial, and health records. Governments updated regulations often, which pushed firms to adopt flexible platforms. Clearer compliance paths helped many sectors raise security levels and drove steady market growth.
- For instance, Thales’ CipherTrust Cloud Key Manager produces detailed log records for every key operation (creation, rotation, import/export), which can be exported to a SIEM or syslog server for audit purposes.
Rising Cloud Adoption Across All Industries
Cloud use expanded across every major sector and created strong demand for secure key handling. Companies moved workloads to public and hybrid clouds and needed reliable encryption to protect sensitive data. Key management as a service helped organizations keep control of cryptographic keys while using remote systems. Many firms lacked in-house security skills, so they turned to outside platforms for simple and safe key storage. Global rules also pushed firms toward stronger cloud security. These factors encouraged widespread adoption and made cloud growth a major driver for this market.
Rapid Increase in Cyberattacks Targeting Sensitive Data
Cyberattacks became more common and more advanced, forcing organizations to strengthen encryption methods. Hackers targeted stored data, cloud files, and internal databases across many industries. Firms used key management services to close security gaps and limit damage from breaches. Centralized control helped teams rotate, store, and revoke keys quickly. Attack costs also increased, which pushed companies to invest in safer systems. Better risk awareness across leadership groups supported this shift. The rising threat landscape made strong encryption a priority and boosted demand for key management as a service.
Key Trends & Opportunities
Expansion of Multi-Cloud and Hybrid IT Environments
Multi-cloud use increased as companies mixed services from several providers. This created new security issues because each cloud followed different rules. Key management as a service helped firms unify key control across all systems. Central tools simplified encryption tasks and reduced manual errors. This trend opened opportunities for flexible platforms that supported many cloud setups. Firms also needed tools that scaled with heavy workloads, creating strong demand for advanced and automated services. Growing hybrid networks made unified key control an important market opportunity.
- For instance, Thales’ Cloud Key Manager supports automation via RESTful APIs, allowing enterprises to rotate, backup, and manage hundreds of master keys per cloud subscription programmatically, rather than handling each key manually.
Growth of Zero-Trust Security Adoption
Many firms shifted to zero-trust security models to protect modern networks. Zero-trust required strict verification and constant checking of user actions. Encryption played a major role, which increased demand for strong key management. Companies needed tools that worked well with identity systems and provided real-time control. Key management services offered this support and helped firms move toward zero-trust faster. Vendors gained new opportunities by creating tools that linked with security platforms. The move toward zero-trust made encryption and key control central to long-term security plans.
- For instance, Thales’ CipherTrust Manager gives granular role‑based access control and integrates with identity systems so that only verified identities can perform key lifecycle operations (generation, rotation, deletion) strengthening zero‑trust governance.
Key Challenges
High Integration Complexity in Large Enterprises
Large firms often struggled to connect key management with existing systems. Older networks and custom apps required extra setup steps, slowing adoption. Integration problems increased the need for skilled teams, raising project costs. Some firms delayed upgrades because of these challenges. Vendors had to offer special support and simpler tools to reduce these hurdles. Complex systems also caused delays in meeting security goals. This challenge remained a major barrier for companies with wide and older IT setups.
Limited Security Expertise in Small and Mid-Size Companies
Smaller firms often lacked the skills needed to manage encryption and key policies. Many teams understood basic security but struggled with advanced key handling. This skill gap created risks during setup and daily use. Smaller budgets also limited access to expert help. These issues slowed adoption and made firms depend more on outside support. Vendors needed easier tools to reach this segment. Without simpler systems, many small firms continued facing delays in adopting strong key management.
Regional Analysis
North America
North America led the key management as a service market in 2024 with about 38% share. Strong adoption of cloud platforms, strict data protection rules, and higher cyberattack risks supported steady growth. The U.S. dominated due to advanced security spending by BFSI, healthcare, and tech firms. Canada added momentum as businesses modernized IT systems and adopted zero-trust frameworks. Widespread use of multi-cloud setups increased the need for unified key handling. Major vendors and rapid regulatory updates further strengthened the region’s leadership, helping North America maintain a clear edge over other markets.
Europe
Europe held nearly 29% share in 2024, driven by strict privacy laws and strong industry compliance needs. The GDPR requirement for strict encryption practices raised demand for centralized key control. Germany, the U.K., and France led adoption as enterprises transitioned to cloud and hybrid systems. Financial services, government agencies, and telecom firms pushed the market forward through higher investments in secure IT modernization. Growing cyber risks and national security initiatives also supported broader uptake. These factors helped Europe remain one of the most security-driven markets for key management services.
Asia-Pacific
Asia-Pacific accounted for about 23% share in 2024 and remained the fastest-growing regional market. Rapid digitalization in China, India, Japan, and South Korea increased the need for cloud-based encryption tools. Expanding fintech ecosystems and large e-commerce networks created high demand for secure data handling. Rising cybercrime and new national cybersecurity rules encouraged firms to adopt structured key management. Cloud migration across IT, telecom, and manufacturing sectors boosted uptake further. Strong investments in modern security infrastructure supported the region’s growth and positioned Asia-Pacific as a long-term opportunity.
Latin America
Latin America held around 6% share in 2024, supported by growing cloud adoption and stronger regulatory efforts. Brazil and Mexico led the market as enterprises modernized IT operations and improved data protection systems. Expanding digital banking, e-commerce activity, and rising breach incidents pushed firms toward centralized encryption management. Adoption remained slower compared to developed regions due to budget limits and skills gaps. However, more companies moved toward managed security services, raising the use of cloud-based key management. This shift strengthened the region’s growth potential.
Middle East & Africa
The Middle East & Africa region captured nearly 4% share in 2024, driven by rising cybersecurity concerns and expanding digital transformation programs. Gulf countries such as the UAE and Saudi Arabia adopted advanced encryption solutions to protect government, finance, and energy sector data. Cloud service expansion across emerging markets supported the need for secure key handling. Many organizations relied on managed platforms due to limited in-house expertise. Growing investment in national cybersecurity frameworks further supported market activity. Despite smaller scale, the region continued showing strong long-term growth prospects.
Market Segmentations:
By Vertical Outlook
- BFSI
- Healthcare
- IT & Telecommunications
- Government
- Retail
- Manufacturing
- Aerospace & Defense
By Component
- Solution
- Service
- Managed
By Application
- Disk Encryption
- File Encryption
- Database Encryption
- Communication Encryption
- Cloud Encryption
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the key management as a service market features IBM Corporation, CipherCloud, Unbound Tech, Google, Thales (Gemalto), Intel Corporation, Sepior ApS, Egnyte, and KeyNexus Inc. Companies expanded their reach with strong cloud-ready encryption tools and simple key control systems. Many vendors improved integration with major cloud platforms to support multi-cloud use. Firms focused on faster key rotation, safer storage, and zero-trust support. Players added automation features to reduce human error and improve daily security tasks. Several companies invested in quantum-safe methods to prepare for future risks. Partnerships with financial, healthcare, and telecom firms helped vendors grow. Many providers also offered managed services for teams lacking security skills. These strategies strengthened competition and pushed vendors to deliver better performance and stronger compliance features across global markets.
Key Player Analysis
- IBM Corporation
- CipherCloud
- Unbound Tech
- Thales (Gemalto)
- Intel Corporation
- Sepior ApS
- Egnyte
- KeyNexus Inc.
- Others
Recent Developments
- In June 2025, Egnyte launched Project Hub an AI-powered data-infrastructure platform for the AEC sector; while not strictly a KMaaS move, it implies deeper investment in secure key/control infrastructure.
- In April 2025, Intel corporation Highlighted a security advisory concerning encryption-key exposure on Intel Apollo Lake platforms a relevant risk to key-management services.
- In March 2025, IBM Corporation Announced a broader push in its as-a-service portfolio (though not specifically KMaaS) as part of infrastructure management tools
Report Coverage
The research report offers an in-depth analysis based onVertical Outlook, Component, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for cloud-based key control will rise as enterprises expand multi-cloud systems.
- Zero-trust adoption will push firms to use stronger and more automated encryption tools.
- Quantum-safe cryptography will gain traction as companies prepare for future security risks.
- AI-driven key monitoring will improve threat detection and reduce manual workload.
- More industries will shift from on-premise key systems to fully managed cloud platforms.
- Integration with identity and access management tools will become a core requirement.
- Regulatory pressure will increase adoption in BFSI, healthcare, government, and telecom sectors.
- Cross-border data flow rules will encourage firms to adopt region-specific key governance.
- SMEs will adopt simpler and low-cost managed services to close skill gaps.
- Global vendors will expand partnerships with cloud providers to strengthen market presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Key management as a service market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Key management as a service market projected to grow between 2025 and 2032?
Which is the leading region of the market for key management as a service?
What are the key drivers for the growth of the key management as a service market?
Which is the major segment in the key management as a service market by industry?
Who are the leading companies in Key management as a service market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Key Management as a Service Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Key Management as a Service Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 820.5 million → 2032: USD 3103.01 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Key Management as a Service Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Key Management as a Service Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Key Management as a Service Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Key Management as a Service Market Drivers
- 3.3 Key Management as a Service Market Restraints & Challenges
- 3.4 Key Management as a Service Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Key Management as a Service Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Key Management as a Service Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Key Management as a Service category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Key Management as a Service Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Key Management as a Service Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Key Management as a Service market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Key Management as a Service Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Key Management as a Service Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Key Management as a Service Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Key Management as a Service (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Key Management as a Service Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Key Management as a Service Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Key Management as a Service Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Key Management as a Service Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Key Management as a Service Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Key Management as a Service Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Key Management as a Service Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Key Management as a Service Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Key Management as a Service Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
