
Market Overview
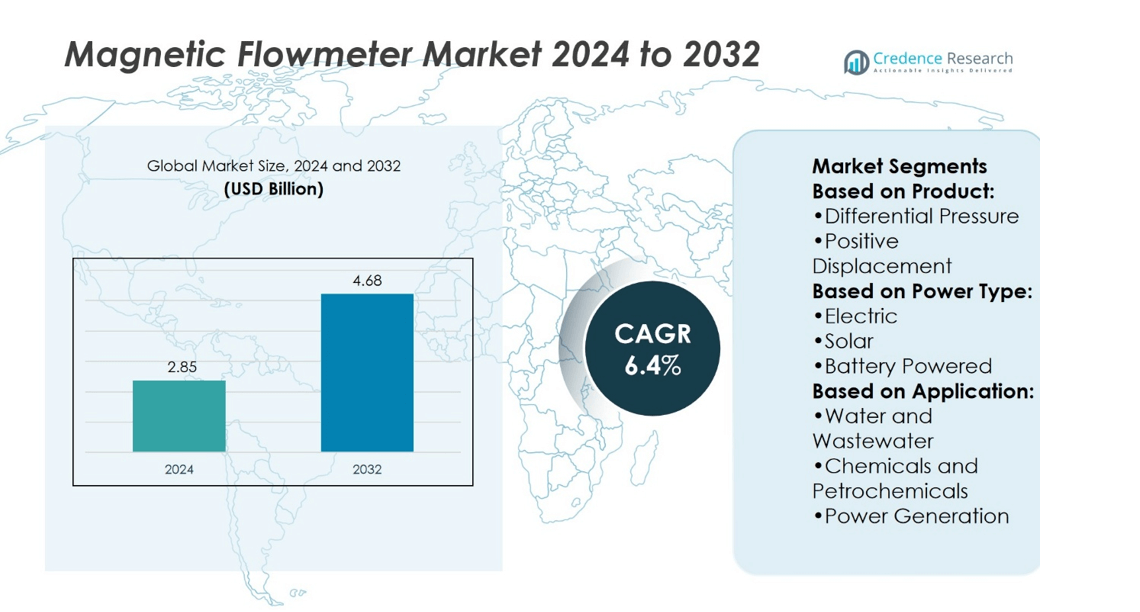
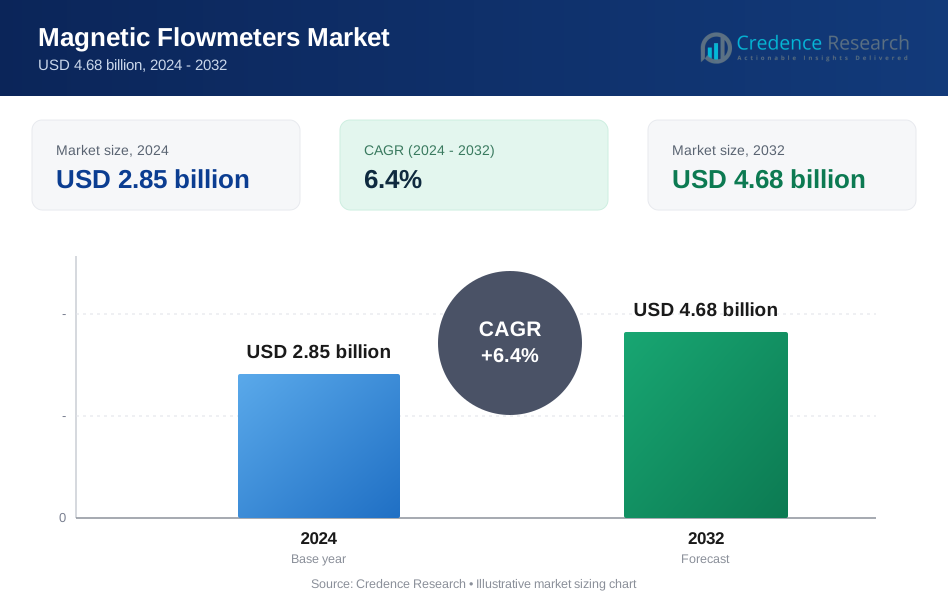
Magnetic Flowmeter Market size was valued at USD 2.85 billion in 2024 and is anticipated to reach USD 4.68 billion by 2032, at a CAGR of 6.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Magnetic Flowmeter Market Size 2024 | USD 2.85 billion |
| Magnetic Flowmeter Market, CAGR | 6.4% |
| Magnetic Flowmeter Market Size 2032 | USD 4.68 billion |
The Magnetic Flowmeter Market grows through strong demand for accurate, maintenance-free flow measurement across industries such as water, chemicals, and power generation. Drivers include rising infrastructure investments, strict environmental regulations, and the need for reliable monitoring in harsh operating conditions. It supports industrial automation by enabling real-time data access, predictive maintenance, and regulatory compliance. Key trends highlight the integration of IoT-enabled features, wireless connectivity, and cloud-based platforms, which enhance performance and data management. Expanding adoption in smart water networks, sustainable resource projects, and emerging economies further strengthens its role in advancing efficiency and operational reliability.
The Magnetic Flowmeter Market shows strong geographical presence, with Asia-Pacific leading due to rapid industrialization and water infrastructure projects, while North America and Europe maintain steady demand driven by strict regulations and advanced automation. Latin America and the Middle East & Africa witness growing adoption in oil, gas, and utilities. Key players such as ABB Ltd., Siemens, Emerson Electric Corporation, Endress+Hauser AG, Yokogawa Electric Corporation, Honeywell International Inc., Krohne Messtechnik GmbH, and General Electric strengthen competition through innovation and global reach.
Market Insights
- The Magnetic Flowmeter Market size was valued at USD 2.85 billion in 2024 and is projected to reach USD 4.68 billion by 2032, at a CAGR of 6.4%.
- Strong demand for accurate, maintenance-free flow measurement in water, chemicals, and power generation industries drives consistent market growth.
- Rising infrastructure investments, regulatory compliance, and the need for reliable monitoring in harsh environments act as key drivers.
- Integration of IoT features, wireless connectivity, and cloud platforms reflects major trends improving performance and data accessibility.
- Competition remains strong, with global players focusing on innovation, durability, and predictive maintenance to expand market presence.
- High installation costs and limited compatibility with non-conductive fluids continue to challenge broader adoption across industries.
- Asia-Pacific leads due to rapid industrialization, while North America and Europe maintain steady demand, and Latin America along with the Middle East & Africa show growing adoption in oil, gas, and utilities.
Market Drivers
Rising Demand for Accurate and Reliable Flow Measurement in Industrial Operations
The Magnetic Flowmeter Market benefits from strong demand in industries where precise flow measurement determines operational efficiency. It ensures consistent monitoring in sectors such as oil and gas, water treatment, and chemicals. Industries rely on it to handle challenging fluids, including slurries and corrosive liquids, with minimal maintenance requirements. Enhanced accuracy and non-intrusive operation make it suitable for environments where downtime creates high costs. The ability to deliver repeatable measurements under varying flow conditions strengthens adoption. Growing infrastructure development in water and wastewater treatment also accelerates its integration.
- For instance, Endress+Hauser, a global leader in process automation, reported installing more than 3 million electromagnetic flowmeters worldwide by 2022, ensuring reliable measurement performance across critical industrial applications.
Expanding Use in Water and Wastewater Treatment Facilities
The Magnetic Flowmeter Market shows significant momentum in municipal and industrial water management. It plays a critical role in monitoring water distribution, leak detection, and wastewater treatment processes. Utilities adopt it to meet strict regulatory compliance on water usage and discharge. Advanced meters provide digital communication capabilities, enabling remote monitoring and integration with supervisory control systems. Its non-mechanical design minimizes pressure drop and reduces maintenance frequency. The growing focus on resource optimization and sustainability encourages widespread deployment.
- For instance, ABB has supplied more than 500,000 electromagnetic flowmeters globally, with a large share deployed in water and wastewater plants to improve distribution efficiency and regulatory compliance monitoring.
Technological Advancements Enhancing Performance and Connectivity
The Magnetic Flowmeter Market experiences steady progress through innovations in sensor design and communication protocols. It now supports IoT-enabled features, wireless connectivity, and diagnostics for predictive maintenance. Digital signal processing improves accuracy and reduces noise interference, enhancing reliability in complex flow environments. Smart features allow operators to receive real-time performance updates and alerts. Integration with cloud-based platforms improves data accessibility for industrial automation. Such advancements strengthen its role in digital transformation strategies across industries.
Rising Adoption in Energy and Process Industries
The Magnetic Flowmeter Market gains momentum in energy-intensive industries where process efficiency and safety are critical. It supports applications in power generation, refining, and mining by offering precise flow data for critical operations. Strong performance in harsh conditions makes it a preferred choice for industries handling conductive fluids. Companies invest in it to improve productivity while maintaining compliance with environmental and safety standards. Growing emphasis on energy conservation and process optimization drives higher penetration. Its role in enabling cost-efficient operations secures long-term demand.
Market Trends
Growing Integration of Smart and Connected Flow Technologies
The Magnetic Flowmeter Market reflects a strong trend toward smart instrumentation with built-in communication protocols. It now incorporates IoT-enabled features that allow remote monitoring and real-time data analysis. Manufacturers enhance products with advanced diagnostics to support predictive maintenance strategies. Cloud connectivity provides industries with continuous access to performance data and operational insights. The integration of digital tools improves decision-making for operators in critical sectors. This shift aligns with broader industrial automation and digital transformation initiatives.
- For instance, Siemens has installed more than 30 million SITRANS magnetic flowmeters worldwide, many equipped with digital communication interfaces such as HART, Profibus, and Modbus, enabling integration with IoT platforms for real-time monitoring and predictive maintenance.
Rising Preference for Non-Intrusive and Maintenance-Free Designs
The Magnetic Flowmeter Market shows increasing demand for designs that minimize operational disruption. It eliminates moving parts, which reduces wear and enhances long-term reliability. Non-intrusive construction ensures minimal pressure drop and stable measurement in diverse conditions. Industries favor it for applications involving corrosive, abrasive, or slurry-type fluids where durability is essential. Compact, maintenance-free solutions reduce lifecycle costs and improve efficiency. This trend strengthens adoption across utilities, chemical processing, and mining operations.
- For instance, Krohne has delivered more than 2 million electromagnetic flowmeters globally, with its OPTIFLUX series specifically designed as maintenance-free systems without moving parts, ensuring reliable operation in industries such as water, chemicals, and food processing.
Expansion in Water and Wastewater Management Applications
The Magnetic Flowmeter Market demonstrates growing adoption in water distribution and treatment facilities worldwide. It supports regulatory compliance by ensuring accurate measurement of inflows, outflows, and discharge levels. Governments and utilities invest in it to optimize water usage and improve leak detection systems. Advanced models allow utilities to integrate flow monitoring into smart grid and smart city infrastructure. The rising focus on sustainable resource management fuels continued growth in this segment. Its application in wastewater treatment strengthens the market’s role in environmental management.
Increasing Adoption in Harsh and Complex Industrial Environments
The Magnetic Flowmeter Market benefits from wider use in industries that operate under demanding conditions. It delivers precise readings in high-pressure, high-temperature, and chemically aggressive environments. Operators in energy, oil and gas, and mining adopt it for critical process control and safety monitoring. Enhanced material engineering improves resistance to abrasion and corrosion. Its capability to perform reliably in conditions that challenge other technologies makes it a preferred choice. This trend underscores its value in securing operational continuity and efficiency.
Market Challenges Analysis
High Installation Costs and Limited Compatibility Across Applications
The Magnetic Flowmeter Market faces a key challenge in high initial investment, which restricts adoption in cost-sensitive industries. It requires careful installation and calibration, increasing project expenses for utilities and small enterprises. Compatibility issues also arise, as it measures only conductive fluids, limiting use in oil-based and non-conductive applications. This restriction creates dependency on alternative flow measurement technologies in certain industries. Integration with existing legacy systems can be complex and costly, further slowing adoption. These factors create barriers for broader penetration in emerging markets with limited budgets.
Operational Constraints and Maintenance-Related Concerns
The Magnetic Flowmeter Market encounters difficulties in environments where extreme temperatures or non-conductive materials reduce accuracy. It demands periodic verification to maintain reliable performance, which adds to operating costs. Power supply requirements and electromagnetic interference risks can affect long-term stability in industrial settings. Industries with highly viscous fluids or very low conductivity face performance limitations that reduce efficiency. While manufacturers continue to innovate, these technical constraints remain a challenge for widespread deployment. Such limitations encourage industries to evaluate hybrid or alternative flow measurement solutions.
Market Opportunities
Expanding Role in Water Management and Environmental Sustainability
The Magnetic Flowmeter Market holds strong opportunities in water and wastewater management projects driven by global sustainability goals. Governments and municipalities adopt it to improve monitoring of water distribution, reduce losses, and meet strict environmental regulations. Its ability to handle large volumes with high accuracy positions it as a preferred tool for utilities modernizing infrastructure. Growing investments in smart city initiatives create further demand for connected and automated flow measurement. The rising focus on clean water access and efficient wastewater treatment enhances its long-term relevance. Expanding infrastructure programs in emerging economies strengthen its growth prospects.
Advancements in Smart Technologies and Industrial Automation
The Magnetic Flowmeter Market benefits from opportunities linked to digitalization and Industry 4.0 adoption. It integrates with IoT platforms and advanced analytics, enabling predictive maintenance and operational optimization. Energy, chemical, and mining industries explore these solutions to improve efficiency and reduce downtime. Manufacturers gain opportunities to differentiate through wireless connectivity, compact designs, and improved material engineering. Expansion of automated facilities worldwide creates growing demand for intelligent flow monitoring systems. This trend allows it to play a central role in shaping future industrial operations.
Market Segmentation Analysis:
By Product
The Magnetic Flowmeter Market is segmented by product into differential pressure and positive displacement types. Differential pressure flowmeters dominate due to their precision in monitoring variable flow conditions across industrial applications. It provides high reliability in large-scale operations such as water treatment and power plants, where continuous accuracy is essential. Positive displacement flowmeters, while less common, hold relevance in specific sectors requiring precise volumetric measurements. These devices offer consistent performance in applications where fluid characteristics remain stable. The balance between both product types ensures that industries can select the right solution based on operational needs.
- For instance, Yokogawa has supplied more than 1.5 million differential pressure and flow measurement devices worldwide, with a significant share deployed in water treatment and power generation facilities to ensure stable and accurate monitoring.
By Power Type
The market includes electric, solar, and battery-powered magnetic flowmeters. Electric-powered devices lead the segment because of their wide deployment in industrial automation and process industries. It offers uninterrupted performance in high-demand environments, which makes them highly reliable for continuous operations. Solar-powered flowmeters gain momentum in remote or off-grid installations, especially in water management projects. Battery-powered options provide flexibility in temporary or mobile applications where grid connectivity is limited. This diversity in power types supports the expansion of flowmeter adoption across multiple industries and geographies.
- For instance, em-tec GmbH, part of the Verder Group, has delivered more than 20,000 flow measurement systems for medical, bioprocess, and industrial applications, with its non-invasive magnetic flowmeters increasingly adopted in water treatment and process industries to ensure hygienic, precise monitoring.
By Application
The Magnetic Flowmeter Market shows strong penetration across water and wastewater, chemicals and petrochemicals, power generation, and metals and mining applications. Water and wastewater remain a leading segment, with growing infrastructure investments and regulatory pressure driving adoption. It enables accurate measurement of inflows and outflows, improving resource management and compliance. Chemicals and petrochemicals also contribute significantly, as precise monitoring of conductive fluids ensures safety and operational efficiency. Power generation facilities deploy magnetic flowmeters to optimize cooling water and fuel management systems. Metals and mining operations use them for handling abrasive slurries and process monitoring, where durability and accuracy are vital. Together, these applications highlight the market’s critical role in supporting industrial efficiency and sustainability.
Segments:
Based on Product:
- Differential Pressure
- Positive Displacement
Based on Power Type:
- Electric
- Solar
- Battery Powered
Based on Application:
- Water and Wastewater
- Chemicals and Petrochemicals
- Power Generation
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds about 28% share of the Magnetic Flowmeter Market. The region benefits from a strong industrial base in oil & gas, petrochemicals, and power generation. Strict water management and environmental regulations drive widespread adoption across the U.S. and Canada. It finds heavy use in wastewater treatment facilities, municipal utilities, and refineries. Digital integration, IoT-enabled meters, and predictive maintenance solutions see rapid deployment. High demand for reliable, long-life instruments secures the region’s strong market position.
Europe
Europe accounts for nearly 26% of the Magnetic Flowmeter Market. Strong policies on water conservation, emission control, and industrial efficiency support adoption. Countries such as Germany, the UK, and France invest in advanced process industries, making magnetic flowmeters vital for compliance. It plays a key role in water distribution, energy transition projects, and chemical manufacturing. Industrial automation initiatives and sustainability programs accelerate integration of smart flow measurement technologies. Stable demand across utilities and process industries ensures continued growth.
Asia-Pacific
Asia-Pacific leads the Magnetic Flowmeter Market with around 32% share. Rapid urbanization, growing water infrastructure, and heavy investments in power and chemical industries fuel demand. China, India, Japan, and Southeast Asia drive expansion through large-scale municipal and industrial projects. It is widely adopted in wastewater treatment, mining, and energy sectors, where high accuracy and durability are critical. Governments push for modernization of infrastructure, supporting steady deployment of digital flowmeters. The region’s scale and industrial growth secure its dominant market position.
Latin America
Latin America contributes close to 7% share of the Magnetic Flowmeter Market. Rising investments in oil & gas, mining, and water management projects drive adoption. Brazil and Mexico lead with infrastructure upgrades and industrial automation efforts. It supports safe and efficient handling of conductive fluids in industries facing resource management challenges. Local governments and utilities increase focus on water efficiency, creating opportunities for market players. Growing demand in industrial hubs ensures a steady upward trend.
Middle East & Africa
The Middle East & Africa hold about 7% share of the Magnetic Flowmeter Market. Strong investments in oil, gas, and desalination projects create consistent demand. Countries such as Saudi Arabia, UAE, and South Africa deploy it across energy and water infrastructure. The technology’s durability and accuracy make it suitable for harsh operating environments. Growing focus on resource efficiency and utility modernization drives wider adoption. Expanding infrastructure programs signal positive long-term prospects.
Key Player Analysis
- Krohne Messtechnik Gmbh
- Emerson Electric Corporation
- Honeywell International Inc.
- HÖNTZSCH GMBH & CO. KG
- Yokogawa Electric Corporation
- Hitachi High-Tech Corporation
- ABB Ltd.
- Endress+Hausar AG
- Siemens
- em-tec GmbH
- General Electric
Competitive Analysis
The Magnetic Flowmeter Market companies such as Krohne Messtechnik Gmbh, Emerson Electric Corporation, Honeywell International Inc., HÖNTZSCH GMBH & CO. KG, Yokogawa Electric Corporation, Hitachi High-Tech Corporation, ABB Ltd., Endress+Hausar AG, Siemens, em-tec GmbH, and General Electric. The Magnetic Flowmeter Market demonstrates intense competition, with companies focusing on innovation, product reliability, and global reach to secure advantage. Firms emphasize advanced features such as IoT integration, wireless connectivity, and predictive diagnostics to meet rising demand for smart measurement solutions. Strong investment in research and development ensures improved accuracy, durability, and adaptability across industries. Competition also arises from the need to offer cost-effective solutions that balance performance with long-term maintenance savings. Many players expand through partnerships with utilities and industrial operators, ensuring steady growth in water, chemical, mining, and energy sectors. The market reflects a balance of global presence and localized service, where strong after-sales support often determines customer retention.
Recent Developments
- In August 2024, ABB has unveiled its newest generation of electromagnetic flowmeters, delivering unparalleled accuracy, connectivity, and adaptability for both industrial and utility uses. This introduction allows ABB to refine its product lineup, focusing on two of its most versatile offerings.
- In March 2024, Yokogawa Electric Corporation announced the acquisition of Adept Fluidyne Pvt. Ltd., one of India's largest domestic manufacturers of magnetic flowmeters. This acquisition provides Yokogawa with a manufacturing base in India for its range of high-performance magnetic flowmeters.
- In March 2024, SONOTEC GmbH unveiled the SONOFLOW CO.55 SD V3.0 at the INTERPHEX exhibition in New York. This stainless steel, non-contact clamp-on flow meter features an integrated touch display. Designed to meet Good Manufacturing Practice (GMP) requirements, it offers real-time flow data, flow direction, and status information directly on the sensor's display.
- In March 2024, ONICON Incorporated has unveiled the FT-3500, an advanced Insertion Electromagnetic Flow Meter paired with a Thermal Energy Measurement System. This state-of-the-art solution seamlessly integrates modern technology with user-friendly features. Tailored for networking, the FT-350.
Report Coverage
The research report offers an in-depth analysis based on Product, Power Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Magnetic Flowmeter Market will expand steadily with rising demand from water and wastewater treatment projects.
- It will gain momentum through wider integration of IoT-enabled and smart monitoring technologies.
- Industrial automation will increase adoption as companies prioritize predictive maintenance and real-time data access.
- It will see higher penetration in emerging economies supported by infrastructure investments and utility modernization.
- Energy, mining, and chemical industries will continue driving demand for durable and accurate flow measurement.
- Sustainability initiatives will boost its role in resource management and regulatory compliance.
- It will benefit from advancements in materials that enhance resistance to corrosion and abrasion.
- Manufacturers will focus on compact, low-maintenance models to address cost-sensitive markets.
- Digital connectivity and cloud-based solutions will strengthen its use in smart city and smart grid projects.
- The competitive landscape will evolve with stronger collaborations and regional expansions by leading players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Magnetic Flowmeter Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Magnetic Flowmeter Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Magnetic Flowmeter Market?
Who are the leading companies in the Magnetic Flowmeter Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Magnetic Flowmeters Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Magnetic Flowmeters Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.85 billion → 2032: USD 4.68 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Magnetic Flowmeters Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Magnetic Flowmeters Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Magnetic Flowmeters Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Magnetic Flowmeters Market Drivers
- 3.3 Magnetic Flowmeters Market Restraints & Challenges
- 3.4 Magnetic Flowmeters Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Magnetic Flowmeters Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Magnetic Flowmeters Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Magnetic Flowmeters category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Magnetic Flowmeters Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Magnetic Flowmeters Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Magnetic Flowmeters market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Magnetic Flowmeters Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Magnetic Flowmeters Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Magnetic Flowmeters Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Magnetic Flowmeters (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Magnetic Flowmeters Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Magnetic Flowmeters Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Magnetic Flowmeters Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Magnetic Flowmeters Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Magnetic Flowmeters Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Magnetic Flowmeters Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Magnetic Flowmeters Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Magnetic Flowmeters Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Magnetic Flowmeters Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
