
Magnetorheological Damper Sales Market Overview:
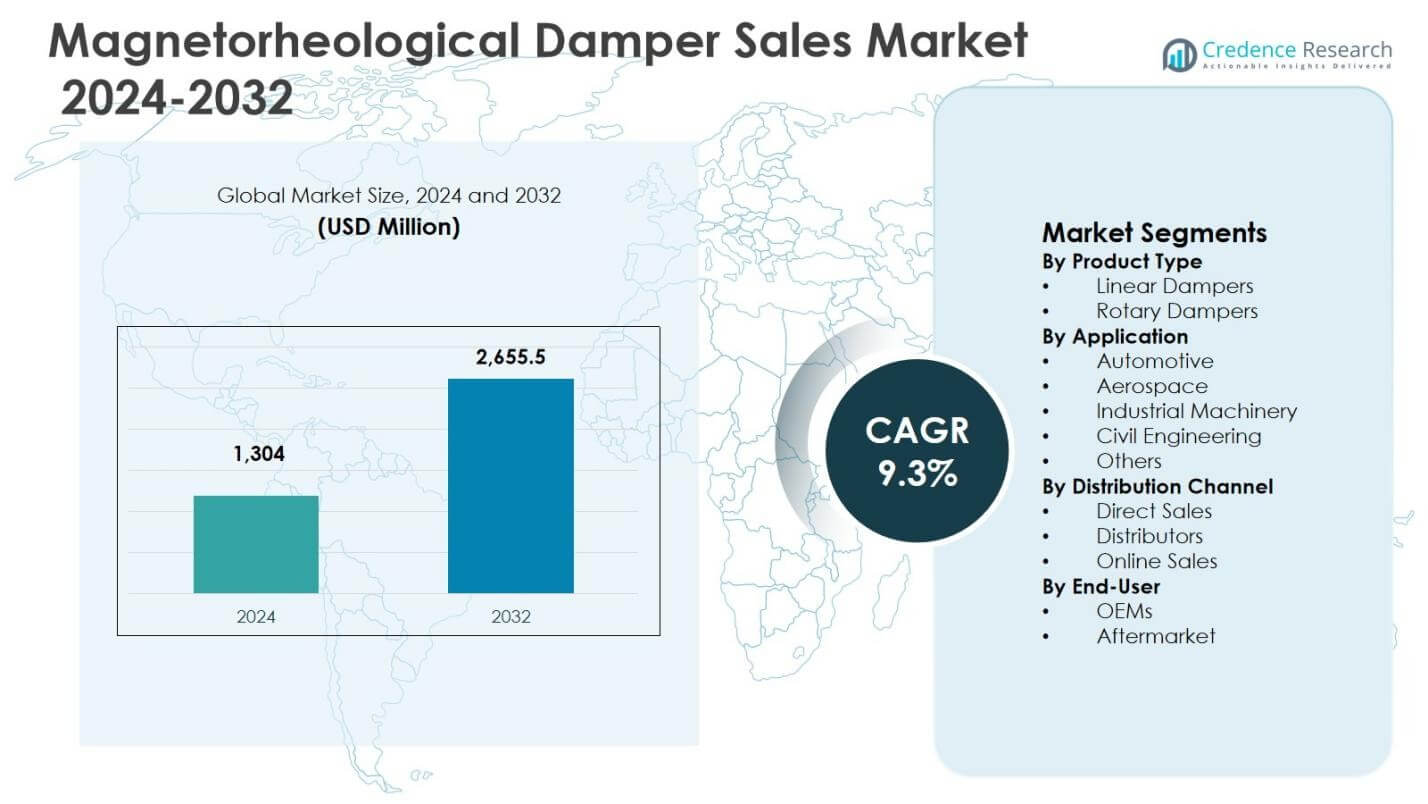
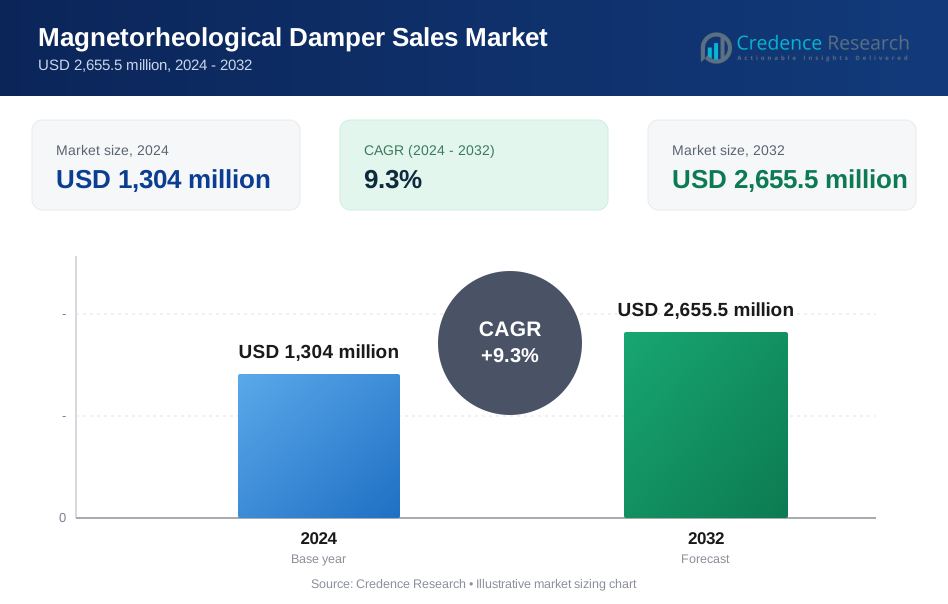
The Magnetorheological Damper Sales Market size was valued at USD 1,304 million in 2024 and is anticipated to reach USD 2,655.5 million by 2032, expanding at a CAGR of 9.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Magnetorheological Damper Sales Market Size 2024 | USD 1,304 million |
| Magnetorheological Damper Sales Market, CAGR | 9.3% |
| Magnetorheological Damper Sales Market Size 2032 | USD 2,655.5 million |
Magnetorheological Damper Sales Market Insights
- Market growth is primarily driven by increasing use of advanced and semi-active suspension systems in automotive applications, where the automotive segment accounted for 7% market share in 2024, driven by demand for improved ride comfort, safety, and real-time damping control.
- Key market trends include integration of smart control systems, sensors, and IoT-enabled dampers, along with rising deployment in electric vehicles and seismic protection infrastructure, while linear dampers dominated the product segment with 68.4% share in 2024 due to superior load handling and response speed.
- Market expansion faces restraints from high system costs, complex integration requirements, and temperature sensitivity of magnetorheological fluids, which limit adoption in cost-sensitive and mass-market applications despite ongoing R&D improvements.
- Regionally, North America led with a 34.6% share in 2024, followed by Europe at 28.9% and Asia Pacific at 26.8%, while Latin America and Middle East & Africa together accounted for the remaining share, supported by infrastructure development and gradual automotive adoption.
Magnetorheological Damper Sales Market Segmentation Analysis:
By Product Type:
The Magnetorheological Damper Sales Market, segmented by product type into linear dampers and rotary dampers, is led by linear dampers, which accounted for 68.4% market share in 2024. Linear dampers dominate due to their superior load-bearing capacity, faster response time, and ease of integration in suspension and vibration-control systems. Their widespread adoption in automotive suspension, seismic protection systems, and heavy machinery enhances demand. Growth is driven by increasing focus on ride comfort, vehicle safety, and adaptive damping technologies, along with rising investments in smart suspension systems across passenger and commercial vehicles.
- For instance, BWI Group's MagneRide linear dampers in the Chevrolet Corvette provide real-time adaptability, stiffening instantly via magnetic fields to improve handling during cornering and braking without harsh ride quality.
By Application:
By application, the Magnetorheological Damper Sales Market is dominated by the automotive segment, which held a 54.7% share in 2024. Automotive applications benefit from the ability of MR dampers to provide real-time damping adjustment, improving ride quality, handling, and safety. Rising adoption of semi-active suspension systems in premium and electric vehicles strongly supports growth. Aerospace and civil engineering segments also contribute steadily, driven by vibration mitigation needs, while industrial machinery applications gain traction due to increasing automation and demand for precision vibration control.
- For instance, General Motors employs Delphi Technologies’ MagneRide suspension system in vehicles like the Cadillac CT5 and Chevrolet Corvette, offering adaptive damping control based on road conditions.
By Distribution Channel:
Based on distribution channel, direct sales emerged as the dominant sub-segment with a 61.9% market share in 2024 in the Magnetorheological Damper Sales Market. Direct sales dominate as OEMs and large infrastructure developers prefer customized solutions, technical support, and long-term supply agreements offered by manufacturers. This channel ensures better performance optimization and integration support, particularly for automotive and aerospace applications. Distributor networks support regional reach, while online sales remain limited but growing, driven by increasing digital procurement practices in industrial and aftermarket segments.
Key Growth Drivers
Rising Adoption of Advanced Suspension Systems in Automotive Sector
The Magnetorheological Damper Sales Market is strongly driven by increasing adoption of advanced and semi-active suspension systems in passenger and commercial vehicles. Automakers are integrating magnetorheological dampers to enhance ride comfort, vehicle stability, and handling performance under varying road conditions. The ability of these dampers to respond instantly to changing inputs makes them highly suitable for premium, electric, and performance vehicles. Growing consumer demand for improved driving experience, safety features, and adaptive vehicle technologies continues to accelerate penetration across mid-range and high-end automotive segments globally.
- For instance, Cadillac introduced MagneRide magnetorheological dampers in the 2002 Seville STS, the first production vehicle application using monotube dampers with magnetorheological fluid controlled by an ECU and sensors for adaptive ride without mechanical valves.
Growing Infrastructure Development and Seismic Protection Demand
Expanding infrastructure development and rising focus on seismic safety significantly drive the Magnetorheological Damper Sales Market. Magnetorheological dampers are increasingly deployed in bridges, high-rise buildings, and civil structures to control vibrations and enhance structural resilience during earthquakes and extreme loads. Rapid urbanization, large-scale transportation projects, and stricter building safety regulations are supporting adoption. Governments and private developers are investing in smart vibration-control systems to reduce long-term maintenance costs and improve structural durability, strengthening demand across civil engineering and construction applications.
- For instance, Lord Corporation installed 312 RD-1005 semi-active MR dampers on the stay cables of Dongting Lake Bridge in China in 2002 to mitigate wind-rain-induced vibrations.
Increasing Industrial Automation and Precision Machinery Usage
The rising adoption of industrial automation and high-precision machinery is another major growth driver for the Magnetorheological Damper Sales Market. Manufacturing facilities increasingly rely on vibration control solutions to improve equipment accuracy, operational stability, and product quality. Magnetorheological dampers offer adjustable damping characteristics that support diverse industrial applications such as CNC machines, robotics, and heavy equipment. As industries pursue higher productivity, reduced downtime, and improved process control, demand for advanced damping technologies continues to grow across industrial machinery and automation environments.
Key Trends & Opportunities
Integration of Smart Control Systems and IoT-Enabled Dampers
A key trend shaping the Magnetorheological Damper Sales Market is the integration of smart control systems and IoT-enabled technologies. Manufacturers are developing dampers with embedded sensors and real-time monitoring capabilities to enable predictive maintenance and adaptive performance optimization. This trend creates opportunities in automotive, aerospace, and infrastructure sectors where data-driven control improves safety and operational efficiency. The convergence of magnetorheological technology with artificial intelligence and digital control platforms supports innovation, differentiation, and long-term value creation for solution providers.
- For instance, BWI Group's MagneRide system incorporates wheel accelerometers and inertial measurement units (IMUs) for precise real-time sensing of suspension movements and vehicle body dynamics, enabling adaptive damping adjustments up to 1,000 times per second.
Expanding Applications in Electric Vehicles and Aerospace Platforms
The expanding use of magnetorheological dampers in electric vehicles and aerospace platforms presents significant growth opportunities in the Magnetorheological Damper Sales Market. Electric vehicles require efficient vibration control to compensate for battery weight and enhance passenger comfort, making MR dampers highly suitable. In aerospace, demand for lightweight, responsive damping solutions supports adoption in landing gear and structural vibration control. Continuous advancements in material science and compact damper design further broaden application potential across next-generation mobility platforms.
- For instance, LORD Corporation produces MR dampers like the Motion Master series for truck seat suspensions, using MR fluid in valve mode to enable rapid viscosity changes for enhanced vibration isolation under heavy loads.
Key Challenges
High Cost of Technology and System Integration
High production costs and complex system integration remain key challenges in the Magnetorheological Damper Sales Market. Magnetorheological fluids, precision components, and advanced control electronics increase overall system cost, limiting adoption in cost-sensitive applications. Integration with existing mechanical and electronic systems requires specialized expertise, increasing development time and expenses for OEMs. These factors can restrict penetration in mass-market vehicles and smaller infrastructure projects, creating pricing pressure for manufacturers seeking broader market adoption.
Performance Sensitivity to Temperature and Long-Term Reliability
Performance sensitivity to temperature variations and concerns over long-term reliability pose challenges for the Magnetorheological Damper Sales Market. Magnetorheological fluids can exhibit changes in viscosity under extreme temperatures, affecting damping consistency. Additionally, prolonged exposure to harsh operating conditions may impact fluid stability and component durability. Addressing these issues requires continuous material innovation, rigorous testing, and improved sealing technologies, increasing research and development costs while extending product qualification timelines.
Regional Analysis
North America
North America held a 34.6% market share in 2024 in the Magnetorheological Damper Sales Market, supported by strong adoption across automotive, aerospace, and civil infrastructure applications. The region benefits from advanced vehicle suspension integration, high penetration of premium and electric vehicles, and early adoption of smart damping technologies. Ongoing investments in seismic protection systems for bridges and high-rise buildings further support demand. The presence of established OEMs, technology developers, and research institutions accelerates product innovation and commercialization, reinforcing North America’s leadership in high-performance and adaptive damping solutions.
Europe
Europe accounted for a 28.9% market share in 2024 in the Magnetorheological Damper Sales Market, driven by strong automotive manufacturing and stringent safety and ride-comfort standards. The region sees high demand from luxury and performance vehicle segments, where adaptive suspension systems are increasingly standard. Infrastructure modernization projects and earthquake-resilient construction initiatives also support adoption. Technological collaboration between automotive OEMs and component suppliers enhances innovation in damper design and control systems. Regulatory emphasis on vehicle safety, efficiency, and sustainability continues to strengthen long-term market growth across Europe.
Asia Pacific
Asia Pacific captured a 26.8% market share in 2024 in the Magnetorheological Damper Sales Market and remains the fastest-growing region. Rapid expansion of automotive production, increasing electric vehicle penetration, and large-scale infrastructure development drive demand. Countries such as China, Japan, and South Korea actively integrate advanced suspension and vibration-control technologies across automotive and industrial sectors. Rising urbanization and investments in smart transportation infrastructure further support growth. Cost-effective manufacturing capabilities and growing adoption of automation in industrial machinery position Asia Pacific as a key growth engine for the market.
Latin America
Latin America represented a 5.6% market share in 2024 in the Magnetorheological Damper Sales Market, supported by gradual adoption in automotive and infrastructure applications. Increasing vehicle production, improving road conditions, and rising demand for enhanced ride comfort are contributing factors. Infrastructure investments in bridges and commercial buildings also create opportunities for vibration-control technologies. While adoption remains moderate due to cost sensitivity, growing awareness of advanced damping benefits and expanding industrial activity are supporting steady market expansion across key economies in the region.
Middle East & Africa
The Middle East & Africa held a 4.1% market share in 2024 in the Magnetorheological Damper Sales Market, driven primarily by infrastructure development and large-scale construction projects. Demand is supported by investments in high-rise buildings, transportation networks, and seismic-resistant structures in select countries. The automotive segment shows gradual adoption, particularly in premium vehicle categories. Although market penetration remains limited, increasing focus on smart infrastructure, urban development, and long-term structural safety is expected to enhance adoption of magnetorheological damping solutions across the region.
Magnetorheological Damper Sales Market Segmentations:
By Product Type
- Linear Dampers
- Rotary Dampers
By Application
- Automotive
- Aerospace
- Industrial Machinery
- Civil Engineering
- Others
By Distribution Channel
- Direct Sales
- Distributors
- Online Sales
By End-User
- OEMs
- Aftermarket
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Magnetorheological Damper Sales Market highlights the presence of established global manufacturers such as Lord Corporation, ZF Friedrichshafen AG, BWI Group, Mando Corporation, Schaeffler Group, Mitsubishi Heavy Industries, Ltd., Kawasaki Heavy Industries, Ltd., Pintsch Bubenzer GmbH, and Arus MR Tech, which collectively shape market dynamics through technological leadership and long-term OEM relationships. The market is moderately consolidated, with leading players focusing on advanced material formulations, improved response time, and integration of electronic control systems to enhance damper performance. Strategic collaborations with automotive OEMs, aerospace manufacturers, and infrastructure developers remain central to maintaining competitive positioning. Companies also invest heavily in research and development to improve durability, temperature stability, and cost efficiency. Expansion into electric vehicles, smart infrastructure, and industrial automation applications further intensifies competition, while regional manufacturing expansion and customized solution offerings strengthen customer retention and global market reach.
Key Player Analysis
- Mitsubishi Heavy Industries, Ltd.
- Pintsch Bubenzer GmbH
- Lord Corporation
- Schaeffler Group
- Arus MR Tech
- ZF Friedrichshafen AG
- Kawasaki Heavy Industries, Ltd.
- BWI Group
- Mando Corporation
- Beijing West Industries (BWI) Group
Recent Developments
- In February 2025, BWI Group secured a contract from a leading Chinese automaker for its fourth-generation MagneRide suspension, covering sedans, SUVs, and high-performance vehicles with an annual volume of 400,000 units, set for mass production in mid-2025.
- In September 2025, BWI Group announced that its MagneRide semi-active suspension technology, featuring magnetorheological dampers, was selected for Polestar's flagship Polestar 5 Performance GT electric sedan, with supply also for the Dual Motor variant.
- In October 2025, ZF Group launched advanced dampers for metro and high-speed rail applications in India, expanding its portfolio with adaptive damping solutions suitable for magnetorheological technology integration.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Distribution Channel, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Magnetorheological Damper Sales Market will witness sustained growth driven by increasing adoption of adaptive suspension systems across automotive platforms.
- Rising integration of magnetorheological dampers in electric and premium vehicles will strengthen long-term market demand.
- Infrastructure investments focused on seismic protection and vibration control will expand applications in civil engineering projects.
- Technological advancements in magnetorheological fluids will improve temperature stability and long-term damper performance.
- Growing use of smart sensors and electronic control units will enhance real-time damping precision and system efficiency.
- Industrial automation and precision machinery applications will create steady demand for advanced vibration-control solutions.
- Aerospace adoption will increase as manufacturers seek lightweight and responsive damping technologies.
- Expansion of manufacturing capabilities in Asia Pacific will support cost optimization and faster market penetration.
- Strategic partnerships between OEMs and damper manufacturers will accelerate product customization and innovation.
- Continued research and development efforts will reduce system costs and broaden adoption across mid-range applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Magnetorheological Damper Sales Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Magnetorheological Damper Sales Market projected to grow between 2024 and 2032?
Which Magnetorheological Damper Sales Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Magnetorheological Damper Sales Market?
Who are the leading companies in the Magnetorheological Damper Sales Market?
Which region commanded the largest share of the Magnetorheological Damper Sales Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Magnetorheological Damper Sales Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Magnetorheological Damper Sales Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,304 million → 2032: USD 2,655.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Magnetorheological Damper Sales Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Magnetorheological Damper Sales Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Magnetorheological Damper Sales Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Magnetorheological Damper Sales Market Drivers
- 3.3 Magnetorheological Damper Sales Market Restraints & Challenges
- 3.4 Magnetorheological Damper Sales Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Magnetorheological Damper Sales Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Magnetorheological Damper Sales Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Magnetorheological Damper Sales category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Magnetorheological Damper Sales Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Magnetorheological Damper Sales Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Magnetorheological Damper Sales market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Magnetorheological Damper Sales Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Magnetorheological Damper Sales Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Magnetorheological Damper Sales Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Magnetorheological Damper Sales (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Magnetorheological Damper Sales Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Magnetorheological Damper Sales Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Magnetorheological Damper Sales Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Magnetorheological Damper Sales Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Magnetorheological Damper Sales Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Magnetorheological Damper Sales Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Magnetorheological Damper Sales Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Magnetorheological Damper Sales Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Magnetorheological Damper Sales Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
