
Pregelatinized Starch Market Overview:
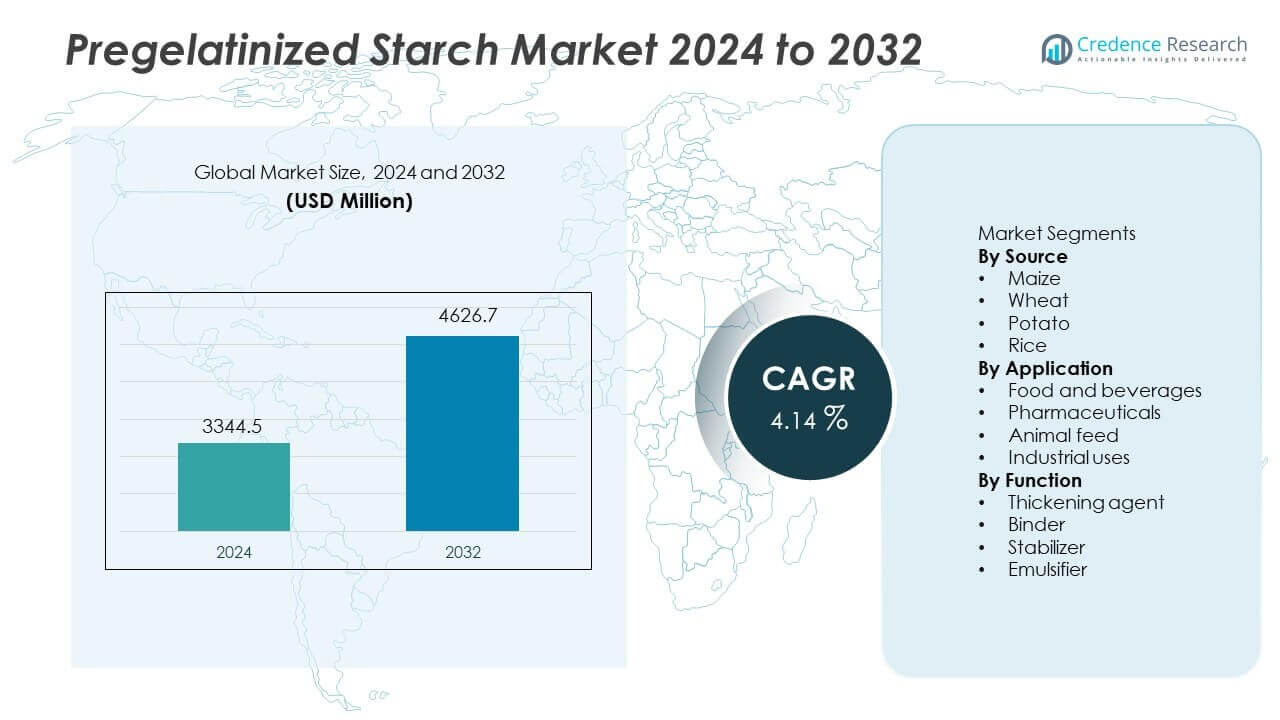
The pregelatinized starch market reached USD 3,344.5 million in 2024 and is projected to reach USD 4,626.7 million by 2032, growing at a CAGR of 4.14% during the forecast period. (Credence Research)
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pregelatinized Starch Market Size 2024 | USD 3,344.5 million |
| Pregelatinized Starch Market, CAGR | 4.14% |
| Pregelatinized Starch Market Size 2032 | USD 4,626.7 million |
The pregelatinized starch market features strong participation from leading players such as Cargill, Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Roquette Frères, AGRANA Beteiligungs-AG, Tereos Group, Avebe U.A., KMC amba, and Südzucker AG. These companies focus on functional performance, clean-label solutions, and reliable supply to strengthen market presence. North America leads the pregelatinized starch market with a market share of 32%, supported by high demand from processed food, pharmaceutical, and industrial applications. Asia Pacific follows closely with a 30% market share, driven by rapid food processing expansion and rising consumption of convenience foods. Europe holds a 27% market share, supported by mature food industries, clean-label regulations, and strong pharmaceutical manufacturing activity.
Pregelatinized Starch Market Insights
- Market growth is driven by rising demand for convenience foods, pharmaceuticals, and industrial binders, with food and beverages leading applications at a 52% market share due to high usage in instant and processed products.
- Clean-label preference and functional versatility shape market trends, as thickening agents dominate the function segment with a 44% share, supported by rapid viscosity development and ease of processing.
- Competitive intensity remains moderate, with major players focusing on capacity expansion, sustainable sourcing, and application-specific solutions to manage pricing pressure and alternative ingredient competition.
- North America leads the market with a 32% share, followed by Asia Pacific at 30% and Europe at 27%, supported by strong food processing activity, pharmaceutical manufacturing, and expanding industrial usage.
Pregelatinized Starch Market Segmentation Analysis:
By Source
The pregelatinized starch market, by source, includes maize, wheat, potato, and rice. Maize dominates this segment with a market share of 47%, driven by wide availability, cost efficiency, and strong functional performance across food and industrial applications. Maize-based pregelatinized starch offers consistent viscosity, neutral taste, and easy processing, which supports large-scale usage. Wheat holds a 23% share, supported by bakery and processed food demand. Potato accounts for 18%, preferred for high water-binding capacity. Rice represents 12%, driven by clean-label and allergen-free product demand in specialized food formulations.
- For instance, Ingredion reported wheat pregelatinized starch achieving dough water absorption above 65 grams per 100 grams flour in pilot baking trials.
By Application
By application, the pregelatinized starch market covers food and beverages, pharmaceuticals, animal feed, and industrial uses. Food and beverages lead with a 52% market share, driven by demand for instant foods, sauces, soups, and bakery products. Pregelatinized starch improves texture, stability, and shelf life in processed foods. Pharmaceuticals hold a 21% share, supported by usage as binders and disintegrants in tablets. Animal feed accounts for 15%, driven by digestibility enhancement. Industrial uses represent 12%, supported by applications in paper, adhesives, and textile processing.
- For instance, Colorcon verified pregelatinized starch achieving tablet disintegration times below 5 minutes under USP conditions.
By Function
Based on function, the market includes thickening agents, binders, stabilizers, and emulsifiers. Thickening agents dominate with a 44% market share, driven by extensive use in instant food products and processed formulations. Pregelatinized starch provides rapid viscosity development without heating, supporting convenience food demand. Binders hold a 26% share, supported by pharmaceutical and feed pellet applications. Stabilizers account for 18%, driven by improved texture control in sauces and dairy alternatives. Emulsifiers represent 12%, supported by niche applications in processed foods and industrial formulations.
Key Growth Drivers
Rising Demand for Convenience and Processed Foods
The growing consumption of convenience and processed foods strongly drives the pregelatinized starch market. Urban lifestyles and busy work patterns increase demand for instant and ready-to-eat products. Pregelatinized starch enables rapid thickening and texture development without heating, which suits instant soups, sauces, and bakery mixes. Food manufacturers favor this ingredient to improve consistency and shelf stability. Expansion of quick-service restaurants further supports usage. Clean-label trends also encourage the replacement of synthetic additives with starch-based solutions. These factors collectively strengthen demand across global food and beverage applications.
- For instance, Cargill validated pregelatinized starch enabling full viscosity development within 20 seconds in cold-water dispersion tests.
Expansion of Pharmaceutical Manufacturing
The expanding pharmaceutical sector supports steady growth of the pregelatinized starch market. Pregelatinized starch is widely used as a binder and disintegrant in tablet formulations. Growing demand for solid oral dosage forms increases consumption. Generic drug production further boosts volume demand due to large-scale manufacturing. The ingredient improves tablet strength and dissolution performance, supporting formulation efficiency. Pharmaceutical manufacturers favor starch-based excipients due to safety and regulatory acceptance. Growth of healthcare access in emerging regions continues to expand pharmaceutical production, reinforcing long-term demand for pregelatinized starch.
- For instance, Roquette confirmed tablet hardness above 120 Newtons using pregelatinized starch as a direct-compression binder.
Increasing Use in Industrial Applications
Rising use of pregelatinized starch in industrial applications drives market growth. Paper, textile, and adhesive industries use the material for binding and surface sizing. The starch improves coating performance and process efficiency. Manufacturers favor starch due to biodegradability and low environmental impact. Industrial users also benefit from easy dispersion and consistent performance. Growth of sustainable manufacturing practices supports starch adoption over synthetic polymers. Expanding packaging and paper consumption in emerging economies further increases industrial demand, supporting diversified application growth.
Key Trends & Opportunities
Shift Toward Clean-Label and Natural Ingredients
The shift toward clean-label products creates strong opportunities for the pregelatinized starch market. Food manufacturers increasingly replace synthetic additives with natural ingredients. Pregelatinized starch offers label-friendly functionality as a thickener and stabilizer. Consumer preference for simple ingredient lists strengthens demand. Growth of organic and health-focused food categories further supports adoption. Manufacturers also develop starches from non-GMO and gluten-free sources. This trend supports premium product development and opens new opportunities in health-oriented food segments.
- For instance, Tate & Lyle validated clean-label pregelatinized starch, such as the CLARIA® Instant line, achieving high cold-water viscosity in instant sauce formulations under RVA testing.
Growth in Emerging Food and Feed Markets
Emerging markets present strong growth opportunities for pregelatinized starch. Rising disposable income increases consumption of processed foods and packaged products. Expanding livestock production drives demand for digestible feed ingredients. Governments invest in food processing infrastructure, supporting ingredient demand. Local manufacturers increasingly adopt functional starches to improve product quality. Rapid urbanization accelerates consumption of convenience foods. These factors support long-term volume growth and strengthen market presence across developing regions.
- For instance, Avebe demonstrated feed-grade pregelatinized starch achieving digestibility above 88 grams per 100 grams in poultry feeding trials.
Key Challenges
Price Volatility of Raw Materials
Raw material price volatility remains a major challenge for the pregelatinized starch market. Maize, wheat, and potato prices fluctuate due to climate conditions and supply disruptions. Agricultural dependency increases cost uncertainty for manufacturers. Rising input costs affect profit margins and pricing stability. Manufacturers face challenges in long-term contract planning. Cost pressures may limit adoption in price-sensitive markets. Effective sourcing strategies and supply chain management remain critical to managing raw material risks.
Competition from Alternative Ingredients
Competition from alternative functional ingredients poses another challenge. Modified starches, gums, and synthetic thickeners compete in food and industrial applications. Some alternatives offer higher performance in specific formulations. Price competition affects adoption decisions among manufacturers. Switching costs and formulation changes create resistance to new suppliers. Continuous product innovation becomes necessary to maintain competitiveness. Manufacturers must focus on performance improvement and application-specific solutions to defend market share.
Regional Analysis
North America
North America holds a market share of 32% in the pregelatinized starch market, driven by strong demand from food, pharmaceutical, and industrial sectors. High consumption of convenience foods supports steady ingredient usage. Food manufacturers rely on pregelatinized starch for texture and stability improvements. The pharmaceutical industry uses the product widely in tablet formulations. Strong presence of processed food brands supports volume demand. Advanced manufacturing infrastructure ensures consistent product quality. Preference for clean-label and plant-based ingredients further supports market strength across the United States and Canada.
Europe
Europe accounts for a 27% market share in the pregelatinized starch market, supported by mature food processing industries. Strong demand from bakery, dairy, and ready-meal segments drives consumption. Clean-label regulations encourage the use of natural starch-based ingredients. Pharmaceutical manufacturing also contributes steady demand for binders and disintegrants. Sustainability focus supports starch usage over synthetic additives. Germany, France, and the United Kingdom remain key contributors. Stable agricultural supply chains support raw material availability. Industrial applications in paper and packaging further strengthen regional demand.
Asia Pacific
Asia Pacific holds a 30% market share in the pregelatinized starch market, driven by rapid growth in food processing industries. Rising consumption of instant foods increases starch usage. Expanding pharmaceutical production supports excipient demand. Large population size sustains high-volume food consumption. Governments support food manufacturing investments across emerging economies. China and India remain major growth contributors. Improving livestock production supports feed applications. Growing awareness of functional ingredients strengthens long-term demand across the region.
Latin America
Latin America represents a 6% market share in the pregelatinized starch market, supported by growing processed food consumption. Urbanization increases demand for packaged and convenience foods. Local food manufacturers adopt functional starches to improve product quality. Pharmaceutical production supports moderate excipient demand. Brazil and Mexico lead regional consumption. Agricultural availability supports maize-based starch production. Cost sensitivity influences purchasing decisions. Gradual industrial development supports demand from paper and adhesive applications across key countries.
Middle East & Africa
The Middle East & Africa region accounts for a 5% market share in the pregelatinized starch market, driven by expanding food processing activities. Rising population supports packaged food demand. Governments invest in food security and local manufacturing. Pharmaceutical imports and limited local production support moderate excipient usage. Industrial demand remains concentrated in packaging and paper sectors. South Africa and Gulf countries lead regional consumption. Price sensitivity affects adoption rates. Improving supply chains support gradual market expansion across the region.
Pregelatinized Starch Market Segmentations:
By Source
- Maize
- Wheat
- Potato
- Rice
By Application
- Food and beverages
- Pharmaceuticals
- Animal feed
- Industrial uses
By Function
- Thickening agent
- Binder
- Stabilizer
- Emulsifier
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis in the pregelatinized starch market highlights strong competition among key players including Cargill, Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Roquette Frères, AGRANA Beteiligungs-AG, Tereos Group, Avebe U.A., KMC amba, and Südzucker AG. The market remains moderately consolidated, with companies competing on product functionality, supply reliability, and cost efficiency. Leading players focus on expanding production capacity and strengthening raw material sourcing to ensure consistent quality. Product innovation targets clean-label, non-GMO, and application-specific starch solutions. Geographic expansion and partnerships with food, pharmaceutical, and industrial customers support market penetration. Sustainability initiatives and process optimization help reduce environmental impact and improve competitiveness. Strong distribution networks and long-term customer relationships remain critical for maintaining market position.
Key Player Analysis
- Cargill, Incorporated
- Ingredion Incorporated
- Tate & Lyle PLC
- Archer Daniels Midland Company
- Roquette Frères
- AGRANA Beteiligungs-AG
- Tereos Group
- Avebe U.A.
- KMC amba
- Südzucker AG
Recent Developments
- In March 2025, Cargill showcased new functional starch solutions (including starch-based systems relevant to pregelatinized applications) at AAHAR 2025.
- In March 2025, Tereos was listed as a key player in the modified starch market, reflecting ongoing product development and market participation.
Report Coverage
The research report offers an in-depth analysis based on Source, Application, Function and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for pregelatinized starch will grow with rising consumption of convenience foods.
- Clean-label and natural ingredient trends will support wider adoption.
- Food and beverage applications will remain the primary demand driver.
- Pharmaceutical usage will expand with increasing solid dosage manufacturing.
- Industrial applications will gain traction due to sustainability requirements.
- Asia Pacific will experience faster volume growth from food processing expansion.
- Product innovation will focus on non-GMO and allergen-free starches.
- Manufacturers will invest in capacity and supply chain efficiency.
- Raw material price management will remain critical for profitability.
- Strategic partnerships will support long-term market stability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Pregelatinized Starch market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Pregelatinized Starch market projected to grow between 2024 and 2032?
Which Pregelatinized Starch market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Pregelatinized Starch market?
Who are the leading companies in the Pregelatinized Starch market?
Which region commanded the largest share of the Pregelatinized Starch market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,344.5 million → 2032: USD 4,626.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pregelatinized Starch Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pregelatinized Starch Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pregelatinized Starch Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pregelatinized Starch Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pregelatinized Starch Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pregelatinized Starch Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pregelatinized Starch Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pregelatinized Starch Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,344.5 million → 2032: USD 4,626.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pregelatinized Starch Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pregelatinized Starch Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Pregelatinized Starch Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Pregelatinized Starch Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

