
Swiss practices and rehab clinics re-equip as use rises
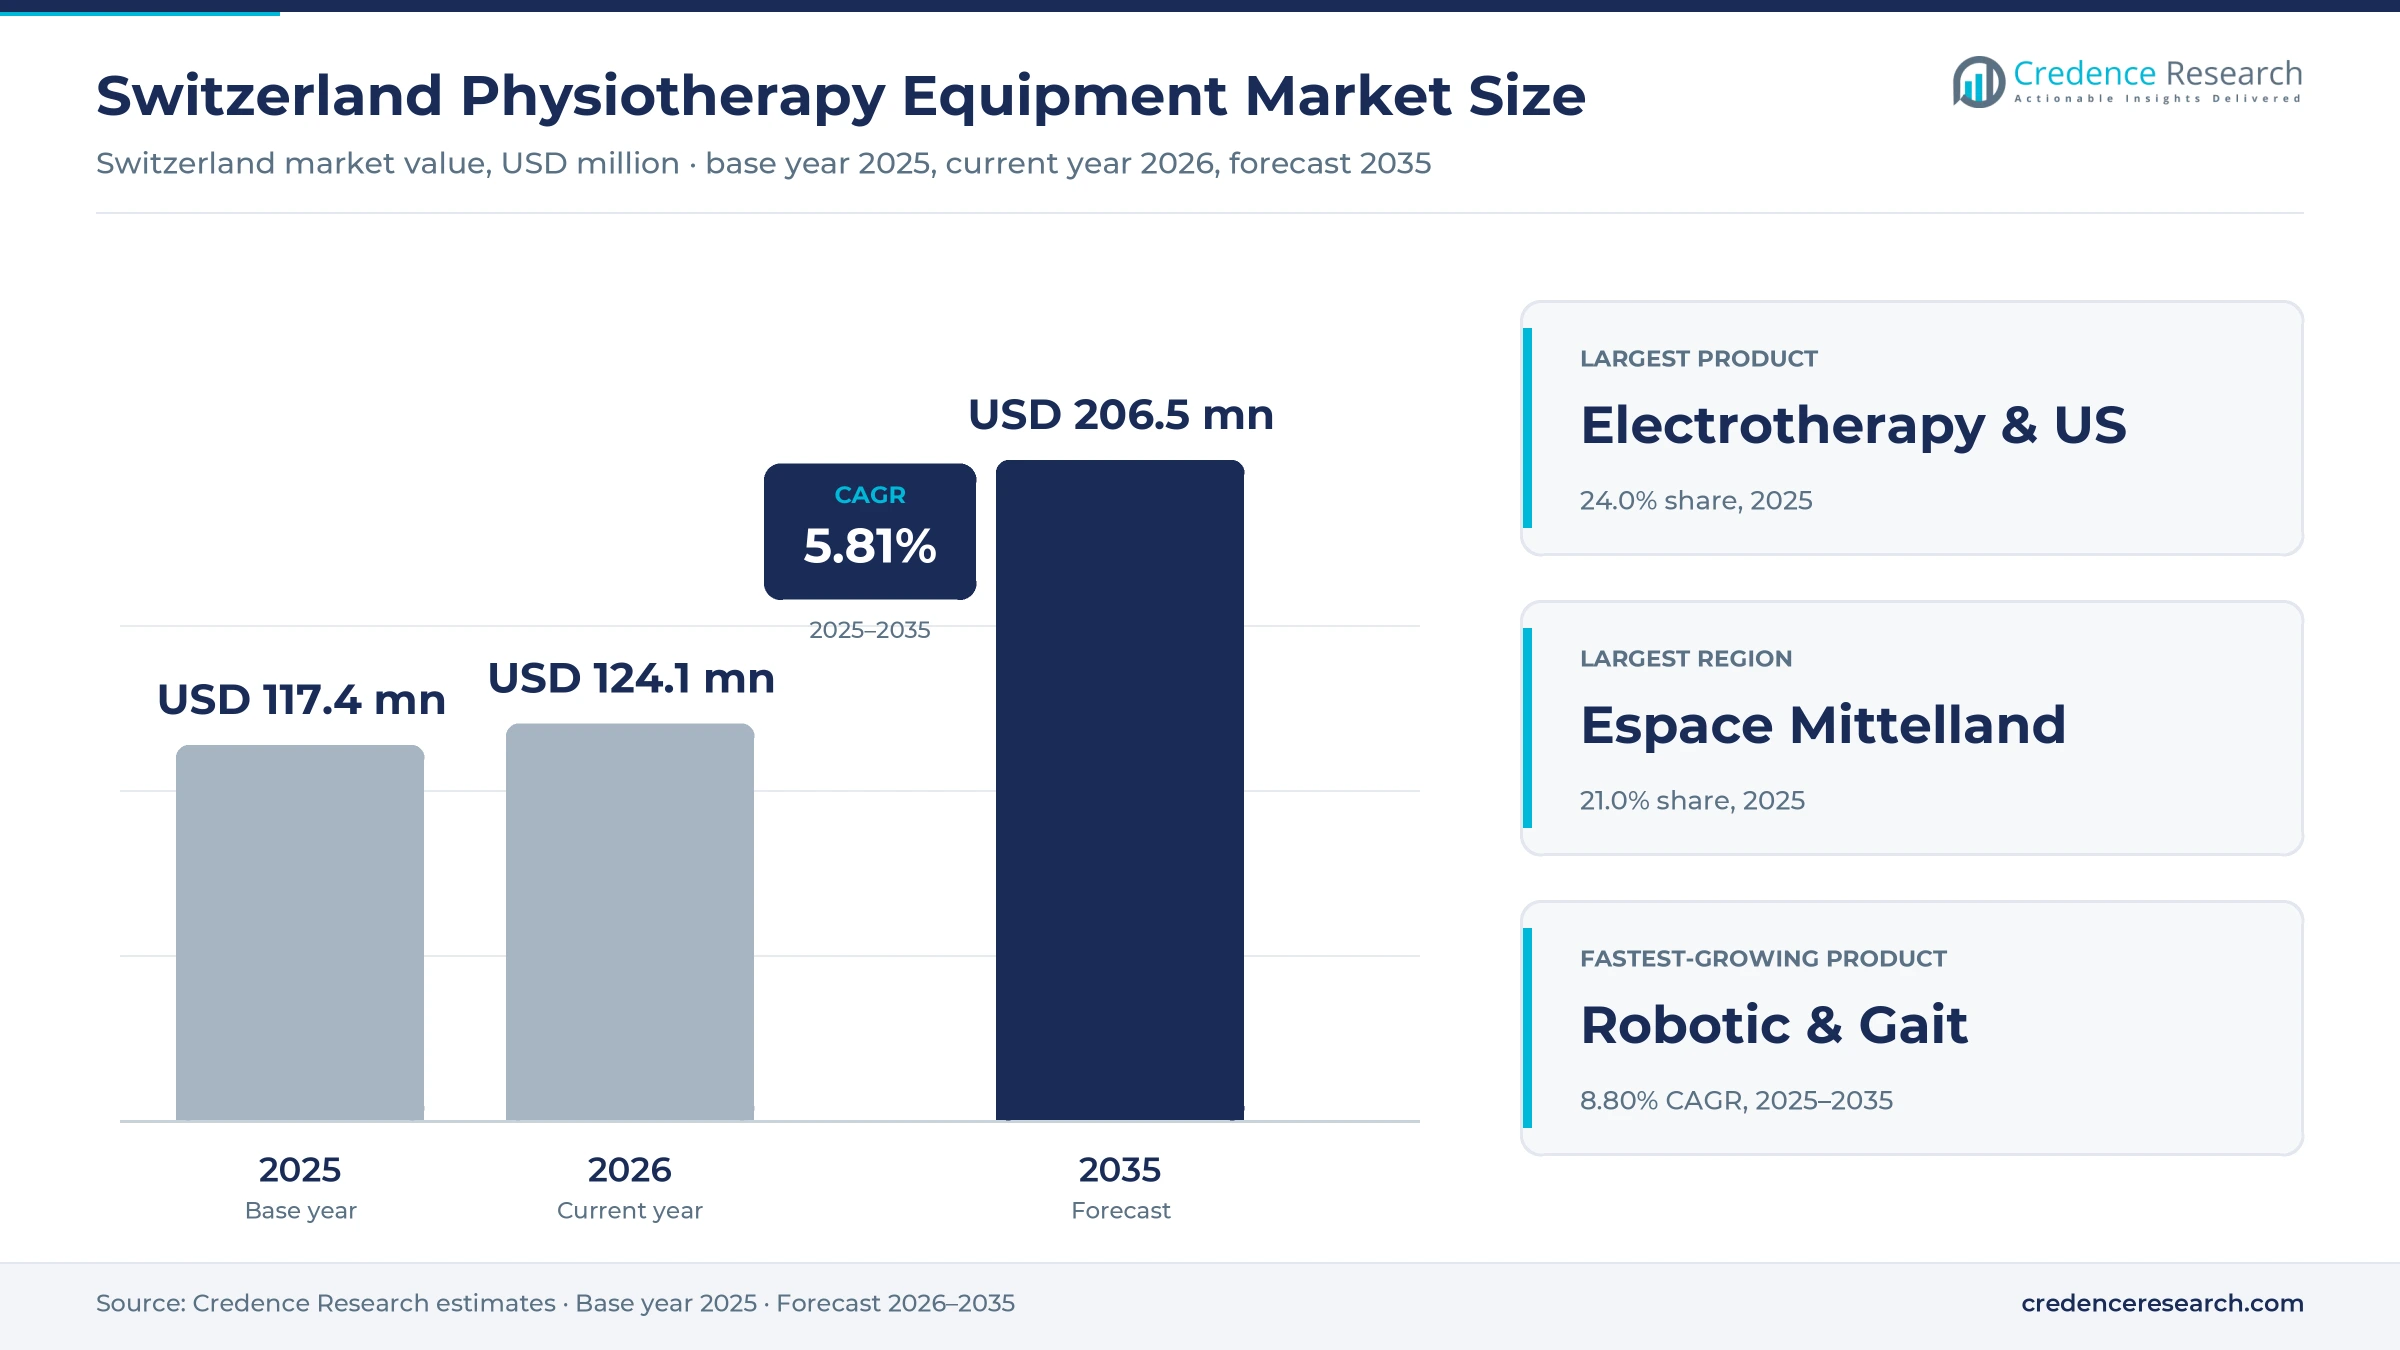
The Switzerland physiotherapy equipment market was valued at USD 117.4 million in 2025 and is projected to increase from USD 124.1 million in 2026 to USD 206.5 million by 2035, registering a CAGR of 5.81% during 2025–2035. Demand follows treatment volume, which is rising as more insured people use physiotherapy and attend more sessions, while Switzerland counted more people aged 65 and over than under 20 at the end of 2025. Espace Mittelland accounted for 21.0% of 2025 value, the largest regional share, supported by large rehabilitation clinics around Bern and a broad base of private practices. The main commercial change is a new time-based physiotherapy tariff, submitted to the Federal Council in April 2026 and planned for January 2027, which bills in five-minute units and favors active-therapy rooms and devices that document treatment.
Which Swiss buyers purchase physiotherapy equipment, and what is excluded?
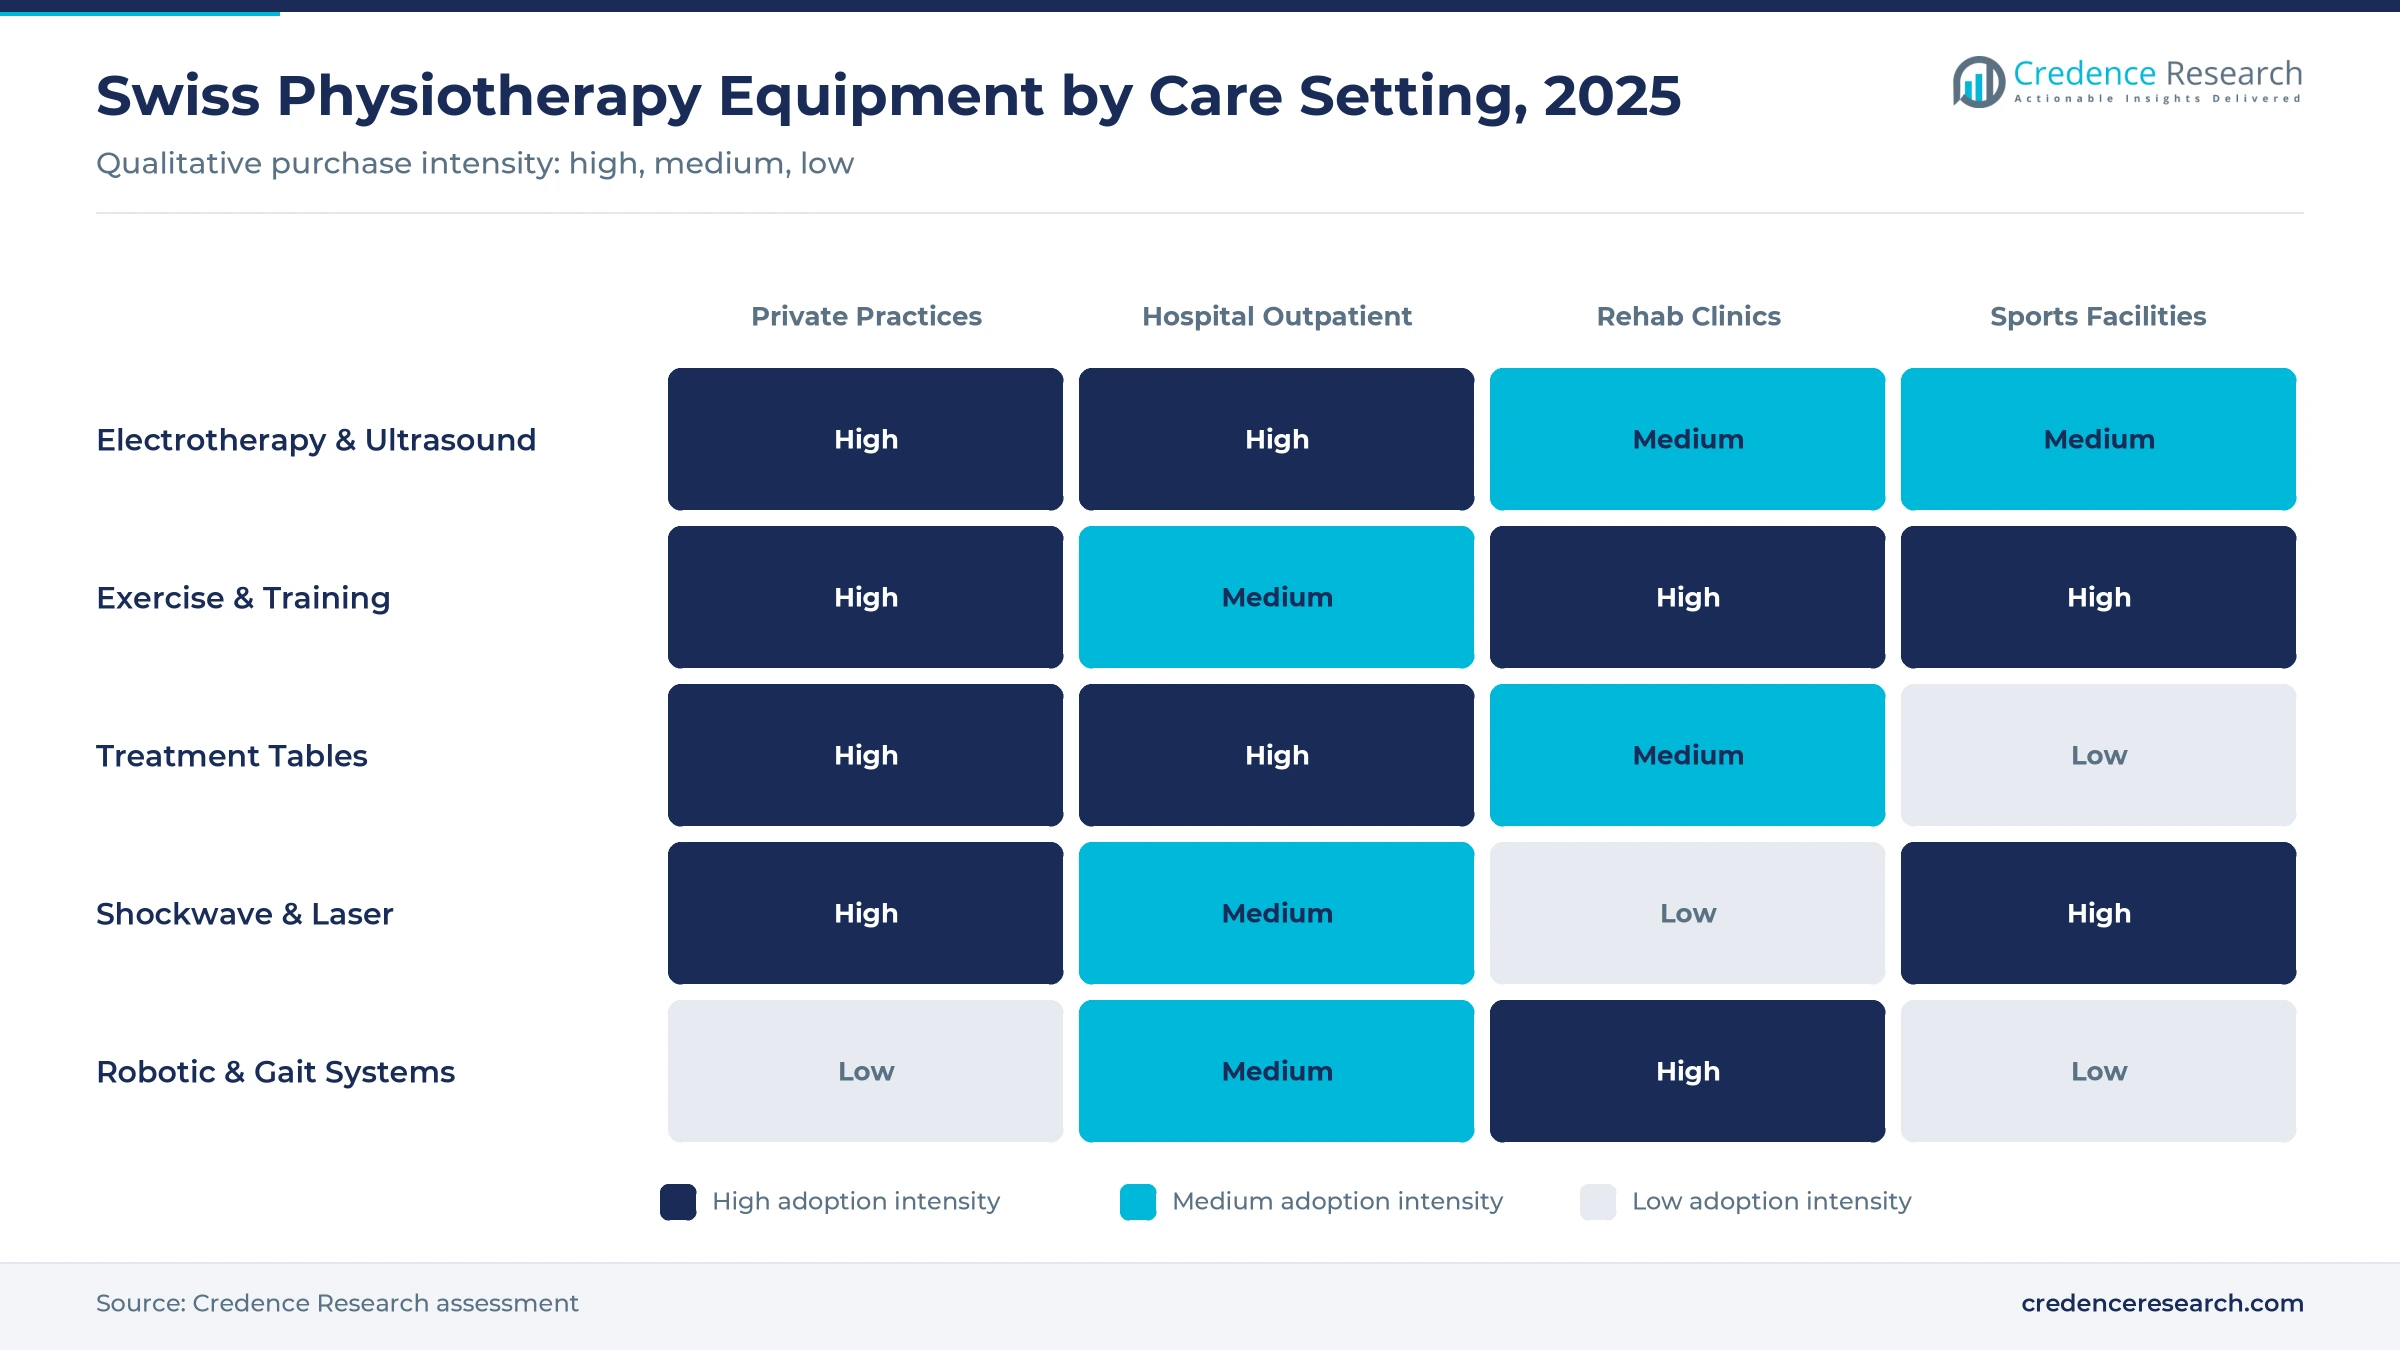
Equipment demand comes from outpatient physiotherapy practices, hospital physiotherapy departments, rehabilitation clinics, sports facilities and home-care providers. Practices buy electrotherapy units, treatment tables and training equipment when they open, expand or refit, while clinics fund robotic gait and upper-limb systems from capital budgets. Most care is reimbursed under compulsory health insurance, so treatment volume and the national tariff set how much practices can invest.
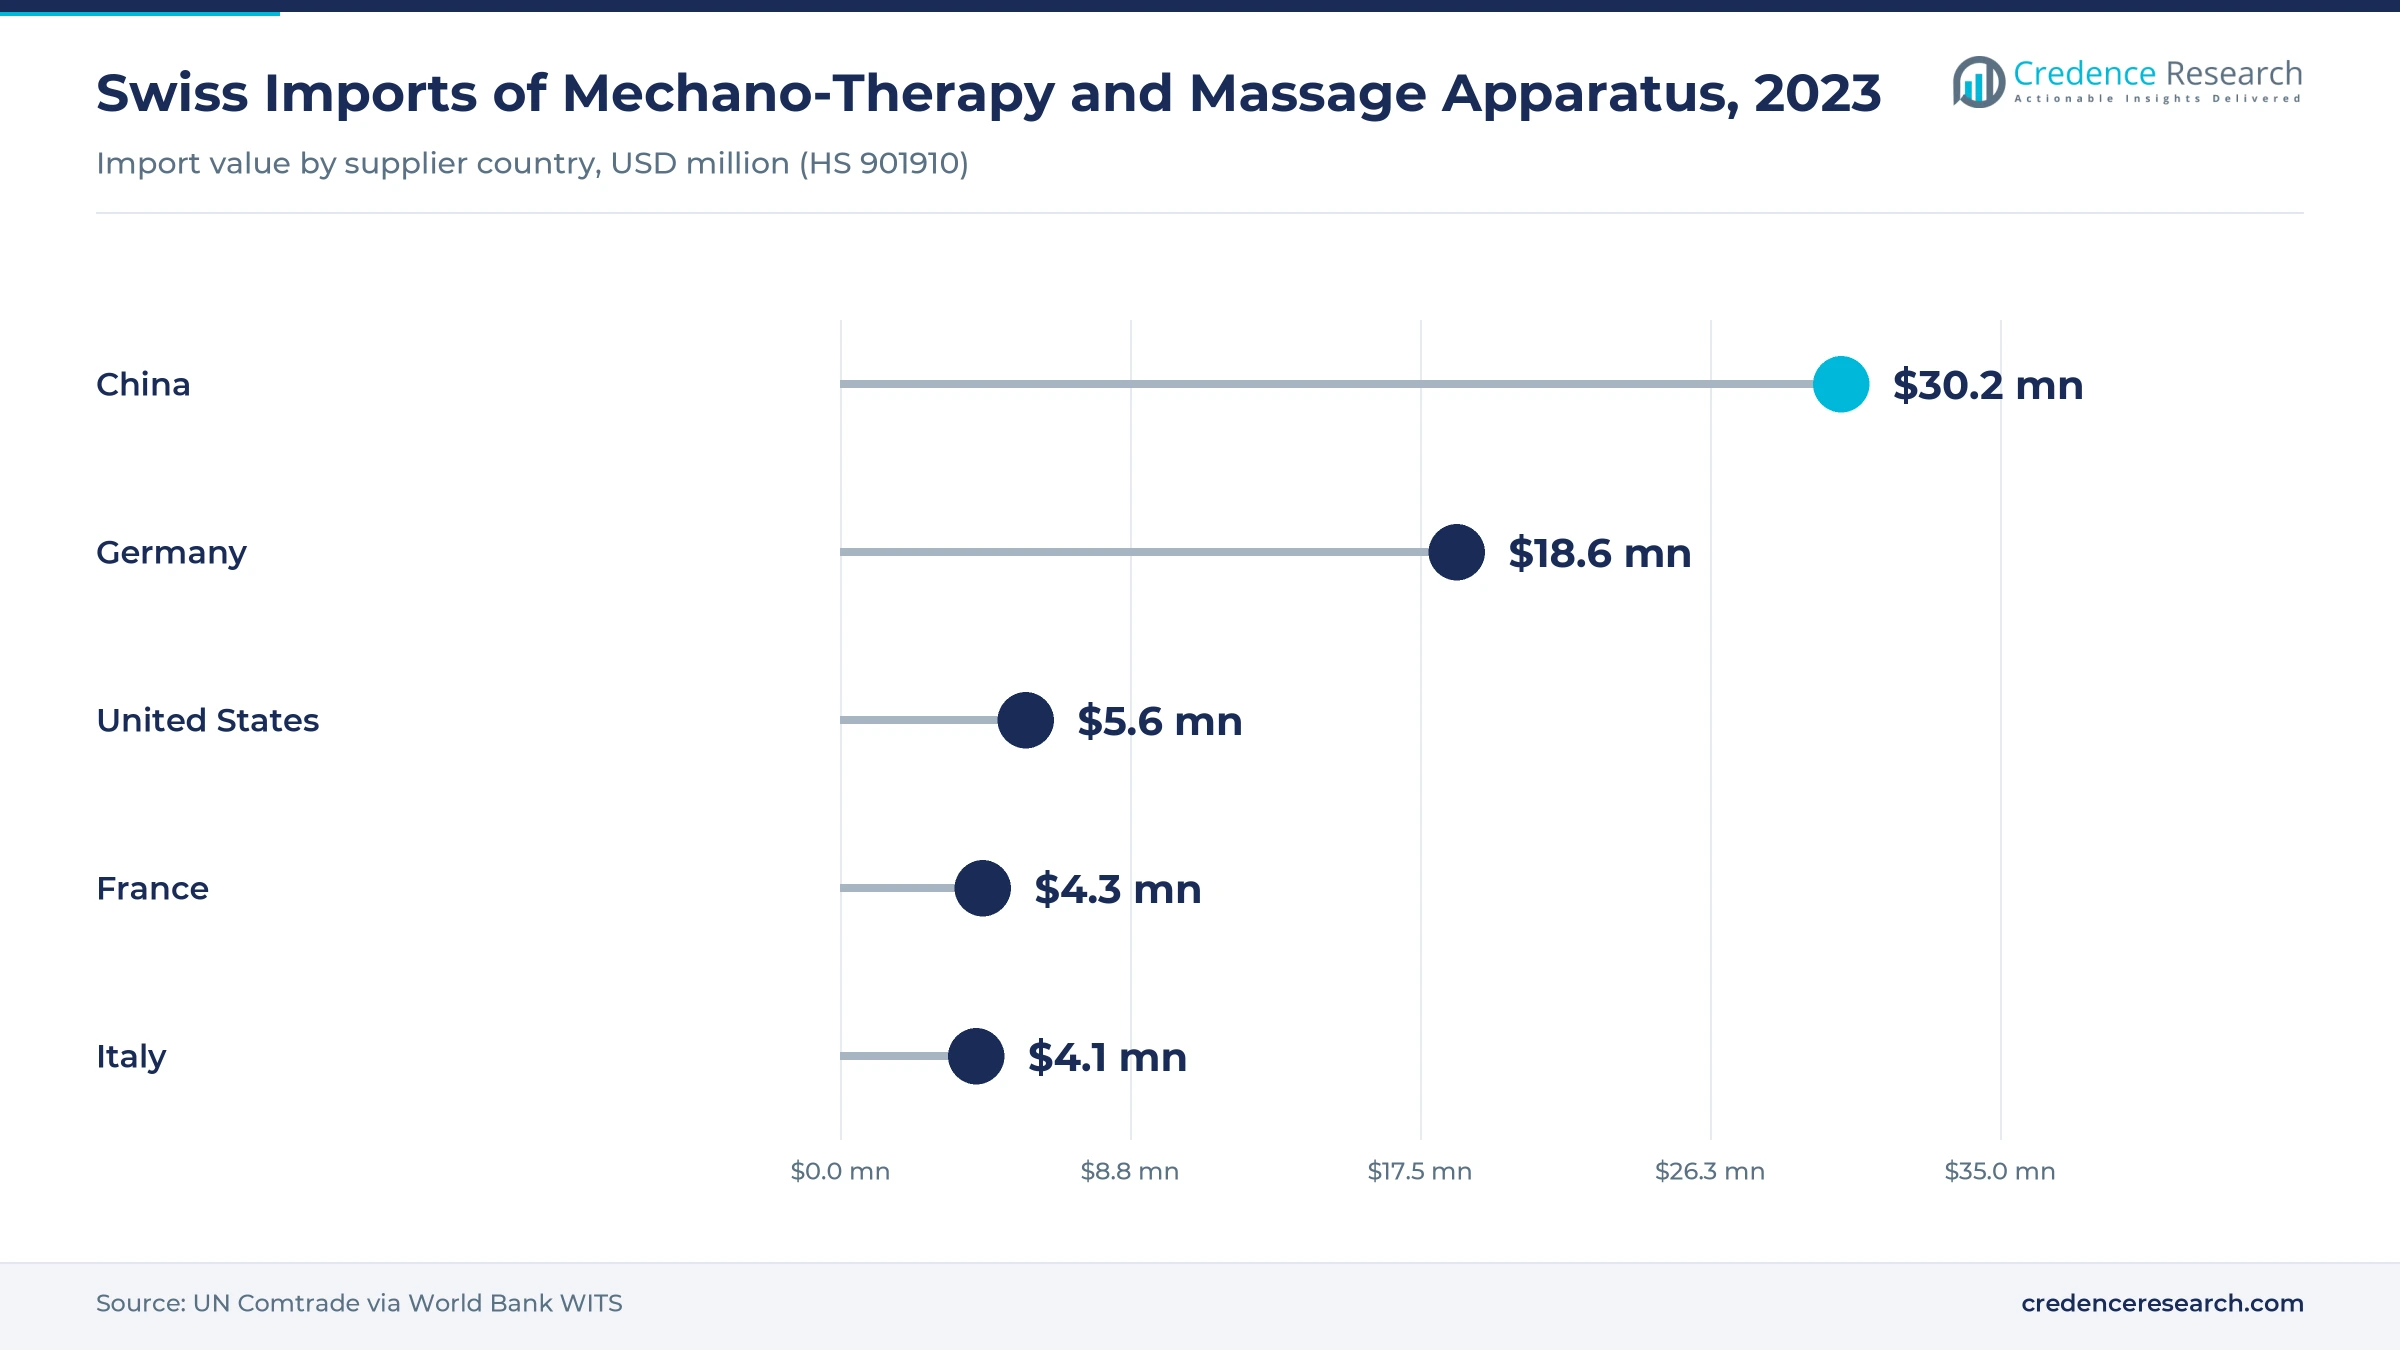
The estimate excludes consumer massage chairs and wellness devices, orthoses, wheelchairs and other assistive devices, and consumables such as electrodes, gels and tapes, along with service contracts. According to UN Comtrade data on World Bank WITS, Switzerland imported USD 30.2 million of mechano-therapy and massage apparatus from China and USD 18.6 million from Germany in 2023, and much of the Chinese volume is consumer massage equipment outside the market.
Switzerland Physiotherapy Equipment Market Insights
- The Switzerland physiotherapy equipment market is projected to grow from USD 124.1 million in 2026 to USD 206.5 million by 2035, a 5.81% CAGR, as treatment volume keeps rising.
- Espace Mittelland accounted for 21.0% of 2025 value, the largest Swiss regional share, because large rehabilitation clinics around Bern anchor capital spending.
- Electrotherapy and ultrasound devices accounted for 24.0% of 2025 value, the largest product group, because nearly every Swiss practice runs these units.
- A time-based physiotherapy tariff planned for January 2027 moves billing to five-minute units, shifting practice investment toward active therapy rooms and documentation.
- Robotic and gait rehabilitation systems grow fastest at 8.80% a year from 2025 to 2035, rewarding Swiss specialists such as Hocoma in neurological rehabilitation.
Electrotherapy holds value while gait robots supply growth
Electrotherapy and ultrasound lead products while robotic gait systems grow fastest
Based on product, the market is categorized into electrotherapy and ultrasound devices, exercise and strength training equipment, treatment tables and manual therapy, shockwave and laser therapy devices, robotic and gait rehabilitation systems, and heat, cold, hydro and other equipment. Electrotherapy and ultrasound led with 24.0% of 2025 value, because almost every practice runs these units. Robotic and gait systems grow fastest at 8.80% a year as regional clinics adopt them.
Musculoskeletal care leads applications while neurological rehabilitation grows fastest
Based on application, the market is categorized into musculoskeletal and orthopedic care, neurological rehabilitation, sports injuries, cardiopulmonary and geriatric care, and pediatric and other uses. Musculoskeletal and orthopedic care led with 46.0% of 2025 value, reflecting back pain, joint replacement and post-surgical treatment. Neurological rehabilitation grows fastest at 7.22% a year, because stroke and spinal cord patients need high-repetition training that robots deliver.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Product | Electrotherapy & Ultrasound Devices | 24.0% | Robotic & Gait Rehabilitation Systems | 8.80% |
| By Application | Musculoskeletal & Orthopedic | 46.0% | Neurological Rehabilitation | 7.22% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
More users, more sessions and aging drive Swiss demand
More insured patients use physiotherapy, and each attends more sessions
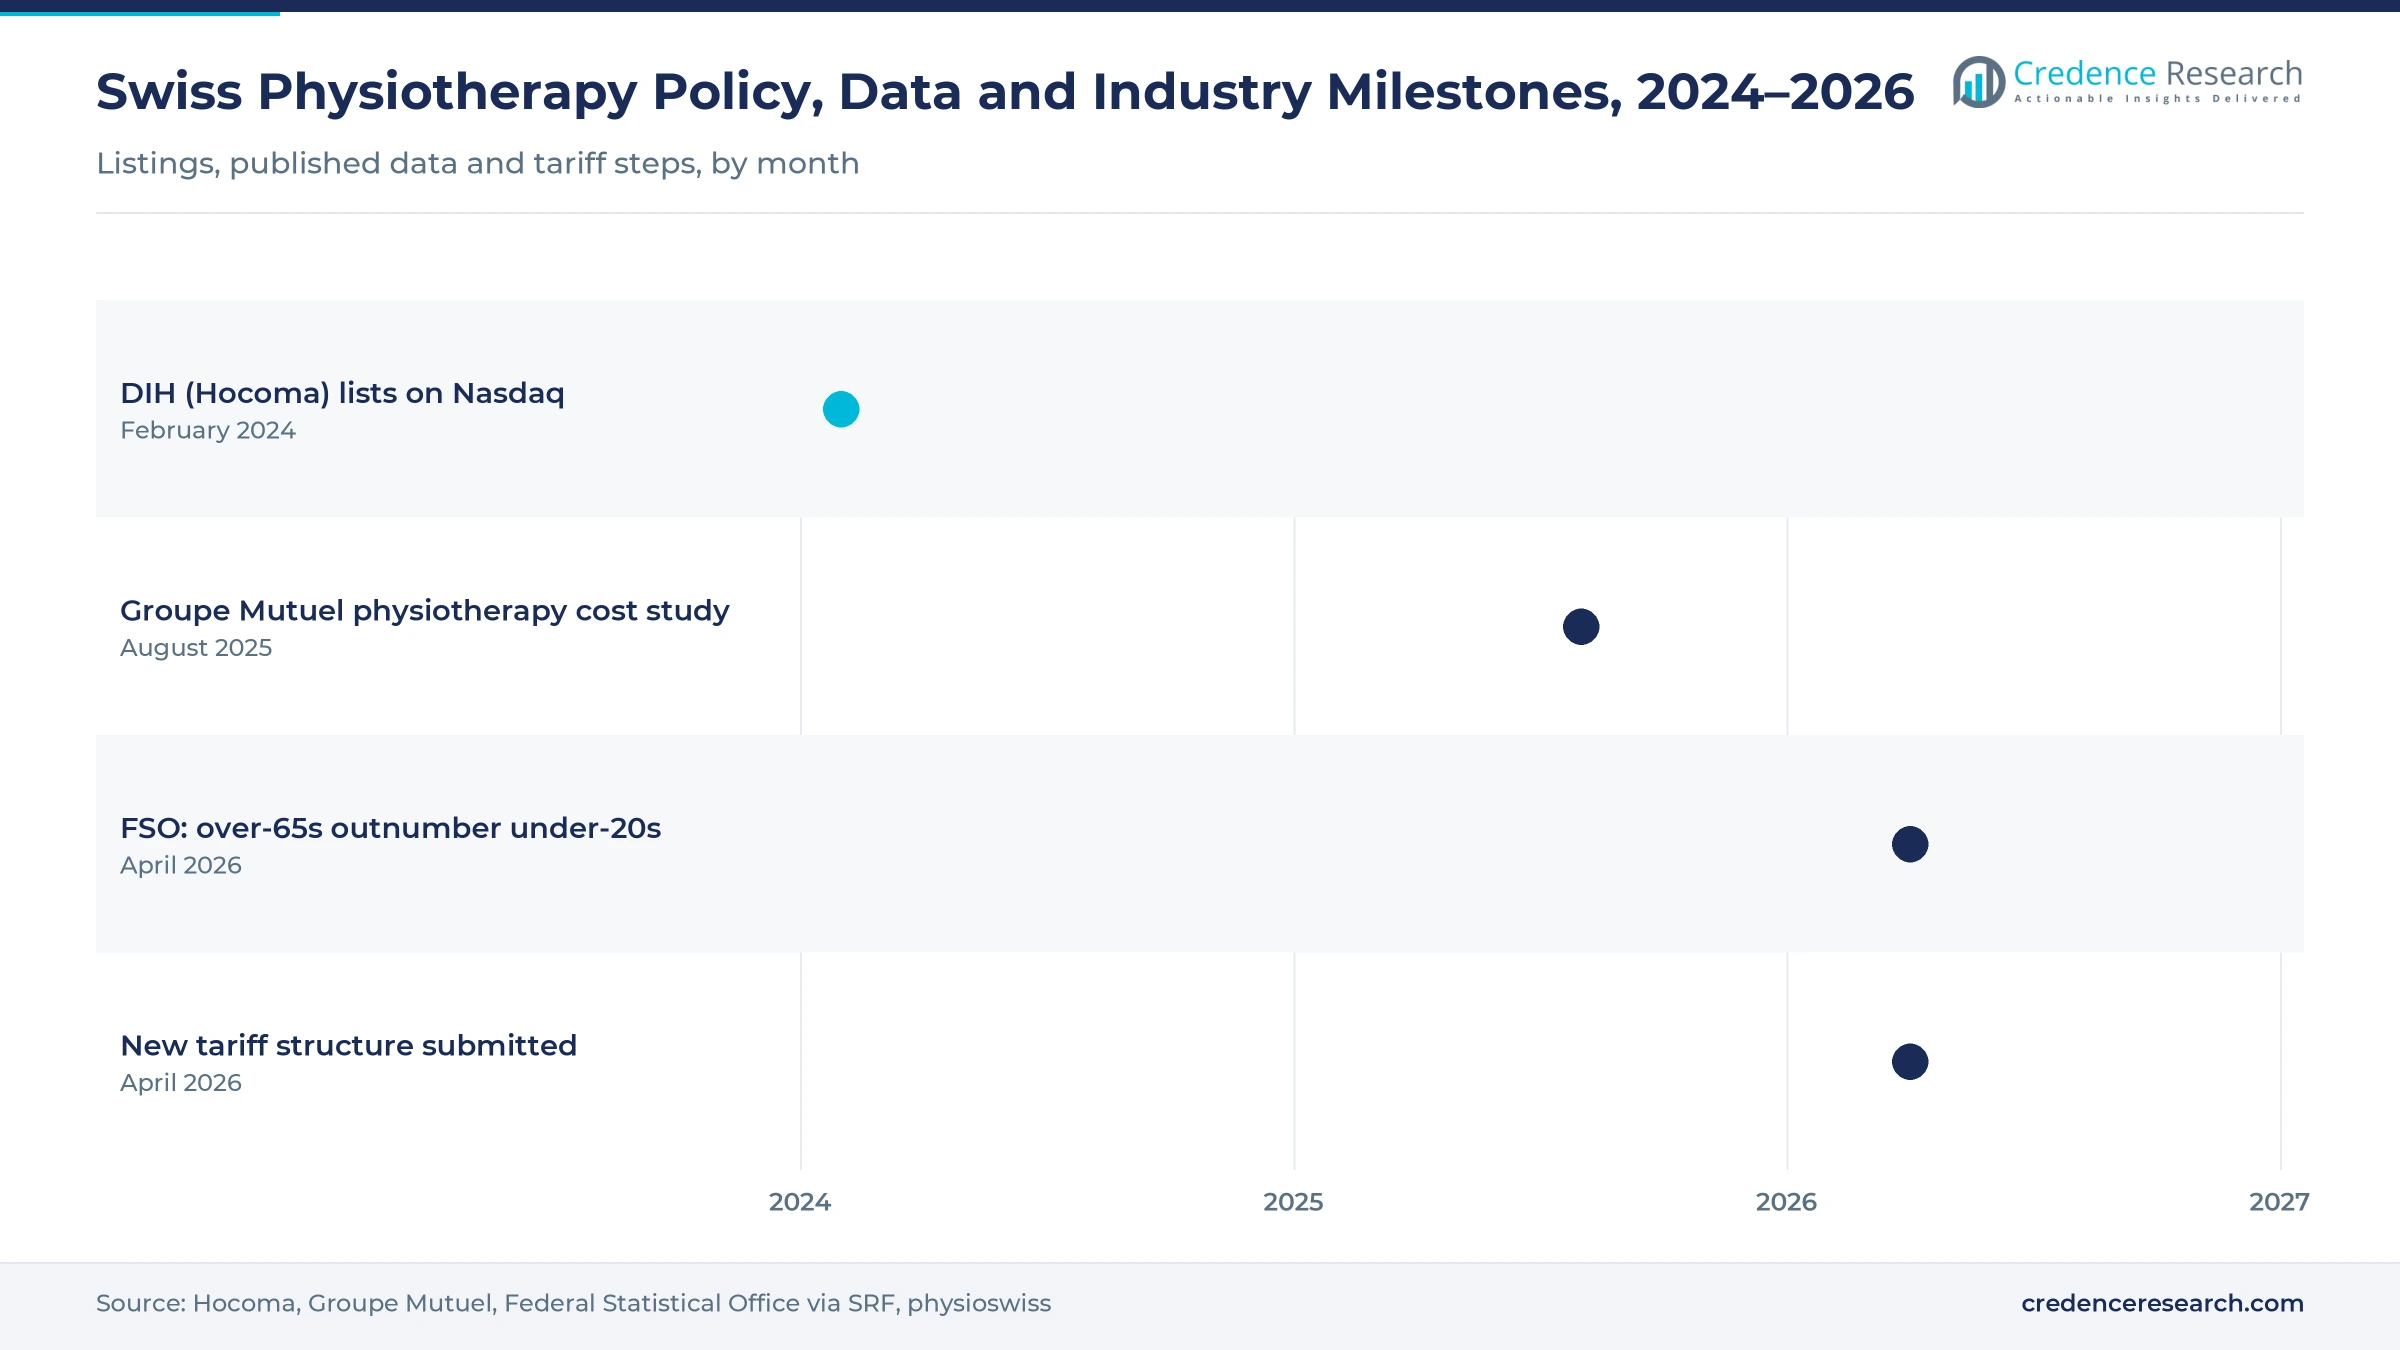
A Zurich University of Applied Sciences study funded by Fondation Groupe Mutuel, summarized in Groupe Mutuel claims analysis, shows the share of insured people using physiotherapy rising from 14% in 2017 to 19% in 2023, with average sessions per user up from 13 to 16. Cost per insured person rose from CHF 120 to CHF 200, and about 40% of that increase came from more users. More treatment hours require more rooms, devices and faster replacement across Swiss practices, a long-term effect.
An older population needs joint, fall and stroke rehabilitation
Older patients need physiotherapy after joint replacement, falls and strokes, and for chronic back and joint pain. SRF reported Federal Statistical Office figures showing 1,811,000 people aged 65 and over at the end of 2025, against 1,802,000 under 20, the first time older residents outnumbered the young. The same study attributes only 16% of the cost increase to aging, so demographics add a steady, long-term base of patients rather than the main push behind short-term equipment orders.
Complex, active sessions shift purchases toward training equipment
Swiss physiotherapists increasingly treat with guided exercise rather than passive treatment alone. The share of complex, more expensive sessions rose from 14% to 34% between 2017 and 2023, and about 40% of the cost increase reflects more intensive use. Practices respond by adding training rooms, cable machines and sensor-based devices that record progress. The shift is medium term and supports exercise equipment and connected devices in urban practices, where complex sessions have risen fastest.
Neurological rehabilitation draws robotics investment from Swiss clinics
Stroke, spinal cord injury and multiple sclerosis patients benefit from high-repetition training that robots and gait systems deliver. Switzerland is a home market for this technology through Hocoma, and its rehabilitation clinics are early buyers. Neurological rehabilitation therefore grows fastest among applications, and robotic systems lead product growth. Swiss demand for these systems depends on clinic capital budgets and cantonal hospital planning over the long term, although leasing and shared-use models now help regional clinics that cannot fund a full purchase.
Time-based tariff and connected devices shift Swiss buying
A time-based tariff rewards documented, longer treatments
In April 2026, physioswiss, the hospital association H+ and insurer association prio.swiss announced that they had submitted a new tariff structure for physiotherapy to the Federal Council. Planned for Jan. 1, 2027, it moves billing from a flat fee per session to itemized services in five-minute units. Time-based billing favors practices that document complex treatment, so equipment that records exercise data gains value. Practices are likely to time refits around the change, if it is approved.
A shift to combination and connected devices replaces single-function units
Practices prefer combination units that deliver electrotherapy and ultrasound from one device, saving space in small treatment rooms, and training equipment that stores patient data for progress reports to insurers. This trend favors suppliers that link devices to therapy software, and it puts price pressure on basic stand-alone stimulators. Swiss buyers also weigh multilingual service and repair quality as heavily as device features when they refit treatment rooms.
Robotic gait and upper-limb systems open an opportunity beyond flagship clinics
Robotic gait trainers, upper-limb robots and body-weight support systems are spreading from university hospitals to regional rehabilitation clinics. Robotic and gait rehabilitation systems are the fastest-growing product, and suppliers that offer leasing, shared-use models and training for therapists can win clinics that cannot fund a full purchase. The barrier is price, so financing, therapist training and evidence of better functional outcomes decide how fast regional clinics adopt these systems.
Shockwave, laser and home therapy offer an opportunity to widen the buyer base
Radial and focused shockwave devices and high-intensity laser therapy are now common in Swiss practices treating tendon and soft-tissue problems, and Swiss makers Storz Medical and EMS supply shockwave devices. Short hospital stays also push rehabilitation into the home, with rented exercise and electrotherapy devices and app-guided programs. Home use is still small, but it adds demand for compact devices and rental services from dealers that already serve practices, and it gives suppliers a second channel beyond clinic budgets.
Cost containment, robot prices and staff gaps limit budgets
Insurer cost containment squeezes practice margins
Outpatient physiotherapy is paid under a national tariff negotiated between insurers and providers, including the new structure announced in April 2026. Physiotherapy costs per user rose 67% between 2017 and 2023, and insurers want to slow that growth. When fees stay flat while rents and wages rise, practices delay buying equipment, which hits suppliers of tables, electrotherapy and training devices first. Mitigation comes from equipment that documents outcomes and supports time-based billing under the planned tariff.
Robotic systems remain affordable only for larger clinics
A robotic gait trainer costs far more than a typical practice spends on equipment over several years, so adoption depends on hospital budgets and cantonal funding. Smaller clinics and private practices are largely excluded, which slows the spread of robotics outside major centers and lengthens sales cycles for suppliers. Leasing, pay-per-use contracts and shared regional facilities lower the entry cost, and published evidence on outcomes helps clinics justify the investment.
Therapist shortages limit the value of new equipment
Clinics and practices compete for physiotherapists, and equipment adds little value if there are not enough therapists to use it. Staff shortages slow the opening of new practices and delay capacity expansions in rehabilitation clinics, which reduces equipment orders in the affected regions. Suppliers respond with devices that let one therapist supervise several patients, such as robotic trainers and sensor-based circuits, and with training programs that shorten onboarding for newly hired therapists in busy practices.
Long replacement cycles slow table and passive-device sales
Treatment tables, heat and cold units and other passive equipment last many years and are replaced only when a practice expands or refits. That limits repeat demand for makers of these products and makes their sales sensitive to practice openings rather than treatment volume. Suppliers mitigate the effect with service contracts, trade-in offers and upgrade paths that bundle tables with electrotherapy or training equipment during a refit, which turns a single replacement into a larger order.
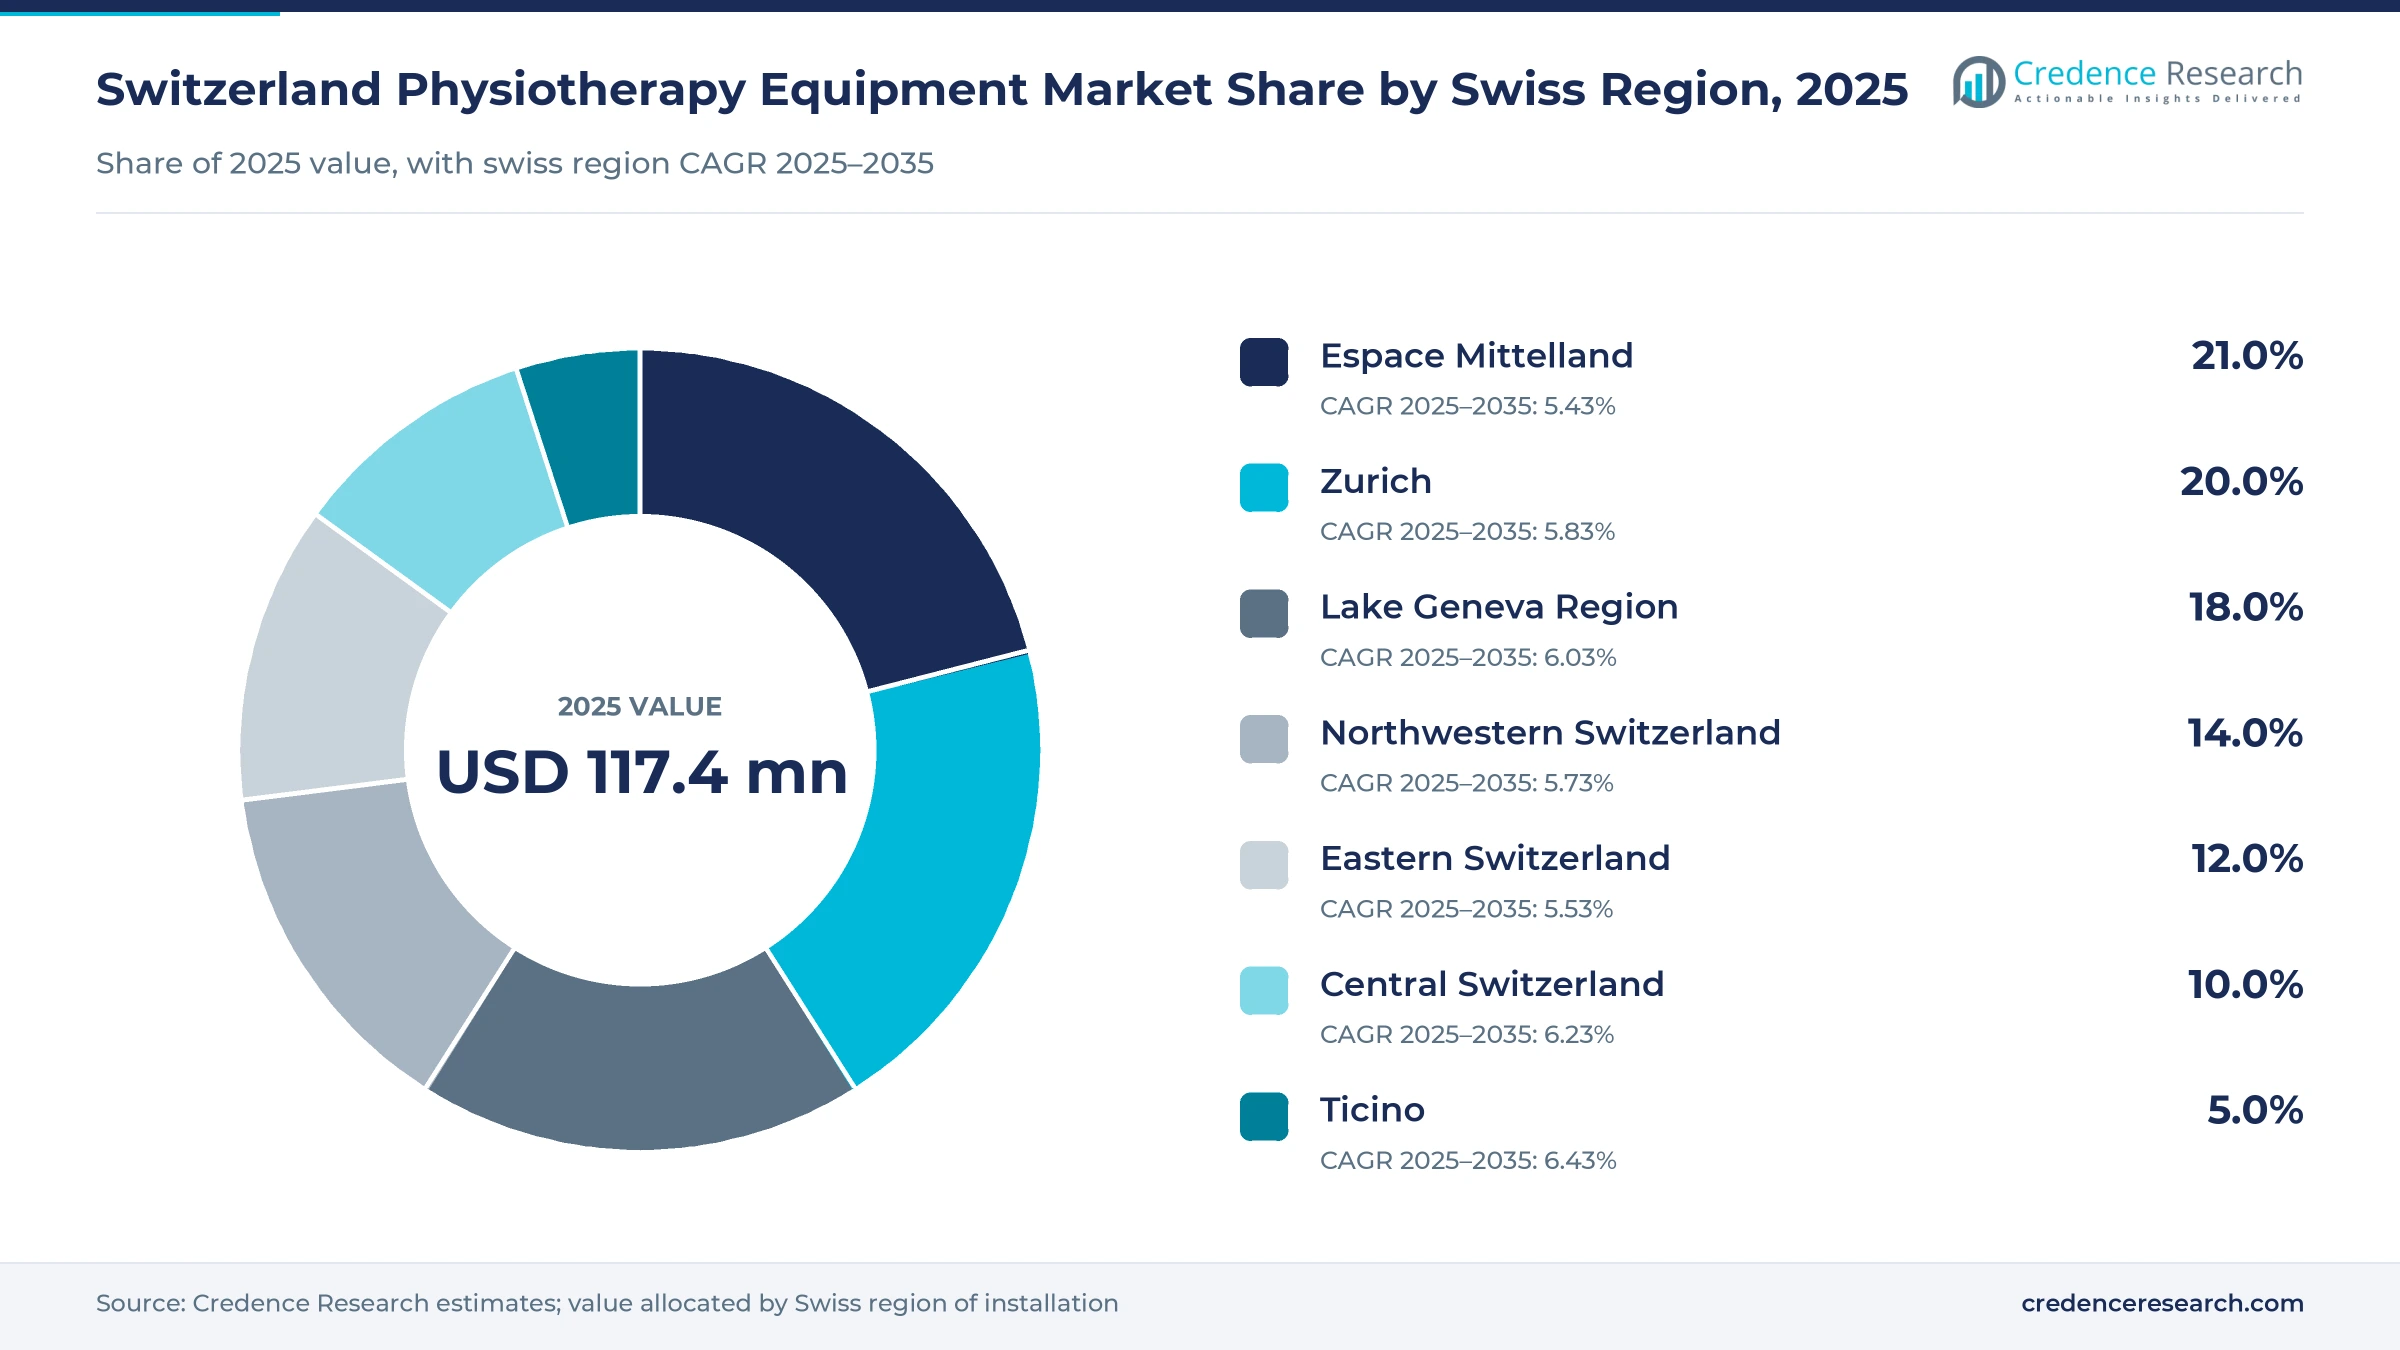
Bern and Zurich carry demand while Ticino expands fastest
| Swiss Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Espace Mittelland | 21.0% | 5.43% |
| Zurich | 20.0% | 5.83% |
| Lake Geneva Region | 18.0% | 6.03% |
| Northwestern Switzerland | 14.0% | 5.73% |
| Eastern Switzerland | 12.0% | 5.53% |
| Central Switzerland | 10.0% | 6.23% |
| Ticino | 5.0% | 6.43% |
Espace Mittelland is the largest region, anchored by rehabilitation clinics around Bern
Espace Mittelland held 21.0% of 2025 value and grows at 5.43% a year. The region spans the cantons of Bern, Fribourg, Solothurn, Neuchâtel and Jura, and its large rehabilitation clinics around Bern buy robotic gait systems and complete therapy rooms. Practice density is lower than in Zurich, which keeps growth below the national rate, but clinic refits and neurological rehabilitation programs support steady capital spending through 2035. German-speaking and French-speaking practices in the region expect dealer service in both languages.
Zurich combines dense private practices and university rehabilitation
Zurich held 20.0% of 2025 value and grows at 5.83% a year. The canton has the densest network of private practices and university hospital rehabilitation, and complex sessions have risen sharply there, which favors training equipment and connected devices. High rents in the city push practices toward compact combination units. Zurich is also the most populous Swiss canton, which sustains a broad base of outpatient treatment and steady replacement demand across both city and suburban practices.
Lake Geneva Region gains growth from above-average use
The Lake Geneva Region held 18.0% of 2025 value and grows at 6.03% a year. Physiotherapy use per person is above the national average, and the region recorded a sharp rise in complex sessions between 2017 and 2023. French-speaking practices buy through dealers with local service teams, and active-therapy refits add to demand as practices adapt to complex, time-intensive treatment. Growth runs above the national rate through 2035, supported by Geneva and Vaud hospitals and private clinics.
Northwestern and Eastern Switzerland show steady, practice-led demand
Northwestern Switzerland held 14.0% of 2025 value and grows at 5.73% a year. Eastern Switzerland held 12.0% and grows at 5.53% a year, where usage rates are among the lowest in the country.
Central Switzerland and Ticino grow fastest from lower bases
Central Switzerland held 10.0% of 2025 value and grows at 6.23% a year. Ticino held 5.0% and is the fastest-growing region at 6.43% a year, with the highest share of physiotherapy users in Switzerland, about one in five insured people, and an older population.
A new tariff, an aging milestone and a robotics listing
| Development | Status and market relevance |
|---|---|
| In April 2026, physioswiss, H+ and prio.swiss announced that they had submitted a new physiotherapy tariff structure to the Federal Council, planned to take effect on Jan. 1, 2027. | Submitted for approval. Moves billing to five-minute units. |
| In April 2026, Federal Statistical Office figures showed that Switzerland had more people aged 65 and over than under 20 at the end of 2025. | Published. Signals rising demand for geriatric and orthopedic rehabilitation. |
| In August 2025, Groupe Mutuel published a study showing physiotherapy costs per insured person rising from CHF 120 in 2017 to CHF 200 in 2023. | Published. Confirms rising treatment volume, the main demand driver. |
| In February 2024, DIH Holding U.S., parent of Hocoma, completed its merger with Aurora Technology Acquisition Corp. and listed on Nasdaq. | Completed. Gives a Swiss-founded robotics business access to public capital. |
Robotics, sensor-based training and combination units
- Rehabilitation robotics such as gait trainers, exoskeleton-based systems and upper-limb robots deliver high numbers of repetitions per session for neurological patients.
- Sensor-based training machines that measure force, range and repetitions produce the documentation that time-based billing rewards.
- Combination units that combine electrotherapy, ultrasound and sometimes laser save space and cost in small Swiss treatment rooms.
- Shockwave and laser devices, including radial and focused shockwave and high-intensity laser, extend practice services for tendon and soft-tissue conditions.
- Tariff and documentation are now linked, as the planned five-minute billing units tie equipment choice to how well practices can record treatment time and content.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Swiss robotics and shockwave makers face European brands
The Swiss market is served by a few domestic specialists, European device makers and local dealers that equip practices. Hocoma, part of the Nasdaq-listed DIH group, leads in robotic gait and upper-limb rehabilitation, while Swiss makers Storz Medical and EMS (Electro Medical Systems) are leading names in shockwave therapy. Zimmer MedizinSysteme, Enraf-Nonius, BTL and Enovis, through its Chattanooga brand, compete in electrotherapy, ultrasound and laser. Gymna supplies treatment tables, and Technogym and David Health Solutions supply medical training equipment. Service and language matter, because practices buy through dealers that install, calibrate and repair equipment in German, French and Italian, and clinics expect on-site training. In February 2024, DIH, the parent of Hocoma, completed its merger with Aurora Technology Acquisition Corp. and listed on Nasdaq, giving the robotics business access to public capital. No supplier publishes Swiss physiotherapy equipment sales, so no share ranking is given.
Companies profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Hocoma (DIH) | Swiss robotics specialist | Robotic gait and upper-limb rehabilitation systems |
| Storz Medical | Swiss shockwave specialist | Radial and focused shockwave therapy devices |
| EMS (Electro Medical Systems) | Swiss device maker | Shockwave therapy devices |
| Zimmer MedizinSysteme | European device maker | Electrotherapy, ultrasound and laser devices |
| Enraf-Nonius | European device maker | Electrotherapy, ultrasound and laser devices |
| BTL | European device maker | Electrotherapy, ultrasound and laser devices |
| Enovis | Device maker | Electrotherapy and ultrasound through the Chattanooga brand |
| Gymna | European device maker | Treatment tables |
| Technogym | Training equipment maker | Medical training equipment |
| David Health Solutions | Training equipment maker | Medical training equipment |
Treatment volume, not device novelty, sets the Swiss cycle
Credence Research's view is that Swiss equipment spending tracks treatment volume more than device innovation, and treatment volume keeps rising as more insured people attend more, and more complex, sessions. The largest new demand lies in robotic rehabilitation for neurological patients and in active-therapy rooms with training equipment that documents care. Suppliers with local service teams in three languages and financing for clinics are best positioned. The main risk is insurer pressure on fees, which delays practice refits. Buyers and suppliers should watch the tariff approval and therapist supply.
Claims studies, practice counts and import records
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built from physiotherapy use per insured person, the number of practices and rehabilitation clinics and equipment replacement cycles; segment and regional splits are Credence Research estimates. Supporting evidence comes from insurer claims studies, Federal Statistical Office population data, UN Comtrade import records, tariff documents and company information.
Active therapy rooms and rehab robots lead Swiss spending
Through 2035, Swiss equipment demand will tilt toward active-therapy rooms, connected training devices and robotic rehabilitation. The time-based tariff, if approved for 2027, is likely to trigger refits as practices adapt to five-minute billing. Ticino, Central Switzerland and the Lake Geneva Region will grow faster than the national rate, while Espace Mittelland and Zurich remain the largest regions. Robotic rehabilitation will spread from flagship centers to regional clinics as financing models mature. The pace will depend on insurer cost controls, therapist supply and clinic capital budgets.
Frequently Asked Questions
What was the size of the Switzerland physiotherapy equipment market in 2025?
What is the forecast value and CAGR of the Swiss physiotherapy equipment market?
What is driving physiotherapy equipment demand in Switzerland?
Which Swiss region holds the largest share of the market?
Which product leads Swiss physiotherapy equipment sales?
How will the new physiotherapy tariff affect equipment buying?
Who are the major companies in the Swiss physiotherapy equipment market?
What challenges could slow the Swiss physiotherapy equipment market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Electrotherapy & Ultrasound Devices
- 1.2.2 Exercise & Strength Training Equipment
- 1.2.3 Treatment Tables & Manual Therapy
- 1.2.4 Shockwave & Laser Therapy Devices
- 1.2.5 Robotic & Gait Rehabilitation Systems
- 1.2.6 Heat, Cold, Hydro & Other
- 1.3 By Application
- 1.3.1 Musculoskeletal & Orthopedic
- 1.3.2 Neurological Rehabilitation
- 1.3.3 Sports Injuries
- 1.3.4 Cardiopulmonary & Geriatric Care
- 1.3.5 Pediatric & Other
- 1.4 By Swiss Region
- 1.4.1 Espace Mittelland
- 1.4.2 Zurich
- 1.4.3 Lake Geneva Region
- 1.4.4 Northwestern Switzerland
- 1.4.5 Eastern Switzerland
- 1.4.6 Central Switzerland
- 1.4.7 Ticino
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 117.4 million → 2035: USD 206.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Switzerland Physiotherapy Equipment Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Switzerland Physiotherapy Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Switzerland Physiotherapy Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Switzerland Physiotherapy Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Switzerland Physiotherapy Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Switzerland Physiotherapy Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Switzerland Physiotherapy Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Switzerland Physiotherapy Equipment Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 117.4 million → 2035: USD 206.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Switzerland Physiotherapy Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Electrotherapy & Ultrasound Devices
- 12.3.7.2 Exercise & Strength Training Equipment
- 12.3.7.3 Treatment Tables & Manual Therapy
- 12.3.7.4 Shockwave & Laser Therapy Devices
- 12.3.7.5 Robotic & Gait Rehabilitation Systems
- 12.3.7.6 Heat, Cold, Hydro & Other
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Musculoskeletal & Orthopedic
- 12.4.7.2 Neurological Rehabilitation
- 12.4.7.3 Sports Injuries
- 12.4.7.4 Cardiopulmonary & Geriatric Care
- 12.4.7.5 Pediatric & Other
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Swiss Region - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Espace Mittelland
- 12.5.7.2 Zurich
- 12.5.7.3 Lake Geneva Region
- 12.5.7.4 Northwestern Switzerland
- 12.5.7.5 Eastern Switzerland
- 12.5.7.6 Central Switzerland
- 12.5.7.7 Ticino
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Switzerland Physiotherapy Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Switzerland Physiotherapy Equipment Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Switzerland Physiotherapy Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Switzerland Physiotherapy Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hocoma (DIH)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Storz Medical
- 18.4 EMS (Electro Medical Systems)
- 18.5 Zimmer MedizinSysteme
- 18.6 Enraf-Nonius
- 18.7 BTL
- 18.8 Enovis
- 18.9 Gymna
- 18.10 Technogym
- 18.11 David Health Solutions
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

