
Market Overview:
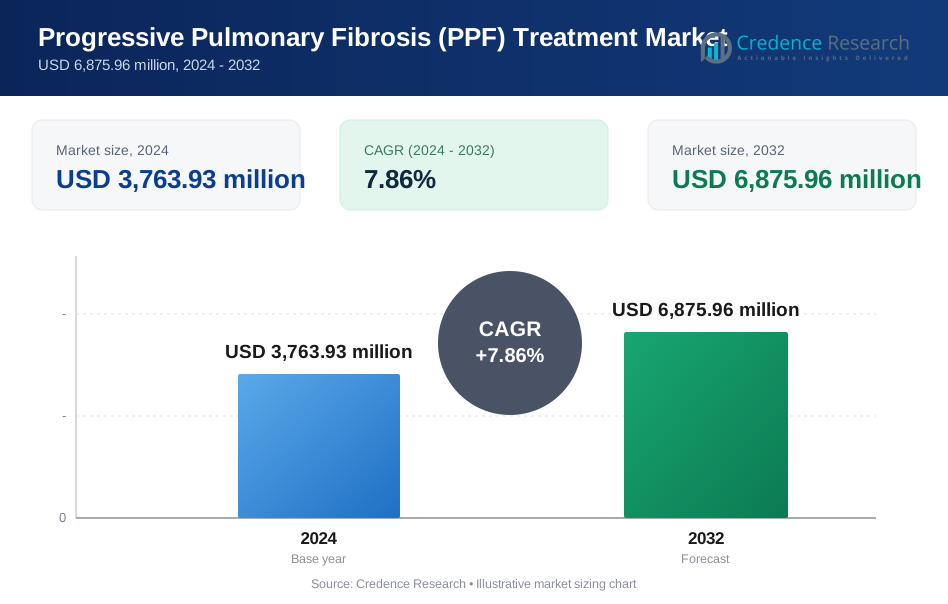
The Progressive Pulmonary Fibrosis (PPF) Treatment Market size was valued at USD 2,800.00 million in 2018 to USD 3,763.93 million in 2024 and is anticipated to reach USD 6,875.96 million by 2032, at a CAGR of 7.86% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Progressive Pulmonary Fibrosis (PPF) treatment market Size 2024 | USD 3,763.93 million |
| Progressive Pulmonary Fibrosis (PPF) treatment market , CAGR | 7.86% |
| Progressive Pulmonary Fibrosis (PPF) treatment market Size 2032 | USD 6,875.96 million |
The market is expanding steadily due to increased disease recognition, improved diagnostic techniques, and growing demand for early-stage intervention. Rising prevalence of interstitial lung diseases, especially in aging populations, is fueling treatment adoption. Availability of antifibrotic drugs and emerging combination therapies is reshaping long-term disease management. Healthcare systems are integrating guidelines for structured diagnosis and referral pathways. Pharmaceutical companies continue to invest in novel drug development, supported by incentives for orphan indications.
North America currently leads the market due to its advanced healthcare infrastructure, strong reimbursement coverage, and early adoption of antifibrotic therapies. Europe follows with widespread treatment protocols and established pulmonary care networks. Asia Pacific is emerging as a high-growth region due to its rising patient base, expanding hospital networks, and increasing research investment. Latin America and the Middle East show steady progress, supported by partnerships and awareness initiatives. Africa remains in early stages, with market growth linked to future healthcare expansion and access improvements.

Market Insights:
- The market reached USD 2,800.00 million in 2018, grew to USD 3,763.93 million in 2024, and is projected to reach USD 6,875.96 million by 2032, reflecting a CAGR of 7.86% over the period.
- North America leads with about 42.15% share, followed by Asia Pacific at 25.93% and Europe at 21.78%, supported by strong healthcare systems, early diagnosis, and wider access to antifibrotic therapies.
- Asia Pacific is the fastest‑growing region with a 25.93% share, driven by a large patient base, rising awareness, expanding hospital networks, and increased clinical research activity.
- Latin America accounts for nearly 5.53% share, supported by improving urban healthcare access and gradual adoption of structured pulmonary care in major countries.
- Middle East and Africa together contribute about 4.59% share, reflecting limited access and awareness today, but showing steady progress through healthcare investments and specialty center expansion.
Market Drivers
Growing Incidence of Interstitial Lung Diseases Among Aging Populations Worldwide
The rising elderly population has increased the diagnosis of interstitial lung diseases, including progressive pulmonary fibrosis. Age-related decline in lung function and immunity makes this group more vulnerable to fibrotic lung conditions. This leads to higher demand for long-term respiratory treatment and specialist care. Healthcare systems are allocating more resources to manage chronic pulmonary diseases. The Progressive Pulmonary Fibrosis (PPF) Treatment Market benefits from this demographic shift. Geriatric care facilities are also improving diagnostic and treatment capacities. Pharmaceutical firms are targeting this age group with tailored therapies. Aging-linked inflammation and tissue degeneration remain key clinical targets. It supports consistent patient flow into care pipelines and drives sustained therapy demand.
- For instance, Boehringer Ingelheim's nintedanib reduced the adjusted annual rate of FVC decline by 57% (from 187.8 mL/year placebo to 80.8 mL/year) over 52 weeks in the Phase III INBUILD trial for progressive fibrosing ILDs, including older patients.
Stronger Clinical Guidelines and Diagnostic Standards Enabling Early Detection
Medical bodies have improved clinical guidelines for detecting and managing fibrotic lung conditions. Physicians now follow clearer protocols to identify PPF at earlier stages. Access to high-resolution imaging and lung function testing has improved diagnostic accuracy. This enables early intervention and better treatment outcomes. The Progressive Pulmonary Fibrosis (PPF) Treatment Market gains from wider adoption of structured assessment tools. Pulmonologists rely more on multidisciplinary care models. It supports long-term therapy planning and patient monitoring. Early detection reduces hospital admissions and long-term complications. Hospitals invest in training and screening to meet new standards.
High Clinical Trial Activity Supporting Drug Innovation and Label Expansion
Drug developers are investing in trials for novel antifibrotic and anti-inflammatory agents. Ongoing studies explore combination therapies and biomarkers for disease tracking. The Progressive Pulmonary Fibrosis (PPF) Treatment Market grows with trial outcomes that lead to regulatory approvals. Many trials focus on expanding indications for existing drugs. It also encourages investment from biotech firms and specialty pharma players. Increased pipeline visibility improves investor confidence. Trial enrollment is rising across North America, Europe, and Asia. Public and private research institutions collaborate to accelerate evidence generation. New data allows faster adaptation of treatment protocols.
- For instance, Roche’s pirfenidone, in the Phase III ASCEND trial, reduced the proportion of patients experiencing a ≥10% decline in FVC or death at 52 weeks to 16.5%, compared to 31.8% in the placebo group, demonstrating a significant slowing of lung function decline in fibrotic lung disease.
Increasing Role of Patient Advocacy and Global Awareness Campaigns
Patient organizations play a key role in promoting early diagnosis and treatment access. Advocacy groups work with health systems to educate patients about symptoms and therapies. Campaigns highlight unmet needs and influence policy reforms. The Progressive Pulmonary Fibrosis (PPF) Treatment Market benefits from these efforts through higher patient engagement. Digital platforms help disseminate information to broader audiences. It improves patient-doctor interactions and increases adherence to therapies. Governments recognize the burden of chronic lung diseases more clearly. Funding and coverage support expand through lobbying efforts. Stakeholder collaboration helps shape supportive care environments.
Market Trends
Integration of Digital Health Technologies into Pulmonary Care Management Pathways
Digital tools enhance patient monitoring, symptom tracking, and data collection. Remote care models allow physicians to monitor lung function over time. It helps reduce clinic visits and supports early intervention when symptoms worsen. The Progressive Pulmonary Fibrosis (PPF) Treatment Market sees increased use of wearable devices and connected inhalers. These solutions improve adherence and reduce delays in treatment adjustment. AI-enabled software assists in interpreting imaging data and progression risk. Pulmonary centers are adopting virtual care platforms to manage chronic patients. Telehealth reimbursement is expanding across regions. Technology-driven models gain favor in long-term disease management.
- For instance, Qureight’s AI imaging platform supports clinical trials by quantifying changes in lung fibrosis volume with high sensitivity, aiding more precise assessment of disease progression.
Adoption of Personalized and Precision Medicine Approaches in Therapy Development
Biomarker-based drug development is shaping the next generation of treatment options. Researchers identify genetic and molecular signatures linked to fibrotic progression. The Progressive Pulmonary Fibrosis (PPF) Treatment Market increasingly supports patient stratification methods. Targeted therapies improve clinical outcomes by addressing specific fibrotic mechanisms. Precision dosing and disease subtype classification drive clinical decisions. It reduces trial-and-error prescribing and limits unnecessary side effects. Pharma companies invest in companion diagnostics and biomarker validation. Personalized medicine strategies influence regulatory pathways and trial design. Market players differentiate portfolios through patient-centric innovation.
- For instance, a bioinformatics study identified a three‑gene signature (IL13RA2, CDH3, COMP) that showed high diagnostic accuracy for idiopathic pulmonary fibrosis across multiple independent datasets.
Shift Toward Combination Therapy and Multi-Target Drug Formulations
Monotherapies have limited effect in halting progressive lung scarring in many patients. Clinicians explore drug combinations that address both fibrosis and inflammation. The Progressive Pulmonary Fibrosis (PPF) Treatment Market reflects this transition through pipeline diversification. Companies focus on integrating antifibrotics with immunomodulators or kinase inhibitors. It allows broader efficacy coverage and improved symptom control. Combination regimens undergo phased clinical evaluation globally. Health systems evaluate long-term outcomes of dual therapy protocols. Payers assess cost-effectiveness of multi-target drugs. Physicians align treatment goals with holistic patient needs.
Increased Inclusion of Underrepresented Populations in Global Clinical Trials
Global sponsors expand patient recruitment across Asia, Latin America, and the Middle East. Historically underrepresented populations are gaining trial access through site expansion. It diversifies clinical evidence and improves generalizability of study outcomes. The Progressive Pulmonary Fibrosis (PPF) Treatment Market supports inclusivity in regulatory submissions. Local CROs help manage compliance and logistics in emerging trial geographies. Greater demographic diversity enhances real-world relevance of safety data. It strengthens post-approval outcomes across varied populations. Governments encourage trial investments through incentives and streamlined approvals. Sponsors integrate equity goals into research strategies.
Market Challenges Analysis
Limited Awareness and Misdiagnosis Rates Delay Treatment Initiation for Many Patients
Many patients remain undiagnosed or misdiagnosed due to overlapping symptoms with other lung diseases. General practitioners often lack training to recognize fibrotic patterns early. This leads to delays in referrals and missed intervention windows. The Progressive Pulmonary Fibrosis (PPF) Treatment Market faces barriers from fragmented referral systems. Lung function decline accelerates before treatment begins. Patients enter therapy late in the disease course, reducing outcomes. Primary care pathways lack standardized screening for fibrotic markers. Misclassification with COPD or asthma is common in early stages. It weakens patient access to advanced therapies.
High Cost of Treatment and Limited Reimbursement Coverage in Several Regions
Antifibrotic therapies are expensive and require sustained use, often over years. Not all health systems reimburse these treatments fully. The Progressive Pulmonary Fibrosis (PPF) Treatment Market encounters affordability issues in middle- and low-income regions. Patients face high out-of-pocket costs or coverage rejections. Insurers apply strict eligibility criteria for drug reimbursement. Budget impact concerns influence formulary decisions. Physicians hesitate to prescribe costly drugs without assurance of payment. Lack of financial support discourages long-term adherence. It affects market penetration and therapy uptake globally.

Market Opportunities
Emerging Focus on Early Intervention and Screening Programs for High-Risk Groups
Pulmonary specialists and health systems are launching screening programs targeting smokers, elderly individuals, and those with autoimmune conditions. These efforts support early-stage diagnosis and timely treatment planning. The Progressive Pulmonary Fibrosis (PPF) Treatment Market gains from this preventive approach. Health insurers support screening initiatives to reduce future hospitalizations. It allows physicians to start patients on therapy before irreversible damage occurs. Industry partners fund awareness campaigns to improve participation rates. Radiologists play a stronger role in identifying fibrotic patterns early. Screening improves patient outcomes and strengthens therapy value.
Expansion of Research Collaborations Between Academic Centers and Biotech Innovators
Universities and research institutes partner with biotech firms to explore novel fibrosis targets. These partnerships pool resources and shorten discovery cycles. The Progressive Pulmonary Fibrosis (PPF) Treatment Market benefits from accelerated innovation. Shared databases and tissue banks support preclinical validation. Collaborative funding reduces early-stage financial risk. It encourages niche players to enter the market with focused programs. Public grants further incentivize rare disease research. New research hubs emerge in Asia and Europe.
Market Segmentation Analysis:
By Treatment Type, antifibrotic therapy holds the dominant share due to its disease-modifying effect. Drugs like nintedanib and pirfenidone slow disease progression and are widely prescribed. Immunosuppressants follow, especially in cases with autoimmune links, where they reduce inflammation. Supportive or adjunct therapy includes corticosteroids, oxygen support, and pulmonary rehabilitation, helping improve patient quality of life. The Progressive Pulmonary Fibrosis (PPF) Treatment Market benefits from the expanding clinical use of combination approaches involving these treatment types.
- For instance, Insilico Medicine’s rentosertib in the Phase 2a GENESIS‑IPF trial showed improved lung function compared with placebo while meeting predefined safety endpoints, supporting its potential in fibrotic lung disease research.
By Route of Administration, oral therapies remain the preferred choice due to ease of use and better compliance. Most antifibrotic drugs are available in oral forms, making them suitable for outpatient settings. Inhalation therapies offer targeted pulmonary delivery, reducing systemic side effects. Intravenous routes are used in hospital environments, mainly for acute episodes or when rapid intervention is needed. It supports diverse care models ranging from home-based care to specialized hospital treatments.
- For instance, nerandomilast in the FIBRONEER‑IPF and FIBRONEER‑ILD trials slowed lung function decline over one year in more than 2,200 participants across 40+ countries, both as monotherapy and in combination with existing antifibrotics, supporting its potential benefit in fibrotic lung disease.
By End-User, hospitals and clinics form the largest segment, handling both initial diagnosis and long-term management. Specialty treatment centers offer focused care, including advanced diagnostics, trial participation, and multidisciplinary support. Home care is gaining traction among stable patients, supported by telemedicine and portable devices. It enables continuity of care and reduces patient burden. Demand continues to shift toward outpatient and home-based care solutions, especially in developed markets.

Segmentation:
By Treatment Type:
- Antifibrotic Therapy
- Immunosuppressants
- Supportive / Adjunct Therapy
By Route of Administration:
- Oral
- Inhalation
- Intravenous
By End-User:
- Hospitals & Clinics
- Specialty Treatment Centers
- Home Care
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Progressive Pulmonary Fibrosis (PPF) Treatment Market size was valued at USD 1,192.80 million in 2018 to USD 1,586.85 million in 2024 and is anticipated to reach USD 2,895.48 million by 2032, at a CAGR of 7.9% during the forecast period. North America holds the largest market share at 42.15% in 2024, driven by high disease awareness and advanced healthcare infrastructure. The region benefits from early diagnosis practices and strong reimbursement systems. Leading pharmaceutical companies operate clinical trials extensively in the U.S. and Canada. The presence of FDA-approved antifibrotic drugs boosts drug availability. It sees high patient adoption of oral therapies and growing investment in personalized treatment. Digital health platforms support home care and remote monitoring. Specialized treatment centers offer advanced pulmonary care across the region. Continued focus on innovation strengthens North America’s leadership position.
Europe
The Europe Progressive Pulmonary Fibrosis (PPF) Treatment Market size was valued at USD 638.40 million in 2018 to USD 819.68 million in 2024 and is anticipated to reach USD 1,401.00 million by 2032, at a CAGR of 7.0% during the forecast period. Europe accounts for 21.78% market share in 2024, supported by strong regulatory frameworks and structured public healthcare systems. Countries such as Germany, France, and the UK lead in research and therapy access. It benefits from EU-level funding for rare diseases and innovation hubs. Specialist clinics and university hospitals offer multidisciplinary care models. National registries help track disease prevalence and treatment effectiveness. Biosimilars are gaining ground in cost-sensitive markets. Physicians widely adopt guidelines from the European Respiratory Society. Ongoing collaboration between research bodies and biotech firms supports drug innovation.
Asia Pacific
The Asia Pacific Progressive Pulmonary Fibrosis (PPF) Treatment Market size was valued at USD 695.80 million in 2018 to USD 976.16 million in 2024 and is anticipated to reach USD 1,965.16 million by 2032, at a CAGR of 9.2% during the forecast period. Asia Pacific contributes 25.93% of the market share in 2024, driven by a large aging population and rising disease prevalence. Japan, China, and South Korea lead in market adoption. Governments invest in expanding respiratory care infrastructure. It benefits from faster urban diagnosis and rising healthcare spending. Pharmaceutical companies are launching region-specific trials and local manufacturing units. Awareness programs target early detection and treatment adherence. Academic centers in Japan and Australia focus on fibrosis research. The region is emerging as a key hub for future growth.
Latin America
The Latin America Progressive Pulmonary Fibrosis (PPF) Treatment Market size was valued at USD 156.80 million in 2018 to USD 208.48 million in 2024 and is anticipated to reach USD 349.78 million by 2032, at a CAGR of 6.7% during the forecast period. Latin America holds 5.53% of the 2024 market, with Brazil and Mexico leading demand. Limited access to specialists delays diagnosis across rural areas. Hospitals in urban centers offer advanced therapies and diagnostics. The region sees slow but growing awareness of fibrotic lung diseases. It faces challenges in drug affordability and insurance coverage. Partnerships between public and private sectors help expand therapy reach. Multinational companies are increasing investments through local distributors. Latin America presents opportunity through patient education and care accessibility.
Middle East
The Middle East Progressive Pulmonary Fibrosis (PPF) Treatment Market size was valued at USD 66.08 million in 2018 to USD 79.77 million in 2024 and is anticipated to reach USD 121.74 million by 2032, at a CAGR of 5.5% during the forecast period. The Middle East accounts for 2.12% market share in 2024, led by the Gulf Cooperation Council countries. Wealthier nations such as the UAE and Saudi Arabia invest in specialized respiratory care centers. National health strategies now include rare and chronic pulmonary diseases. It experiences rising diagnosis rates through awareness initiatives and screening programs. Oral antifibrotic therapies are available in major private hospitals. Public reimbursement remains inconsistent across countries. Global drug manufacturers partner with local agents for supply. Continued regulatory improvements may increase market visibility.
Africa
The Africa Progressive Pulmonary Fibrosis (PPF) Treatment Market size was valued at USD 50.12 million in 2018 to USD 92.98 million in 2024 and is anticipated to reach USD 142.81 million by 2032, at a CAGR of 5.0% during the forecast period. Africa represents 2.47% market share in 2024, with growth concentrated in South Africa, Egypt, and Nigeria. Low awareness and limited access to diagnostics hinder early treatment. Hospitals in capital cities handle most PPF cases. The region lacks consistent access to antifibrotic medications. Health ministries prioritize infectious diseases over rare lung conditions. It sees some growth in specialty care through public-private programs. NGOs and aid agencies support training and supply efforts. Infrastructure development remains key to long-term market potential.
Key Player Analysis:
- Boehringer Ingelheim
- Hoffmann-La Roche Ltd.
- Novartis AG
- Bayer AG
- Galapagos NV
Competitive Analysis:
The Progressive Pulmonary Fibrosis (PPF) Treatment Market is highly consolidated, with a few major players dominating global revenue. Key companies include Boehringer Ingelheim, Roche, AstraZeneca, and Bristol-Myers Squibb, each focusing on antifibrotic and immunomodulatory therapies. It sees continuous R&D investment aimed at expanding treatment indications and improving efficacy. New entrants and biotech firms are exploring novel drug classes and delivery platforms. Companies actively pursue regulatory approvals, orphan drug designations, and strategic partnerships to strengthen their pipeline. Patent protection on leading drugs shapes pricing and competitive positioning. Firms target both hospital and outpatient care channels through distribution alliances. The market’s competitive intensity grows as late-stage candidates near approval, expanding therapy options.
Recent Developments:
- In December 2025, Boehringer Ingelheim announced FDA approval for JASCAYD® (nerandomilast) tablets as a new treatment for adults with progressive pulmonary fibrosis.
Report Coverage:
The research report offers an in-depth analysis based on Treatment Type, Route of Administration and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for antifibrotic therapies will remain high as more patients receive early diagnosis through screening efforts.
- Oral route of administration is expected to dominate due to better adherence and patient comfort in long-term use.
- Asia Pacific is likely to gain higher market share driven by improving healthcare access and rising disease burden.
- Growth in personalized medicine will push demand for biomarker-guided treatments and companion diagnostics.
- Partnerships between biotech firms and research institutions will expand new drug pipelines and clinical innovation.
- Digital health tools will support long-term monitoring, adherence, and symptom tracking for outpatient care.
- Home care segment will grow steadily, aided by telehealth adoption and portable respiratory management systems.
- Regulatory bodies may speed up orphan drug designations, improving market entry for novel therapies.
- Market competition will intensify as biosimilars and combination therapies expand the treatment landscape.
- Investment in specialty clinics and fibrosis research centers will shape infrastructure and care delivery models.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Progressive Pulmonary Fibrosis (PPF) Treatment market?
At what Compound Annual Growth Rate is the Progressive Pulmonary Fibrosis (PPF) Treatment Market projected to grow between 2024 and 2032?
Which Progressive Pulmonary Fibrosis (PPF) Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Progressive Pulmonary Fibrosis (PPF) Treatment Market?
Who are the leading companies in the Progressive Pulmonary Fibrosis (PPF) Treatment Market?
Which region commanded the largest share of the Progressive Pulmonary Fibrosis (PPF) Treatment Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Progressive Pulmonary Fibrosis (PPF) Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Progressive Pulmonary Fibrosis (PPF) Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,763.93 million → 2032: USD 6,875.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Progressive Pulmonary Fibrosis (PPF) Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Progressive Pulmonary Fibrosis (PPF) Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Progressive Pulmonary Fibrosis (PPF) Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Progressive Pulmonary Fibrosis (PPF) Treatment Market Drivers
- 3.3 Progressive Pulmonary Fibrosis (PPF) Treatment Market Restraints & Challenges
- 3.4 Progressive Pulmonary Fibrosis (PPF) Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Progressive Pulmonary Fibrosis (PPF) Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Progressive Pulmonary Fibrosis (PPF) Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Progressive Pulmonary Fibrosis (PPF) Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Progressive Pulmonary Fibrosis (PPF) Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Progressive Pulmonary Fibrosis (PPF) Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Progressive Pulmonary Fibrosis (PPF) Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Progressive Pulmonary Fibrosis (PPF) Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Progressive Pulmonary Fibrosis (PPF) Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Progressive Pulmonary Fibrosis (PPF) Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Progressive Pulmonary Fibrosis (PPF) Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Progressive Pulmonary Fibrosis (PPF) Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Progressive Pulmonary Fibrosis (PPF) Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Progressive Pulmonary Fibrosis (PPF) Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Progressive Pulmonary Fibrosis (PPF) Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Progressive Pulmonary Fibrosis (PPF) Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Progressive Pulmonary Fibrosis (PPF) Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Progressive Pulmonary Fibrosis (PPF) Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Progressive Pulmonary Fibrosis (PPF) Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Progressive Pulmonary Fibrosis (PPF) Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
