
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
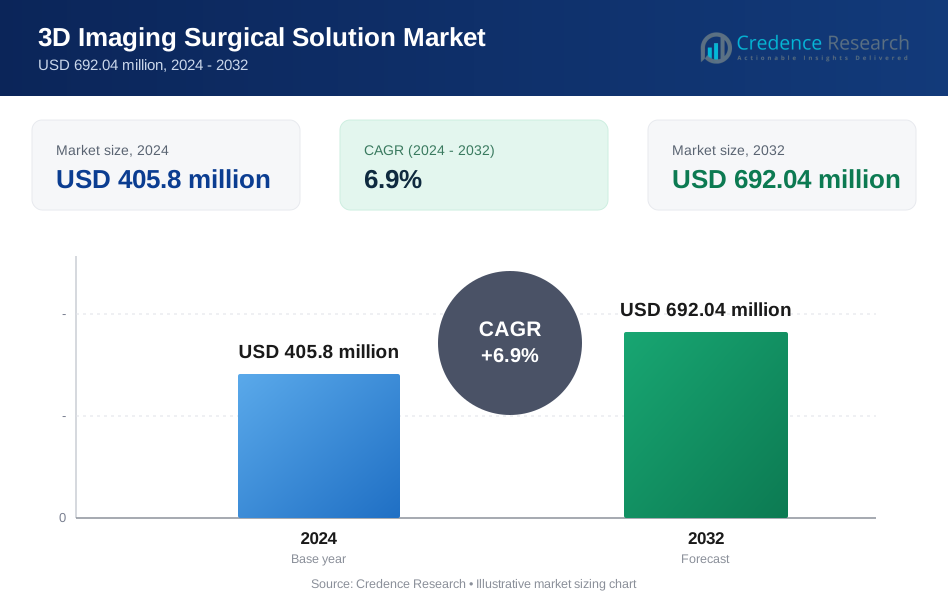
| 3D Imaging Surgical Solution Market Size 2024 | USD 405.8 million |
| 3D Imaging Surgical Solution Market, CAGR | 6.9% |
| 3D Imaging Surgical Solution Market Size 2032 | USD 692.04 million |
Market Overview
The 3D Imaging Surgical Solution Market is projected to grow from USD 405.8 million in 2024 to USD 692.04 million by 2032, with a compound annual growth rate (CAGR) of 6.9% during the forecast period.
The 3D imaging surgical solution market is driven by advancements in medical imaging technology, increasing demand for minimally invasive surgeries, and the rising prevalence of chronic diseases requiring precise surgical interventions. The integration of artificial intelligence (AI) and machine learning into 3D imaging systems enhances diagnostic accuracy and surgical planning, further propelling market growth. Surgeons benefit from improved visualization of anatomical structures, enabling better outcomes and reduced procedural risks. Growing adoption of augmented reality (AR) and virtual reality (VR) technologies in surgical training and real-time guidance adds momentum to market expansion. Additionally, the rising geriatric population and associated healthcare needs create significant demand for advanced imaging solutions. Key trends include the development of portable and cost-effective 3D imaging devices and increased investment in research and development to enhance system efficiency. These factors collectively drive the adoption of 3D imaging surgical solutions across diverse medical disciplines, ensuring sustained market growth over the forecast period.
The 3D imaging surgical solution market demonstrates significant geographical variations, with North America leading due to advanced healthcare infrastructure, high adoption of cutting-edge technologies, and strong investments in research and development. Asia-Pacific is emerging as the fastest-growing region, driven by increasing healthcare expenditure, medical tourism, and rising demand for minimally invasive surgeries in countries like China, India, and Japan. Key players shaping the global market include GE Healthcare, Philips Healthcare, Agilent Technologies, Olympus Medical System, 3D Systems Inc., Siemens Healthineers, Fujifilm Holdings Corporation, Lockheed Martin, Panasonic, and Able Software. These companies focus on technological innovations, strategic partnerships, and expanding their global presence to capture emerging opportunities. Their continuous advancements in AI-driven imaging systems and cost-effective solutions are pivotal in addressing the diverse needs of healthcare facilities worldwide.
Market Drivers
Advancements in Medical Imaging Technology
Technological advancements in medical imaging have significantly driven the growth of the 3D imaging surgical solution market. Innovations such as high-resolution imaging, integration of AI, and machine learning algorithms enhance diagnostic precision and surgical planning. For instance, a report by the Competition Commission of India highlights that the integration of AI in imaging technologies has significantly reduced diagnostic errors. These advancements enable healthcare professionals to gain detailed insights into anatomical structures, improving surgical accuracy and reducing the risk of complications. The continuous evolution of imaging technologies ensures better outcomes and positions 3D imaging solutions as indispensable tools in modern surgical practices.
Growing Preference for Minimally Invasive Surgeries
The increasing demand for minimally invasive surgical procedures is a pivotal driver for the 3D imaging surgical solution market. These procedures require precise imaging to navigate complex anatomical structures effectively. For example, a survey conducted by the World Journal of Emergency Surgery found that minimally invasive techniques are increasingly being adopted in emergency surgeries, with a significant portion of surgeons reporting high confidence in these techniques. 3D imaging solutions provide enhanced depth perception and spatial understanding, which are crucial for minimally invasive techniques. As patients and healthcare providers prioritize reduced recovery times, lower risks, and minimal scarring, the adoption of 3D imaging solutions continues to grow across various surgical specialties, including orthopedics, neurosurgery, and cardiology.
Integration of Augmented and Virtual Reality
The integration of augmented reality (AR) and virtual reality (VR) in 3D imaging surgical solutions is transforming the healthcare landscape. These technologies enable real-time visualization and simulation, offering surgeons enhanced precision during complex procedures. For instance, a report by the International Journal of Scientific and Research Publications discusses how AR technology is being used to provide visual overlays of medical images, improving diagnostic accuracy and surgical outcomes. AR and VR applications are increasingly used in surgical training, pre-operative planning, and intra-operative guidance, improving overall surgical outcomes. The growing adoption of these immersive technologies underscores their value in improving operational efficiency and patient safety, thereby driving market growth.
Increasing Healthcare Expenditure and Aging Population
Rising healthcare expenditure and the growing geriatric population are key contributors to the market's expansion. Older adults are more likely to require surgical interventions, creating a consistent demand for advanced imaging technologies. For instance, the Longitudinal Ageing Study in India (LASI), 59% of the elderly sought outpatient services within the past year, with a significant portion opting for private healthcare providers. Governments and healthcare institutions are investing in modernizing surgical infrastructure, further boosting the adoption of 3D imaging solutions. These investments, combined with the healthcare sector's focus on innovation, continue to propel the market forward, ensuring sustained growth over the forecast period.
Market Trends
Integration of Artificial Intelligence and Machine Learning
The integration of artificial intelligence (AI) and machine learning (ML) technologies into 3D imaging surgical solutions is a notable trend reshaping the market. AI-powered systems enhance imaging precision by identifying intricate anatomical details and predicting potential complications during surgical planning. For instance, a report by the National Institutes of Health (NIH) highlights that AI-assisted surgeries have been shown to significantly improve patient outcomes by reducing diagnostic errors and enhancing surgical precision. These capabilities improve diagnostic accuracy and surgical outcomes while reducing errors. Machine learning algorithms are also being employed to optimize image processing speeds and automate repetitive tasks, making surgical procedures more efficient.
Growing Adoption of Augmented Reality (AR) and Virtual Reality (VR)
Augmented reality (AR) and virtual reality (VR) are becoming increasingly prominent in the 3D imaging surgical solution market. These technologies allow surgeons to visualize and interact with 3D models of patient anatomy in real time. For example, a report by the U.S. Department of Health and Human Services (HHS) discusses how AR and VR technologies are extensively used in medical training, with institutions like Harvard Medical School developing VR content for emergency care training. AR overlays critical information during surgeries, enabling precision, while VR is extensively used for simulation-based surgical training and pre-operative planning. The immersive experience provided by AR and VR enhances decision-making and procedural accuracy, driving their adoption across medical institutions globally.
Development of Portable and Cost-Effective Solutions
Manufacturers are focusing on the development of portable and cost-effective 3D imaging surgical solutions to expand market accessibility. Compact systems equipped with advanced imaging capabilities are gaining traction in ambulatory surgical centers and smaller healthcare facilities. For instance, a report by the Indian Ministry of Health and Family Welfare highlights that regulatory clearances for compact surgical imaging solutions have been granted across the United States, Europe, and Asia, facilitating broader adoption. These solutions cater to the growing demand for affordable yet sophisticated imaging technologies in emerging markets, ensuring broader adoption and addressing budgetary constraints faced by smaller healthcare providers.
Increasing Focus on Personalized Medicine
The trend toward personalized medicine is fostering innovations in 3D imaging surgical solutions. Customized imaging tailored to individual patient needs enhances the accuracy of surgical procedures. For example, a report by the Journal of Clinical Imaging Science discusses how 3D printing technology is being used to create patient-specific implants and surgical guides, significantly improving surgical outcomes. Surgeons can create patient-specific surgical plans using 3D imaging, reducing risks and improving outcomes. This trend aligns with the broader healthcare shift toward individualized treatment, making 3D imaging solutions integral to modern surgical practices and fueling their continued growth.
Market Challenges Analysis
High Costs of Implementation and Maintenance
One of the significant challenges facing the 3D imaging surgical solution market is the high cost associated with the implementation and ongoing maintenance of these advanced systems. The initial investment required for purchasing state-of-the-art imaging equipment, combined with additional expenses for software updates, system integration, and infrastructure upgrades, poses a substantial financial burden on healthcare institutions, particularly in emerging economies and low-resource settings. Moreover, the cost of training medical professionals to operate and interpret these technologies effectively adds to the overall expenditure, creating further barriers for adoption. Smaller hospitals, clinics, and rural healthcare facilities often struggle to allocate sufficient funds for such investments, limiting their ability to adopt 3D imaging solutions. This financial constraint restricts the market's reach, slowing the adoption rate of these transformative technologies in cost-sensitive regions and hindering their potential to revolutionize surgical outcomes on a global scale.
Limited Accessibility in Emerging Markets
Limited accessibility to 3D imaging surgical solutions in developing regions represents another critical challenge for the market. The lack of adequate healthcare infrastructure, including advanced facilities, modern diagnostic tools, and skilled professionals, significantly hampers the adoption of these technologies in low- and middle-income countries. Additionally, insufficient government support, such as inadequate reimbursement policies for advanced imaging procedures, further discourages healthcare providers from investing in 3D imaging systems, even where the need is significant. This disparity creates a pronounced gap in the global adoption of 3D imaging surgical solutions, leaving many patients in underserved regions without access to cutting-edge medical advancements. Bridging this gap requires collaborative efforts from manufacturers, governments, and healthcare organizations to enhance affordability, build robust infrastructure, provide targeted training programs, and raise awareness about the benefits of 3D imaging, ultimately enabling broader access to these life-saving technologies worldwide.
Market Segmentation Analysis:
By Technology Type The 3D imaging surgical solution market is segmented by technology type into hardware, software, and services. Hardware dominates the segment, comprising advanced imaging devices and systems such as 3D scanners and cameras, which are critical for capturing detailed anatomical structures. The software segment is witnessing rapid growth due to the integration of artificial intelligence (AI) and machine learning (ML) for enhanced imaging precision and automation. Services, including maintenance and training, form an essential component, ensuring the optimal functionality and utilization of these solutions. Continuous advancements in technology and the increasing integration of AI are expected to further drive innovation across all technology segments.
By Imaging Solutions Within the imaging solutions segment, systems are categorized into intraoperative imaging, preoperative imaging, and postoperative imaging. Preoperative imaging holds the largest share, as it is essential for surgical planning and risk assessment. Intraoperative imaging is gaining traction due to its ability to provide real-time visualization during surgeries, enhancing precision and reducing complications. Postoperative imaging plays a critical role in monitoring surgical outcomes and patient recovery. The growing adoption of intraoperative imaging, driven by the increasing demand for minimally invasive procedures, is expected to propel the overall market growth. Continuous developments in imaging modalities, such as portable and high-resolution systems, further expand the application scope across these segments, ensuring robust market growth in the coming years.
Segments:
Based on Technology Type:
- Holography
- Volumetric Display
- Anaglyphy
- Stereoscopy
- Auto-stereoscopy
Based on Imaging Solutions:
- Layout and Animation
- 3D Rendering
- Image Reconstruction
- 3D Modeling
- 3D Scanning
Based on End User:
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America dominates the 3D imaging surgical solution market, holding a significant 35% of the global market share in 2024. This leadership stems from the region's advanced healthcare infrastructure and widespread adoption of cutting-edge surgical technologies. The United States, as the largest contributor within the region, benefits from a well-established network of hospitals, surgical centers, and research institutions equipped with modern imaging systems. The increasing prevalence of chronic diseases, such as cardiovascular conditions and cancer, necessitates precise surgical interventions, driving demand for advanced 3D imaging solutions. Furthermore, the region's strong emphasis on minimally invasive procedures, which rely heavily on high-resolution imaging, propels market growth. Government initiatives supporting healthcare modernization, combined with favorable reimbursement policies, create an environment conducive to technological adoption. The integration of artificial intelligence (AI) and machine learning (ML) into imaging systems has further enhanced diagnostic precision, enabling surgeons to achieve better outcomes. North America's strong focus on innovation, coupled with the presence of leading market players, ensures its continued dominance in the global 3D imaging surgical solution market.
Asia-Pacific
Asia-Pacific is emerging as the fastest-growing region in the 3D imaging surgical solution market, projected to account for 25% of the global market share by 2032. Factors driving this rapid growth include rising healthcare expenditure, increasing medical tourism, and the growing prevalence of chronic conditions in densely populated nations such as China and India. Governments across the region are actively investing in healthcare infrastructure and promoting the adoption of advanced imaging technologies to improve surgical outcomes. Local manufacturers are introducing cost-effective 3D imaging solutions, making these technologies more accessible to smaller healthcare providers. Countries like Japan and South Korea are recognized for their innovation in imaging systems and contribute significantly to regional growth. Although challenges such as inadequate infrastructure persist in some developing nations, the region's overall focus on modernizing healthcare facilities and enhancing medical accessibility positions it as a key growth hub. The adoption of portable and affordable imaging solutions tailored to meet the region's diverse healthcare needs further accelerates the market's expansion, making Asia-Pacific a vital contributor to the global 3D imaging surgical solution market.
cr_cta type="customize_now"]
Key Player Analysis
- 3D Systems Inc.
- Philips Healthcare
- Agilent Technologies
- Olympus Medical System
- Lockheed Martin
- GE Healthcare
- Able Software
- Panasonic
- Siemens Healthineers
- Fujifilm Holdings Corporation
Competitive Analysis
The 3D imaging surgical solution market is characterized by intense competition among leading players such as GE Healthcare, Philips Healthcare, Siemens Healthineers, Agilent Technologies, and Olympus Medical System. These companies leverage advanced technologies, such as AI and machine learning, to enhance imaging precision and surgical outcomes. They are focused on expanding their product portfolios through innovation and strategic acquisitions, targeting both developed and emerging markets. For instance, GE Healthcare launched the Revolution Apex CT system, which integrates AI to improve diagnostic accuracy and surgical planning. Additionally, partnerships with healthcare providers and research institutions enable them to maintain a strong presence in the market. The emphasis on developing portable and cost-effective solutions further intensifies the competitive landscape, as companies aim to cater to a wider range of healthcare facilities. With continuous investments in R&D and efforts to enhance global reach, these players significantly shape the market dynamics and drive the adoption of advanced 3D imaging solutions worldwide.
Recent Developments
- In October 2024, Ricoh USA and Insight Surgery formed a strategic partnership to provide patient-specific surgical guides for pediatric and adult orthopedic and maxillofacial surgeries across the United States.
- In September 2024, OsseoLabs, an AI-powered 3D printing medical device startup, announced expansion into the global market after establishing partnerships with over 20 hospitals in Thailand.
- In January 2024, Probo Medical acquired Alpha Source Group to enhance their diagnostic imaging solutions platform.
- In October 2024, Smith+Nephew partnered with JointVue to integrate OrthoSonic™ 3D Surgery Planning Technology with their CORI Surgical System, enabling radiation-free 3D surgical planning using ultrasound technology.
Market Concentration & Characteristics
The 3D imaging surgical solution market is moderately concentrated, with a mix of established players and emerging companies driving competition. Dominated by global leaders such as GE Healthcare, Philips Healthcare, and Siemens Healthineers, the market is characterized by significant investments in research and development, leading to rapid technological advancements. These key players maintain their competitive edge through innovation, strategic partnerships, and acquisitions, enabling them to expand their product portfolios and global reach. The market is further characterized by the increasing integration of artificial intelligence (AI) and augmented reality (AR) technologies, enhancing imaging accuracy and surgical outcomes. While developed regions like North America and Europe have high adoption rates, emerging markets in Asia-Pacific are witnessing rapid growth due to improved healthcare infrastructure and increasing demand for cost-effective solutions. This dynamic combination of technological innovation and regional growth opportunities defines the market's competitive and evolving nature.
Report Coverage
The research report offers an in-depth analysis based on Technology Type, Imaging Solutions, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The 3D imaging surgical solution market is expected to experience steady growth driven by advancements in imaging technologies.
- The integration of artificial intelligence (AI) and machine learning will enhance precision and efficiency in surgical planning and execution.
- Increasing demand for minimally invasive surgeries will continue to propel the adoption of 3D imaging systems globally.
- Portable and cost-effective imaging solutions will gain traction in emerging markets, expanding accessibility.
- Augmented reality (AR) and virtual reality (VR) applications will play a significant role in surgical training and real-time guidance.
- Rising healthcare expenditure in developing countries will support the modernization of surgical infrastructure.
- Key players are likely to focus on strategic partnerships and acquisitions to expand their global presence and technological capabilities.
- Government initiatives promoting advanced healthcare solutions will further drive market adoption.
- Innovations in imaging modalities will open new opportunities across diverse medical fields.
- The Asia-Pacific region is expected to emerge as a significant growth hub due to rapid healthcare advancements and increasing patient demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the 3D imaging surgical solution market?
What factors are driving the growth of the 3D imaging surgical solution market?
What are the key segments within the 3D imaging surgical solution market?
What are some challenges faced by the 3D imaging surgical solution market?
Who are the major players in the 3D imaging surgical solution market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 3D Imaging Surgical Solution Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global 3D Imaging Surgical Solution Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 405.8 million → 2032: USD 692.04 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 3D Imaging Surgical Solution Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. 3D Imaging Surgical Solution Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 3D Imaging Surgical Solution Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 3D Imaging Surgical Solution Market Drivers
- 3.3 3D Imaging Surgical Solution Market Restraints & Challenges
- 3.4 3D Imaging Surgical Solution Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 3D Imaging Surgical Solution Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 3D Imaging Surgical Solution Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, 3D Imaging Surgical Solution category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 3D Imaging Surgical Solution Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. 3D Imaging Surgical Solution Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the 3D Imaging Surgical Solution market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 3D Imaging Surgical Solution Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 3D Imaging Surgical Solution Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 3D Imaging Surgical Solution Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in 3D Imaging Surgical Solution (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New 3D Imaging Surgical Solution Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global 3D Imaging Surgical Solution Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America 3D Imaging Surgical Solution Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe 3D Imaging Surgical Solution Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific 3D Imaging Surgical Solution Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America 3D Imaging Surgical Solution Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East 3D Imaging Surgical Solution Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa 3D Imaging Surgical Solution Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. 3D Imaging Surgical Solution Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
