
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aerospace Data Recorder Market Size 2024 | USD 1,870 million |
| Aerospace Data Recorder Market, CAGR | 5.79% |
| Aerospace Data Recorder Market Size 2032 | USD 2,933.584 million |
Market Overview
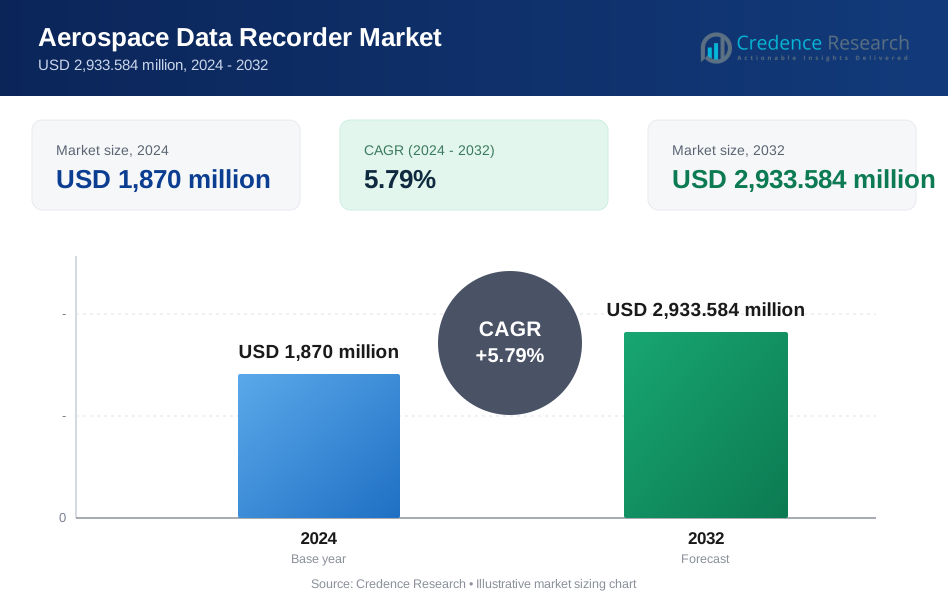
The aerospace data recorder market is projected to grow from USD 1,870 million in 2024 to USD 2,933.584 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.79%.
The aerospace data recorder market is primarily driven by the increasing demand for flight safety, stringent regulations, and advancements in aviation technology. As global air traffic grows, airlines and aviation authorities are focusing on improving safety measures, enhancing data collection, and ensuring real-time monitoring, driving the need for advanced data recording systems. The integration of innovative features like automatic data extraction, real-time communication, and advanced data analytics is a key trend reshaping the market. Moreover, rising investments in aircraft modernization programs and the growing adoption of next-generation aircraft contribute to the market's expansion. The demand for lightweight and high-performance recorders, including cockpit voice and flight data recorders (CVFDR), is also increasing due to the focus on fuel efficiency and environmental sustainability. With these drivers and trends, the aerospace data recorder market is poised for significant growth, fueled by evolving technologies and a strong emphasis on operational safety and compliance across the aviation industry.
The aerospace data recorder market exhibits strong regional growth across North America, Europe, Asia-Pacific, and the Rest of the World. North America dominates the market, driven by the presence of major companies and regulatory frameworks like the FAA. Europe follows closely, supported by robust aviation safety regulations and advancements in technology. The Asia-Pacific region is expected to experience the highest growth rate, driven by rising air traffic and military spending, particularly in China and India. Meanwhile, the Rest of the World, including the Middle East, Africa, and Latin America, is gradually expanding due to increasing infrastructure investments and air traffic. Key players, including Boeing, Airbus, GE Aviation, Rockwell Collins, and Safran, are focused on innovation and strategic partnerships to cater to these diverse regional demands and expand their market presence.
Market Insights
- The aerospace data recorder market is projected to grow from USD 1,870 million in 2024 to USD 2,933.584 million by 2032, reflecting a CAGR of 5.79%.
- Increasing demand for flight safety and stringent regulations are driving the adoption of advanced data recording systems to ensure real-time monitoring and improve safety measures.
- Technological advancements, including real-time communication, automatic data extraction, and advanced data analytics, are reshaping the market.
- The rise in global air traffic and the modernization of fleets are contributing to the demand for sophisticated aerospace data recorders.
- Lightweight, high-performance recorders, such as cockpit voice and flight data recorders (CVFDR), are gaining traction due to a focus on fuel efficiency and sustainability.
- Regional growth is strong across North America, Europe, Asia-Pacific, and the Rest of the World, with North America holding the largest market share at 35%.
- Key players like Boeing, Airbus, and GE Aviation focus on innovation and strategic partnerships to meet growing regional demands.
Market Drivers
Increasing Demand for Aviation Safety
The primary driver of the aerospace data recorder market is the increasing focus on aviation safety. As air travel continues to grow, there is a heightened emphasis on ensuring the safety of passengers and crew. Regulatory bodies, such as the FAA and EASA, mandate the installation of cockpit voice recorders (CVRs) and flight data recorders (FDRs) to monitor aircraft performance and collect critical data during flight. For instance, CVRs and FDRs developed by Honeywell Aerospace are widely used to monitor aircraft performance and collect critical data during flight, providing invaluable insights for accident investigations. These data recorders provide invaluable insights for accident investigations, leading to enhanced safety protocols and a reduction in aviation-related incidents.
Stringent Regulatory Requirements
Global aviation authorities have imposed stricter regulations regarding flight data monitoring, bolstering the demand for advanced aerospace data recorders. These regulations require airlines to adopt modern flight data monitoring systems, which can track and analyze a wide range of operational data in real-time. The growing need for compliance with evolving standards in data recording and retrieval has further accelerated the adoption of sophisticated aerospace data recorders across the industry. For instance, L3Harris Technologies has developed advanced flight data monitoring systems that comply with evolving regulatory standards, helping airlines track and analyze operational data in real-time.
Technological Advancements
Technological advancements in aerospace data recorders are playing a pivotal role in shaping the market. Innovations such as data encryption, remote data extraction, and real-time monitoring are driving the market forward. Additionally, the integration of artificial intelligence (AI) and machine learning (ML) in data analysis is enabling more accurate and faster decision-making processes. For instance, Curtiss-Wright Corporation is integrating AI and ML in their data recorders to enable more accurate and faster decision-making processes, improving both flight safety and operational efficiency. These advancements not only improve flight safety but also enhance operational efficiency, contributing to the increased adoption of next-generation aerospace data recorders.
Growth in Global Air Traffic
The steady growth in global air traffic is a significant driver for the aerospace data recorder market. As the number of flights increases, airlines and aviation operators are increasingly investing in modernized fleets equipped with advanced data recording systems. The need to manage and analyze vast amounts of data generated by aircraft systems is driving the demand for high-performance aerospace data recorders. For instance, modernized fleets equipped with data recorders from Teledyne Technologies help airlines manage and analyze vast amounts of data generated by aircraft systems, supporting the global effort to maintain flight safety and operational efficiency. As more aircraft enter service, the market for data recording devices is expected to expand, supporting the global effort to maintain flight safety and operational efficiency.
Market Trends
Integration of Real-Time Data Monitoring
A key trend in the aerospace data recorder market is the integration of real-time data monitoring systems. These advanced recorders enable continuous tracking of flight parameters and provide immediate feedback to ground personnel, enhancing situational awareness and operational decision-making. Real-time monitoring helps detect potential issues early, allowing for prompt corrective actions to ensure flight safety. For instance, real-time data monitoring systems developed by Honeywell Aerospace enable continuous tracking of flight parameters and provide immediate feedback to ground personnel, enhancing situational awareness and operational decision-making. This trend is gaining traction due to the increased focus on proactive maintenance and data-driven aviation management strategies.
Adoption of Advanced Flight Data Analysis
The adoption of advanced flight data analysis tools is another significant trend in the aerospace data recorder market. With the rise of artificial intelligence (AI) and machine learning (ML) technologies, data recorders are now capable of providing deeper insights into aircraft performance. These systems can analyze vast amounts of data to predict maintenance needs, optimize fuel consumption, and improve overall flight efficiency. For instance, advanced flight data analysis tools developed by GE Aviation leverage AI and ML technologies to provide deeper insights into aircraft performance, predicting maintenance needs and optimizing fuel consumption. Airlines are leveraging these tools to enhance operational effectiveness and reduce costs, contributing to the growing demand for sophisticated data recording solutions.
Miniaturization and Lightweight Design
Another prominent trend is the miniaturization and lightweight design of aerospace data recorders. As aircraft manufacturers strive for improved fuel efficiency and reduced weight, the demand for compact and lightweight recording devices has increased. These advancements allow for the integration of more data collection systems without significantly impacting aircraft performance. For instance, Teledyne Technologies has developed miniaturized and lightweight data recorders that integrate seamlessly with other data collection systems, enhancing fuel efficiency and overall aircraft performance. The trend towards smaller, more efficient devices is further driven by the need for cost-effective and easy-to-install solutions, benefiting both commercial and military aviation sectors.
Expansion of Data Recorder Applications
The expansion of aerospace data recorder applications is also driving market growth. Beyond traditional cockpit voice and flight data recording, modern recorders are being used for a wider range of functions, including tracking cabin conditions, engine performance, and passenger data. For instance, modern data recorders developed by L3Harris Technologies are used to track cabin conditions, engine performance, and passenger data, enhancing safety, compliance, and operational optimization. This broader scope of applications enhances the overall utility of data recorders, making them integral to not only safety and compliance but also operational optimization and customer experience management.
Market Challenges Analysis
Regulatory and Compliance Challenges
A major challenge in the aerospace data recorder market is ensuring compliance with constantly evolving global regulations and industry standards. Aviation authorities such as the FAA, EASA, and ICAO frequently update their requirements for flight data and cockpit voice recorders, which compel airlines and aircraft manufacturers to implement new technologies or modify existing systems. This dynamic regulatory environment often places significant pressure on the aerospace industry to keep pace with these changes, leading to costly investments in the certification and integration of upgraded data recording systems. Additionally, regulatory requirements vary between different regions and countries, creating complexities for international operators who must adhere to multiple standards. The certification process can be time-consuming and costly, especially when new features or technologies are required to meet evolving guidelines. These challenges often lead to delays in product deployment and increased costs for both manufacturers and end users, ultimately affecting operational efficiency and profitability in the aerospace sector.
Data Security and Privacy Concerns
Data security and privacy concerns present another significant challenge in the aerospace data recorder market. As aircraft data recorders generate and store large amounts of sensitive information—ranging from flight performance metrics to crew interactions and passenger data—ensuring the protection of this information is critical. The increasing reliance on cloud-based storage and data transfer systems introduces potential vulnerabilities, making the aerospace sector an attractive target for cyberattacks. The risk of unauthorized access or data breaches can compromise both operational security and passenger privacy. Additionally, airlines and operators must navigate complex data privacy regulations, such as the General Data Protection Regulation (GDPR) in Europe, which sets strict standards for the processing and handling of personal information. Ensuring compliance with these regulations while maintaining the integrity and confidentiality of critical flight data presents an ongoing challenge, requiring continuous investment in cybersecurity technologies and data encryption solutions.
Market Opportunities
The aerospace data recorder market presents significant opportunities driven by the increasing demand for advanced flight data monitoring systems and the growing emphasis on flight safety. As global air traffic continues to rise, there is an urgent need for innovative solutions that can efficiently capture and analyze large volumes of flight data. This presents opportunities for manufacturers to develop next-generation data recorders with enhanced capabilities, including real-time data transmission, predictive analytics, and remote data extraction. Airlines, aircraft manufacturers, and aviation regulators are increasingly seeking solutions that can provide better insights into aircraft performance, ensure compliance with evolving safety standards, and help mitigate risks. With the aviation industry striving to improve operational efficiency and reduce maintenance costs, the demand for sophisticated data recording systems, capable of delivering actionable insights, is set to increase significantly.
Additionally, the shift toward the integration of artificial intelligence (AI) and machine learning (ML) in data analysis offers substantial opportunities for growth. As these technologies become more advanced, they can enhance the capabilities of aerospace data recorders by enabling predictive maintenance, optimizing fuel usage, and improving overall flight operations. The development of lightweight, compact, and cost-effective data recorders also opens doors for new market segments, such as regional airlines and smaller aircraft operators who require high-performance solutions at competitive price points. Furthermore, the expansion of aerospace data recorder applications beyond traditional voice and flight data recording—such as monitoring engine health, cabin conditions, and real-time flight optimization—will unlock new opportunities in the market. These trends position the aerospace data recorder market for significant expansion in the coming years, as stakeholders recognize the value of data-driven decision-making in aviation safety and operations.
Market Segmentation Analysis:
By Type
The aerospace data recorder market is segmented by type into cockpit voice recorders (CVRs), flight data recorders (FDRs), and combined voice and flight data recorders (CVFDRs). CVRs and FDRs remain the most commonly used, while CVFDRs are gaining popularity due to their ability to consolidate multiple recording functions into a single unit, enhancing operational efficiency.
By End Use
The market is segmented by end use into commercial aviation, military aviation, and others. Commercial aviation dominates the market, driven by the rising global air traffic and strict regulatory requirements. Military aviation also contributes significantly, as advanced data recorders are integral for mission-critical operations and ensuring safety in defense aircraft.
By Technology
In terms of technology, the market is categorized into traditional and advanced data recording systems. Advanced systems, including real-time data transmission, predictive analytics, and cloud-based storage, are witnessing robust growth due to the rising demand for enhanced operational insights and proactive maintenance capabilities, offering superior data analysis and decision-making.
Segments:
Based on Type
- Cockpit Voice Recorder
- Flight Data Recorder
- Combined Flight Recorder
Based on End Use
- Commercial Aviation
- Military Aviation
- General Aviation
Based on Technology
- Solid-State Recorders
- Magnetic Tape Recorders
- Hybrid Recorders
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America is expected to hold the largest market share of the aerospace data recorder market in 2024, accounting for 35%. The region’s dominance is driven by the strong presence of leading aircraft manufacturers, such as Boeing, and aviation authorities, including the FAA, which enforce stringent regulations on flight data recording systems. Additionally, the growing emphasis on safety and security in the aviation sector, combined with substantial investments in advanced technologies, fuels market growth. The increasing adoption of next-generation aircraft by both commercial and military sectors in the U.S. and Canada further supports the demand for advanced aerospace data recorders. Furthermore, the rapid integration of artificial intelligence and machine learning in data analysis provides a competitive edge to North American companies, ensuring continuous growth in the region.
Europe
Europe is another prominent market for aerospace data recorders, holding a market share of 28% in 2024. The region’s strong regulatory framework, led by EASA, plays a critical role in shaping the demand for flight data and cockpit voice recorders. The growing trend toward aircraft modernization and the expansion of the European aviation network, especially in Eastern Europe, are key contributors to market growth. European countries, particularly the UK, France, and Germany, are also investing heavily in the development of advanced aerospace technologies, including real-time data transmission and predictive analytics, which are boosting the demand for advanced data recorders. Additionally, the rising adoption of electric aircraft and unmanned aerial vehicles (UAVs) in Europe presents new opportunities for the aerospace data recorder market.
Asia-Pacific
The Asia-Pacific region is anticipated to witness the highest growth rate in the aerospace data recorder market, with a projected market share of 22% in 2024. Rapid expansion in air travel, particularly in China, India, and Southeast Asia, is driving the demand for new aircraft, which in turn boosts the need for modern data recording systems. The region’s growing focus on enhancing aviation safety standards and infrastructure development further fuels market expansion. Moreover, the increasing military spending by countries such as Japan, India, and South Korea contributes to the demand for advanced data recorders in defense applications. As the Asia-Pacific region continues to modernize its fleets and expand aviation capabilities, the aerospace data recorder market is set for significant growth.
Rest of the World
The Rest of the World, comprising regions such as the Middle East, Africa, and Latin America, accounts for a smaller market share of 15% in 2024. However, this market is steadily growing due to increased investments in infrastructure and the rising demand for aviation safety solutions. The Middle East, driven by airlines like Emirates and Qatar Airways, is witnessing significant fleet expansion, which contributes to the demand for aerospace data recorders. In Africa and Latin America, improving aviation safety standards and increasing air traffic are also boosting the market for data recording systems. As these regions continue to enhance their aviation industries, the aerospace data recorder market will likely experience gradual growth in the coming years.
Key Player Analysis
- Airbus
- Teledyne Technologies
- United Technologies Corporation
- Boeing
- Safran
- GE Aviation
- Rockwell Collins
- CurtissWright Corporation
- Northrop Grumman
- Ametek
- Aviation Sales
Competitive Analysis
The aerospace data recorder market is highly competitive, with leading players such as Boeing, Airbus, GE Aviation, Rockwell Collins, Safran, Ametek, Curtiss-Wright Corporation, Northrop Grumman, Teledyne Technologies, United Technologies Corporation, and Aviation Sales driving innovation and growth. These companies are continually focusing on technological advancements to stay ahead in the market, with developments in real-time data transmission, predictive analytics, and advanced data encryption being key areas of innovation. Additionally, they are investing heavily in R&D to integrate artificial intelligence (AI) and machine learning (ML) capabilities into their systems, which enhance data analysis and decision-making processes. For instance, Curtiss-Wright Corporation is integrating AI and ML capabilities into their data recording systems to enhance data analysis and decision-making processes. Strategic partnerships and collaborations also play a significant role in expanding their market share, particularly in emerging markets like Asia-Pacific and the Middle East. Moreover, as regulatory requirements around flight data recorders become more stringent, these companies are increasingly offering solutions that comply with evolving industry standards, helping to maintain their competitive edge in the global aerospace data recorder market.
Recent Developments
- In November 2023, HENSOLDT unveiled a new cockpit voice and flight data recorder at the European Rotors 2023 conference in Madrid. This innovative CVFDR integrates advanced technologies, including the ability to load software on the ground and extract data without powering the aircraft’s electrical systems.
- In May 2024, Saudia awarded Airbus a contract to deliver 54 A321neo aircraft, while its subsidiary Flyadeal is set to acquire 12 A320neo and 39 A321neo planes for USD 19 billion. Deliveries are expected to begin in 2026 and will conclude in 2032.
- In July 2024, the Federal Aviation Administration and Canada West Aviation Company appointed Sentry cockpit voice recorders for several aircraft amendments.
- In December 2023, the United Kingdom, in partnership with Japan and Italy, initiated the future combat air program to develop a next-generation stealth fighter. This new fighter is expected to feature supersonic capabilities and be equipped with cutting-edge technologies.
Market Concentration & Characteristics
The aerospace data recorder market exhibits a moderate level of market concentration, with several leading players dominating the industry. Major companies, including Boeing, Airbus, GE Aviation, and Rockwell Collins, hold significant market shares, driving innovation and setting industry standards. These companies leverage advanced technologies such as real-time data transmission, AI-driven analytics, and predictive maintenance to maintain competitive advantage. However, the market also features a number of smaller players offering niche solutions and specialized products, which helps drive competition and encourages continuous technological advancements. The market is characterized by high regulatory compliance, as strict safety standards and certifications are required for data recording systems. This ensures the consistent demand for high-quality and reliable data recorders across commercial, military, and private aviation sectors. Additionally, manufacturers are increasingly focusing on lightweight, cost-effective solutions to cater to the diverse needs of the global aviation industry.
Report Coverage
The research report offers an in-depth analysis based on Type, End-Use, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing adoption of advanced flight data monitoring systems is expected to drive market growth, enhancing safety protocols and operational efficiency.
- Increasing global air traffic will drive higher demand for advanced flight data monitoring systems.
- Airlines and aviation authorities will place more emphasis on real-time monitoring and enhanced safety features.
- Technological innovations, such as AI, machine learning, and predictive analytics, will play a key role in shaping future product offerings.
- The adoption of lightweight and eco-friendly data recording systems will increase due to sustainability concerns.
- Growing investments in military aviation will drive demand for advanced data recorders in defense applications.
- New regulatory requirements and standards will push for more sophisticated and compliant data recording solutions.
- Manufacturers will focus on offering integrated solutions that combine multiple recording functions in a single unit.
- Asia-Pacific will experience the highest growth, driven by the rising number of aircraft and modernization in emerging economies.
- The market will see more partnerships and collaborations as key players strive to strengthen their regional presence and technological capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the aerospace data recorder market?
What are the key segments within the aerospace data recorder market?
What are some challenges faced by the aerospace data recorder market?
Who are the major players in the aerospace data recorder market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aerospace Data Recorder Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aerospace Data Recorder Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,870 million → 2032: USD 2,933.584 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aerospace Data Recorder Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aerospace Data Recorder Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aerospace Data Recorder Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aerospace Data Recorder Market Drivers
- 3.3 Aerospace Data Recorder Market Restraints & Challenges
- 3.4 Aerospace Data Recorder Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aerospace Data Recorder Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aerospace Data Recorder Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aerospace Data Recorder category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aerospace Data Recorder Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aerospace Data Recorder Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aerospace Data Recorder market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aerospace Data Recorder Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aerospace Data Recorder Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aerospace Data Recorder Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aerospace Data Recorder (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aerospace Data Recorder Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aerospace Data Recorder Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aerospace Data Recorder Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aerospace Data Recorder Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aerospace Data Recorder Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aerospace Data Recorder Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aerospace Data Recorder Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aerospace Data Recorder Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aerospace Data Recorder Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
