
Military Helmet Market Overview:
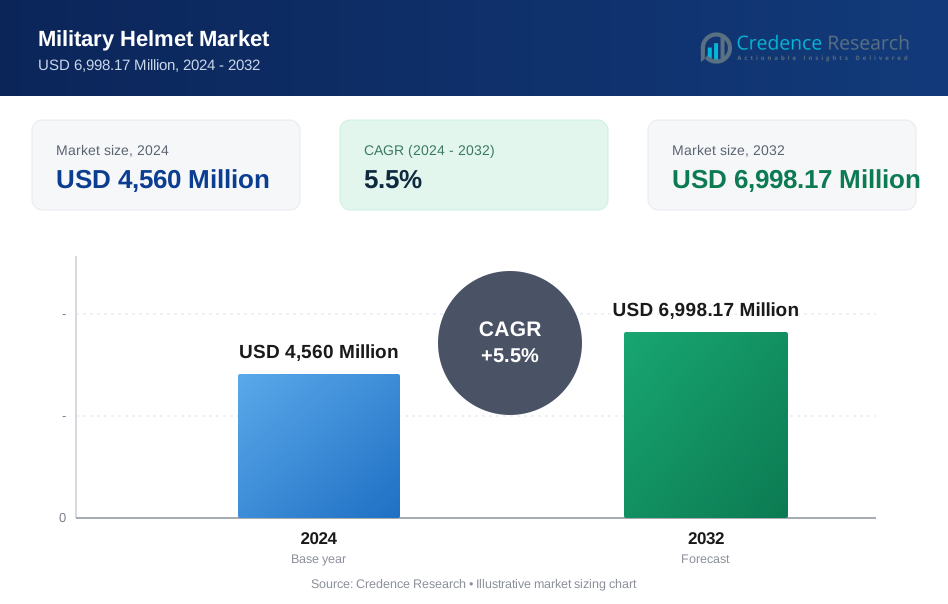
Military Helmet market size was valued USD 4,560 Million in 2024 and is anticipated to reach USD 6,998.17 Million by 2032, at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Military Helmet Market Size 2024 | USD 4,560 million |
| Military Helmet Market , CAGR | 5.5% |
| Military Helmet Market Size 2032 | USD 6,998.17 million |
Military Helmet Market Insights
- Market overview highlights growing adoption of lightweight and modular integrated communication helmets, with the Modular Integrated Communication Helmets segment leading the type category, accounting for a 42.8% share due to rising demand for communication-enabled and night-vision-compatible systems.
- Market drivers include accelerated soldier modernization programs, increasing focus on head protection against ballistic threats, and technological advancements in aramid fibers and UHMWPE materials that enhance durability while reducing weight.
- Competitive analysis shows strong participation from key players such as BAE Systems, Gentex Corporation, Revision Military, Safariland Group, MKU Limited, and ArmorSource, all investing in product innovation, ergonomic design, and integration of electronics to secure defense procurement contracts.
- Regional analysis indicates North America leads the market with 34.7% share, followed by Europe at 27.5%, while Asia-Pacific holds 24.1% and remains the fastest-growing region due to expanding defense budgets and troop modernization initiatives.

Military Helmet Market Segmentation Analysis:
By Type
In the Military Helmet market, the Modular Integrated Communication Helmets (MICH) segment dominated the type category with a 42.8% market share in 2024, driven by rising adoption across armed forces for integrated communication capability, situational awareness, and compatibility with night-vision devices and tactical accessories. Lightweight helmets accounted for a growing share as defense agencies emphasized soldier mobility and fatigue reduction during extended field operations. The Enhanced Combat segment advanced steadily as armies upgraded legacy headgear systems, supported by investments in modernization programs and survivability enhancement initiatives across major defense markets.
- For instance, the U.S. Army’s Integrated Head Protection System (IHPS), produced under Gentex and Ceradyne contracts, integrates communication mounts and night-vision interfaces to support infantry operations.
By Material
The Advanced Aramid Fiber segment led the material category with a 39.6% market share in 2024, supported by superior ballistic resistance, thermal stability, and durability compared with conventional materials. Defense forces increasingly preferred these helmets for high-risk combat missions, strengthening their deployment across infantry and special operations units. Original Aramid Fiber Kevlar maintained relevance within existing helmet inventories, while UHMWPE (Ultra High Molecular Weight Polyethylene) Fiber gained momentum due to its lightweight profile and strong strength-to-weight characteristics, aligning with initiatives to reduce overall soldier load without compromising ballistic protection.
- For instance, DuPont’s Kevlar KM2 and KM2 Plus fibers are used in U.S. Army and Marine Corps ballistic helmets to improve fragmentation resistance and durability in combat conditions.
By Weight
The Up to 3 Lbs segment emerged as the leading weight category with a 55.3% market share in 2024, reflecting a significant industry transition toward lightweight helmet platforms designed to minimize fatigue and enhance operational endurance during prolonged missions. Demand accelerated as global armies prioritized ergonomics and mobility, particularly in dismounted and rapid-response combat scenarios. The Over 3 Lbs segment continued to support missions requiring higher ballistic layering and modular accessories, although its growth remained moderate as procurement strategies increasingly favored lighter next-generation protective headgear solutions.
Key Growth Drivers
Rising Defense Modernization Programs
Global defense modernization initiatives are a major growth driver in the Military Helmet market, as armed forces invest in next-generation soldier protection systems to enhance survivability and battlefield readiness. Governments are prioritizing upgrades from legacy steel and basic Kevlar helmets to advanced ballistic helmets with improved durability, multi-impact resistance, and compatibility with tactical accessories. Modern warfare environments, including asymmetric and urban conflicts, demand helmets that integrate communication modules, cameras, and night-vision systems, fueling procurement of Modular Integrated Communication Helmets and lightweight ballistic variants. Additionally, military alliances and joint defense programs are accelerating technology standardization and large-scale procurement cycles. The expansion of special operations units and rapid-response forces across North America, Europe, and Asia-Pacific further strengthens demand for high-performance helmet platforms that support mission flexibility, enhancing long-term market growth.
- For instance, the British Army’s Virtus Helmet system, introduced under the Virtus Soldier System program, offers improved blunt-impact protection and compatibility with weapon sights and night-vision devices.
Increasing Focus on Soldier Safety and Survivability
Heightened emphasis on troop protection and injury prevention is driving substantial investment in advanced military helmets that offer superior ballistic protection and impact absorption. Rising awareness of traumatic brain injuries, blast-related head trauma, and operational fatigue has encouraged defense forces to adopt helmets with enhanced ergonomic design, padding systems, and load-balancing structures. The integration of energy-absorbing liners, modular visors, and neck stabilization components supports improved comfort and mission endurance. Additionally, militaries are prioritizing research into blast mitigation technologies and next-generation composite materials to reduce weight while strengthening protective capabilities. Programs supporting veteran health data and battlefield injury analytics are reinforcing helmet performance standards and procurement priorities. This safety-driven shift is significantly influencing helmet innovation, leading to wider adoption of lightweight, multi-functional combat helmets across infantry, reconnaissance, and tactical support divisions.
- For instance, the U.S. Marine Corps has updated its helmet pad specifications based on research from the Joint Trauma Analysis and Prevention of Injury in Combat (JTAPIC) program to better address blast-related head injuries.
Technological Advancements in Materials and Helmet Integration
Rapid advancements in material science and helmet integration technologies are propelling market growth, as manufacturers adopt advanced aramid fibers, UHMWPE composites, hybrid laminates, and graphene-enhanced structures to improve ballistic efficiency and reduce overall helmet weight. These innovations enable stronger impact resistance without compromising soldier mobility, contributing to higher operational performance. Parallel developments in integrated electronics-such as real-time communication systems, augmented-reality visors, battlefield data displays, and sensor-based situational awareness tools-are transforming helmets into intelligent tactical platforms. The convergence of protection, communication, and digital connectivity aligns with evolving military doctrines centered on network-centric warfare. Additionally, additive manufacturing and precision-molding technologies support customization for different mission profiles and head-geometry variations, strengthening adoption across diverse combat environments. These technological improvements continue to expand application potential and procurement interest from technologically advanced defense forces.
Key Trends & Opportunities
Integration of Smart and Connected Helmet Systems
A key trend in the Military Helmet market is the rising adoption of smart and connected helmet systems that integrate communication, surveillance, and data-sharing technologies to enhance battlefield awareness. Modern helmets increasingly feature built-in microphones, tactical headsets, GPS modules, heads-up displays, and wireless connectivity to support real-time coordination between ground units and command centers. The shift toward digital soldier systems and wearable-electronics ecosystems creates strong opportunities for manufacturers collaborating with defense electronics and cybersecurity providers. Integration with night-vision goggles, thermal sensors, and body-worn cameras further strengthens multifunctional capability. As autonomous and drone-assisted operations expand, helmets enabling live video streaming and target-tracking overlays will gain strategic relevance. This trend presents significant opportunities for innovation in power-management modules, lightweight circuit integration, and ruggedized electronic shielding, positioning smart helmets as a core component of future combat infrastructure.
- For instance, Elbit Systems’ DOMINATOR and similar soldier systems integrate helmet-mounted displays and communications gear to provide real-time situational awareness for dismounted troops.
Growing Demand for Lightweight and Ergonomic Helmet Designs
Another major opportunity emerges from the increasing demand for lightweight, ergonomic, and fatigue-reducing helmet platforms designed to improve soldier comfort during extended combat and patrol missions. Advances in UHMWPE composites, nano-reinforced fibers, and hybrid ballistic structures enable meaningful reductions in helmet mass while sustaining high protection levels. Defense forces are prioritizing mobility-centric systems that minimize neck strain, enhance balance, and support modular attachment compatibility without increasing load burden. This trend supports the development of customizable padding systems, adaptive fit mechanisms, and biometric-responsive interior liners. Manufacturers focusing on weight-optimized designs for airborne units, special forces, and rapid-deployment troops are well-positioned to capture emerging procurement opportunities. As military strategies shift toward agile combat capabilities and rapid maneuver warfare, demand for ergonomic, high-mobility helmets is expected to expand significantly across global defense procurement programs.
- For instance, DSM’s Dyneema-based ballistic helmet solutions have demonstrated weight reductions of around 25–30% compared with traditional aramid-only designs while maintaining required ballistic performance.
Key Challenges
High Production Costs and Advanced Material Constraints
One of the key challenges in the Military Helmet market is the high production cost associated with advanced ballistic materials, precision-engineering processes, and integrated electronic systems. The use of next-generation aramid fibers, UHMWPE composites, and hybrid laminates significantly increases manufacturing expenditure, limiting procurement capacity for cost-sensitive defense agencies. Additionally, supply-chain dependencies for specialized raw materials and proprietary technologies create pricing volatility and procurement risk. Integrating electronics such as communication modules and sensors further elevates development complexity, requiring strict testing protocols and compliance with military performance standards. These cost pressures can delay modernization cycles, especially in emerging economies, and may encourage refurbishment of older helmet fleets rather than replacement. Balancing affordability with technological enhancement remains a persistent strategic challenge for both manufacturers and defense procurement authorities.
Stringent Regulatory Standards and Performance Certification Requirements
The Military Helmet market also faces challenges related to stringent regulatory certifications, ballistic testing protocols, and compliance with evolving defense safety standards. Helmets must undergo extensive validation for impact resistance, fragmentation protection, weight balance, environmental endurance, and electronic integration reliability, leading to long development timelines and high certification expenses. Variations in regional defense specifications complicate standardization, requiring manufacturers to customize models for different military branches and geographies. Additionally, continuous updates to battlefield safety guidelines and emerging injury research necessitate frequent design revisions and retesting cycles. Meeting these regulatory expectations while maintaining production efficiency and innovation momentum remains a significant operational barrier, particularly for smaller manufacturers competing against established defense contractors.
Regional Analysis
North America
North America held the largest share of the Military Helmet market in 2024, accounting for 34.7% of global revenue, driven by strong defense modernization programs in the United States and Canada. The region’s procurement initiatives emphasize lightweight ballistic helmets, integrated communication systems, and advanced material technologies to support network-centric warfare capabilities. Extensive investment in soldier protection programs, research partnerships with defense contractors, and large-scale upgrade cycles across infantry and special operations units further strengthened demand. Ongoing replacement of legacy headgear, combined with rising deployment of modular combat helmets for training and active missions, continues to reinforce North America’s leading market position.
Europe
Europe represented 27.5% of the Military Helmet market in 2024, supported by increasing defense budgets, NATO-aligned modernization strategies, and rising cross-border military cooperation programs. Countries such as the United Kingdom, Germany, France, and Italy are prioritizing advanced ballistic protection solutions and communication-ready helmets to enhance soldier survivability in complex operational environments. Procurement momentum accelerated with multinational upgrade frameworks and technology standardization initiatives. Growing investments in lightweight aramid- and UHMWPE-based helmets, along with upgrades across infantry, mechanized forces, and peacekeeping units, contributed significantly to regional demand and reinforced Europe’s role as a key global market.
Asia-Pacific
Asia-Pacific accounted for 24.1% of the Military Helmet market in 2024 and emerged as the fastest-growing regional segment, driven by expanding military forces and rising defense procurement spending across China, India, South Korea, and Southeast Asian nations. Governments are prioritizing improved troop safety, battlefield mobility, and border-security readiness, leading to rapid adoption of lightweight ballistic helmets and modular communication-enabled variants. Indigenous manufacturing programs and domestic defense-industry expansion further support supply capability and cost-effective procurement. Ongoing territorial security initiatives, large troop deployments, and sustained investment in soldier-modernization projects continue to strengthen Asia-Pacific’s growth trajectory.
Latin America
Latin America captured 7.2% of the Military Helmet market in 2024, supported by gradual modernization of defense and law-enforcement equipment across Brazil, Mexico, Colombia, and Chile. Regional priorities focus on upgrading legacy helmets with improved ballistic protection and ergonomic performance to support counter-insurgency missions, border-security operations, and peacekeeping deployments. Although budgetary limitations slow large-scale procurement cycles, targeted acquisitions for specialized units and rapid-response forces continue to stimulate demand. Growing collaboration with international defense suppliers and selective adoption of lightweight UHMWPE-based helmets are enhancing operational readiness and contributing to steady, moderate market expansion across the region.
Middle East & Africa
The Middle East & Africa region accounted for 6.5% of the Military Helmet market in 2024, supported by rising defense spending, internal security programs, and modernization initiatives across Gulf states, North Africa, and select Sub-Saharan countries. Governments are prioritizing troop protection and procuring ballistic helmets suited for desert and urban combat conditions, including modular designs compatible with communications and night-vision systems. Demand is influenced by counter-terror operations and border-protection requirements, while procurement volumes vary significantly by country. Increasing reliance on imported advanced protective gear and limited local assembly capabilities continue to support incremental but sustained market growth in the region.
Market Segmentations:
By Type
- Lightweight
- Modular Integrated Communication Helmets
- Enhanced Combat
By Material
- Original Aramid Fiber Kevlar
- Advanced Aramid Fiber
- UHMWPE (Ultra High Molecular Weight Polyethylene) Fiber
By Weight
- Up to 3 Lbs
- Over 3 Lbs
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Military Helmet market features a diverse mix of global defense contractors, advanced material technology companies, and specialized armor manufacturers, all competing to deliver lightweight, high-protection headgear with integrated communication and situational-awareness capabilities. Leading players such as BAE Systems, Gentex Corporation, Revision Military, MKU Limited, ArmorSource, and Safariland Group focus on continuous product innovation, modular design enhancements, and ballistic-grade material development to meet evolving defense procurement standards. Companies including Honeywell International, DuPont, and Morgan Advanced Materials strengthen the supply chain through advanced aramid fibers and composite technologies that support weight reduction without compromising protection. Meanwhile, Point Blank Enterprises Inc., Eagle Industries, and 3M Company concentrate on helmet integration, comfort engineering, and soldier-centric ergonomics to improve operational endurance and mission performance. Strategic partnerships with defense agencies, technology vendors, and research institutions, along with government modernization programs and long-term procurement contracts, continue to shape competition and reinforce market leadership among established manufacturers.
Key Player Analysis
- Honeywell International
- Revision Military
- ArmorSource
- DuPont
- Gentex Corporation
- Safariland Group
- BAE Systems
- Morgan Advanced Materials
- Point Blank Enterprises Inc.
- MKU Limited
Recent Developments
- In November 2025, MKU Limited unveiled multiple innovations at Milipol Paris 2025, including the upgraded Kavro Doma 360 Ultra helmet, and advanced technologies such as the Netro Aksion Thermal Core and Kavro Kiro’X Ballistic Ceramics, expanding its high-performance helmet offerings.
- In October 2025, Galvion launched the new Batlskin Caiman® UL ultra-lightweight and stable military helmet at AUSA 2025, featuring an advanced APEX liner, redesigned harness, and modular 3-hole shroud for improved fit and mission performance.
- In October 2025, Anduril Industries, in partnership with Meta, unveiled the EagleEye AI-powered mixed-reality helmet system designed to integrate mission command, augmented reality (AR/VR) capabilities, and advanced situational awareness directly into warfighter helmets
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Weight and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness growing adoption of lightweight and ergonomic helmet designs to reduce soldier fatigue and improve mobility in extended combat operations.
- Defense agencies will increasingly prioritize helmets with integrated communication, sensor, and vision-support systems to enhance situational awareness on the battlefield.
- Advancements in composite materials, including aramid and UHMWPE fibers, will continue to drive improvements in ballistic protection and weight optimization.
- Demand will rise for customizable and modular helmet platforms that support mission-specific attachments and digital soldier system compatibility.
- Military modernization programs across emerging economies will expand procurement opportunities for next-generation ballistic helmets.
- Collaboration between defense manufacturers and material-technology companies will strengthen innovation in durability, impact resistance, and thermal stability.
- Smart helmet features such as heads-up displays and wireless connectivity will become more prevalent as digital warfare capabilities evolve.
- Increasing focus on soldier safety and injury-prevention standards will influence product design and testing requirements.
- Procurement strategies will gradually shift from legacy helmet refurbishment to large-scale fleet replacement programs.
- Global competition among leading manufacturers will intensify, encouraging greater emphasis on performance certification, reliability, and lifecycle support solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Military Helmet market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Military Helmet market projected to grow between 2024 and 2032?
Which Military Helmet market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Military Helmet market?
Who are the leading companies in the Military Helmet market?
Which region commanded the largest share of the Military Helmet market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Military Helmet Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Military Helmet Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,560 Million → 2032: USD 6,998.17 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Military Helmet Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Military Helmet Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Military Helmet Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Military Helmet Market Drivers
- 3.3 Military Helmet Market Restraints & Challenges
- 3.4 Military Helmet Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Military Helmet Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Military Helmet Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Military Helmet category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Military Helmet Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Military Helmet Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Military Helmet market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Military Helmet Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Military Helmet Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Military Helmet Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Military Helmet (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Military Helmet Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Military Helmet Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Military Helmet Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Military Helmet Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Military Helmet Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Military Helmet Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Military Helmet Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Military Helmet Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Military Helmet Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
