
Brewing Ingredients Market Overview:
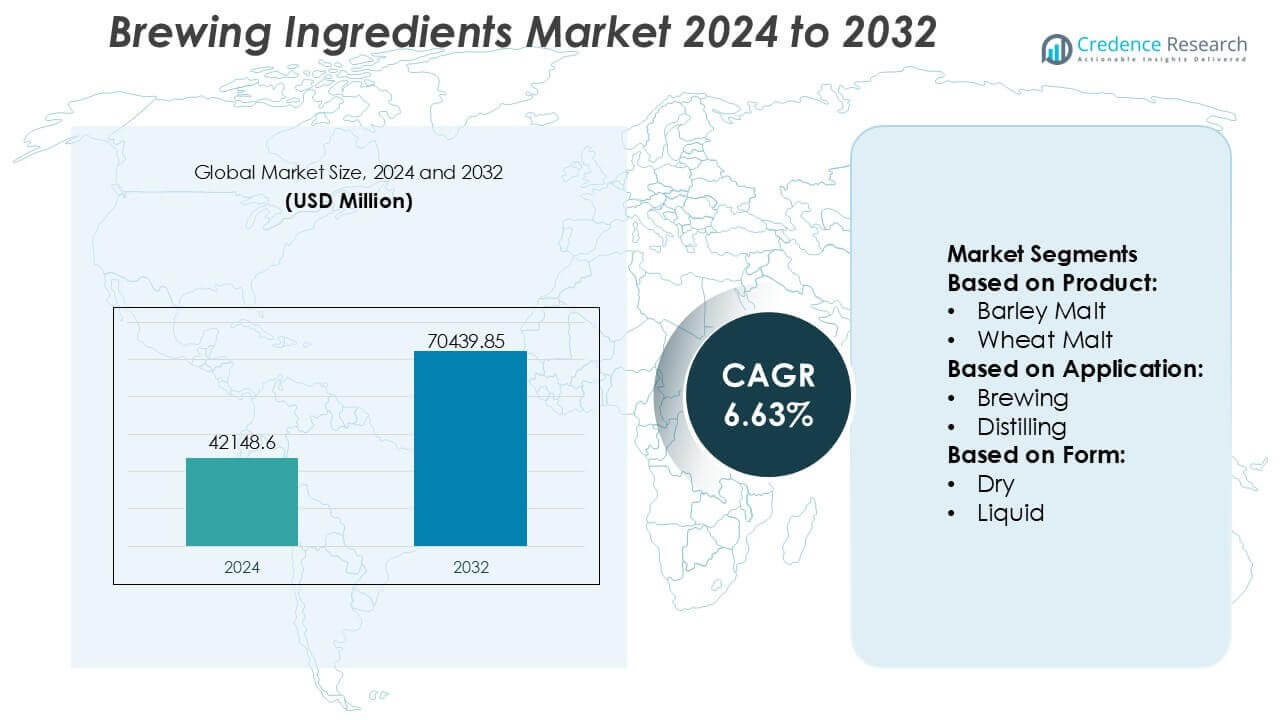
Brewing Ingredients Market size was valued USD 42148.6 million in 2024 and is anticipated to reach USD 70439.85 million by 2032, at a CAGR of 6.63% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Brewing Ingredients Market Size 2024 | USD 42148.6 million |
| Brewing Ingredients Market, CAGR | 6.63% |
| Brewing Ingredients Market Size 2032 | USD 70439.85 million |
Brewing Ingredients Market Insights
- Market growth is primarily driven by increasing demand for specialty malts, enzymes, and yeast cultures as brewers focus on craft, premium, and non-alcoholic beer production to differentiate flavors and improve consistency.
- Key market trends include clean-label ingredient adoption, advanced fermentation technologies, and growing use of application-specific ingredient solutions that enhance brewing efficiency and sensory performance.
- The competitive landscape is defined by large multinational ingredient suppliers and specialized solution providers competing on innovation, technical support, sustainable sourcing, and global supply-chain reliability.
- Regionally, North America leads with an exact 34% market share, while specialty malts dominate the product segment due to widespread use in craft and premium beers across mature and emerging brewing markets.
Brewing Ingredients Market Segmentation Analysis:
By Product
By product, barley malt represents the dominant sub-segment in the brewing ingredients market, accounting for an estimated 62% market share. Its leadership is driven by high enzymatic activity, consistent fermentable sugar yield, and its essential role in beer flavor, color, and foam stability. Barley malt remains the primary raw material for lagers and ales globally, supported by well-established malting infrastructure and standardized quality parameters. Wheat malt follows, driven by demand for wheat beers and craft styles, while corn, rye, and specialty malts support product differentiation, mouthfeel enhancement, and flavor complexity in both traditional and experimental formulations.
- For instance, Sensient Technologies supports barley-malt-based formulations through malt-derived flavor systems and brewing colors produced across more than 40 manufacturing facilities worldwide, supplying customers in over 80 countries.
By Application
By application, brewing dominates the market with approximately 58% market share, supported by sustained global beer consumption and premiumization trends. Breweries increasingly focus on specialty and craft beers, driving demand for high-quality base and specialty malts. Distilling follows as a significant segment, fueled by rising production of malt-based whiskies and spirits. Food and beverage applications, including bakery and confectionery, benefit from malt’s natural sweetness and coloring properties. Pharmaceutical and cosmetics uses remain niche but growing, driven by malt extracts’ nutritional profile, antioxidants, and functional binding properties in health-oriented formulations.
- For instance, Kerry Group Plc operates a global research and development network comprising more than 800 dedicated scientists and technologists focused on taste, nutrition and functional ingredient innovation, enabling precision formulation across applications from savoury broths to fortified beverages.
By Form
By form, dry brewing ingredients hold a dominant share of nearly 71%, driven by longer shelf life, ease of storage, and lower transportation costs. Dry malts and powders are widely preferred by large-scale breweries and food manufacturers due to consistent performance and compatibility with automated dosing systems. Liquid forms, including malt extracts and syrups, continue to gain traction in craft brewing, baking, and beverage formulations where rapid solubility and flavor control are critical. Growth in liquid formats is further supported by customization needs, though dry forms remain the standard for high-volume industrial applications.
Key Growth Drivers
Rising Global Beer Consumption and Product Premiumization
The brewing ingredients market is strongly driven by rising global beer consumption, supported by increasing demand for premium, craft, and specialty beers. Consumers are showing greater willingness to pay for differentiated taste profiles, unique aromas, and consistent quality, encouraging brewers to invest in high-grade malts, hops, yeasts, and adjuncts. Expansion of microbreweries and regional craft breweries further amplifies ingredient demand, as these producers rely heavily on specialty ingredients to create distinct formulations. Growth in on-trade and off-trade beer channels across both developed and emerging economies continues to reinforce volume stability and ingredient procurement.
- For instance, Archer Daniels Midland supports premium and craft brewing through its global network of more than 75 grain processing and ingredient manufacturing facilities, backed by an R&D organization employing over 2,000 scientists and technical experts.
Expansion of Craft Brewing and Microbrewery Ecosystems
The rapid expansion of craft brewing ecosystems is a major structural driver for brewing ingredients. Small and mid-scale brewers prioritize recipe innovation, limited-batch production, and experimentation with diverse raw materials, increasing the use of specialty malts, flavoring adjuncts, and novel yeast strains. This trend supports higher ingredient turnover per unit of beer produced compared to mass-produced lagers. In addition, local sourcing initiatives and collaboration brews are encouraging diversified ingredient portfolios, strengthening demand across both traditional and non-traditional brewing inputs while improving margins for specialty ingredient suppliers.
- For instance, Tate & Lyle Plc has advanced its brewing-adjacent ingredient capabilities through proprietary carbohydrate science and processing technologies developed across more than 20 global innovation and production facilities, supported by over 1,000 food scientists, chemists, and application technologists.
Technological Advancements in Brewing and Ingredient Processing
Advancements in brewing technology and ingredient processing are accelerating market growth by improving efficiency, consistency, and yield optimization. Modern malting techniques, advanced hop extraction methods, and precision fermentation technologies enable brewers to achieve stable flavor profiles while reducing wastage. Ingredient suppliers are increasingly offering standardized, high-performance inputs that integrate seamlessly with automated brewing systems. These innovations reduce batch variability and enhance scalability, making advanced brewing ingredients more attractive to both industrial breweries and fast-scaling craft producers, thereby supporting sustained market expansion.
Key Trends & Opportunities
Growing Demand for Clean-Label and Natural Ingredients
A prominent trend in the brewing ingredients market is the growing demand for clean-label, natural, and minimally processed inputs. Consumers increasingly scrutinize ingredient lists and favor beers made with recognizable, natural components. This trend is driving brewers to adopt organic malts, natural flavoring agents, and non-synthetic stabilizers. Ingredient suppliers are responding by expanding portfolios that emphasize traceability and transparency. This shift creates strong opportunities for premium ingredient differentiation and long-term partnerships with brewers focused on brand authenticity and sustainability.
- For instance, legacy Frutarom maintained a Prior to the IFF acquisition, Frutarom marketed and sold over 70,000 products to more than 30,000 customers in over 150 countries.
Innovation in Non-Alcoholic and Low-Alcohol Brewing
Innovation in non-alcoholic and low-alcohol beer production presents a significant growth opportunity for brewing ingredients. These products require specialized yeasts, enzymes, and flavor-enhancing ingredients to maintain mouthfeel and taste despite reduced alcohol content. As health-conscious consumption rises, brewers are investing in advanced formulations that rely heavily on functional ingredients. This trend expands the application scope of brewing ingredients beyond traditional beer categories and encourages suppliers to develop customized solutions tailored to alcohol-reduction technologies.
- For instance, DuPont won three R&D 100 Awards for advanced materials and process technologies, with award-winning products such as Tychem™ 6000 SFR fabric, which delivers at least 30 minutes of protection against more than 250 chemical challenges under standardized testing conditions, evidencing high-performance barrier functionality.
Increasing Focus on Sustainable and Efficient Brewing Inputs
Sustainability is emerging as a key opportunity area, with brewers seeking ingredients that support resource efficiency and lower environmental impact. Demand is increasing for high-yield malts, concentrated hop products, and ingredients that reduce water and energy consumption during brewing. Sustainable sourcing practices and reduced transportation footprints are also influencing purchasing decisions. Ingredient suppliers that align with environmental goals and offer efficiency-driven solutions are well positioned to gain competitive advantage in long-term supply contracts.
Key Challenges
Volatility in Raw Material Supply and Agricultural Dependence
The brewing ingredients market faces challenges from volatility in raw material supply due to its heavy dependence on agricultural outputs such as barley, wheat, and hops. Weather variability, crop diseases, and fluctuating farming inputs can disrupt availability and quality, creating cost uncertainty for ingredient suppliers and brewers. These disruptions complicate long-term procurement planning and pricing strategies, particularly for small and mid-scale breweries with limited sourcing flexibility. Managing supply consistency remains a critical operational challenge across the value chain.
Regulatory Complexity and Quality Compliance Requirements
Regulatory complexity represents another key challenge for the brewing ingredients market. Ingredient suppliers must comply with diverse food safety, labeling, and quality standards across different regions, increasing operational and documentation burdens. Variations in permissible additives, processing aids, and import regulations can delay market entry and increase compliance costs. For brewers operating across multiple geographies, aligning ingredient specifications with regional regulations adds further complexity, potentially slowing product launches and innovation cycles.
Regional Analysis
North America
North America leads the global brewing ingredients market with an estimated 34% market share, driven by a mature beer industry and a strong concentration of craft and microbreweries. The United States dominates regional demand due to high per-capita beer consumption, advanced brewing infrastructure, and sustained innovation in specialty and premium beer categories. Brewers in the region increasingly utilize specialty malts, hop extracts, and tailored yeast strains to support differentiated flavor profiles. Strong distribution networks, stable raw material sourcing, and high adoption of automation and precision brewing technologies further reinforce North America’s leadership position.
Europe
Europe accounts for approximately 32% of the global brewing ingredients market, supported by its deep-rooted brewing heritage and large base of established breweries. Countries such as Germany, Belgium, and the United Kingdom drive consistent demand for malted barley, hops, and traditional yeast cultures. The region benefits from well-developed agricultural supply chains and strict quality standards that promote premium ingredient usage. Growth is further supported by rising demand for specialty and craft beers, alongside increasing exports of European beer styles. Regulatory stability and a strong focus on ingredient authenticity sustain long-term market resilience.
Asia-Pacific
Asia-Pacific holds around 24% market share and represents the fastest-growing regional market for brewing ingredients. Rapid urbanization, rising disposable incomes, and shifting consumer preferences toward premium and international beer brands are key growth drivers. China, Japan, India, and Southeast Asian countries are witnessing expanding brewery footprints and increased investment in local production capacity. Brewers in the region are progressively adopting specialty malts, enzymes, and flavoring ingredients to meet evolving taste profiles. The growing presence of multinational brewers and expanding craft beer culture further accelerate ingredient demand across the region.
Latin America
Latin America represents roughly 6% of the global brewing ingredients market, supported by steady beer consumption growth and expanding middle-class populations. Brazil and Mexico dominate regional demand, driven by strong domestic beer production and export-oriented brewing operations. While mainstream lagers continue to account for a significant share, rising interest in craft and flavored beers is increasing the use of specialty malts and hop varieties. Improving brewing infrastructure and growing investments from international brewers are enhancing ingredient quality requirements, gradually shifting the market toward higher-value brewing inputs.
Middle East & Africa
The Middle East & Africa region accounts for an estimated 4% market share in the brewing ingredients market. Growth remains selective and concentrated in Africa, where rising urban populations and expanding local breweries support increasing ingredient demand. South Africa, Nigeria, and Kenya are key markets benefiting from improving cold-chain logistics and domestic malt production. In contrast, parts of the Middle East show limited consumption due to regulatory constraints, though non-alcoholic beer production supports niche ingredient demand. Overall, gradual market development and infrastructure expansion underpin moderate regional growth.
Brewing Ingredients Market Segmentations:
By Product:
- Barley Malt
- Wheat Malt
By Application:
- Brewing
- Distilling
By Form:
- Dry
- Liquid
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The brewing ingredients market players such as Sensient Technologies, Cargill, Corbion Inc., Kerry Group Plc, Archer Daniels Midland, Tate & Lyle Plc, Frutarom, DuPont de Nemours and Company, Koninklijke DSM N.V., Kerry Group PLC. The brewing ingredients market is characterized by a competitive environment shaped by large multinational ingredient suppliers and specialized fermentation and flavor solution providers. Competition centers on portfolio breadth, product consistency, and the ability to deliver application-specific ingredients across industrial, craft, and specialty brewing segments. Companies increasingly differentiate through advanced fermentation technologies, clean-label formulations, and technical service capabilities that support recipe optimization and process efficiency. Strategic emphasis is placed on innovation in enzymes, yeast strains, and flavor systems to address premiumization and non-alcoholic beer trends. Sustainability, supply-chain reliability, and traceability have become critical competitive factors, as brewers seek long-term partnerships that ensure quality stability, cost control, and alignment with evolving regulatory and environmental expectations.
Key Player Analysis
- Sensient Technologies
- Cargill
- Corbion Inc.
- Kerry Group Plc
- Archer Daniels Midland
- Tate & Lyle Plc
- Frutarom
- Dupont De Nemours and Company
- Koninklijke DSM N.V
- Kerry Group PLC
Recent Developments
- In April 2025, Arla Foods Ingredients (AFI) saw a 5.4% revenue increase, reaching driven by strong demand for specialized proteins. The company is actively expanding the application of milk fat globule membrane (MFGM) beyond infant nutrition and has introduced a new micellar casein ingredient for medical nutrition.
- In June 2025, Ajinomoto continues its long-standing efforts to dispel myths surrounding monosodium glutamate (MSG) as part of its broader commitment to health and wellness through "AminoScience".
- In December 2024, Nestlé has intensified its research into bioactive compounds aimed at promoting muscle health and longevity. Recent studies have highlighted the benefits of ingredients like nicotinamide, pyridoxine, oleuropein, and trigonelline in supporting cellular aging and muscle regeneration.
- In March 2024, Triplebar to develop precision fermentation-derived lactoferrin, aiming to meet the growing demand for this bioactive protein. Additionally, the company introduced the Biotis Fermentis bar concept, combining proteins, prebiotics, and probiotics to target the gut-muscle axis.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Form and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Brewing ingredient demand will increasingly align with premium and craft beer production, supporting higher usage of specialty malts, hops, and tailored yeast strains.
- Ingredient innovation will accelerate to support non-alcoholic and low-alcohol beer formulations without compromising flavor or mouthfeel.
- Clean-label, natural, and minimally processed ingredients will gain stronger preference among both brewers and end consumers.
- Advanced fermentation and enzyme technologies will be adopted to improve yield efficiency and batch-to-batch consistency.
- Sustainability-focused ingredients with lower water, energy, and carbon footprints will influence procurement decisions.
- Local and regional sourcing strategies will expand to reduce supply-chain risk and improve ingredient traceability.
- Digital integration and data-driven brewing will increase demand for standardized, high-performance ingredient solutions.
- Custom ingredient blends and application-specific formulations will strengthen collaboration between brewers and suppliers.
- Regulatory alignment and quality compliance will shape ingredient development and market entry strategies.
- Emerging markets will contribute incremental growth as beer consumption patterns shift toward premium and differentiated products.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Brewing Ingredients Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Brewing Ingredients Market projected to grow between 2024 and 2032?
Which Brewing Ingredients Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Brewing Ingredients Market?
Who are the leading companies in the Brewing Ingredients Market?
Which region commanded the largest share of the Brewing Ingredients Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 42,148.6 million → 2032: USD 70,439.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Brewing Ingredients Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Brewing Ingredients Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Brewing Ingredients Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Brewing Ingredients Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Brewing Ingredients Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Brewing Ingredients Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Brewing Ingredients Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Brewing Ingredients Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 42,148.6 million → 2032: USD 70,439.85 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Brewing Ingredients Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Brewing Ingredients Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Brewing Ingredients Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Brewing Ingredients Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

